
 Singapore Maritime Market | 2026-2036
Singapore Maritime Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Maritime Market Analytics
Container shipping lines is consolidating their reliance on Singapore as a transhipment hub, driving sustained investment in terminal capacity and vessel services. PSA International leverages its deep-water berth infrastructure to dominate container handling volumes across Southeast Asian trade lanes. Pacific International Lines anchors its regional feeder network through Singapore, while Ocean Network Express competes on transpacific route density from the port.
Singapore Maritime encompasses the full spectrum of commercial marine activities centered on one of the world's busiest container transshipment nodes, where vessel traffic management systems coordinate up to 1,000 ship movements daily through the Singapore Strait. The sector's primary purpose is to facilitate international cargo flows between Europe, Asia, and the Americas while supporting ship repair, bunkering, and maritime ancillary services. Port Operations commands the largest revenue pool given PSA International's terminal dominance, though Marine Automation within the Technology segment is expanding fastest as terminal operators deploy autonomous yard cranes and AI-driven berth scheduling. Container Ships under Vessel Type remain the structural backbone of demand, while Bulk Carriers face stagnant growth amid energy transition pressures on coal and iron ore trades.
Singapore's Maritime and Port Authority enforces the International Maritime Organization's 2020 sulphur cap through mandatory use of low-sulphur fuel or scrubber installations for vessels in its waters, directly shaping bunker demand and retrofit activity. The city-state's adoption of ISO maritime standards and its own Green Port Programme creates compliance-driven procurement for emission monitoring systems and shore power infrastructure. Stakeholders must weigh the pace of ammonia and methanol fuel infrastructure investment against the risk of stranded conventional assets as regulatory timelines tighten without specifying exact phase-out dates.
Market Dynamics
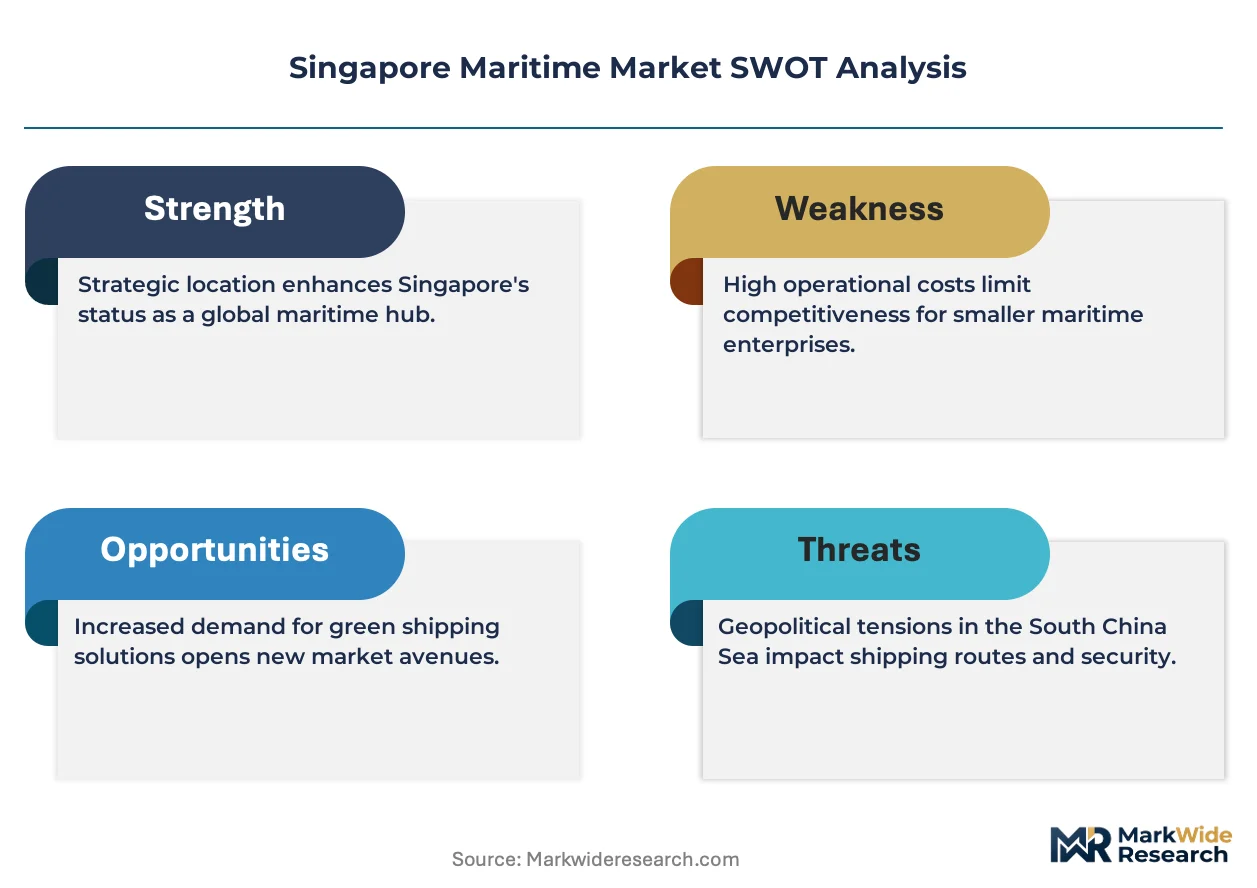
The Singapore Maritime and Port Authority's enforcement of IMO 2020 sulphur regulations and its Green Port Programme are compressing vessel turnaround economics while forcing terminal operators to accelerate digital infrastructure deployment.
Growth Catalysts
- IMO Decarbonization Mandates:International Maritime Organization emission targets are compelling container shipping lines to renew fleets with dual-fuel capability, expanding demand for Singapore's retrofit and bunkering services.
- Port Digitalization:Autonomous yard cranes and AI-driven berth scheduling systems are reducing vessel dwell times and increasing terminal throughput capacity at PSA International facilities.
- Southeast Asian Transshipment Concentration:Manufacturing relocation to Vietnam and Indonesia is reinforcing Singapore's hub position for intra-Asia cargo consolidation.
Market Restraints
- Alternative Fuel Infrastructure Uncertainty:Ammonia and methanol bunkering facilities require capital commitments before regulatory timelines clarify fuel standards, creating stranded asset risk for terminal investors.
- Feeder Network Competition:Port Klang and Tanjung Pelepas are expanding capacity with lower cost structures, threatening Singapore's dominance in regional container relay.
- Scrubber Retrofit Saturation:Open-loop scrubber restrictions in Singapore waters have eliminated a compliance pathway, forcing immediate shift to more expensive low-sulphur fuels or closed-loop systems.
Strategic Opportunities
- Maritime Data Services:Vessel traffic management systems generating 1,000 daily ship movements create proprietary datasets for predictive analytics and port optimization software exports.
- Shore Power Infrastructure:The Green Port Programme's cold-ironing incentives position Singapore to capture first-mover revenue from cruise and container vessel electrification at berth.
- Ship Repair Automation:Drydock operators integrating robotic hull cleaning and automated welding systems can compress repair cycles for methanol-ready vessel conversions.
Industry Challenges
- Maritime Cybersecurity Certification:Terminal operators face fragmented IMO and ISO 27001 compliance timelines for autonomous crane networks and vessel-to-shore data links.
- Dual-Fuel Technician Scarcity:Ammonia and methanol propulsion systems require specialized training pipelines that Singapore's maritime education institutions have not yet scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Maritime Market |
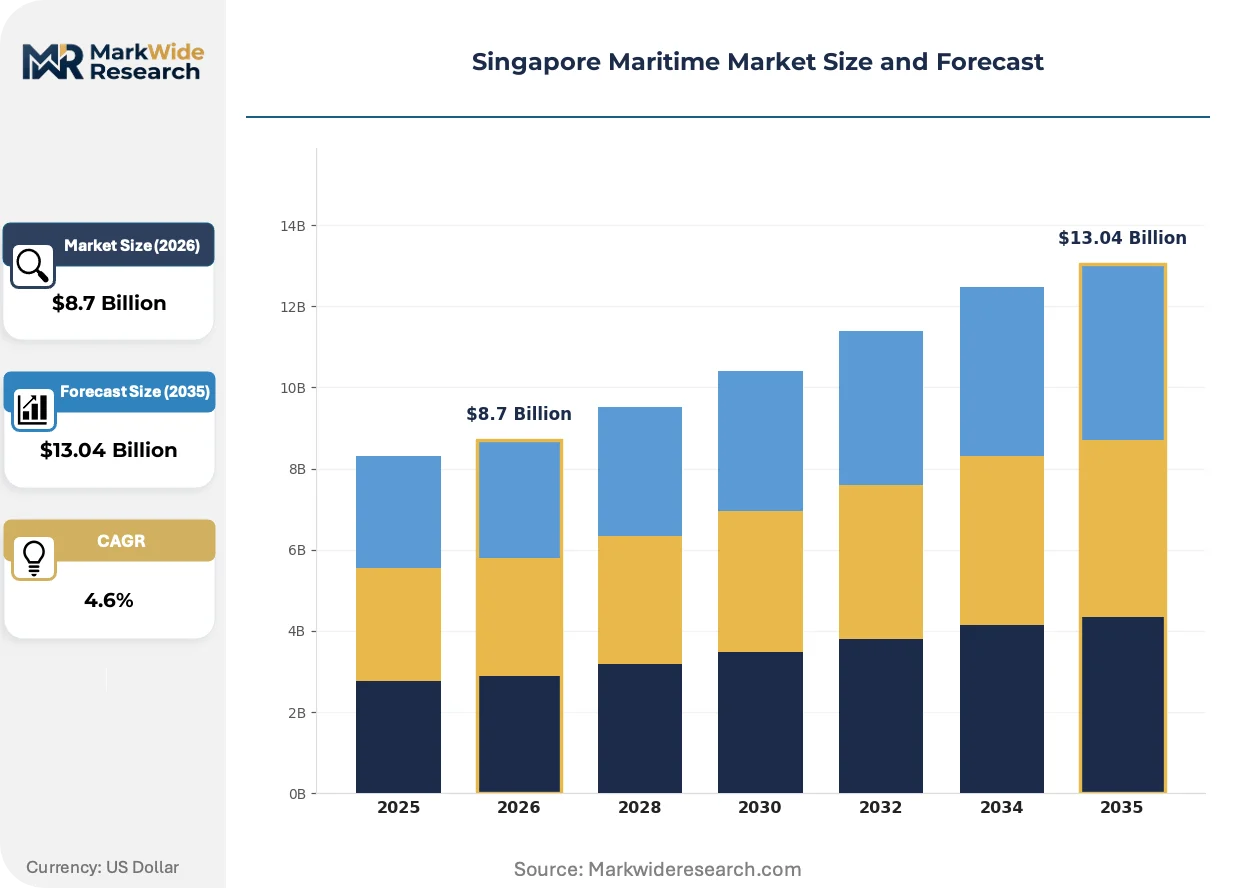
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Shipping, Shipbuilding, Port Operations, Maintenance Vessel Type: Container Ships, Bulk Carriers, Tankers, Fishing Vessels End User: Logistics Companies, Shipping Lines, Freight Forwarders, Government Agencies Technology: Nautical Electronics, Marine Automation, Navigation Systems, Safety Equipment |
| Companies Covered | PSA International, Pacific International Lines, CMA CGM, Ocean Network Express, Maersk, X-Press Feeders, Singapore Shipping Corporation Limited, AP Moller Singapore Pte Ltd, Evergreen Marine (Singapore) Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Maritime Market Evolving Landscape
Digital twin technology and autonomous systems are compressing operational decision cycles across Singapore's terminal ecosystem, while regulatory pressure on vessel emissions accelerates fuel infrastructure experimentation.
Digital twin platforms are integrating real-time vessel positioning, berth occupancy, and equipment status into unified simulation environments. PSA International and terminal operators are deploying these systems to optimize crane dispatch and reduce vessel turnaround windows. The technology is integrating historically siloed operational data streams into predictive maintenance and dynamic scheduling workflows.
Singapore's Maritime and Port Authority is tightening enforcement of its Green Port Programme through mandatory shore power readiness assessments for cruise terminals and container berths. Vessel operators calling at Singapore must now demonstrate compliance with emission monitoring protocols or face priority berthing penalties. Container shipping lines are responding by accelerating retrofit schedules for shore power connection capability.
Charterers are consolidating procurement of bundled port services—bunkering, provisions, and repair—through single-contract arrangements with integrated terminal operators. Traditional spot-market purchasing of individual services is contracting as vessel operators seek operational predictability. This consolidation is most visible among transpacific container lines optimizing Singapore calls within tight schedule windows.
Singapore Maritime Market Segmentation
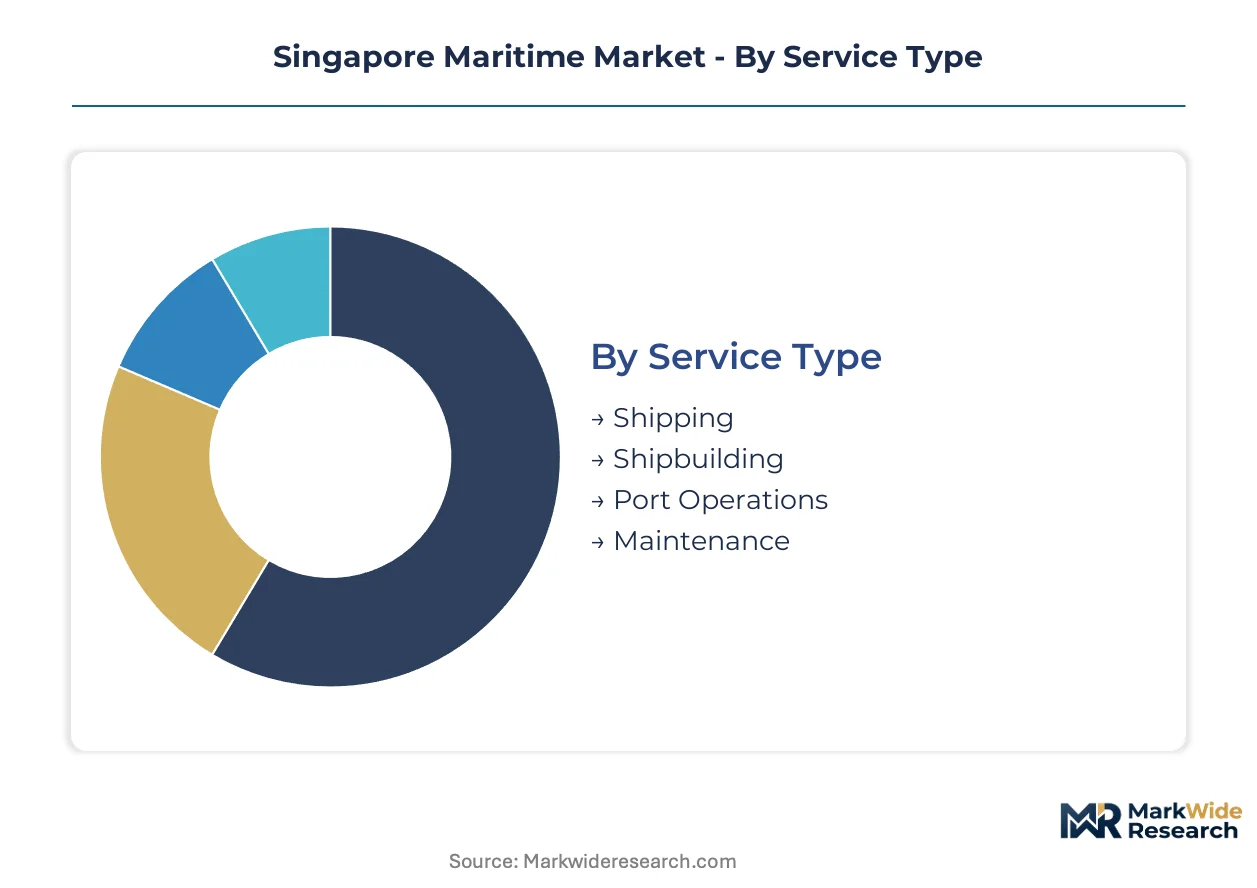
Segmentation in the Singapore Maritime Market reveals how capital deployment and regulatory compliance reshape competitive positioning across service lines and vessel categories. Terminal operators and shipping lines allocate investment differently depending on whether they prioritize physical infrastructure, digital systems, or fleet assets.
Service Type:
Capital intensity varies sharply across service categories, with fixed infrastructure demanding the heaviest upfront commitment and maintenance services offering more variable cost structures.
- Port Operations:Deep-water berths, automated yard systems, and vessel traffic management infrastructure require sustained capital renewal. PSA International's terminal dominance concentrates demand here, with the Maritime and Port Authority mandating emission monitoring equipment and shore power readiness as condition of operating licenses.
- Shipping:Fleet ownership and charter operations tie up capital in hull assets with 20-25 year depreciation cycles. Container shipping lines are accelerating fleet renewal to meet IMO decarbonization targets, expanding demand for Singapore's bunkering and retrofit services.
- Shipbuilding:Drydock capacity and specialized fabrication facilities serve regional vessel construction and conversion demand.
- Maintenance:Repair cycles compress as dual-fuel propulsion systems introduce complexity; robotic hull cleaning and automated welding systems are compressing turnaround times.
Most installed capacity flows through Port Operations. Expansion is steepest in Shipping as fleet renewal accelerates.
Vessel Type:
Application profiles determine berthing priority, fuel infrastructure requirements, and terminal handling economics across Singapore's port ecosystem.
- Container Ships:Box vessels dominate vessel movements through the Singapore Strait, with up to 1,000 daily ship movements coordinated through traffic management systems. PSA International's deep-water berths anchor regional transshipment flows between Europe, Asia, and the Americas.
- Bulk Carriers:Dry bulk faces stagnant demand amid energy transition pressures on coal and iron ore trades, though grain and mineral flows sustain some calling frequency.
- Tankers:Liquid cargo vessels drive specialized bunkering demand and chemical handling infrastructure at Jurong Terminal.
- Fishing Vessels:Smaller craft require harbor craft services and maintenance facilities separate from main container terminal operations.
Container Ships absorb the majority of terminal throughput investment. Tankers are gaining share fastest as ammonia and methanol fuel trials expand.
End User:
Customer type shapes procurement patterns, contract duration, and service bundling preferences across the maritime value chain.
- Shipping Lines:Ocean carriers like Pacific International Lines and Ocean Network Express consolidate procurement of bunkering, provisions, and repair through single-contract arrangements with integrated terminal operators, displacing spot-market purchasing.
- Logistics Companies:Third-party logistics providers concentrate demand for cargo visibility systems and intermodal connectivity through Singapore's port.
- Freight Forwarders:Consolidators rely on Singapore's hub position for intra-Asia cargo consolidation as manufacturing relocates to Vietnam and Indonesia.
- Government Agencies:The Maritime and Port Authority's enforcement of IMO 2020 sulphur regulations and Green Port Programme creates compliance-driven procurement for emission monitoring and shore power infrastructure.
Shipping Lines command the largest contract values. Logistics Companies are expanding their technology spend fastest.
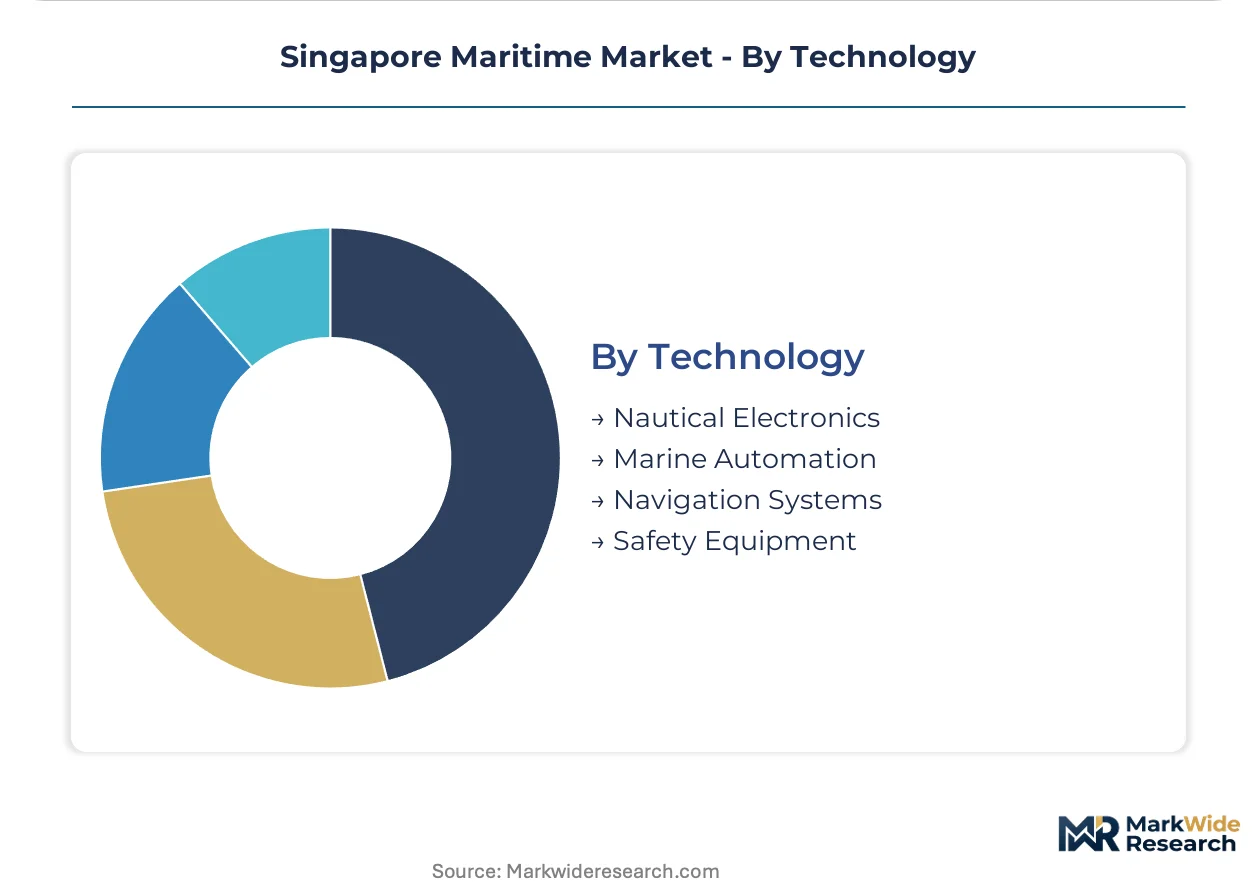
Technology:
Maturity curves separate established navigation equipment from emerging automation systems requiring new certification pathways and technician training pipelines.
- Marine Automation:Autonomous yard cranes and AI-driven berth scheduling systems are reducing vessel dwell times and increasing terminal throughput capacity. Digital twin platforms integrate real-time vessel positioning, berth occupancy, and equipment status into unified simulation environments.
- Nautical Electronics:Radar, AIS, and communication systems form the baseline equipment layer with established certification and maintenance protocols.
- Navigation Systems:ECDIS and positioning equipment face upgrade cycles as cybersecurity standards tighten for vessel-to-shore data links.
- Safety Equipment:Regulatory mandates drive replacement schedules for lifeboats, fire suppression, and emission monitoring systems under the Green Port Programme.
Most technology revenue currently flows through Nautical Electronics. Marine Automation is climbing the fastest as terminal operators deploy predictive maintenance and dynamic scheduling workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping maritime activity across Southeast Asia as vessel operators seek cost-efficient compliance pathways while Singapore tightens emission enforcement. The Maritime and Port Authority's Green Port Programme creates a compliance premium that neighboring ports exploit through lower-cost structures.
Malaysia
Port Klang and Tanjung Pelepas are expanding container terminal capacity to capture transshipment flows diverted from Singapore's higher-cost compliance environment. The Port Klang Authority offers competitive berthing incentives under its Free Commercial Zone framework. Johor's Pasir Gudang port cluster is positioning for ship repair and maintenance services as Singapore drydock rates rise.
Indonesia
Batam and Bintan free trade zones are developing maritime support services targeting Singapore-registered vessels seeking lower-cost provisioning and repair. The Indonesia Port Corporation is modernizing Tanjung Priok terminal automation to compete for intra-Asia cargo consolidation. Surabaya's Tanjung Perak is expanding feeder vessel services to connect with Singapore's mainline networks.
Vietnam
Cai Mep deep-water terminals are attracting direct mainline calls from transpacific container services, bypassing Singapore for certain trade lanes. The Vietnam Maritime Administration is streamlining port clearance procedures to reduce vessel dwell times. Hai Phong's Lach Huyen terminal is developing cold chain infrastructure for agricultural exports.
Thailand
Laem Chabang port is investing in automated yard crane systems to match Singapore's terminal productivity benchmarks. The Port Authority of Thailand is negotiating with major shipping lines for dedicated terminal concessions. Bangkok's Khlong Toei terminal faces capacity constraints that push transshipment demand toward Singapore.
Singapore Maritime Market Competitive Landscape
Capacity expansion dominates the current landscape as terminal operators and shipping lines race to secure berth infrastructure and fleet renewal positions. The market exhibits tiered consolidation with state-linked terminal operators controlling physical infrastructure, diversified shipping conglomerates managing fleet assets, and specialized feeder operators filling network gaps. Strategic partnerships between terminal operators and shipping lines are locking in long-term volume commitments, while vertical integration into bunkering and logistics services is compressing margins for standalone service providers.
Within the state-linked terminal operator tier, PSA International exemplifies infrastructure dominance through its deep-water berth portfolio and automated yard systems. Among Singapore-based shipping lines, Pacific International Lines occupies a position as a regional feeder network anchor, while Ocean Network Express represents the consolidated Japanese carrier presence competing on transpacific route density. These entities sit within distinct competitive archetypes—PSA International as infrastructure gatekeeper, Pacific International Lines as regional network specialist, and Ocean Network Express as global alliance participant.
| Leading Market Players |
|---|
| PSA International |
| Pacific International Lines |
| CMA CGM |
| Ocean Network Express |
| Maersk |
| X-Press Feeders |
| Singapore Shipping Corporation Limited |
| AP Moller Singapore Pte Ltd |
| Evergreen Marine (Singapore) Pte Ltd |
| Others |
Value Network & Pricing Analysis
Container shipping lines consolidating procurement through PSA International and integrated terminal operators drive contract-based long-term offtake pricing that bundles bunkering, provisions, and repair services. This buyer concentration compresses spot-market premiums while rewarding volume commitments with preferential berthing access under the Maritime and Port Authority's emission compliance framework.
Pricing Analysis
Distributor margins on marine fuels and port services compress as charterers negotiate direct terminal operator contracts. Three-tier pricing structure across premium low-sulphur fuels, standard compliant blends, and economy high-sulphur residual separates compliance grades. Pricing pressure stems from Port Klang and Tanjung Pelepas undercutting Singapore's Green Port Programme surcharges. Regional feeder operators exhibit highest price sensitivity; transpacific alliance carriers absorb premiums for schedule reliability.
Supply Chain Analysis
Singapore's domestic-content mandates on shore power infrastructure and emission monitoring equipment reshape sourcing toward local system integrators. Equipment fabrication draws from South Korea, Japan, and China for autonomous crane components and digital twin platforms. Low-sulphur fuel supply rests on Middle Eastern and Asian refinery output vulnerable to IMO regulatory shifts. Single-source vulnerability concentrates in ammonia and methanol bunkering trials. Distribution runs through PSA International's terminal network with direct vessel-to-berth service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Singapore Maritime Market functions as a stable compounder anchored by irreplaceable transshipment geography and regulatory enforcement that perpetually renews compliance-driven investment cycles.
For Market Incumbents: Hedge against stranded conventional bunkering assets by securing first-mover positions in ammonia and methanol fuel infrastructure before regulatory timelines clarify. Deepen backward integration into shore power systems and emission monitoring technology to capture Green Port Programme procurement. Port Klang's capacity expansion and cost undercutting present the primary margin threat requiring terminal productivity defense through automation deployment. For New Entrants and Emerging Players: Mid-sized logistics companies underserved by PSA International's enterprise-focused automation platforms represent the most penetrable buyer archetype. White-space exists in predictive analytics exports derived from vessel traffic management datasets and specialized technician training for dual-fuel propulsion systems. A channel partnership route with existing terminal operators offers faster market access than greenfield infrastructure investment. For Investors and Strategic Acquirers: State-linked terminal operators are the most active acquirer in this space, consolidating regional port assets to secure transshipment volume corridors. Long-term viability centers on infrastructure gatekeepers with regulatory compliance mandates embedded in operating licenses. Acquisition targets should display captive berth infrastructure and automation deployment capability. The signal to watch is IMO regulatory acceleration on ammonia fuel standards triggering infrastructure investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Buildout | Captures Green Port Programme incentives while positioning for cruise and container vessel electrification at berth. |
| Autonomous Terminal Systems Deployment | Compresses vessel dwell times against Port Klang competition through AI-driven berth scheduling and robotic yard cranes. |
| Alternative Fuel Bunkering Trials | Establishes first-mover ammonia and methanol supply infrastructure ahead of IMO decarbonization timeline clarity. |
| Maritime Data Services Export | Monetizes proprietary vessel traffic datasets through predictive analytics platforms for regional port optimization. |
| Dual-Fuel Technician Training Scale-Up | Addresses capability scarcity in ammonia and methanol propulsion systems through institutional education partnerships. |
Research Methodology
Coverage spans Singapore, Malaysia, Indonesia, Vietnam, and Thailand, with primary inputs from each market through structured interviews with terminal operations directors, fleet procurement managers at container shipping lines, Maritime and Port Authority regulatory officials, and marine automation technology vendors. Secondary validation draws from port authority annual reports, IMO regulatory filings, customs trade statistics, and terminal operator capacity disclosures. Bottom-up vessel movement and service revenue estimates triangulate against top-down macroeconomic trade flow projections.
Rate-of-change decomposition separates volume growth from price realization across the analysis window. Segmentation dimensions modeled include service type, vessel category, end-user procurement pattern, and technology maturity tier. CAGRs derive from historical trajectory fitting adjusted for regulatory inflection points. Forecast inputs incorporate fleet renewal schedules for dual-fuel vessel deliveries and Green Port Programme compliance phase-in assumptions.
Underlying measurement precision varies by segment; Port Operations and Container Ships carry tighter precision than emerging Marine Automation and alternative fuel infrastructure categories. Forecasts embed assumptions on IMO regulatory timeline adherence and regional competitor capacity expansion that could materially revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market