
 Russia Road Freight Transport Market | 2026-2036
Russia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Road Freight Transport Market Analytics
Domestic distribution corridors between Moscow and the Urals is tilting toward consolidated fleet operators with dedicated lane contracts. Delovye Linii Group leverages its terminal network density to control last-mile scheduling across European Russia. Globaltruck sustains long-haul capacity through in-house maintenance depots spaced at 400-kilometer intervals. ITECO Corporation anchors project cargo movements for industrial clients in Siberia and the Far East.
Russia road freight transport encompasses the commercial movement of goods by motor vehicle over federal and regional highways, utilizing vehicles ranging from 1.5-ton cargo vans to 40-ton articulated tractor-trailers with Euro-5 or Euro-6 emission compliance where domestically produced. The sector serves as the backbone of domestic supply chain connectivity, linking manufacturing clusters to wholesale distribution centers and retail endpoints across eleven time zones. Full Truck Load operations dominate volume throughput on trunk routes, while Less Than Truck Load services capture fragmented shipper demand through hub-and-spoke terminal consolidation. Refrigerated Trucks command premium rate structures due to cold-chain integrity requirements for food and pharmaceutical cargo moving between Moscow and southern agricultural zones.
Russia's Federal Road Agency (Rosavtodor) governs highway concession terms and axle-load enforcement, while the Ministry of Transport oversees carrier licensing and driver qualification standards under federal mobility statutes. The Platon toll system administered by RT-Invest Transport Systems directly inflates per-kilometer operating costs for vehicles exceeding twelve tons, pushing smaller carriers toward fleet modernization or subcontracting models. Stakeholders must weigh the capital intensity of Euro-5 compliant tractor acquisitions against the operational savings from reduced toll penalties and fuel consumption.
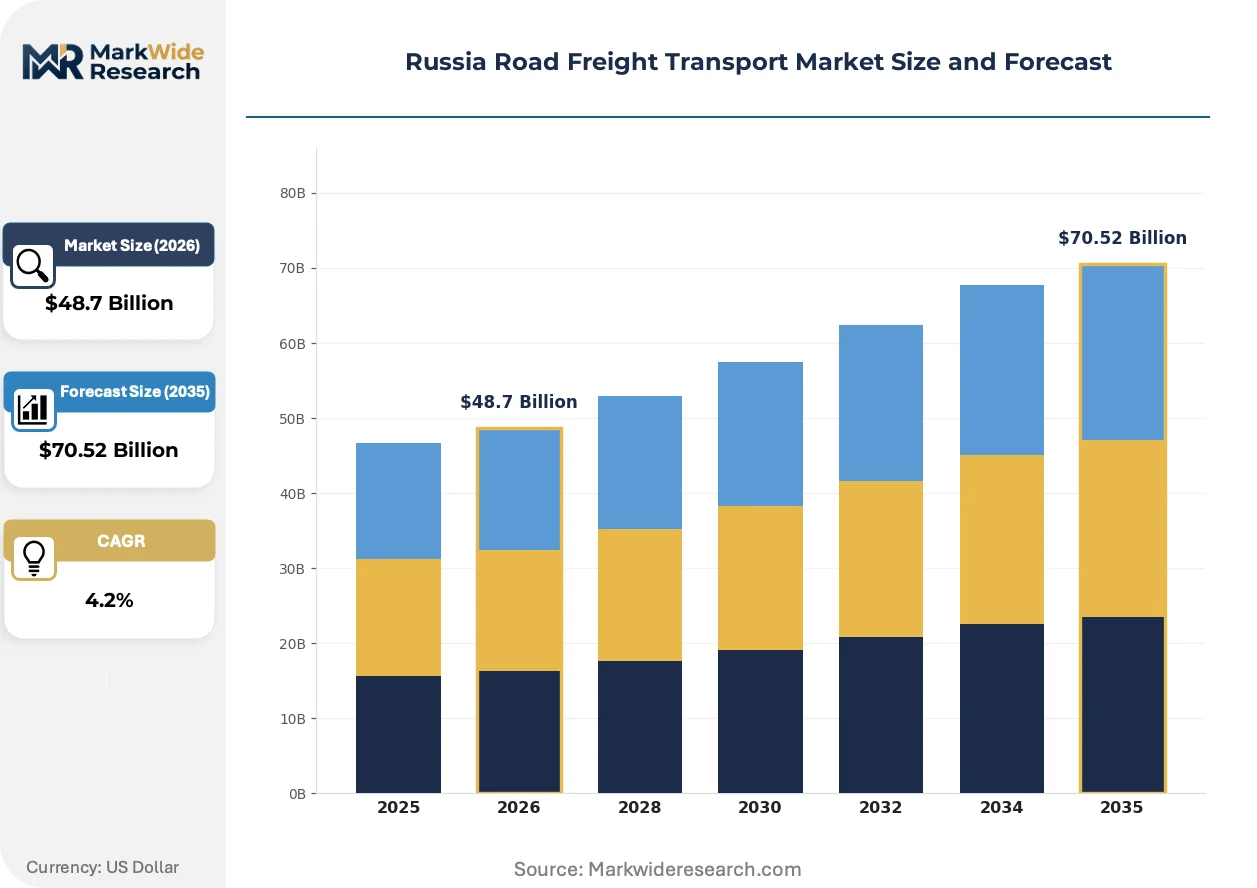
Market Dynamics
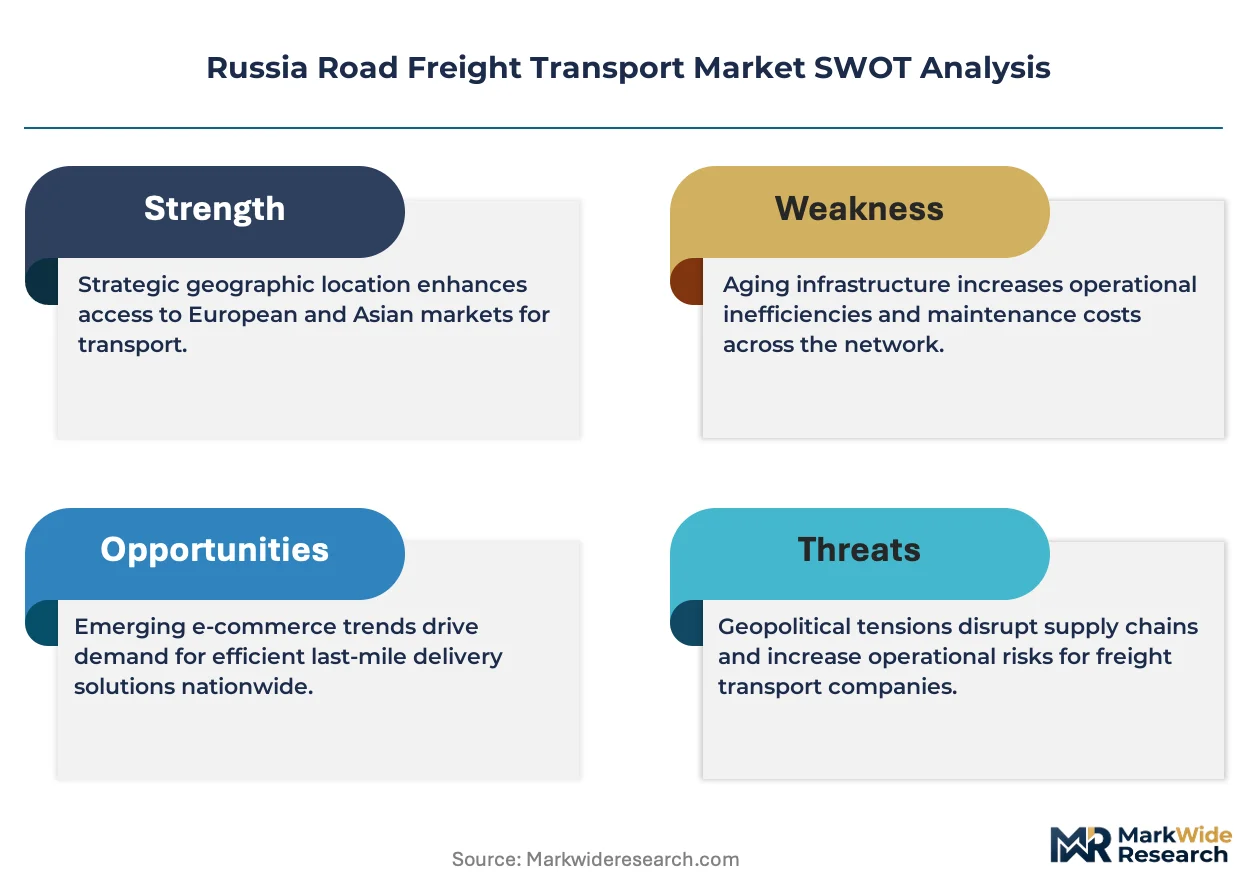
The Platon toll system administered by RT-Invest Transport Systems is restructuring operating economics for heavy-duty carriers, forcing fleet-wide decisions between toll avoidance through route optimization, axle-weight compliance investments, or subcontracting to larger integrated operators with scale efficiencies.
Growth Catalysts
- E-commerce fulfillment density:Online retail consolidation in Moscow's Central Federal District is generating dedicated fleet contracts for next-day delivery corridors to Tver, Vladimir, and Kaluga.
- Rosavtodor concession expansion:Federal highway modernization programs are reducing transit times on the M-11 Neva and M-4 Don corridors, improving asset utilization rates for long-haul operators.
- Cold-chain infrastructure:Refrigerated transport demand from agro-industrial clusters in Krasnodar Krai and Rostov Oblast is pulling specialized capacity southward from Moscow distribution hubs.
Market Restraints
- Platon toll escalation:Per-kilometer charges for twelve-ton-plus vehicles directly inflate marginal costs on trunk routes, squeezing smaller carriers with thin operating margins.
- Euro-5 compliance capital burden:Domestic tractor production at KAMAZ and GAZ Group faces technology gaps versus European emission benchmarks, delaying fleet renewal cycles.
- Driver qualification bottlenecks:Federal mobility statutes under the Ministry of Transport mandate enhanced certification timelines, constraining available labor supply during peak seasons.
Strategic Opportunities
- Siberian project cargo corridors:Industrial development in Krasnoyarsk Krai and Irkutsk Oblast is creating specialized heavy-haul demand for mining and energy infrastructure components.
- Digital freight matching platforms:Real-time load-board integration is collapsing empty-mile ratios for mid-size carriers operating between European Russia and the Urals.
- Platon penalty avoidance through telematics:On-board axle-weight monitoring systems compliant with RT-Invest protocols are opening subcontracting partnerships with penalty-averse shippers.
Industry Challenges
- Maintenance depot spacing constraints:In-house service networks require 400-kilometer interval coverage to sustain long-haul reliability, demanding capital-intensive real estate commitments in low-density regions.
- Terminal consolidation complexity:Hub-and-spoke Less Than Truck Load operations face synchronization failures when connecting Moscow consolidation points with regional spoke destinations across multiple time zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Road Freight Transport Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Dedicated Freight, Intermodal Transport Vehicle Type: Flatbed Trucks, Refrigerated Trucks, Tankers, Cargo Vans End User: Retail, Manufacturing, Construction, E-Commerce Delivery Mode: Same Day Delivery, Scheduled Delivery, Expedited Shipping, Standard Shipping |
| Companies Covered | ITECO Corporation, Globaltruck, Delovye Linii Group, TransContainer, Pro Logistics Group, MONOPOLY, PEK, OOO, ATI.SU, FESCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Road Freight Transport Market Evolving Landscape
Telematics integration and emission compliance technologies are compressing operational planning horizons, while procurement patterns favor carriers with documented toll-optimization capabilities and certified cold-chain integrity.
GPS-enabled route optimization combined with real-time Platon toll calculators is collapsing traditional dispatch decision cycles from daily to hourly intervals. Large fleet operators in the Central Federal District are adopting these systems fastest, compressing the competitive advantage window for technology laggards and forcing mid-size carriers into platform partnerships or obsolescence.
Rosavtodor axle-weight enforcement protocols under federal mobility statutes are mandating on-board mass monitoring for heavy-duty vehicles. This regulatory pressure is accelerating telematics hardware installation across long-haul fleets, with compliance costs concentrated among owner-operators lacking capital access for certified equipment upgrades.
Shippers in food processing and pharmaceutical verticals are consolidating vendor relationships around carriers with documented temperature-integrity certification. This buyer concentration is displacing fragmented spot-market procurement for refrigerated lanes between Moscow and southern agricultural zones, favoring integrated operators with dedicated cold-chain assets and terminal-controlled last-mile scheduling.
Russia Road Freight Transport Market Segmentation
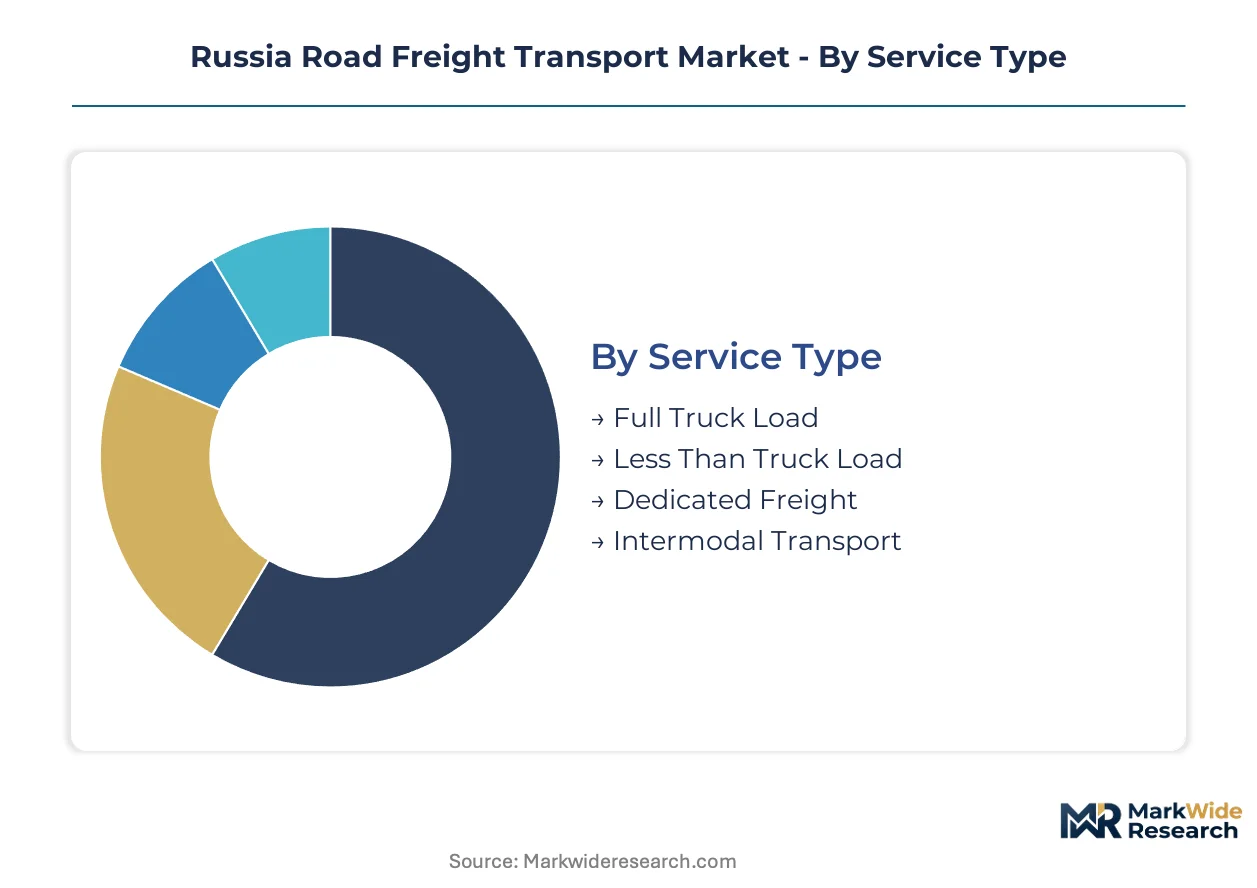
Service differentiation across Russia's road freight market determines carrier capital allocation and route specialization. Fleet composition and delivery velocity requirements segment operational capabilities, while end-use concentration shapes geographic coverage priorities.
Service Type:
Cost tier structures separate asset-heavy dedicated operations from variable-cost spot market participation, with capital intensity driving margin profiles across the service spectrum.
- Full Truck Load:Dedicated tractor-trailer capacity moves single-shipper cargo volumes exceeding twelve tons on direct origin-destination routing. Moscow-Urals corridor demand concentrates among consolidated fleet operators with Rosavtodor concession access, where Platon toll optimization through axle-weight compliance protects per-kilometer margins.
- Less Than Truck Load:Hub-and-spoke terminal consolidation aggregates fragmented shipments below five tons into optimized trailer loads. Tver-Vladimir freight axis operators leverage Delovye Linii Group terminal density to synchronize spoke connections across European Russia's time zone complexity.
- Dedicated Freight:Contracted fleet availability guarantees capacity allocation for industrial shippers with predictable volume profiles. Mining and energy infrastructure clients in Krasnoyarsk Krai anchor long-term agreements with ITECO Corporation for project cargo scheduling.
- Intermodal Transport:Rail-highway coordination extends reach beyond pure road economics on trans-Siberian corridors.
Full Truck Load holds installed capacity. Less Than Truck Load is rotating up the share rankings through e-commerce consolidation density.
Vehicle Type:
Application specialization segments fleet investment by cargo protection requirements and regulatory compliance burdens.
- Refrigerated Trucks:Insulated trailer units with continuous temperature monitoring preserve cold-chain integrity for pharmaceutical and food cargo. Krasnodar Krai agricultural exporters mandate certified carriers for Moscow distribution hub connections, where temperature-integrity documentation displaces spot-market procurement.
- Flatbed Trucks:Open-deck configurations accommodate dimensional cargo and containerized loads with flexible securing systems. Construction material movements across the Central Federal District concentrate demand among operators with project cargo securing certification.
- Tankers:Specialized liquid and dry-bulk containment serves chemical and petroleum product distribution networks.
- Cargo Vans:Light commercial vehicles below 3.5 tons execute urban last-mile delivery exempt from Platon toll obligations.
Refrigerated Trucks command premium rate structures. Cargo Vans are gaining share fastest through Moscow ring road corridor e-commerce density.
End User:
Customer type concentration determines service level requirements and contract duration preferences across vertical markets.
- E-Commerce:Next-day delivery velocity mandates real-time tracking and flexible scheduling across Central Federal District fulfillment networks. Online retail consolidation in Moscow generates dedicated fleet contracts with penalty clauses for missed delivery windows.
- Manufacturing:Just-in-time component logistics requires synchronized inbound supply chain coordination. Automotive and industrial equipment producers in Tver Oblast anchor scheduled delivery agreements with integrated operators.
- Retail:Seasonal volume peaks demand surge capacity access for distribution center replenishment.
- Construction:Project-based cargo movements require heavy-haul permitting and specialized equipment for infrastructure components.
Manufacturing holds installed contract value. E-Commerce is climbing the fastest through fulfillment network expansion.
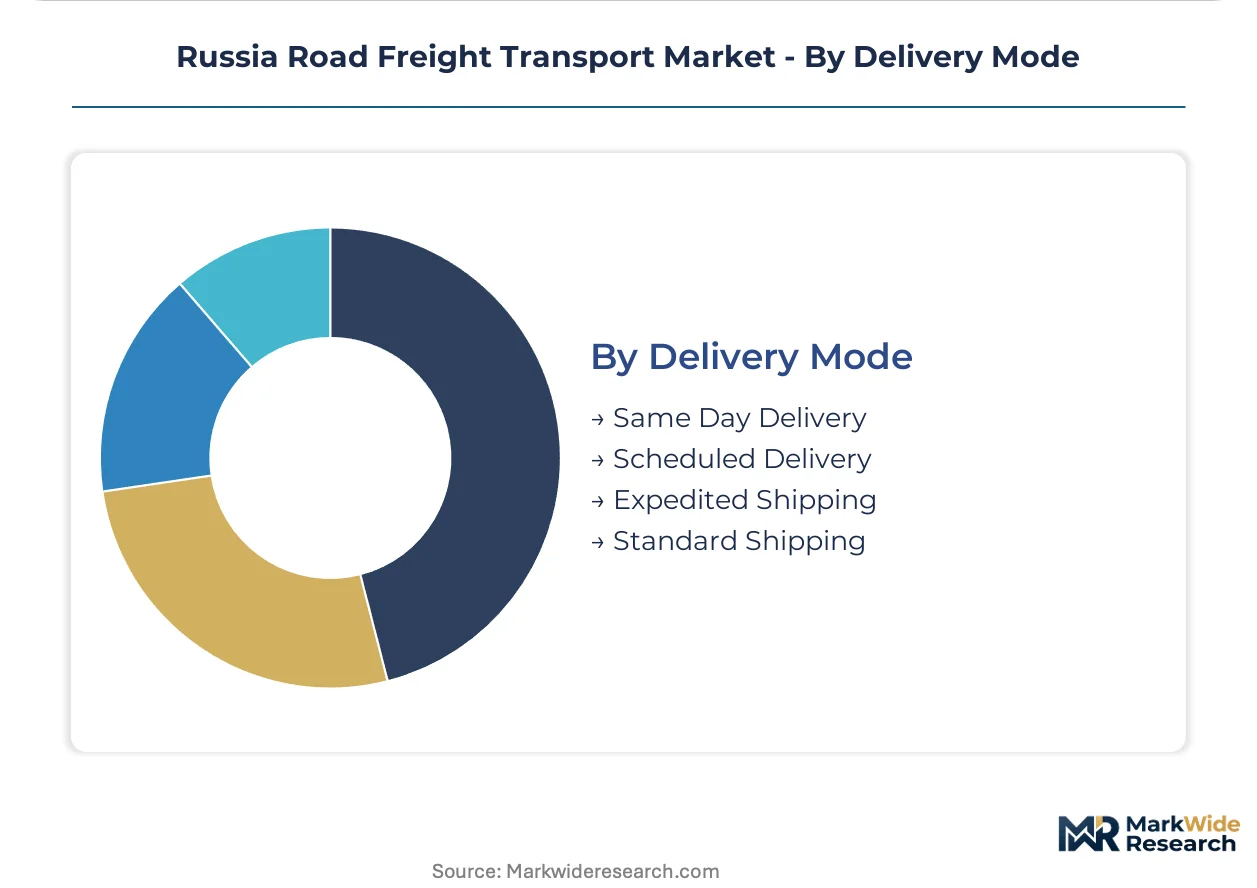
Delivery Mode:
Velocity tier segmentation matches shipper cost sensitivity against transit time requirements across distance bands.
- Same Day Delivery:Express routing within 200-kilometer radii demands dedicated fleet positioning and dynamic dispatch systems. Moscow metropolitan area e-commerce fulfillment concentrates among carriers with GPS-enabled route optimization collapsing decision cycles to hourly intervals.
- Expedited Shipping:Accelerated transit with guaranteed delivery windows serves time-critical manufacturing supply chains. Ural Mountains crossing routes utilize M-11 Neva corridor modernization to compress transit times for penalty-sensitive shippers.
- Scheduled Delivery:Recurring appointment windows support retail replenishment and manufacturing inbound logistics.
- Standard Shipping:Cost-optimized routing with flexible transit windows maximizes asset utilization for non-urgent cargo.
Scheduled Delivery holds installed volume. Same Day Delivery is expanding most quickly through Central Federal District fulfillment density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow commands premium rate structures for refrigerated and dedicated freight, while Siberian corridors absorb higher per-kilometer costs due to depot spacing requirements and Platon toll accumulation on extended hauls.
Central Federal District
E-commerce fulfillment density concentrates fleet investment around Moscow's ring road corridor and the Tver-Vladimir freight axis. Rosavtodor concession access on the M-11 Neva highway reduces transit times for consolidated operators. The Kaluga automotive cluster anchors just-in-time component logistics contracts with dedicated carriers.
Volga Federal District
Chemical and petroleum product movements from Kazan and Nizhny Novgorod generate tanker demand along the M-7 Volga corridor. Federal axle-weight enforcement protocols mandate on-board mass monitoring for heavy-duty vehicles crossing into the Central Federal District. Samara's aerospace manufacturing base sources inbound supply chain coordination from scheduled delivery operators.
Siberian Federal District
Mining and energy infrastructure development in Krasnoyarsk Krai and Irkutsk Oblast creates specialized heavy-haul demand for project cargo. The Ministry of Transport's driver qualification standards constrain labor supply during peak construction seasons. Novosibirsk functions as the primary consolidation hub for LTL spoke connections to remote industrial sites.
Far Eastern Federal District
Port-to-interior container movements from Vladivostok and Nakhodka require intermodal coordination with Trans-Siberian rail links. RT-Invest Transport Systems administers Platon toll collection on federal highways extending westward from the Pacific coast. Khabarovsk anchors cross-border freight corridors to China with customs-bonded terminal infrastructure.
Southern Federal District
Agricultural exporters in Krasnodar Krai and Rostov Oblast mandate certified refrigerated carriers for cold-chain connections to Moscow distribution hubs. Euro-5 emission compliance gaps in domestic tractor production delay fleet renewal cycles for regional operators. The M-4 Don corridor modernization improves asset utilization rates for grain and food product movements.
Russia Road Freight Transport Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on equipment and maintenance services. The Russia road freight market structures around consolidated fleet operators with terminal network density, mid-scale carriers dependent on digital freight matching, and specialized project cargo handlers. Three archetypes dominate: integrated logistics platforms with concession access, asset-heavy long-haul specialists with depot networks, and technology-enabled intermediaries collapsing empty-mile ratios. Competitive positioning sharpens through M&A consolidation among regional carriers and strategic partnerships around Platon toll optimization systems.
Within the integrated platform tier, Delovye Linii Group and Globaltruck exemplify divergent scale strategies. Delovye Linii leverages terminal density across European Russia to control hub-and-spoke synchronization. Globaltruck sustains long-haul reliability through captive maintenance infrastructure. ITECO Corporation occupies the project cargo specialization vector, anchoring heavy-haul capacity for Siberian industrial clients. These three represent the structural fault lines between network density, asset control, and vertical capability depth.
| Leading Market Players |
|---|
| ITECO Corporation |
| Globaltruck |
| Delovye Linii Group |
| TransContainer |
| Pro Logistics Group |
| MONOPOLY |
| PEK, OOO |
| ATI.SU |
| FESCO |
| Others |
Value Network & Pricing Analysis
Domestic tractor production concentration at KAMAZ and GAZ Group facilities in Tatarstan and Nizhny Novgorod Oblast anchors downstream margin distribution, with Euro-5 compliance technology gaps forcing fleet operators toward premium-priced European imports or domestically subsidized renewal programs.
Pricing Analysis
Configured-to-order dedicated freight contracts command spreads against standard spot-market rates, with three-tier pricing structure across premium, standard, and economy levels. Premium tier pricing rests on Platon toll optimization guarantees and certified cold-chain documentation, while standard tier absorbs axle-weight penalty exposure. Cost compression in the economy tier intensifies because smaller carriers lack capital access for telematics compliance hardware. E-commerce shippers exhibit highest price sensitivity, whereas pharmaceutical verticals accept premium rates for temperature-integrity certification.
Supply Chain Analysis
Upstream feedstock for commercial vehicle manufacturing draws from Germany, China, and Japan for emission-control systems, precision electronics, and high-grade steel components. Diesel engine technology sources from European licensors, while telematics hardware hinges on Asian semiconductor supply chains. Single-source vulnerability concentrates in Euro-5 catalytic converter substrates, creating procurement risk for fleet renewal programs. Distribution runs through captive maintenance depots spaced at 400-kilometer intervals, with regional parts consolidation feeding spoke terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet modernization capability gaps—specifically Euro-5 compliance engineering and certified driver training infrastructure—concentrate competitive advantage among operators with state-backed concession access or private equity scale.
For Market Incumbents: Pre-empt margin erosion from Platon toll escalation by consolidating axle-weight compliance investments across captive depot networks. Secure Rosavtodor concession extensions on M-11 Neva and M-4 Don corridors before regulatory capacity caps harden. Backward integration into certified telematics installation protects against RT-Invest penalty exposure. For New Entrants and Emerging Players: Mid-size carriers operating between European Russia and the Urals without dedicated terminal infrastructure represent the most penetrable entry point for digital freight matching platform partnerships. White-space concentrates in refrigerated LTL consolidation for Krasnodar Krai agricultural exporters lacking Moscow hub connections. Go-to-market positioning should anchor on real-time Platon toll calculator integration as a cost transparency differentiator. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional carriers holding 200-400 vehicle fleets and established shipper relationships but lacking telematics modernization capital. Long-term viability across the analysis window favors operators with documented toll-optimization capabilities and Siberian project cargo optionality. Watch RT-Invest toll rate revision announcements as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platon Telematics Compliance Investment | RT-Invest protocol certification opens subcontracting partnerships with penalty-averse industrial shippers. |
| Siberian Depot Network Expansion | Krasnoyarsk Krai maintenance infrastructure captures mining and energy project cargo scheduling. |
| Refrigerated Fleet Certification | Temperature-integrity documentation displaces spot-market procurement for pharmaceutical verticals. |
| Digital Freight Platform Integration | Real-time load-board partnerships collapse empty-mile ratios for mid-size Urals corridor operators. |
| Rosavtodor Concession Renewal | M-11 Neva and M-4 Don access protects per-kilometer margins against toll-avoidance route degradation. |
Research Methodology
A spread of perspectives from fleet operations directors, Rosavtodor concession managers, shipper procurement leads, and refrigerated cargo quality officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Ministry of Transport licensing databases, Platon toll system utilization reports, and federal highway modernization disclosures. Bottom-up carrier capacity modeling and top-down freight volume projections triangulated segment-level outputs.
Demand-supply-balance framing structured the analytical framework across the analysis window, with segmentation dimensions spanning service type, vehicle specialization, end-use vertical, and delivery velocity tier. CAGRs derived from fleet order pipeline analysis, e-commerce fulfillment density metrics, and industrial project cargo scheduling patterns. Forecast inputs incorporated Platon toll rate sensitivity and Euro-5 compliance adoption curves.
Practitioners should monitor RT-Invest toll schedule revisions, Rosavtodor concession award timelines, and domestic tractor production technology gaps for early signals. Forecasts reflect documented assumptions about federal mobility statute enforcement intensity and driver qualification standard implementation pace. Cross-checking against Ministry of Transport freight turnover statistics and Central Bank logistics sector credit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Europe Fleet Management Market