
 Global Marine Port Services Market | 2026-2036
Global Marine Port Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Port Services Market Foresight
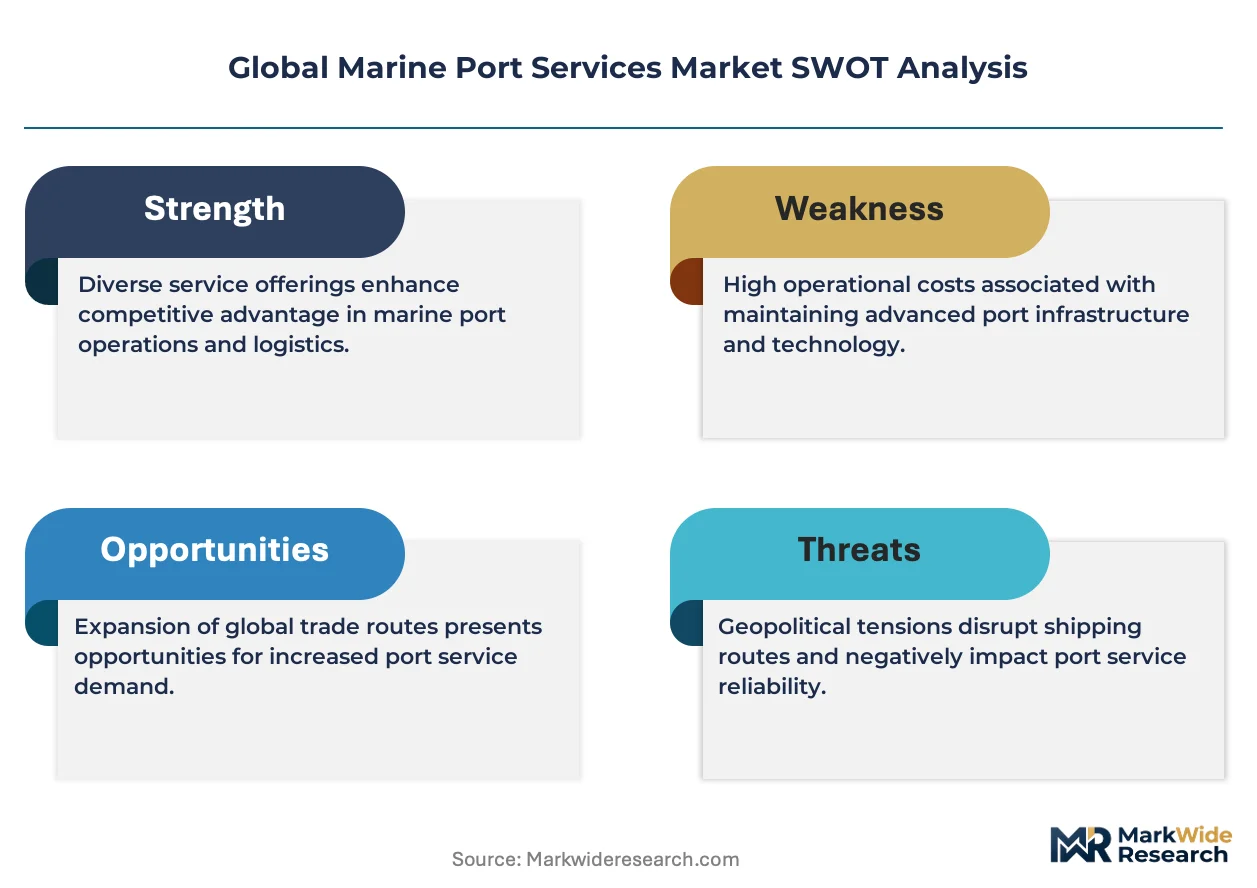
The EU Green Deal is consolidating demand for shore power and low-emission bunkering across European container terminals. DP World Limited leverages its Jebel Ali and London Gateway assets to sustain integrated logistics offerings across three continents. PSA International anchors automated yard operations in Singapore and Antwerp, competing on throughput efficiency against regional rivals. COSCO Shipping Ports Limited dominates Chinese coastal throughput while extending Belt and Road terminal investments into Greece and Spain.
Global marine port services encompass the operational, technical, and logistical functions enabling vessel berthing, cargo transfer, and maritime supply chain continuity, requiring fender systems rated for 50,000–200,000 DWT vessel classes and quay cranes with 65+ tonne lift capacity. Cargo handling generates the largest revenue pool among service types, though ship repair commands premium margins at specialized yards in Hamburg and Dubai. Container terminals absorb the majority of infrastructure capital, while cruise terminals in Barcelona and Miami recover faster from demand cyclicality than bulk facilities tied to commodity price swings.
The International Maritime Organization enforces sulfur cap regulations through MARPOL Annex VI, compelling ports to install scrubber-compatible reception facilities and LNG bunkering infrastructure. The EU F-Gas Regulation and national port authorities in Germany, the Netherlands, and the UAE mandate cold-ironing capabilities that reshape electrical grid investments at berth. Stakeholders must weigh stranded asset risk in conventional fueling infrastructure against the pace of green hydrogen certification standards and carrier fleet renewal commitments.
Market Dynamics
Container shipping lines are forcing terminal operators to automate cargo handling systems to maintain throughput competitiveness amid vessel size inflation and labor cost pressures.
Growth Catalysts
- IMO MARPOL Annex VI sulfur caps:Ports across Singapore, Rotterdam, and Los Angeles are installing scrubber-compatible reception facilities and LNG bunkering infrastructure to capture vessel traffic.
- Mega-container vessel deployment:Terminals in Shanghai and Antwerp are deepening berths and expanding yard automation to handle 24,000+ TEU vessel classes.
- EU Green Deal cold-ironing mandates:European container terminals are retrofitting electrical grid infrastructure to supply shore power and comply with F-Gas Regulation requirements.
Market Restraints
- Steel price volatility:Quay crane construction and fender system fabrication face input cost swings that compress project margins at greenfield terminals.
- Specialized equipment supply concentration:Heavy-lift crane manufacturing concentrates in China and Germany, creating procurement bottlenecks for mid-sized port authorities.
- Green hydrogen certification gaps:Absence of unified bunkering standards delays alternative fuel infrastructure investment decisions at multi-fuel terminals.
Strategic Opportunities
- Underpenetrated African hub development:Djibouti and Mombasa offer first-mover advantages for automated transshipment facilities serving East African trade corridors.
- Digital twin integration:Convergence of IoT sensor networks with predictive maintenance software is enabling berth optimization and yard crane scheduling improvements.
- US Inflation Reduction Act port electrification credits:Tax incentives are accelerating cold-ironing retrofits at California and Pacific Northwest container terminals.
Industry Challenges
- Automation technician scarcity:Terminal operators in Hamburg and Dubai struggle to recruit software engineers capable of maintaining autonomous yard crane systems.
- Legacy crane control system integration:Brownfield terminals face software architecture conflicts when retrofitting AI-driven container positioning onto 1990s-era hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Port Services Market |
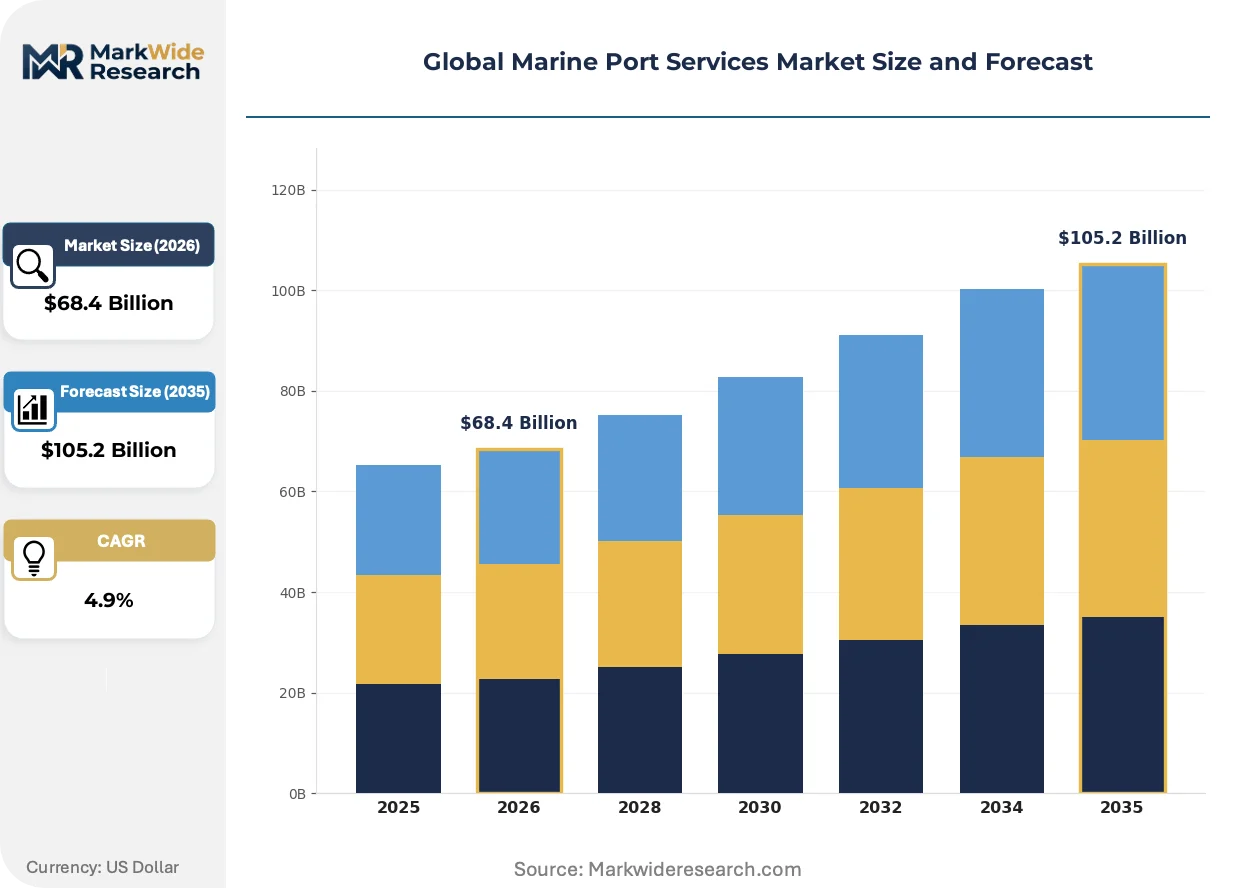
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $105.2 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cargo Handling, Pilotage, Towage, Ship Repair, Bunkering Port Infrastructure: Container Terminals, Bulk Terminals, Ro-Ro Terminals, Cruise Terminals, Breakbulk Facilities Shipping Mode: Container Ships, Bulk Carriers, Tankers, Passenger Vessels, Offshore Support Vessels Customer Type: Shipping Lines, Freight Forwarders, Importers, Exporters, Logistics Operators |
| Companies Covered | Hutchison Port Holdings, Shanghai International Port (Group), DP World Limited, China Merchants Port Holdings Company Limited, Hamburger Hafen Und Logistik AG, PSA International, International Container Terminal Services Inc., APM Terminals, COSCO Shipping Ports Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Port Services Market Shifts & Advancements
Digitalization of vessel traffic management and berth allocation systems is compressing turnaround times and enabling dynamic pricing models for terminal capacity.
Autonomous yard cranes equipped with computer vision and lidar-based positioning systems are integrating real-time container tracking with terminal operating software. Major transshipment hubs in Singapore and Rotterdam are deploying these systems to reduce human error in high-density stacking environments. The technology is integrating predictive maintenance algorithms that anticipate hydraulic and electrical failures before operational disruption occurs.
EU F-Gas Regulation phase-down schedules are compelling refrigerated container terminals to retrofit cooling systems with lower-global-warming-potential refrigerants. Cold chain facilities at Antwerp and Hamburg face compliance deadlines that accelerate capital replacement cycles. Container lines operating Mediterranean routes are prioritizing terminals with certified low-emission reefers to avoid regulatory penalties and brand exposure.
Carrier consolidation into three major alliances is concentrating procurement leverage and compressing terminal concession negotiations. Shipping lines now demand guaranteed berth windows and priority crane allocation as standard contract terms rather than premium services. This pattern is most visible at Southeast Asian transshipment hubs where alliance members control 70%+ of vessel calls and can shift volumes between competing terminals within the same port cluster.
Global Marine Port Services Market Segmentation
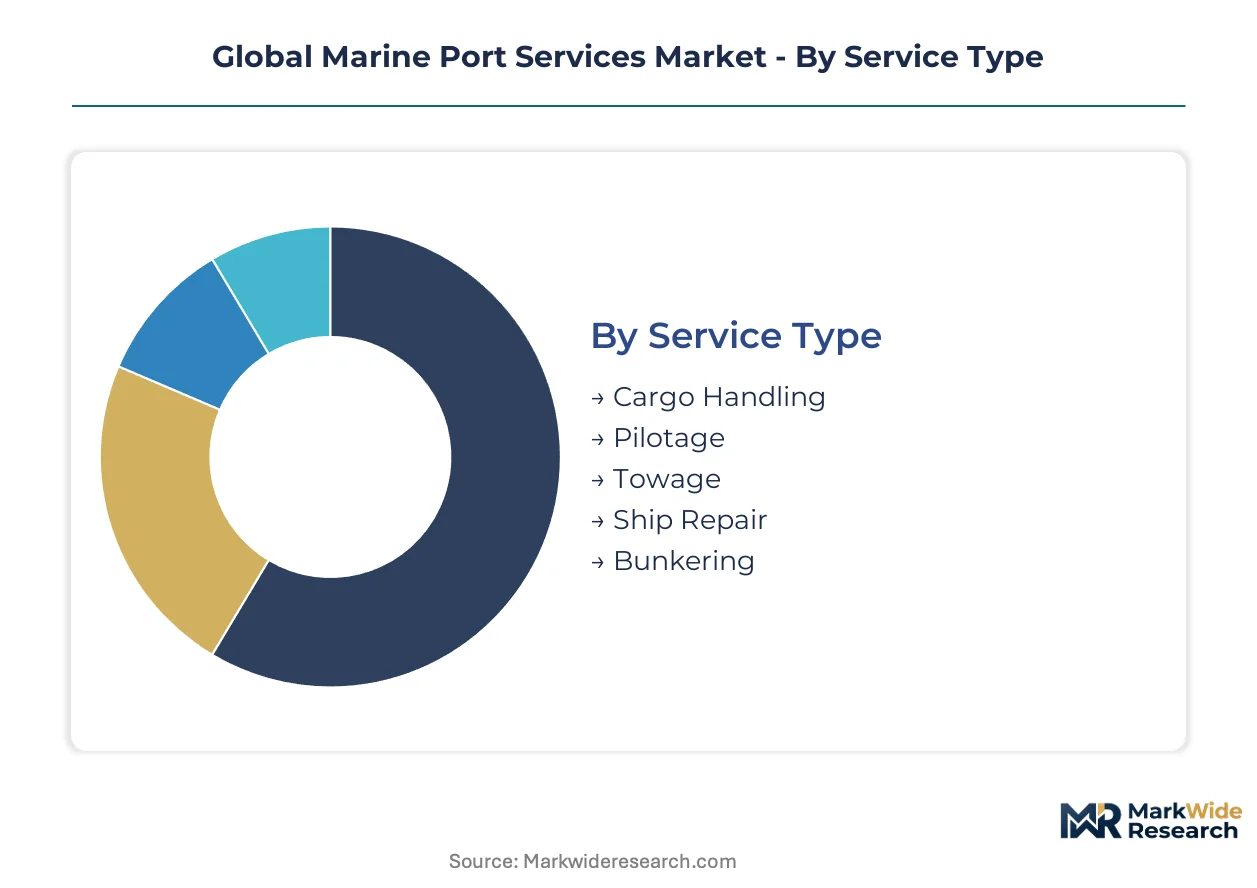
Port service providers structure operations around vessel specifications, cargo categories, and customer procurement patterns. Segmentation clarity enables terminal operators to allocate capital between high-throughput automation and specialized handling capabilities.
Service Type:
Cargo handling absorbs the heaviest capital deployment, with quay cranes and automated yard systems requiring decades-long amortization schedules.
- Cargo Handling:Quay cranes rated for 65+ tonne lifts and automated guided vehicles dominate capital expenditure at mega-hubs. Demand concentrates in Singapore and Rotterdam as vessel size inflation forces throughput upgrades.
- Pilotage:Licensed harbor pilots navigate vessels through confined channels and berthing maneuvers. Regulatory mandates in Hamburg and Dubai require compulsory pilotage for vessels above specific tonnage thresholds.
- Towage:Tug fleets provide maneuvering assistance and emergency response. Port authorities in Shanghai and Antwerp maintain dedicated fleets to guarantee berth availability during peak windows.
- Ship Repair:Dry dock facilities and specialized yards command premium margins. Hamburg and Dubai anchor regional repair clusters serving container lines and tanker operators.
- Bunkering:Fuel supply operations are restructuring around IMO sulfur caps and LNG infrastructure. Singapore and Rotterdam lead alternative fuel investment to capture vessel traffic.
Most installed capacity flows through cargo handling. Expansion is steepest in bunkering as decarbonization mandates reshape fuel infrastructure.
Port Infrastructure:
Terminal category selection determines concession length, revenue stability, and exposure to trade cyclicality.
- Container Terminals:Deep-water berths and automated stacking yards handle 24,000+ TEU vessel classes. Shanghai and Antwerp anchor mega-hub investments with 50-year concession structures.
- Bulk Terminals:Specialized equipment for iron ore, coal, and grain with dedicated unloading systems. Demand tracks commodity price swings at facilities in Rotterdam and Qingdao.
- Ro-Ro Terminals:Roll-on/roll-off facilities serve vehicle carriers and project cargo. Bremerhaven and Zeebrugge concentrate European automotive throughput.
- Cruise Terminals:Passenger processing infrastructure with lower capital intensity than cargo facilities. Barcelona and Miami recover faster from demand disruptions than commodity-linked terminals.
- Breakbulk Facilities:General cargo handling for non-containerized manufactured goods. Antwerp and Hamburg maintain specialized sheds for project cargo and heavy lifts.
Revenue concentration sits with container terminals. Cruise infrastructure is gaining share fastest as passenger volumes rebound and terminal fees reprice.
Shipping Mode:
Vessel type dictates berth design, fender specifications, and auxiliary service requirements.
- Container Ships:Box carriers drive quay crane specifications and yard automation investments. Mega-vessels at Singapore and Los Angeles force 23-meter depth requirements.
- Bulk Carriers:Dry bulk and ore carriers require dedicated unloading equipment and stockyard capacity. Qingdao and Port Hedland anchor iron ore throughput corridors.
- Tankers:Liquid bulk vessels demand specialized manifold connections and spill containment systems. Rotterdam and Houston concentrate crude and product tanker calls.
- Passenger Vessels:Cruise and ferry operations need passenger terminals with customs and immigration integration. Miami and Barcelona lead cruise embarkation infrastructure.
- Offshore Support Vessels:Supply boats and crew transfer vessels serve energy extraction platforms. Aberdeen and Stavanger anchor North Sea support bases.
Container ships absorb the majority of berth construction investment. Offshore support vessels are expanding most quickly as floating wind installations multiply.
Customer Type:
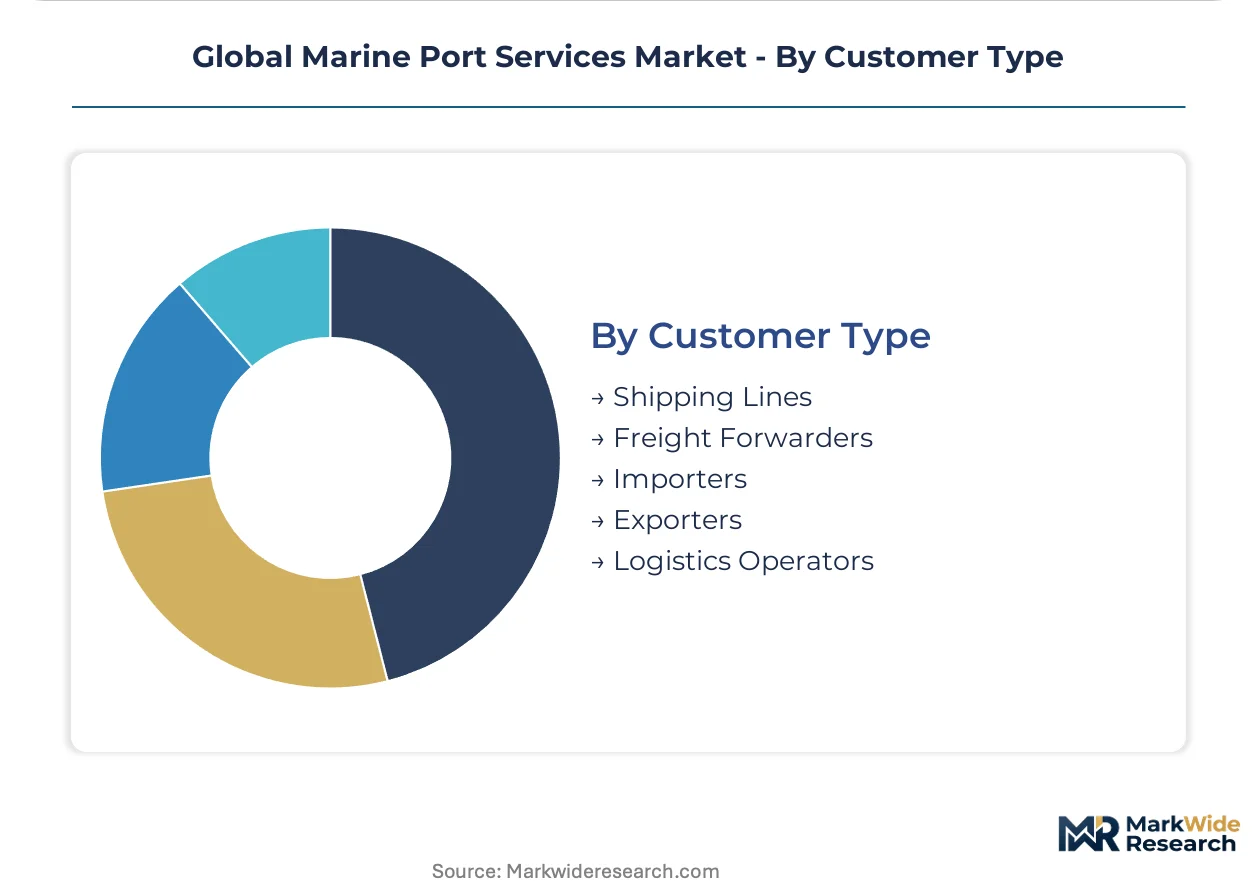
Procurement patterns diverge between asset-heavy carriers and intermediary service providers.
- Shipping Lines:Ocean carriers negotiate long-term terminal concessions and demand guaranteed berth windows. Alliance consolidation in Singapore and Rotterdam concentrates procurement leverage.
- Freight Forwarders:Intermediaries book terminal capacity and auxiliary services on behalf of cargo owners. Forwarders in Hamburg and Dubai aggregate demand across multiple carrier relationships.
- Importers:Beneficial cargo owners procure terminal handling for inbound supply chains. Retail importers in Los Angeles and Long Beach drive peak season volume spikes.
- Exporters:Outbound cargo owners contract stevedoring and yard storage. Agricultural exporters in Santos and New Orleans seasonally saturate grain terminals.
- Logistics Operators:Integrated providers bundle port services with inland distribution. DP World and PSA International capture logistics operators through terminal-plus-warehouse offerings.
Shipping lines control the largest contract value. Logistics operators are climbing the fastest as vertical integration blurs terminal and hinterland boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern container shipping traces its commercial origins to standardized box movements through Rotterdam and Singapore during the 1960s. Those two ports established the operational templates—deep-water berths, gantry crane standardization, and intermodal connectivity—that subsequent hubs replicated worldwide. Today, marine port services concentrate in five national markets that collectively handle over sixty percent of global container throughput.
China
Shanghai and Ningbo-Zhoushan process the world's largest container volumes, driven by manufacturing exports from the Yangtze River Delta. The Ministry of Transport enforces port emission control area standards that mandate shore power availability at designated berths. COSCO Shipping Ports Limited anchors terminal operations across Dalian, Qingdao, and Guangzhou while extending Belt and Road investments into Mediterranean facilities.
Singapore
The Port of Singapore maintains its position as the premier transshipment hub connecting Asia-Europe and intra-Asian trade lanes. The Maritime and Port Authority of Singapore administers the Green Port Programme, offering tariff incentives for vessels adopting low-carbon technologies. PSA International operates automated terminal facilities at Pasir Panjang, competing on berth productivity metrics against regional rivals in Tanjung Pelepas and Laem Chabang.
Netherlands
Rotterdam ranks as Europe's largest seaport, handling crude oil, coal, and containerized cargo through Maasvlakte deep-water terminals. The EU Green Deal and national climate legislation require shore power installation at all container and cruise berths by 2030. Hamburger Hafen Und Logistik AG maintains cross-border terminal partnerships linking Rotterdam's hinterland rail network to German industrial centers.
United Arab Emirates
Jebel Ali Port in Dubai serves as the primary gateway for Gulf trade, with DP World Limited operating integrated logistics corridors connecting maritime terminals to free zone warehousing. The UAE's federal maritime regulations align with IMO MARPOL Annex VI standards while permitting LNG bunkering infrastructure development. Abu Dhabi Khalifa Port competes for transshipment volumes through Khalifa Industrial Zone anchor tenant arrangements.
Germany
Hamburg and Bremerhaven anchor North European container handling, with Hamburg Hafen Und Logistik AG operating three container terminals along the Elbe River. The Federal Immission Control Act implements EU F-Gas Regulation requirements for refrigerated cargo facilities and mandates cold-ironing capabilities at major berths. German port authorities coordinate with Dutch and Belgian counterparts on Rhine corridor barge connectivity optimization.
Global Marine Port Services Market Competitive Landscape
Capital-heavy terminal operators compete with asset-light logistics integrators for control of cargo flows and concession revenues. The market structure consolidates around three to five global players managing multi-continent terminal networks, while regional specialists retain strong positions in single-country markets. Strategic archetypes include integrated port-to-door logistics providers, pure-play terminal operators maximizing throughput efficiency, and state-linked entities securing trade corridor access. Dominant competitive moves involve long-term concession renewals at anchor hubs and vertical integration into adjacent warehousing and inland distribution services.
Among Asia-Pacific headquartered operators, Hutchison Port Holdings, Shanghai International Port (Group), and China Merchants Port Holdings Company Limited exemplify the state-linked archetype, occupying positions that balance commercial returns against national trade corridor objectives. These entities sit within tiered competitive structures where scale advantages in crane productivity and yard automation create defensive moats against mid-sized regional challengers.
| Leading Market Players |
|---|
| Hutchison Port Holdings |
| Shanghai International Port (Group) |
| DP World Limited |
| China Merchants Port Holdings Company Limited |
| Hamburger Hafen Und Logistik AG |
| PSA International |
| International Container Terminal Services Inc. |
| APM Terminals |
| COSCO Shipping Ports Limited |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between IMO-compliant green bunkering and conventional fuel services splits terminal revenue models and procurement networks simultaneously. Premium berth access at Singapore and Rotterdam commands tariff multiples tied to scrubber reception and LNG infrastructure availability, while commodity handling at secondary hubs competes on volume throughput and labor arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs terminal service contracts. Price differentiation stems from automation certification tiers and guaranteed berth window allocations. Cost compression in standard-tier cargo handling intensifies because steel price volatility squeezes crane fabrication margins. Freight forwarders aggregate demand across carriers and exhibit highest price sensitivity; integrated shipping lines securing long-term concessions show lowest sensitivity.
Supply Chain Analysis
Heavy-lift crane manufacturing rests on Chinese and German fabrication clusters for quay systems rated at 65+ tonne lift capacity. Steel plate and high-tensile cabling feed from South Korean and Japanese metallurgical suppliers. Single-source vulnerability concentrates in autonomous yard crane control systems sourced from limited automation vendors. Distribution runs through terminal operator procurement departments negotiating multi-year equipment leases with manufacturer-direct technical service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge where EU Green Deal mandates accelerate cold-ironing investment against Middle Eastern jurisdictions with more flexible emission compliance timelines, compressing relative capital efficiency at European terminals.
For Market Incumbents: Anticipate alliance consolidation pressure by securing 50-year concession renewals at anchor hubs before procurement leverage shifts further toward carrier alliances. Deepen backward integration into adjacent free zone warehousing to capture logistics operator spend. Counter automation technician scarcity through captive training partnerships with Hamburg and Dubai technical institutes. For New Entrants and Emerging Players: Launch via automated transshipment facility development at underpenetrated East African corridors serving Djibouti and Mombasa trade volumes. Target first-mover positioning in multi-fuel bunkering infrastructure where green hydrogen certification gaps delay incumbent commitment. Pursue digital twin integration partnerships with terminal operating software vendors as primary go-to-market channel. For Investors and Strategic Acquirers: Consolidation pressure builds where brownfield terminals face legacy crane control system integration failures against greenfield automation benchmarks. Five-to-ten year viability favors operators with deployed autonomous yard systems and shore power retrofit completion. Monitor EU F-Gas Regulation compliance deadlines at Antwerp and Hamburg refrigerated facilities as inflection signal for cold chain terminal valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Terminal Expansion | Deploys autonomous yard cranes at Pasir Panjang to match PSA International throughput benchmarks. |
| Multi-Fuel Bunkering Infrastructure | Installs LNG and future hydrogen compatibility at Rotterdam to capture IMO MARPOL Annex VI vessel traffic. |
| Shore Power Grid Retrofit | Upgrades electrical infrastructure at Hamburg to satisfy EU Green Deal cold-ironing mandates. |
| Digital Twin Platform Integration | Converges IoT sensor networks with predictive maintenance software for berth optimization. |
| Free Zone Logistics Corridor Development | Links Jebel Ali maritime terminals to DP World warehousing through integrated customs clearance. |
Research Methodology
Direct dialogue with terminal operations directors, port authority procurement managers, shipping line fleet planners, and automation system engineers grounded qualitative findings in operational reality. Secondary validation drew from IMO MARPOL regulatory filings, EU F-Gas Regulation implementation schedules, port authority concession documents, and customs trade flow databases. Bottom-up volume estimates triangulated against top-down macro trade projections across the analysis window.
Bottom-up modeling anchored forecasts in berth capacity utilization, vessel size class deployment schedules, and terminal automation capex cycles segmented by service type, port infrastructure category, and shipping mode. Top-down cross-checks applied trade corridor growth assumptions and regulatory compliance cost burdens. CAGRs derived from iterative convergence between throughput elasticity models and infrastructure investment lag structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated green hydrogen certification timelines or prolonged steel price volatility. Projections reflect documented assumptions regarding alliance consolidation velocity and decarbonization mandate enforcement intensity. Material deviation in IMO regulatory amendment schedules or carrier fleet renewal commitments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive & Transportation
Waste Collection Vehicle Market
Automotive & Transportation
Latin America Two-Wheeler Components Market
Automotive & Transportation
Vehicle Anti-Theft System Market
Automotive & Transportation
Intra-Asia Freight Forwarding Market
Automotive & Transportation
Mexico 3PL Market
Automotive & Transportation
Automotive Ultrasonic Sensors Market
Automotive & Transportation
Train Locomotive Suspension Market
Automotive & Transportation
Battery-Only Electric Bus Market
Automotive & Transportation
Chile Cold Chain Logistics Market
Automotive & Transportation
Europe Light Commercial Vehicle Trailer Market
Automotive & Transportation
Container Terminal Automation Market
Automotive & Transportation
Diesel Oxidation Catalyst Market
Automotive & Transportation
ASEAN Domestic Courier Market
Automotive & Transportation
Global Automotive Defogger System Market
Automotive & Transportation
China Stevedoring and Marine Cargo Handling Market
Automotive & Transportation
Digital Tire Inflator Market