
 Global Electric Classic Car Market | 2026-2036
Global Electric Classic Car Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Classic Car Market Analysis
Modular battery-pack architecture is rebalancing buyer choice between range-optimized touring configurations and lightweight track-day setups. Lunaz Design leverages in-house cell integration to sustain premium positioning across Rolls-Royce and Bentley conversions. Zelectric Motors anchors its competitive stance on Volkswagen Beetle and Porsche 911 electrification, dominating niche volume in North American restoration shops. Everrati differentiates through OEM-grade engineering partnerships, extending brand credibility into Ferrari and Lamborghini platforms.
An electric classic car constitutes a vintage or heritage automobile platform retrofitted with battery-electric propulsion, typically incorporating lithium-ion cell arrays of 40-100 kWh capacity, liquid-cooled thermal management, and regenerative braking systems to preserve original chassis dynamics while eliminating tailpipe emissions. Restomod conversions command the dominant value share as collectors prioritize authenticated provenance paired with modern drivetrain reliability. Solid-state power sources represent the fastest-growing technology segment, though lithium-ion configurations currently occupy the broadest installation base across personal use and rental applications. Replica builds concentrate margin pools in limited-production coachwork where carbon-fiber body panels reduce curb weight and extend effective range.
The EPA tailpipe exemption framework for pre-emissions-era vehicles shapes United States demand by preserving registration pathways for converted classics, while ECHA REACH compliance governs battery-cell chemistry imports into European Union restoration facilities. The F-Gas Regulation mandates refrigerant standards for thermal-management systems, influencing supplier selection across Germany, France, and Italy. China's GB standards for electric vehicle safety create certification barriers for imported conversion platforms. Stakeholders must monitor regulatory divergence between jurisdictions as type-approval pathways fragment and local content requirements reshape supplier geography.
Market Dynamics
Modular battery-pack architecture is compressing conversion timelines and rebalancing buyer choice between range-optimized touring configurations and lightweight track-day setups, forcing converters to develop dual-platform engineering capabilities.
Growth Catalysts
- EU Green Deal ICE Phase-Out:Mandates redirecting restoration investment toward zero-emission drivetrains across member states, accelerating certified conversion demand.
- Hospitality Fleet Electrification:Luxury hotel and vineyard operators in the United Kingdom commissioning electrified vintage Rolls-Royce and Jaguar fleets for guest experiences.
- Solid-State Chemistry Maturation:Cell energy density improvements enabling 100+ kWh packs within original engine bay footprints without structural chassis modification.
Market Restraints
- Lithium-Ion Cell Cost Volatility:Cathode material price swings compress converter margins on fixed-price restoration contracts.
- Specialist Labor Concentration:Certified high-voltage technicians cluster around Silverstone and the Cotswolds, creating geographic supply bottlenecks.
- EPA Tailpipe Exemption Uncertainty:Potential framework revisions threaten registration pathways for pre-emissions-era converted classics in the United States.
Strategic Opportunities
- Australian Collector Market:Underpenetrated demand for electrified Porsche 911 and Mercedes-Benz SL platforms among Sydney and Melbourne vintage car clubs.
- Track-Day Lightweight Configurations:Carbon-fiber battery enclosures and stripped interiors opening weekend motorsport segments previously unreachable by heavy touring setups.
- ECHA REACH Compliance Services:Battery-cell chemistry certification consulting for restoration facilities importing Asian-manufactured cells into European Union markets.
Industry Challenges
- High-Voltage Safety Certification:Converter workshops face 12-18 month approval timelines for EV-specific facility licensing under Germany's KBA and France's ANSM frameworks.
- Provenance Authentication:Documentation gaps for 1960s-1970s chassis complicate insurance underwriting and resale valuation for electrified classics.
- Thermal Management Integration:Liquid-cooled battery packs require bespoke routing through unmodified body shells, stretching engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Classic Car Market |
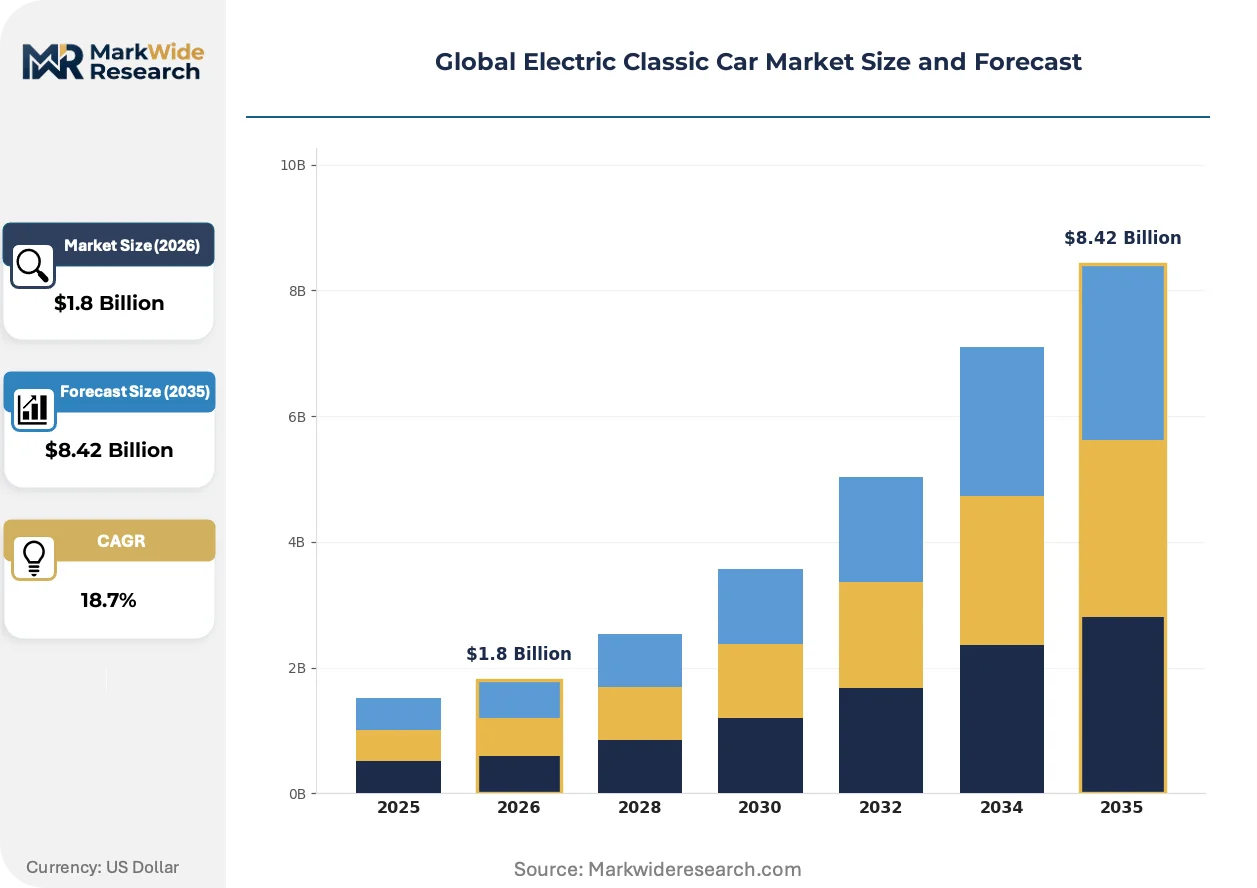
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Restomod, Vintage, Conversion Kits, Replica Power Source: Lithium-Ion, Lead-Acid, Solid State, Others Market Application: Personal Use, Collectors, Shows, Rentals Charging Infrastructure: Home Charging, Public Stations, Solar Solutions, Workplace Charging |
| Companies Covered | Electric Classic Cars, Lunaz Design, Zelectric Motors, EV West, Electrogenic, Everrati, Electric GT, Charge Cars, Zero Labs Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Classic Car Market Emerging Trajectories
Three intersecting forces are restructuring how vintage platforms receive zero-emission propulsion: cell chemistry evolution, regulatory pathway fragmentation, and buyer preference bifurcation between authenticity preservation and performance modernization.
Silicon-anode lithium-ion cells are expanding into the 40-80 kWh sweet spot for daily-driver classics, delivering 15-20% energy density gains over graphite predecessors without requiring chassis structural reinforcement. Specialist converters serving United Kingdom and German markets are adopting these cells for Jaguar E-Type and Mercedes-Benz W113 conversions, compressing pack volume enough to retain spare tire wells and original hood lines. This chemistry shift is expanding into previously uneconomical project categories, enabling electrification of lower-value 1970s mass-market platforms.
The F-Gas Regulation mandates refrigerant standards for thermal-management systems across Germany, France, and Italy, forcing converter supplier selection toward R-1234yf-compatible heat pump vendors. Workshops face retrofit complexity when integrating modern climate control into 1960s ventilation architectures, driving partnerships with HVAC engineering specialists. Ferrari and Lamborghini conversion specialists report the steepest compliance costs, as mid-engine layouts limit compressor placement options.
Collector procurement patterns are fragmenting between authenticated restomod purists and replica-build minimalists. United States buyers increasingly commission full chassis-up reconstructions with carbon-fiber coachwork, while United Kingdom demand concentrates on factory-matching serial number retention. Auction houses are responding with separate electrified-classic catalog categories, recognizing divergent resale value methodologies between provenance-preserved and ground-up builds.
Global Electric Classic Car Market Segmentation
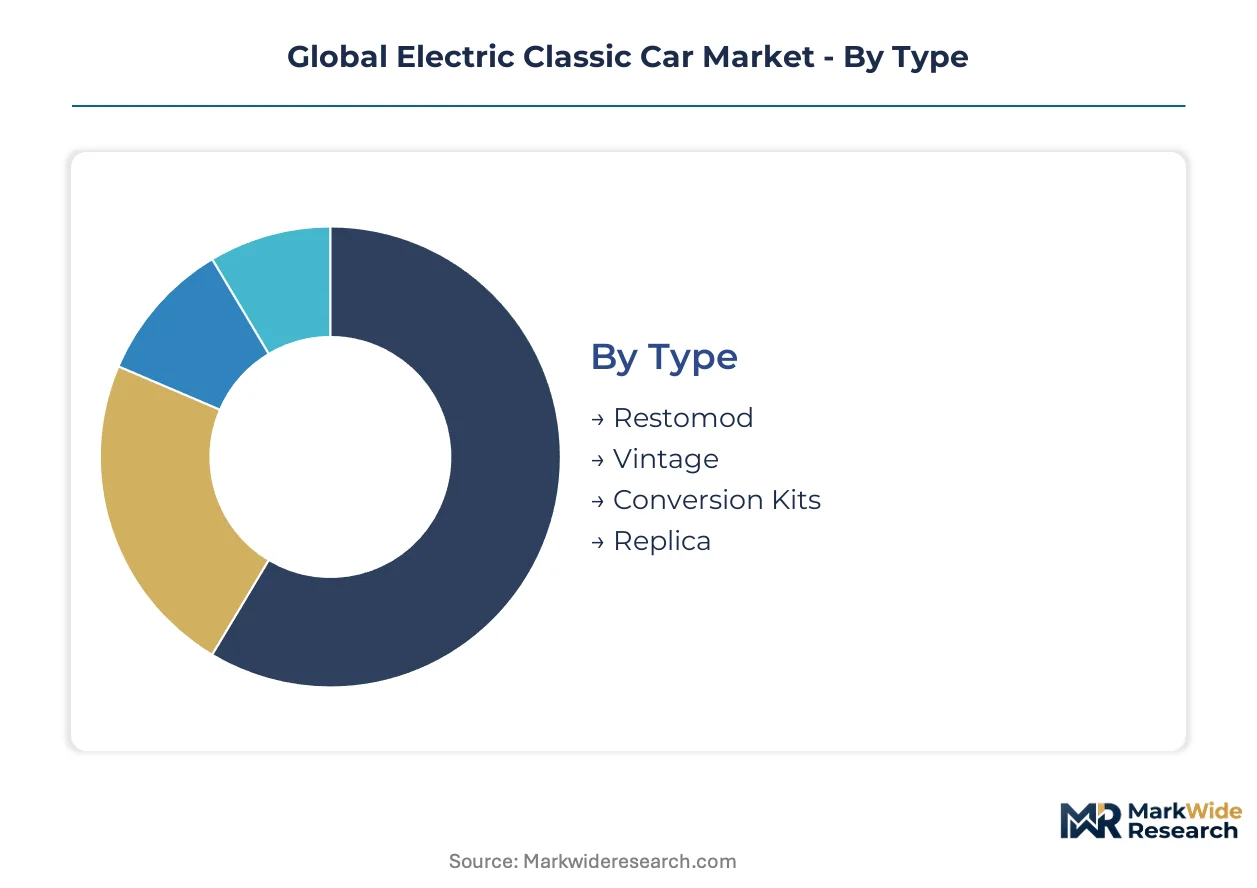
Segmentation in the electric classic car market determines which conversion pathways face streamlined type-approval versus multi-jurisdiction certification burdens. Buyers self-select across technical complexity tiers based on registration requirements and provenance preservation priorities.
Type:
Certification burden varies sharply across conversion approaches, with factory-matching restomods requiring chassis authentication under Germany's KBA and France's ANSM frameworks, while replica builds navigate simplified kit-car pathways.
- Restomod:Original chassis and bodywork receive battery-electric drivetrain integration while preserving factory serial numbers and provenance documentation. United Kingdom specialist converters cluster around Silverstone and the Cotswolds to serve collector demand for authenticated Jaguar E-Type and Rolls-Royce platforms, with EU Green Deal ICE phase-out mandates redirecting restoration investment toward this category.
- Vintage:Factory-original vehicles from pre-emissions eras converted with reversible modifications to maintain historical registration status. United States demand concentrates here under EPA tailpipe exemption frameworks, though potential framework revisions threaten registration pathways for converted classics.
- Conversion Kits:Modular battery-pack and motor assemblies enabling owner-installed electrification without specialist workshop certification.
- Replica:Ground-up coachwork construction with carbon-fiber body panels and modern EV architecture, bypassing heritage authentication requirements entirely.
Restomod sits at the top of the volume ranking, with Replica climbing the fastest.
Power Source:
Cell chemistry selection drives thermal management complexity and REACH compliance costs for European Union restoration facilities importing Asian-manufactured components.
- Lithium-Ion:Graphite-anode and silicon-anode variants dominate current installation bases across 40-100 kWh configurations. German and United Kingdom converters adopt silicon-anode cells for Jaguar E-Type and Mercedes-Benz W113 platforms, compressing pack volume enough to retain spare tire wells without chassis structural reinforcement.
- Solid State:Emerging chemistry enabling 100+ kWh packs within original engine bay footprints, eliminating liquid cooling infrastructure and reducing fire suppression certification burdens.
- Lead-Acid:Legacy chemistry retained for lowest-cost conversions of 1970s mass-market platforms where range requirements remain minimal.
- Others:Sodium-ion and lithium-iron-phosphate alternatives gaining traction for price-sensitive applications.
Lithium-Ion commands current volume leadership, though Solid State is expanding most quickly as energy density maturation enables previously uneconomical project categories.
Market Application:
End-use purpose determines warranty terms, insurance underwriting complexity, and fleet-scale procurement patterns across hospitality and individual ownership models.
- Personal Use:Daily-driver configurations prioritizing range-optimized touring setups with 60-80 kWh packs and regenerative braking integration. United Kingdom and German buyers concentrate here, with modular battery-pack architecture rebalancing choice between touring and track-day setups.
- Collectors:Provenance-focused acquisition with authenticated documentation requirements complicating insurance underwriting for 1960s-1970s chassis with documentation gaps.
- Shows:Exhibition-oriented builds emphasizing aesthetic preservation over performance metrics, often retaining original hood lines through compressed pack volumes.
- Rentals:Hospitality fleet electrification by luxury hotel and vineyard operators commissioning vintage Rolls-Royce and Jaguar platforms for guest experiences.
Personal Use dominates current volume, with Rentals gaining share fastest as hospitality operators scale electrified vintage commitments.
Charging Infrastructure:
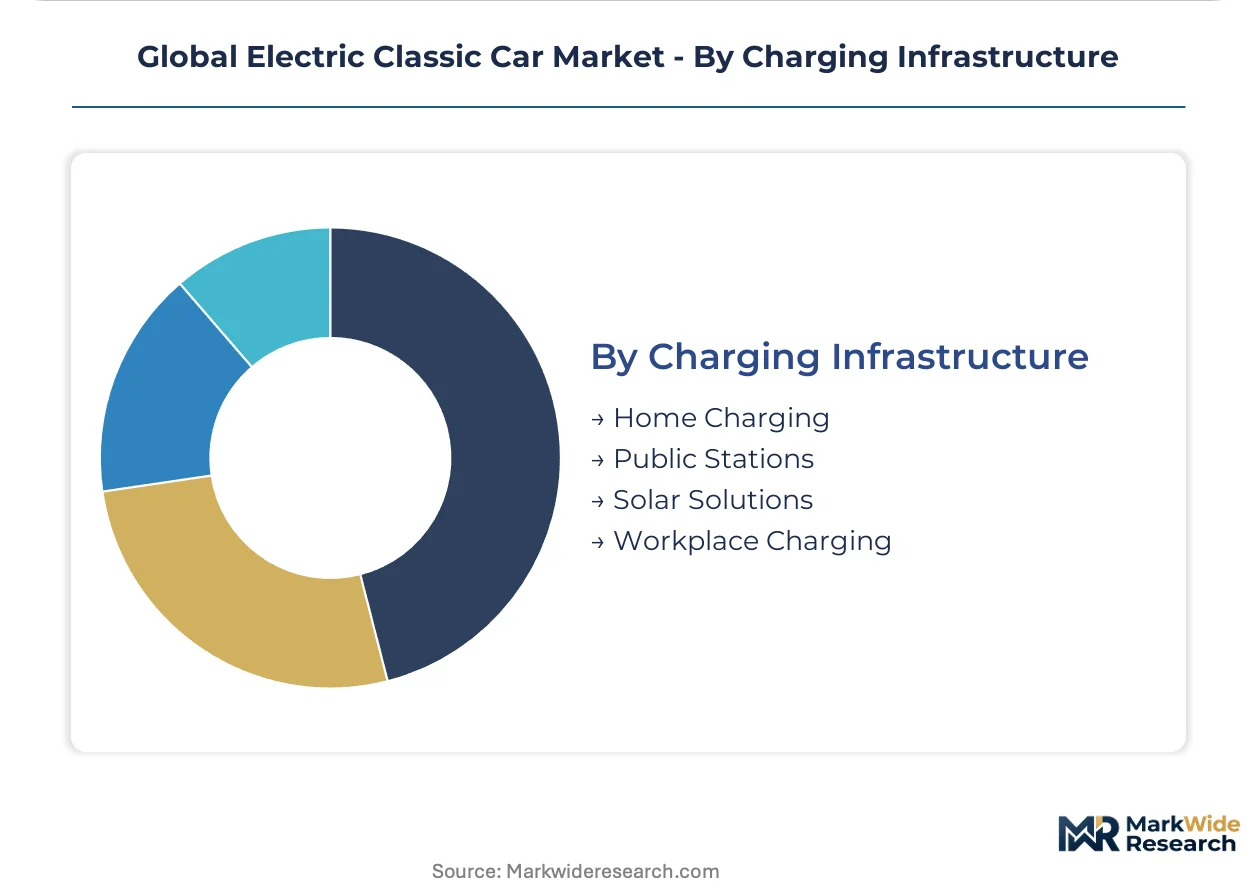
Installation location determines grid interconnection standards and load management certification requirements across residential and commercial electrical codes.
- Home Charging:Level 2 residential installations requiring electrical service upgrades for 7-22 kW sustained draws, with United States NEC compliance and United Kingdom Part P building regulations governing installer certification.
- Public Stations:DC fast-charging compatibility demanding CCS or CHAdeMO inlet integration into vintage body shells, creating bespoke routing challenges through unmodified coachwork.
- Solar Solutions:Off-grid charging arrays for rural vineyard and estate applications reducing operational carbon footprints.
- Workplace Charging:Commercial fleet depot installations serving hospitality and rental operators with centralized maintenance protocols.
Home Charging leads deployment volume, with Solar Solutions climbing the fastest as rural estate operators seek operational carbon neutrality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric classic car conversion industry traces its commercial origins to specialist workshops clustered around British motorsport heritage sites, with Silverstone and the Cotswolds establishing the first scalable restoration-to-electrification pipelines during the mid-2010s.
United Kingdom
Collector demand for authenticated Jaguar E-Type and Rolls-Royce conversions drives workshop capacity expansion across Oxfordshire and Gloucestershire. The EU Green Deal's ICE phase-out mandates redirect continental European restoration investment toward UK-based certified converters. Specialist labor concentration around Silverstone creates geographic supply bottlenecks, with certified high-voltage technicians commanding premium wages.
United States
Vintage Porsche 911 and Volkswagen Beetle electrification dominates restoration shop volume, particularly across California and Arizona collector markets. EPA tailpipe exemption frameworks preserve registration pathways for pre-emissions-era converted classics, though potential framework revisions threaten long-term demand certainty. Zelectric Motors anchors competitive positioning in North American restoration channels.
Germany
Mercedes-Benz W113 and early BMW platforms attract silicon-anode battery configurations that retain original hood lines and spare tire wells. KBA facility licensing requirements impose 12-18 month approval timelines for EV-specific workshop certification, constraining market entry. The F-Gas Regulation mandates R-1234yf-compatible heat pump standards for thermal management systems, elevating supplier compliance costs.
Australia
Sydney and Melbourne vintage car clubs generate underpenetrated demand for electrified Porsche 911 and Mercedes-Benz SL platforms. The country's national automotive safety regulator creates certification barriers for imported conversion platforms, fragmenting type-approval pathways. Specialist converters are establishing beachhead operations in Victoria to serve collector procurement patterns.
France
ANSM framework compliance for high-voltage facility licensing parallels German KBA requirements, extending converter startup timelines. Ferrari and Lamborghini conversion specialists report steepest thermal-management integration costs due to mid-engine layout constraints. The F-Gas Regulation's refrigerant standards force partnerships with HVAC engineering specialists for 1960s ventilation architecture retrofits.
Global Electric Classic Car Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive battery-pack engineering capabilities. Market concentration remains moderate, with premium-tier converters commanding disproportionate value share through authenticated provenance preservation. Two strategic archetypes dominate: heritage-authentication specialists leveraging OEM-grade engineering partnerships, and volume-oriented fabricators optimizing modular kit architectures. Competitive moves center on geographic licensing agreements for type-approval expertise and backward integration into cell chemistry sourcing.
Within the heritage-authentication tier, Lunaz Design and Everrati occupy positions emphasizing factory-matching serial number retention and provenance documentation. Zelectric Motors exemplifies the volume-specialist archetype, anchoring competitive stance on standardized platform electrification for mass-market vintage models. These three entities collectively represent the strategic spectrum from premium collector services to accessible restoration-channel penetration.
| Leading Market Players |
|---|
| Electric Classic Cars |
| Lunaz Design |
| Zelectric Motors |
| EV West |
| Electrogenic |
| Everrati |
| Electric GT |
| Charge Cars |
| Zero Labs Automotive |
| Others |
Supply Flow & Price Mechanics
Certified high-voltage technician concentration around Silverstone and the Cotswolds widens labor-cost spreads between United Kingdom heritage-authentication specialists and volume-oriented kit fabricators, compressing margins on fixed-price restoration contracts while elevating premium-tier pricing power for provenance-preserved builds.
Pricing Analysis
Project-based restoration contracting dominates, with pricing stratifying across provenance-authenticated, performance-optimized, and economy-kit tiers. Price differentiation rests on certification grade under KBA and ANSM frameworks and the extent of chassis structural modification. Cost compression in the economy-kit tier is intensifying because lithium-ion cathode material volatility squeezes converter margins. Hospitality fleet operators show lowest price sensitivity, while individual owner-installers of modular kits exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for remanufactured battery packs and refurbished drivetrain components are emerging as cost-reduction channels, particularly for silicon-anode cell recovery from decommissioned automotive modules. Geographic supply concentration centers on China, South Korea, and Japan for lithium-ion cell production, with Germany and the United Kingdom hosting specialist converter assembly. Raw material dependencies span lithium carbonate, nickel sulfate, and cobalt hydroxide. Single-source vulnerability from concentrated Asian cathode processing elevates supply chain risk. Distribution runs through certified restoration workshops and direct-to-owner kit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-anode chemistry maturation and solid-state cell commercialization are compressing cost curves while expanding premium-tier addressable market, creating margin-expansion headroom for converters with captive engineering capabilities.
For Market Incumbents: Lock in specialist technician pipelines through apprenticeship partnerships with Silverstone-area technical institutes to defend against labor-poaching from emerging Australian entrants. Deepen backward integration into cell chemistry sourcing to offset cathode material price volatility threatening fixed-contract profitability. For New Entrants and Emerging Players: Capture underpenetrated Sydney and Melbourne collector demand for electrified Porsche 911 and Mercedes-Benz SL platforms, where national automotive safety regulator barriers have slowed incumbent establishment. Pursue beachhead licensing under Australia's type-approval framework before specialist labor concentration replicates United Kingdom supply bottlenecks. For Investors and Strategic Acquirers: Luxury hospitality groups with electrified vintage fleet commitments are the most active acquirer in this space, seeking captive conversion capacity for guest-experience differentiation. Target converters with ANSM or KBA facility certification and established OEM-grade engineering partnerships. Monitor solid-state cell pilot production timelines as inflection indicator for technology-displacement risk to lithium-ion dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| OEM-Grade Engineering Partnership | Extends brand credibility into Ferrari and Lamborghini platforms under EU Green Deal mandates. |
| Solid-State Battery Integration | Eliminates liquid cooling infrastructure and reduces fire suppression certification burdens for converters. |
| Geographic Licensing for Type-Approval | Accelerates market entry in Australia where national automotive safety regulator barriers fragment pathways. |
| Carbon-Fiber Coachwork Verticalization | Reduces curb weight and extends effective range for replica-build margin pools. |
| Hospitality Fleet Electrification Partnership | Secures long-term offtake from luxury hotel and vineyard operators commissioning vintage Rolls-Royce fleets. |
Methodological Framework
Coverage spans the United Kingdom, United States, Germany, Australia, and France, with primary inputs from each market cluster. The research combines structured interviews with conversion workshop proprietors, certified high-voltage technicians, hospitality fleet procurement directors, and vintage car club administrators with secondary validation from ECHA REACH compliance filings, KBA facility licensing records, and EPA tailpipe exemption framework documentation. Bottom-up project pipeline enumeration triangulates against top-down restoration investment flow estimates.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the analysis window. Segmentation dimensions modeled include conversion type, cell chemistry, end-use application, and charging infrastructure configuration. CAGRs derive from fitted growth curves against historic conversion commissioning rates and projected hospitality fleet procurement commitments. Solid-state chemistry maturation timelines and F-Gas Regulation compliance cost trajectories inform technology-adoption scenario weighting.
Regulatory framework revision, cathode material price volatility, and specialist labor supply constraints are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about certification pathway stability and cell chemistry cost curves. Practitioners should monitor KBA and ANSM licensing backlog indicators, lithium carbonate futures pricing, and solid-state pilot production announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market