
 Global GPS Antenna for Boats Market | 2026-2036
Global GPS Antenna for Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Global GPS Antenna for Boats Market Analysis
Chinese electronics manufacturing clusters is expanding output of ceramic-patch antenna substrates for marine applications. Garmin Ltd. leverages vertically integrated production of multi-frequency receiver modules to sustain pricing power across premium leisure segments. Raymarine anchors its Atlantic-facing distribution through dedicated marine electronics service networks. Furuno Electric dominates commercial vessel retrofit cycles with specialized phased-array configurations for deep-sea operations.
A GPS antenna for boats is a radio-frequency transducer, typically constructed from ceramic dielectric substrates with copper trace radiating elements, engineered to receive L-band satellite signals at frequencies near 1575 MHz for position-fixing aboard watercraft. Its primary commercial purpose is enabling real-time kinematic navigation, collision avoidance, and automated route optimization for vessels operating beyond visual reference points. Active antenna architectures command the dominant share of marine retrofit revenue due to integrated low-noise amplifier requirements for mast-head installations. GLONASS-compatible receiver modules represent the fastest-expanding technology segment as Russian constellation coverage improves high-latitude reliability for North Sea and Baltic operators. Leisure boats generate the most concentrated margin pool, though cargo ship fleet modernization drives the largest absolute volume requirements.
The U.S. Coast Guard enforces AIS-GPS interoperability mandates under 33 CFR regulations, forcing antenna manufacturers to certify dual-system electromagnetic compatibility. The EU Radio Equipment Directive and CE marking framework restrict market access for non-conforming products across member state marinas and shipyards. ISO 8729 and IEC 60945 standards govern antenna environmental testing protocols for salt-fog resistance and vibration tolerance. Stakeholders must monitor constellation modernization timelines and corresponding receiver firmware upgrade pathways to preserve installed-base competitiveness.
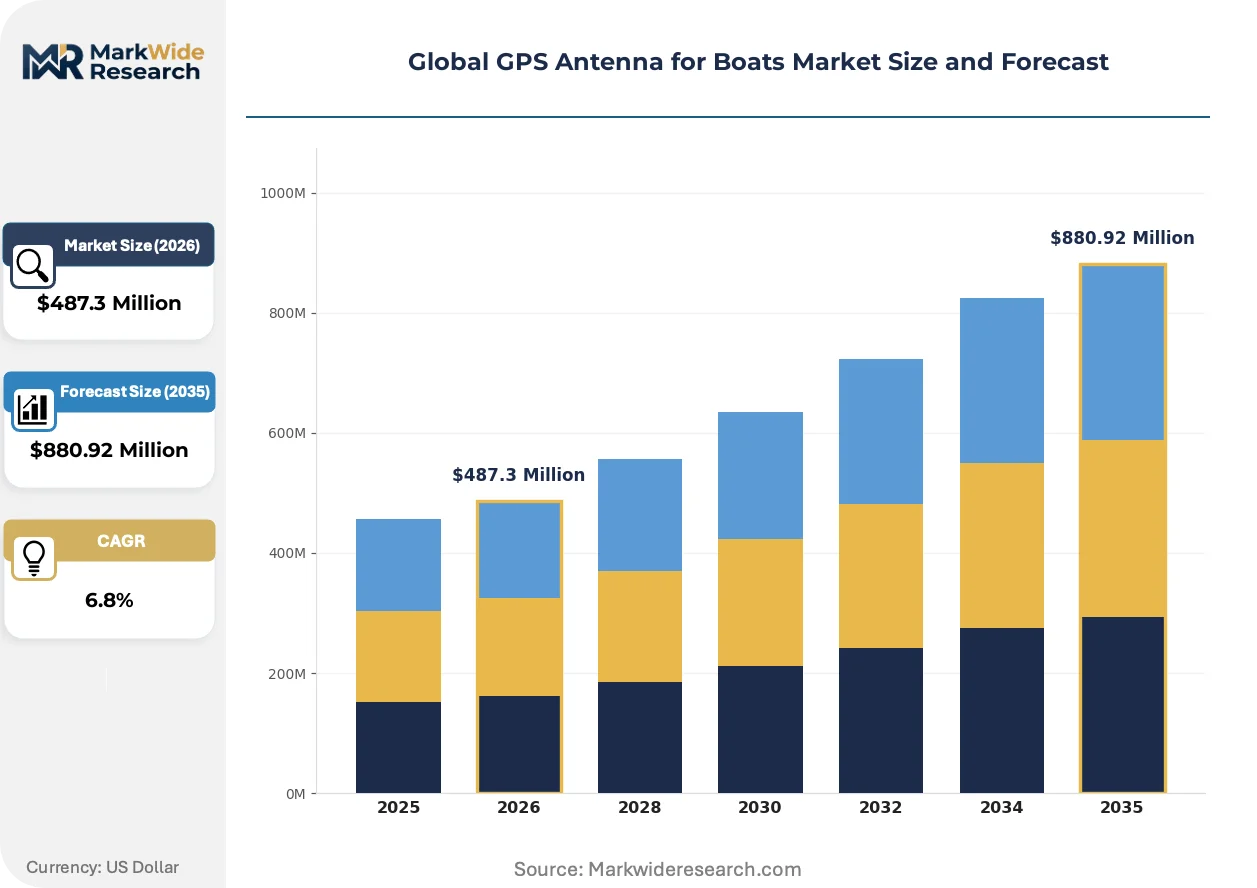
Market Dynamics
Multi-constellation receiver adoption is compressing design cycles for marine antenna manufacturers, forcing rapid firmware adaptation to Galileo and BeiDou signal protocols alongside legacy GPS infrastructure.
Growth Catalysts
- EU Radio Equipment Directive:Tightened electromagnetic compatibility mandates under the EU framework are compelling antenna redesigns that filter interference across L-band frequencies, creating upgrade pull across Mediterranean marinas.
- Ceramic-patch substrate advances:Chinese electronics manufacturing clusters are expanding output of specialized dielectric materials for marine applications, lowering input costs for active antenna architectures.
- Leisure boat retrofit intensity:Coastal manufacturing clusters across Italy and South Korea are channeling OEM specification changes into aftermarket replacement demand for mast-head installations.
Market Restraints
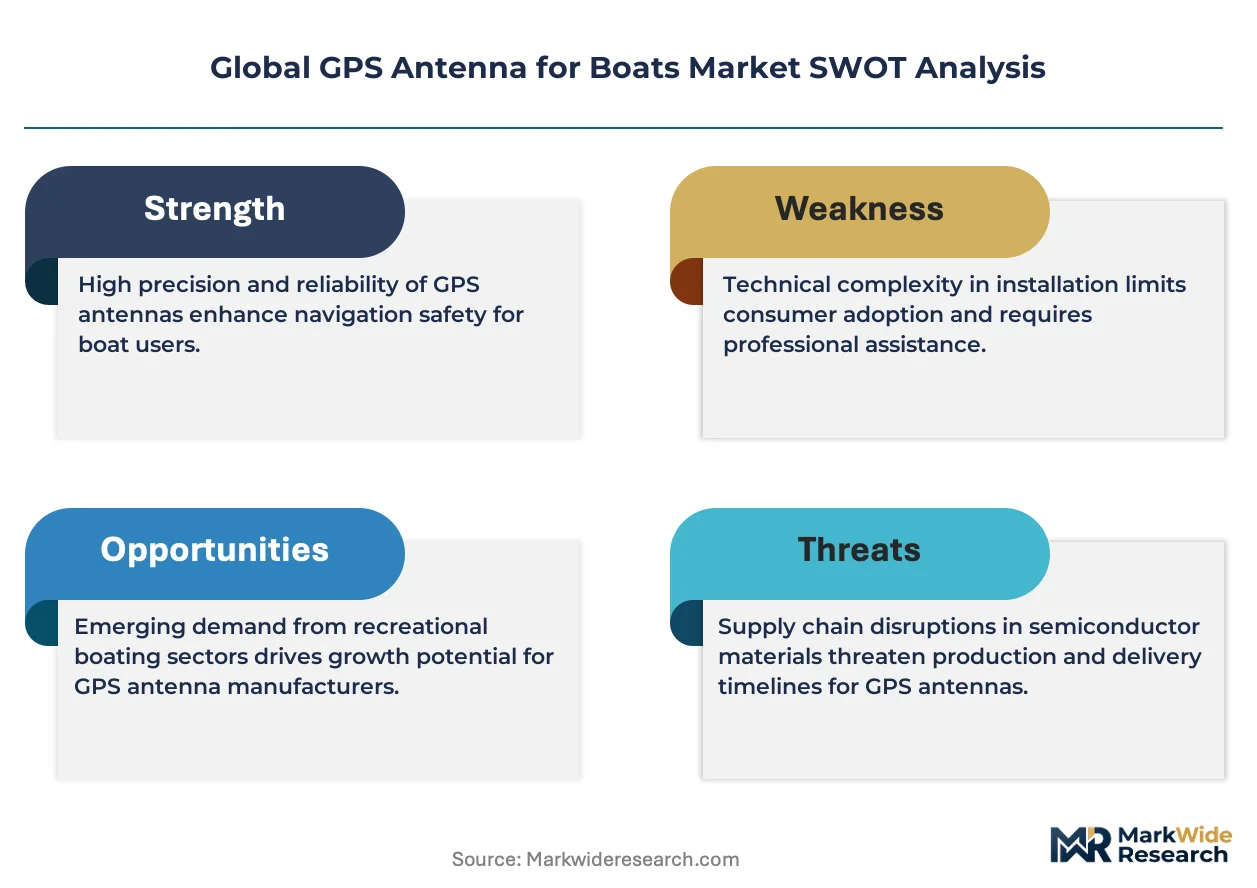
- Copper trace material volatility:Fluctuations in refined copper pricing directly compress margins for radiating element production, particularly affecting small-batch antenna manufacturers without captive metal supply.
- Phased-array supply concentration:Deep-sea commercial vessel configurations depend on a narrow supplier base in Japan and South Korea for specialized beam-steering modules, creating procurement risk during fleet modernization cycles.
- GLONASS receiver firmware fragmentation:Russian constellation signal variations across orbital planes force redundant certification pathways, extending time-to-market for dual-system marine electronics.
Strategic Opportunities
- Baltic Sea high-latitude coverage gaps:North Sea operators are demanding multi-constellation redundancy for ice-class vessels navigating above 60 degrees latitude, opening specification windows for GLONASS-Galileo hybrid receivers.
- AIS-GPS interoperability mandates:U.S. Coast Guard regulations under 33 CFR are forcing integrated antenna-transponder architectures, creating bundled system opportunities for dual-function marine electronics.
- Service network disintermediation:Dedicated marine electronics service networks along Atlantic coastlines are consolidating installation and calibration functions, compressing traditional distributor margins while capturing aftermarket revenue pools.
Industry Challenges
- RF engineer talent scarcity:Low-noise amplifier design for mast-head active antennas requires specialized microwave engineering expertise concentrated in South Korean and Japanese defense-electronics clusters, constraining Western manufacturer hiring pipelines.
- ISO 8729 salt-fog certification timelines:Environmental testing protocols for vibration tolerance and corrosion resistance extend product validation cycles by 8-14 months, delaying revenue recognition for new antenna platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GPS Antenna for Boats Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Antennas, Passive Antennas, Dual-band Antennas, GNSS Antennas Technology: GPS, GLONASS, Galileo, BeiDou End User: Leisure Boats, Commercial Vessels, Fishing Boats, Cargo Ships Installation Type: Through Hull, Deck Mount, Mast Mount, Portable |
| Companies Covered | Garmin Ltd., Raymarine (Teledyne FLIR), Furuno Electric, Navico, Trimble, NovAtel, Hemisphere GNSS, Leica Geosystems, Topcon Positioning Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GPS Antenna for Boats Market Emerging Trajectories
Receiver architecture is fragmenting across frequency bands and constellation sources, compressing the viable product lifecycle for single-GPS designs while opening specification windows for software-defined positioning modules.
Multi-frequency receiver modules are modularizing around interchangeable RF front-end blocks that separate L1/L2/L5 band processing from baseband computation. Leisure boat OEMs in Mediterranean manufacturing clusters are adopting these stackable configurations to reduce inventory SKUs across hull-size variants. The structural consequence is that antenna-transceiver pairing is modularizing, enabling third-party calibration services to capture value previously retained by integrated system vendors.
CE marking enforcement under the EU Radio Equipment Directive is tightening electromagnetic compatibility verification for marina-installed equipment, forcing antenna manufacturers to pre-certify against interference scenarios from onboard radar and VHF systems. Commercial vessel operators in North Sea routes are absorbing these compliance costs through extended procurement timelines. The directive is compressing market access for non-conforming products, privileging established suppliers with dedicated EU notified body relationships.
Leisure boat buyers are unbundling after-sales calibration from initial hardware purchase, treating antenna alignment and receiver firmware updates as separate service line items. Marine electronics service networks along the U.S. Atlantic seaboard are capturing this disaggregated spend through annual maintenance contracts. This behavioral shift is most visible in Florida and Chesapeake Bay boating corridors, where seasonal commissioning rituals now exclude factory-authorized installation mandates.
Global GPS Antenna for Boats Market Segmentation
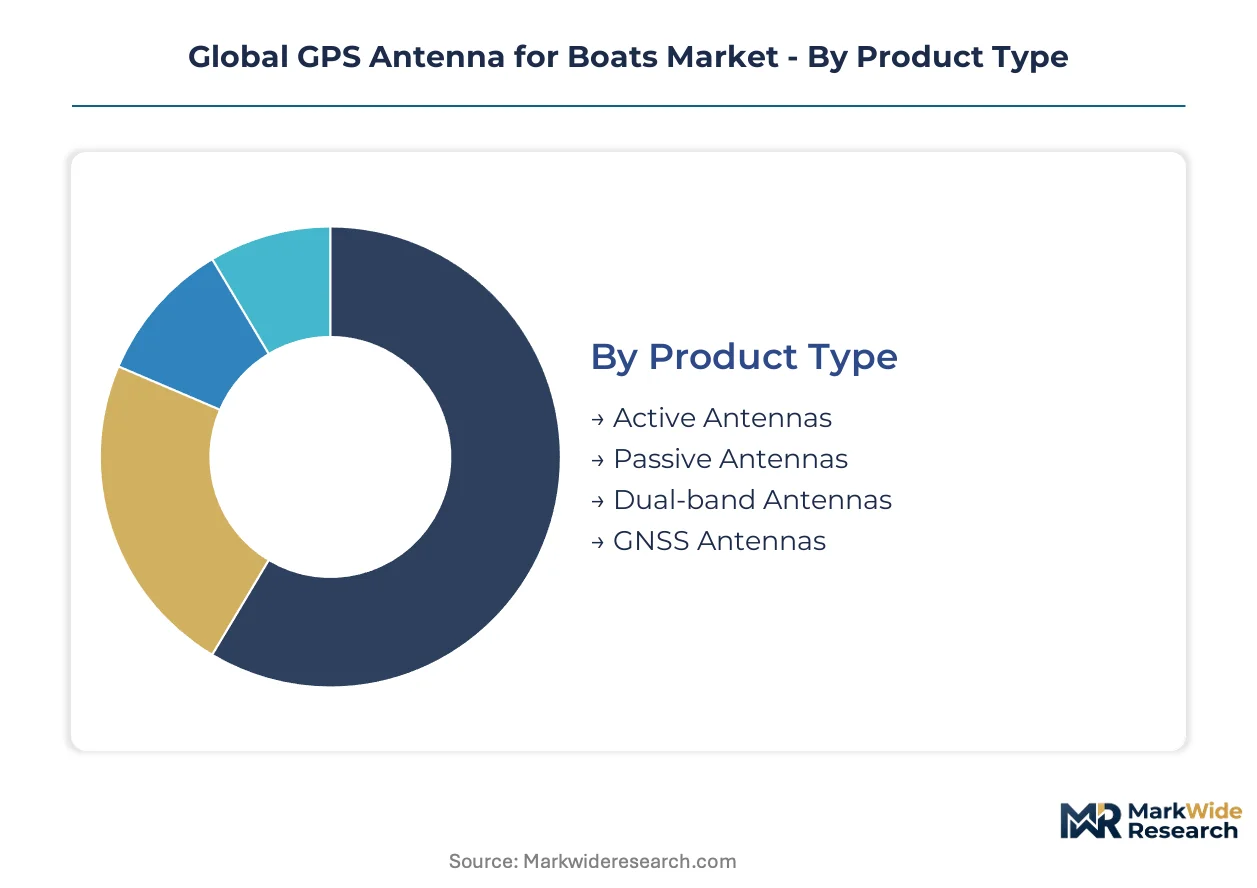
Marine GPS antenna procurement cycles diverge sharply across vessel categories and installation environments. Upgrade intensity concentrates where regulatory mandates intersect with leisure fleet renewal and commercial fleet modernization timelines.
Product Type:
Replacement cycles for marine antenna hardware accelerate where integrated amplifier electronics degrade in salt-air environments. Mast-head installations drive the shortest hardware refresh intervals across all product categories.
- Active Antennas:These units incorporate ceramic-patch substrates with integrated low-noise amplifiers to boost weak satellite signals before cable transmission. Demand clusters in Mediterranean marinas where leisure boat OEMs specify pre-amplified architectures for mast-head placement. Salt-fog degradation of amplifier electronics compresses replacement cycles to 4-6 years in coastal installations.
- Passive Antennas:Simple radiating elements without onboard amplification suit short cable runs and budget retrofit scenarios. Italian and South Korean coastal manufacturing clusters channel specification changes into passive antenna demand for smaller hull sizes where receiver proximity permits unamplified signal paths.
- Dual-band Antennas:L1/L2 frequency reception enables ionospheric correction for sub-meter accuracy in commercial fishing operations.
- GNSS Antennas:Multi-constellation reception architectures accommodate GPS, GLONASS, Galileo, and BeiDou signal protocols in unified hardware platforms.
Active Antennas sits at the top of the volume ranking, with GNSS Antennas climbing the fastest.
Technology:
Constellation diversification is fragmenting receiver firmware requirements across marine electronics supply chains. Firmware upgrade pathways now determine hardware obsolescence timelines more than physical antenna degradation.
- GPS:Legacy L1 C/A-code reception at 1575.42 MHz remains the baseline specification for entry-level leisure installations. U.S. Atlantic seaboard service networks still handle substantial GPS-only replacement volume from aging fleet bases in Florida and Chesapeake Bay corridors.
- GLONASS:Russian constellation compatibility improves high-latitude reliability for North Sea and Baltic operators navigating above 60 degrees latitude. North Sea ice-class vessel operators absorb redundant certification costs for orbital plane signal variations that complicate dual-system marine electronics deployment.
- Galileo:EU constellation signal authentication reduces spoofing vulnerability for commercial cargo routes.
- BeiDou:Chinese constellation coverage extends positioning service to Asia-Pacific commercial fishing grounds.
GPS retains the largest installed base, though GLONASS is expanding most quickly in high-latitude commercial segments.
End User:
Margin extraction potential varies inversely with vessel size across marine antenna end-use categories. Leisure fleet density in coastal manufacturing clusters generates concentrated aftermarket service revenue.
- Leisure Boats:Recreational vessels under 24 meters dominate unit volume and margin concentration for marine electronics vendors. Mediterranean basin manufacturers accelerate multi-constellation receiver adoption, channeling OEM specification changes into aftermarket replacement demand through dedicated marine electronics service networks.
- Commercial Vessels:Deep-sea operations require phased-array configurations with specialized beam-steering modules. Japanese and South Korean suppliers concentrate production of these high-value architectures, creating procurement risk during fleet modernization cycles.
- Fishing Boats:Mixed-use vessels demand ruggedized antenna housings for trawl deck exposure.
- Cargo Ships:Fleet-scale retrofit programs drive absolute dollar volume despite lower per-unit margins.
Cargo Ships command the largest absolute revenue pool, with Leisure Boats delivering the steepest margin trajectory.
Installation Type:
Physical mounting location determines antenna environmental exposure severity and corresponding hardware specification requirements. Salt-fog resistance and vibration tolerance standards vary by installation geometry.
- Mast Mount:Elevated placement maximizes satellite visibility but exposes hardware to maximum wind loading and salt spray. U.S. Coast Guard AIS-GPS interoperability mandates under 33 CFR force integrated antenna-transponder architectures for mast-head installations, creating bundled system opportunities.
- Through Hull:Subsurface or flush-mounted configurations minimize aerodynamic drag for racing sailboats. ISO 8729 salt-fog certification timelines extend 8-14 months for through-hull variants due to complex sealing validation requirements.
- Deck Mount:Surface-mounted pods balance satellite visibility with installation accessibility for mid-size cruisers.
- Portable:Magnetic or suction-cup temporary installations serve charter fleets and emergency backup scenarios.
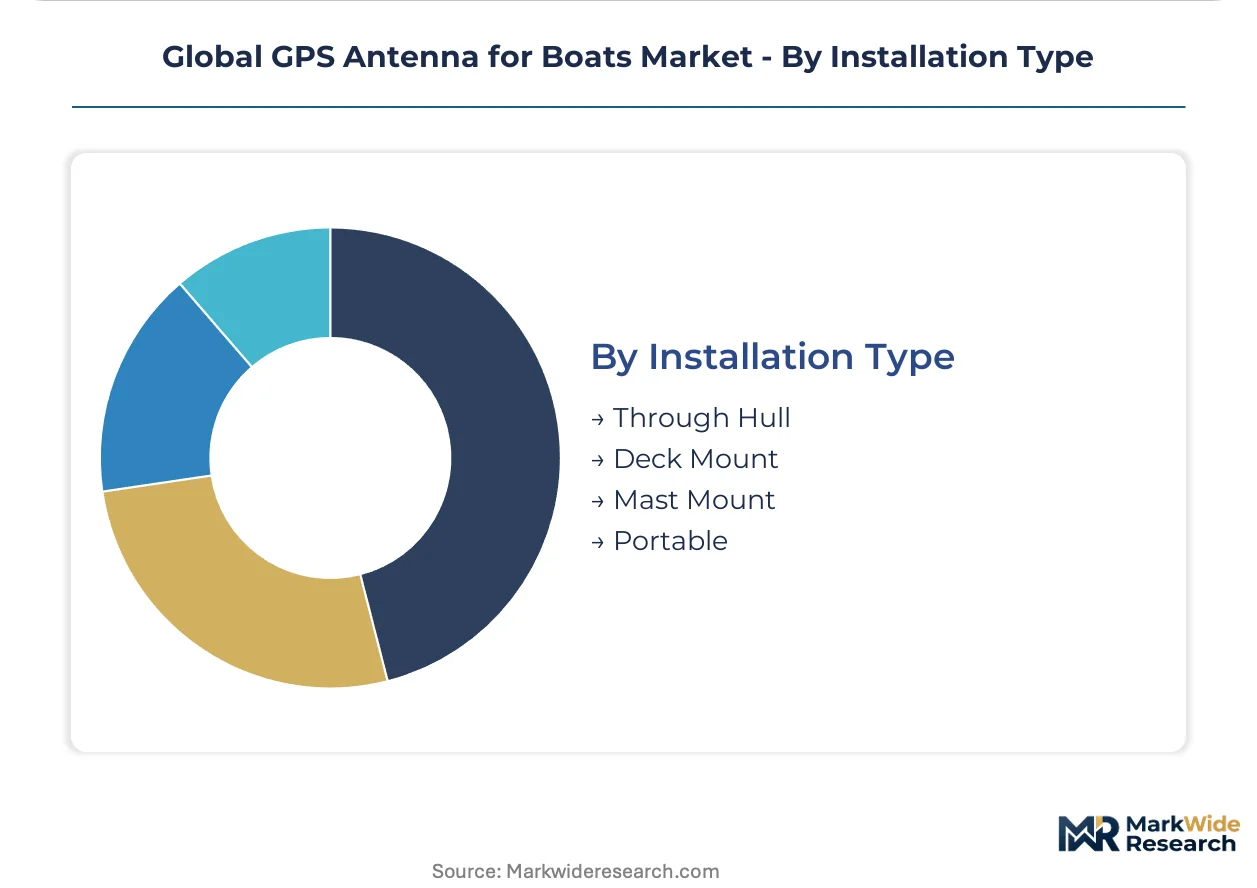
Mast Mount captures the highest unit volume, with Through Hull gaining share fastest in performance sailing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting marine electronics production toward jurisdictions with streamlined electromagnetic compatibility certification pathways, as EU Radio Equipment Directive compliance costs widen cost-of-compliance gaps between manufacturing clusters.
United States
U.S. Coast Guard AIS-GPS interoperability mandates under 33 CFR regulations are forcing integrated antenna-transponder architectures across Atlantic seaboard marinas. Florida and Chesapeake Bay boating corridors concentrate aftermarket service revenue where seasonal commissioning rituals now exclude factory-authorized installation mandates. Garmin Ltd. leverages vertically integrated production from domestic facilities to sustain pricing power across premium leisure segments.
Italy
Mediterranean basin leisure boat manufacturers are accelerating multi-constellation receiver adoption, channeling OEM specification changes into aftermarket replacement demand. CE marking enforcement under the EU Radio Equipment Directive restricts market access for non-conforming products across member state marinas. Coastal manufacturing clusters in Lombardy and Veneto are absorbing tightened electromagnetic compatibility mandates through dedicated marine electronics service networks.
South Korea
Deep-sea commercial vessel configurations depend on specialized beam-steering modules produced by defense-electronics clusters in Busan-Ulsan and Daegu-Gyeongbuk regions. RF engineer talent scarcity for low-noise amplifier design concentrates hiring pipelines within these metropolitan areas. Domestic suppliers dominate phased-array supply for fleet modernization cycles across Asia-Pacific commercial fishing grounds.
Japan
Furuno Electric anchors commercial vessel retrofit cycles with specialized phased-array configurations for deep-sea operations originating from Nagoya and Osaka industrial zones. METI standards alignment with IEC 60945 environmental testing protocols governs salt-fog resistance and vibration tolerance certification. Japanese suppliers concentrate production of high-value beam-steering architectures, creating procurement risk during global fleet modernization cycles.
China
Chinese electronics manufacturing clusters in the Yangtze River Delta and Pearl River Delta are expanding output of ceramic-patch antenna substrates for marine applications, lowering input costs for active antenna architectures. MIIT regulations on radio equipment certification create parallel pathways to EU CE marking for export-oriented producers. Domestic constellation modernization through BeiDou signal authentication is reducing spoofing vulnerability for Asia-Pacific commercial routes.
Global GPS Antenna for Boats Market Vendor Landscape
Japanese and South Korean producers anchor one tier for specialized phased-array configurations; U.S. and European specialists hold premium positioning for integrated receiver modules. The vendor base concentrates around three strategic archetypes: vertically integrated leisure electronics vendors, defense-electronics derived commercial specialists, and modular RF component suppliers. Competitive moves center on backward integration into ceramic substrate supply and geographic expansion through dedicated marine electronics service networks.
Within the vertically integrated tier, Garmin Ltd. and Raymarine exemplify positioning where captive production of multi-frequency receiver modules sustains pricing power. Furuno Electric occupies a distinct position among defense-electronics derived specialists, representing the archetype of commercial vessel retrofit dominance through phased-array expertise. These three companies collectively illustrate how technology lineage and manufacturing geography determine competitive segmentation across leisure and commercial end-use categories.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Raymarine (Teledyne FLIR) |
| Furuno Electric |
| Navico |
| Trimble |
| NovAtel |
| Hemisphere GNSS |
| Leica Geosystems |
| Topcon Positioning Systems |
| Others |
Supply Flow & Price Mechanics
ISO 8729 salt-fog certification timelines gate qualified supply for mast-head active antennas, restricting premium-tier pricing access to manufacturers with dedicated environmental testing facilities in South Korea and Japan while compressing margins for uncertified competitors.
Pricing Analysis
Distributor margins for marine electronics service networks along the U.S. Atlantic seaboard absorb 18-25 point markups before reaching leisure boat end-users. Three-tier pricing structure across premium, standard, and economy levels separates Furuno Electric's phased-array configurations from Garmin's integrated receiver modules and unbranded ceramic-patch alternatives. Cost compression in the passive antenna tier intensifies because Chinese electronics manufacturing clusters expanded ceramic substrate output. Charter fleet operators in Florida and Chesapeake Bay corridors exhibit the highest price sensitivity, while North Sea ice-class vessel operators absorb premium pricing for GLONASS-Galileo hybrid redundancy.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Mediterranean leisure boat manufacturers in Lombardy and Veneto, while dedicated marine electronics service networks manage aftermarket replacement cycles. Supply concentrates in China for ceramic-patch substrates, South Korea for low-noise amplifier modules, and Japan for phased-array beam-steering architectures. Raw material dependencies draw from refined copper for radiating elements, specialized dielectric ceramics, and L-band RF front-end semiconductors. Single-source vulnerability in Japanese beam-steering module production creates procurement risk during commercial fleet modernization cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from EU Radio Equipment Directive compliance costs, where manufacturers with streamlined CE marking pathways in Italy capture margin expansion unavailable to non-conforming suppliers.
For Market Incumbents: To counter RF engineer talent scarcity in Western markets, secure hiring pipelines through partnerships with South Korean defense-electronics clusters and invest in automated calibration services that capture disaggregated aftermarket spend from unbundled installation rituals. For New Entrants and Emerging Players: U.S. Coast Guard AIS-GPS interoperability mandates under 33 CFR open a window for integrated antenna-transponder architectures targeting Atlantic seaboard marinas with bundled system offerings. White-space exists in third-party calibration services for seasonal commissioning rituals, particularly in Florida and Chesapeake Bay corridors where factory-authorized installation mandates have dissolved. For Investors and Strategic Acquirers: Roll-up economics work for modular RF component suppliers because antenna-transceiver pairing modularization enables third-party calibration services to capture value previously retained by integrated system vendors. Target acquisition archetypes include ceramic substrate manufacturers with marine-specific dielectric formulations. The signal to monitor is constellation modernization timelines and corresponding receiver firmware obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Supply | Captive dielectric material production lowers input costs for active antenna architectures against Chinese cluster competition. |
| Geographic Expansion Through Service Networks | Dedicated marine electronics service networks along Atlantic coastlines capture disaggregated calibration and maintenance revenue pools. |
| Multi-Constellation Firmware Certification Investment | Pre-certification against Galileo and BeiDou signal protocols accelerates time-to-market for dual-system marine electronics. |
| Joint Venture for Phased-Array Module Production | Partnerships with South Korean defense-electronics clusters mitigate single-source procurement risk for beam-steering architectures. |
| Platform Integration of AIS-GPS Architectures | Integrated antenna-transponder systems satisfy U.S. Coast Guard 33 CFR mandates while bundling hardware and service revenue. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with marine electronics OEM procurement directors, RF engineering leads at antenna manufacturers, marina service network operators, and leisure boat fleet managers with secondary validation from U.S. Coast Guard regulatory filings, EU Radio Equipment Directive notified body documentation, customs records for ceramic substrate trade flows, and SEC disclosures from vertically integrated leisure electronics vendors. Bottom-up antenna shipment estimates triangulated against top-down vessel fleet counts across Mediterranean, North Sea, and Asia-Pacific operating regions.
Historical reference periods anchored volume and value trajectories across the modeling period, with segmentation dimensions covering product architecture (active/passive/phased-array), constellation compatibility (GPS/GLONASS/Galileo/BeiDou), vessel category (leisure/commercial/fishing/cargo), and installation geometry (mast/through-hull/deck/portable). CAGRs derived from curve-fitting techniques applied to OEM specification change timelines and fleet modernization cycles, incorporating constellation modernization schedules and regulatory mandate enforcement calendars as exogenous drivers.
Revisions become necessary when electromagnetic compatibility certification pathways shift, copper trace material volatility exceeds historical bands, or constellation signal authentication protocols disrupt receiver firmware upgrade economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Plate Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Marine Lubrication System Market