
 United States Concrete Superplasticizer Market | 2026-2036
United States Concrete Superplasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Concrete Superplasticizer Market Intelligence
The direct sales channel is narrowing as national distributors consolidate purchasing power across multi-state ready-mix networks. BASF Construction Chemicals leverages its Gulf Coast manufacturing footprint to sustain bulk supply contracts with top ten concrete producers. Sika Corporation competes through specialized technical service teams embedded in metropolitan batching operations. MBCC Group anchors its position with backward integration into polycarboxylate polymer production.
Concrete superplasticizers are high-range water-reducing admixtures, typically formulated with polycarboxylate ether backbones or sulfonated naphthalene condensates, that enable flowable concrete at water-cement ratios below 0.30 without segregation. Their primary commercial purpose is to achieve specified compressive strength targets while reducing cement content and placement labor. Polycarboxylate formulations command the dominant margin pool due to superior slump retention and compatibility with supplementary cementitious materials. Infrastructure end users represent the fastest-growing demand segment as federal transportation spending elevates performance-grade specifications. Chemical modification technology leads in R&D intensity as producers engineer polymer architectures for extended workability windows.
The EPA regulates volatile organic compound emissions from admixture manufacturing facilities under the National Emission Standards for Hazardous Air Pollutants, while state DOT agencies enforce AASHTO specifications for chloride permeability in bridge deck applications. OSHA's permissible exposure limits for naphthalene vapors in batching plants shape workplace handling protocols and product substitution patterns. Stakeholders must monitor evolving state-level low-carbon concrete mandates that will redefine acceptable embodied carbon thresholds for admixture portfolios.
Market Dynamics
Polycarboxylate ether chemistry is displacing legacy naphthalene formulations as state DOTs tighten chloride permeability specifications for infrastructure concrete. This molecular transition concentrates procurement leverage among producers with captive polymer synthesis capabilities.
Growth Catalysts
- Federal Infrastructure Spending:The Infrastructure Investment and Jobs Act channels funding toward bridge rehabilitation and highway expansion, elevating demand for high-performance admixtures in federally backed projects across the Southeast and Gulf Coast corridors.
- Low-Carbon Concrete Mandates:State-level embodied carbon thresholds in California, New York, and Washington are accelerating specification of superplasticizers that enable cement reduction while maintaining strength targets.
- Polycarboxylate Ether Advances:Extended slump retention polymers allow longer haul distances and complex placements, expanding addressable project types for ready-mix producers serving metropolitan batching operations.
Market Restraints
- Olefins Feedstock Volatility:Polyethylene glycol and methacrylic acid price swings compress formulation margins, particularly for non-integrated admixture blenders lacking long-term supply contracts.
- Gulf Coast Production Concentration:Bulk manufacturing clusters along the Texas and Louisiana chemical corridor create hurricane-related supply disruption exposure and logistics bottlenecks during peak construction seasons.
- OSHA Naphthalene Exposure Limits:Permissible exposure thresholds in batching plants accelerate product substitution costs for producers maintaining legacy sulfonated naphthalene condensate inventories.
Strategic Opportunities
- Mountain West Infrastructure Gap:Underpenetrated markets in Colorado, Utah, and Arizona present expansion targets as interstate highway and data center construction accelerates amid population migration patterns.
- Carbon Capture Integration:Emerging CO2 mineralization technologies in concrete curing create adjacency opportunities for admixture producers positioning chemistry as complementary to carbon-negative cement systems.
- Direct-to-Contractor Digital Platforms:E-procurement channels bypassing traditional distributor networks enable technical service monetization and specification capture among mid-sized infrastructure contractors.
Industry Challenges
- Polymer Architecture Specialization:Shortage of formulation chemists with expertise in graft density optimization and side-chain engineering limits R&D throughput for customized regional performance grades.
- AASHTO Certification Timelines:Extended approval cycles for new admixture chemistries under state DOT qualification protocols delay commercialization of next-generation slump retention technologies.
- Legacy Batching System Integration:Automated dosing equipment in older ready-mix plants requires retrofitting to handle temperature-sensitive polycarboxylate rheology, creating adoption friction among smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Concrete Superplasticizer Market |
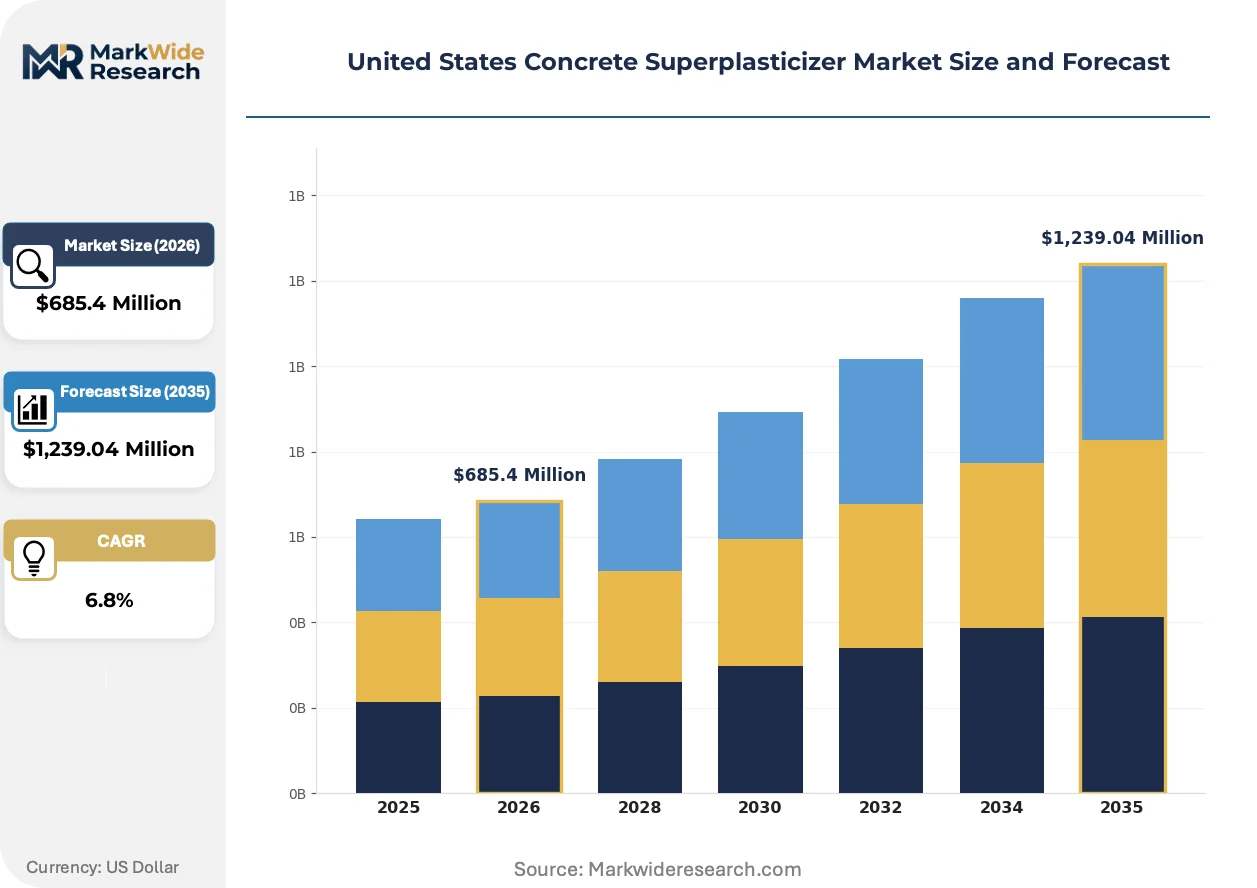
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylate, Sulfonated Naphthalene, Lignosulfonate, Others Technology: Chemical Modification, Physical Blending, Additive Manufacturing, Others End User: Residential Construction, Commercial Construction, Infrastructure, Industrial Applications Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | CEMEX, Mapei S.P.A., BASF Construction Chemicals, MBCC Group, Arkema Group, Sika Corporation, Altus Material, Euclid Chemical, GCP Applied Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Concrete Superplasticizer Market Strategic Shifts & Innovations
Admixture chemistry is converging with digital concrete monitoring systems, creating specification environments where real-time slump data drives purchasing decisions rather than static mix designs.
Hybrid polycarboxylate-lignosulfonate copolymers are rendering obsolete single-backbone formulations in precast applications. Infrastructure contractors in Texas and Florida specify these molecular architectures for chloride-resistant bridge decks. The technology compresses competitive differentiation around slump retention duration rather than initial water reduction alone.
EPA scrutiny of formaldehyde emissions from naphthalene-based production processes accelerates plant retrofit requirements under National Emission Standards for Hazardous Air Pollutants. Admixture manufacturers face capital allocation decisions between emission control installation and full chemistry transitions. Southeast and Gulf Coast facilities bear the highest compliance burden due to concentration of legacy production assets.
Performance-based contracting is displacing volume-centric purchasing among top-ten ready-mix networks. National distributors consolidate specification influence by embedding technical service teams within metropolitan batching operations. The shift concentrates most visibly in Georgia and North Carolina megaproject corridors where extended workability windows command premium positioning.
United States Concrete Superplasticizer Market Segmentation
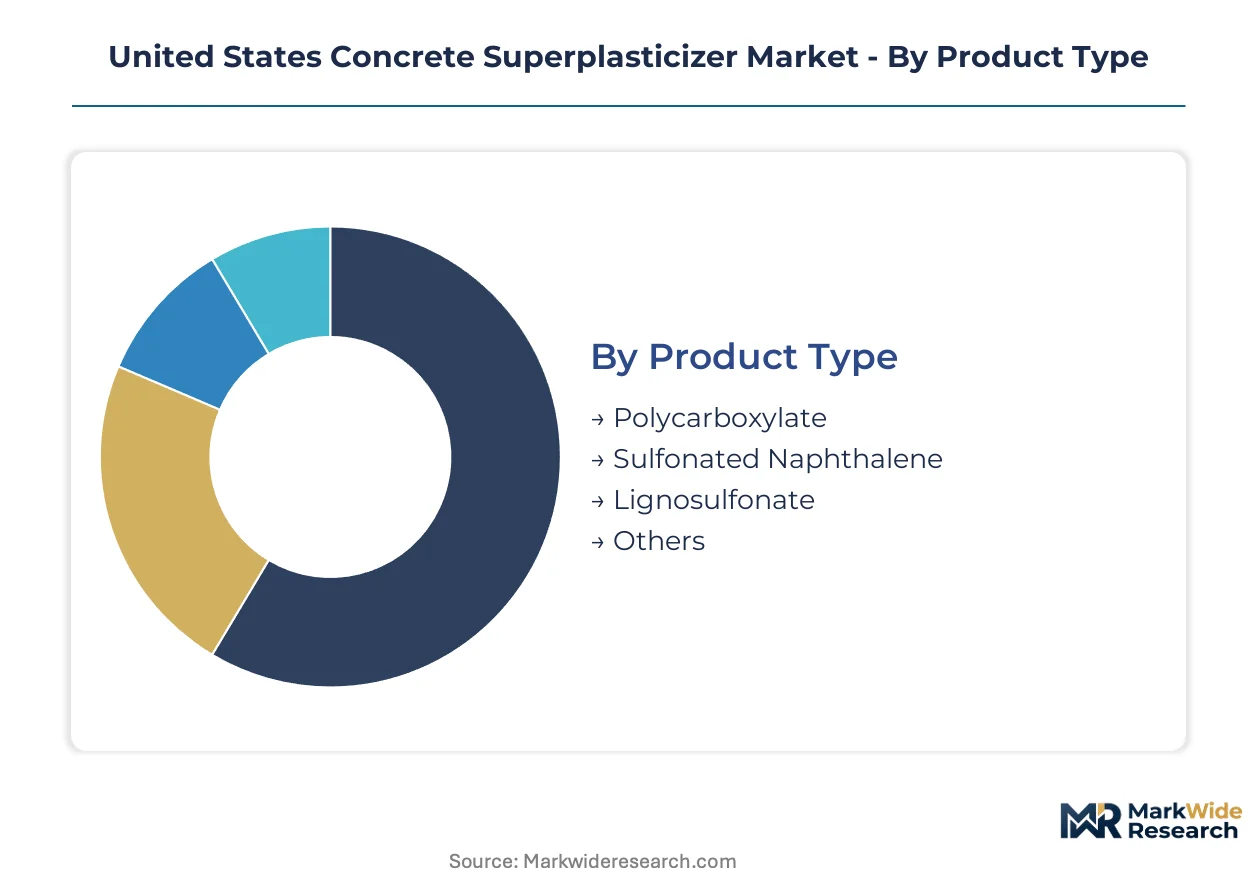
Concrete superplasticizer procurement patterns diverge sharply across formulation chemistry, application intensity, and channel structure. Specification engineers in Texas and Florida DOT offices drive distinct purchasing behaviors compared to residential contractors in metropolitan batching operations.
Product Type:
After-sales technical service intensity peaks with high-performance formulations requiring slump retention calibration and compatibility testing with local cement sources.
- Polycarboxylate:Polycarboxylate ether backbones deliver extended workability windows and superior compatibility with supplementary cementitious materials. Infrastructure contractors in Georgia and North Carolina megaproject corridors specify these formulations for chloride-resistant bridge decks where AASHTO permeability thresholds apply. Technical service teams embed directly in metropolitan batching operations to optimize dosing protocols.
- Sulfonated Naphthalene:Sulfonated naphthalene condensates offer lower unit costs but face accelerating substitution pressure from EPA formaldehyde emission scrutiny under National Emission Standards for Hazardous Air Pollutants. Legacy production assets concentrate along the Gulf Coast chemical corridor, creating compliance retrofit burdens for manufacturers maintaining these inventories.
- Lignosulfonate:Lignosulfonate-based formulations serve cost-sensitive precast applications with moderate water reduction requirements.
- Others:Emerging hybrid chemistries and specialty backbones address niche performance specifications in industrial concrete systems.
By volume, Polycarboxylate leads. By growth pace, Polycarboxylate is ahead.
Technology:
Cost tier stratification separates integrated polymer producers from formulation blenders lacking captive synthesis capabilities.
- Chemical Modification:Chemical modification technology dominates R&D intensity as producers engineer graft density and side-chain architectures for customized regional performance grades. MBCC Group anchors competitive position through backward integration into polycarboxylate polymer production, controlling molecular design from monomer through finished admixture.
- Physical Blending:Physical blending operations concentrate among regional admixture suppliers serving single-state ready-mix networks with standardized performance grades. Margin compression from olefins feedstock volatility hits these operators hardest due to absence of long-term supply contracts.
- Additive Manufacturing:Additive manufacturing approaches enable on-site polymer synthesis for specialized infrastructure applications requiring rapid customization.
- Others:Alternative processing technologies include enzymatic modification and bio-based backbone integration for low-carbon concrete mandates.
Chemical Modification captures the premium tier. Physical Blending serves volume markets.
End User:
Application intensity varies from high-specification infrastructure workability windows to residential placement efficiency.
- Infrastructure:Infrastructure end users represent the fastest-expanding demand segment as federal transportation spending elevates performance-grade specifications. Texas and Florida DOT tightening of chloride permeability requirements for bridge decks drives specification of polycarboxylate formulations with extended slump retention for complex placements.
- Commercial Construction:Commercial construction demands balance workability duration against cost discipline in high-rise and large-format slab applications. Georgia and North Carolina metropolitan batching operations embed technical service teams to optimize mix designs for accelerated construction schedules.
- Residential Construction:Residential construction prioritizes placement labor reduction over extended workability in single-family and low-rise multifamily applications.
- Industrial Applications:Industrial applications encompass precast manufacturing, mining infrastructure, and specialized cementitious systems requiring chemical resistance.
Infrastructure leads specification intensity. Commercial Construction dominates unit volume.
Distribution Channel:
Customer type fragmentation separates national ready-mix networks from mid-sized infrastructure contractors with distinct procurement workflows.
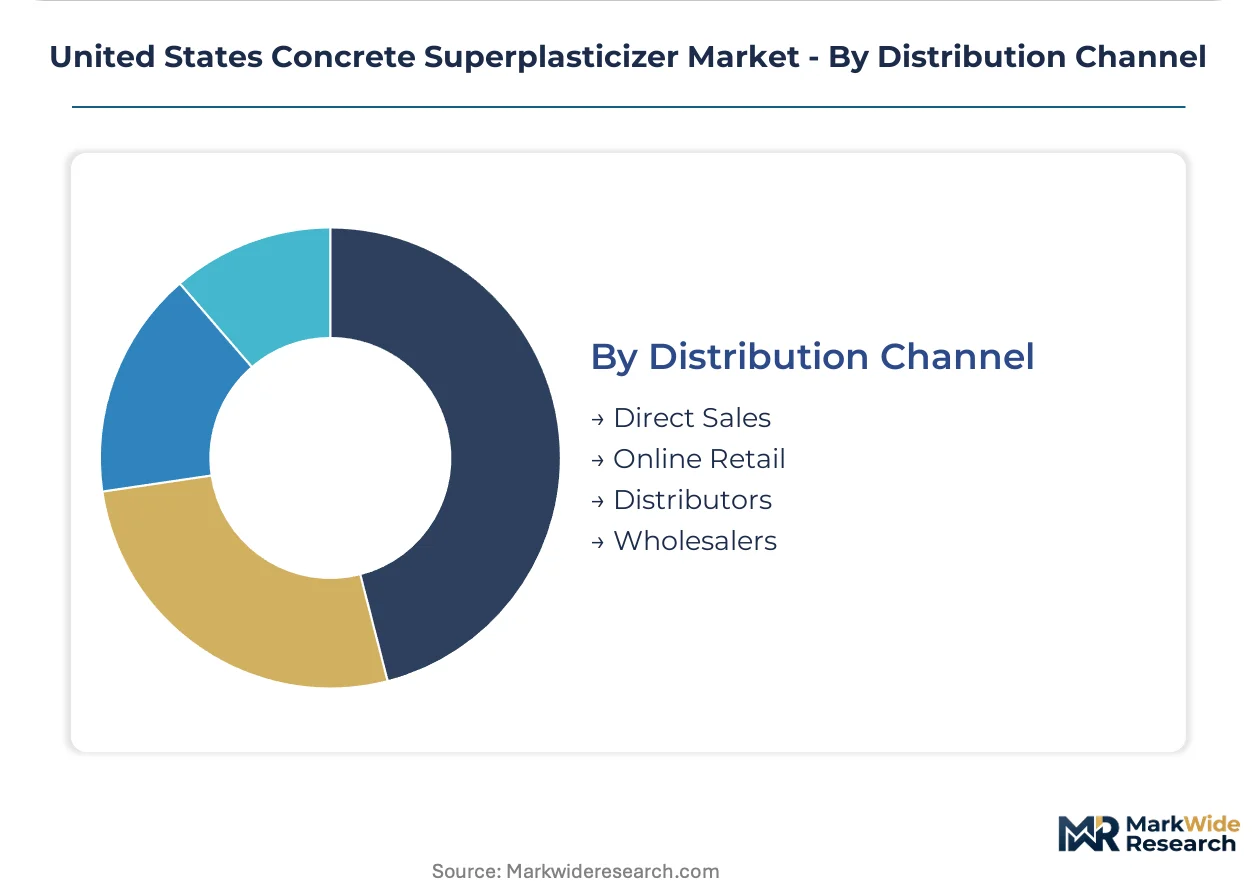
- Distributors:National distributors consolidate purchasing power across multi-state ready-mix networks and embed technical service teams within metropolitan batching operations. BASF Construction Chemicals leverages Gulf Coast manufacturing footprint to sustain bulk supply contracts through these channels.
- Direct Sales:Direct sales channels narrow as specification influence concentrates among consolidated distributor networks with technical service capabilities.
- Online Retail:E-procurement platforms emerge as adjacency opportunities for technical service monetization among mid-sized infrastructure contractors bypassing traditional networks.
- Wholesalers:Wholesalers serve smaller regional ready-mix producers with standardized product grades and limited technical support.
Distributors command specification influence. Direct Sales retains strategic accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission standards under the National Emission Standards for Hazardous Air Pollutants anchor compliance strategy across U.S. manufacturing corridors. State DOT specifications for chloride-resistant infrastructure reshape procurement geography toward high-performance admixture production clusters.
Southeast Corridor
Georgia and North Carolina megaproject activity drives specification of extended workability formulations for complex bridge placements. State DOT agencies enforce AASHTO chloride permeability thresholds that favor polycarboxylate chemistry procurement. Metropolitan batching operations in Atlanta and Charlotte embed technical service teams for mix design optimization.
Gulf Coast Region
Texas and Louisiana host concentrated bulk manufacturing assets vulnerable to hurricane-related supply disruptions. State DOT tightening of bridge deck specifications accelerates reformulation away from legacy naphthalene-based products. Houston and Baton Rouge chemical corridor facilities face capital allocation decisions between emission control retrofit and full chemistry transitions.
Mountain West
Colorado, Utah, and Arizona present underpenetrated expansion targets as interstate highway and data center construction accelerates. Regional DOT specifications increasingly reference AASHTO performance grades for high-elevation concrete placements. Denver and Salt Lake City metropolitan batching operations lack embedded technical service infrastructure found in coastal markets.
Florida Peninsula
Florida DOT chloride-resistant specifications for coastal infrastructure drive premium formulation demand across bridge and marine applications. OSHA naphthalene exposure limits accelerate product substitution in batching plants statewide. Miami and Tampa metropolitan construction corridors concentrate specification influence among consolidated ready-mix networks.
Pacific Coast
California low-carbon concrete mandates reshape admixture portfolios toward cement-reduction enabling technologies. State-level embodied carbon thresholds accelerate specification of superplasticizers maintaining strength at reduced binder content. Los Angeles and San Francisco Bay Area metropolitan markets lead procurement of slump retention polymers for extended haul distances.
United States Concrete Superplasticizer Market Key Industry Players
Vertically integrated polymer producers and regional formulation blenders split the market into distinct capability tiers. Consolidation among national distributors concentrates specification influence across multi-state ready-mix networks. Two strategic archetypes dominate: integrated manufacturers with captive synthesis capabilities, and technical service specialists embedding teams in metropolitan batching operations. Competitive dynamics center on backward integration into polycarboxylate polymer production and geographic expansion into underpenetrated Mountain West corridors.
Within the integrated manufacturing tier, BASF Construction Chemicals and MBCC Group exemplify archetypes controlling molecular design from monomer through finished admixture. Sika Corporation occupies a position emphasizing specialized technical service deployment. These three entities represent the dominant competitive anchors shaping procurement leverage and specification capture across U.S. infrastructure corridors.
| Leading Market Players |
|---|
| CEMEX |
| Mapei S.P.A. |
| BASF Construction Chemicals |
| MBCC Group |
| Arkema Group |
| Sika Corporation |
| Altus Material |
| Euclid Chemical |
| GCP Applied Technologies |
| Others |
Cost & Logistics Intelligence
Gulf Coast capacity utilization rates near 85 percent concentrate pricing leverage among integrated polycarboxylate producers with captive polymer synthesis. This tightness elevates supplier discipline on volume allocations while compressing margins for non-integrated blenders lacking long-term olefins contracts.
Pricing Analysis
Geographic price spreads widen 15-20 percent between Gulf Coast bulk supply hubs and Mountain West distribution terminals. Three-tier pricing structure across premium, standard, and economy levels separates AASHTO-certified infrastructure grades from commercial construction formulations. Pricing pressure stems from polyethylene glycol and methacrylic acid feedstock volatility. Residential contractors exhibit highest price sensitivity; infrastructure DOT specifications show lowest.
Supply Chain Analysis
Contract manufacturing concentrates among Gulf Coast chemical corridor facilities in Texas and Louisiana with legacy naphthalene assets requiring EPA retrofit decisions. Raw material dependencies center on ethylene oxide derivatives, methacrylic acid monomers, and specialized polyethylene glycol feedstocks. Supply chain risk hinges on hurricane-related production disruption exposure during peak construction seasons. Distribution runs through national distributor networks consolidating multi-state ready-mix procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States concrete superplasticizer demand sits in early-cycle expansion as federal infrastructure spending elevates performance-grade specifications across Southeast megaproject corridors. Polycarboxylate chemistry penetration remains below saturation thresholds in Mountain West and residential segments.
For Market Incumbents: Insulate margin positions by accelerating backward integration into polycarboxylate polymer production and embedding technical service teams in Georgia and North Carolina metropolitan batching operations. EPA formaldehyde emission scrutiny threatens legacy naphthalene inventories; capital allocation toward emission control retrofit or full chemistry transition is the critical lever. For New Entrants and Emerging Players: Pursue white-space expansion in Colorado, Utah, and Arizona interstate highway and data center construction corridors where technical service infrastructure remains underdeveloped. Mountain West DOT specifications increasingly reference AASHTO performance grades without embedded admixture optimization support. Digital platform direct-to-contractor channels bypass consolidated distributor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across polycarboxylate polymer synthesis capabilities as backward integration becomes competitive necessity rather than optionality. Long-term viability favors integrated manufacturers controlling molecular design from monomer through finished admixture. Acquisition targets should demonstrate captive synthesis assets or specialized technical service deployment. Quarterly review of state DOT specification adoption timelines and EPA enforcement actions is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polycarboxylate polymer production insulates margin from olefins volatility and secures specification capture. |
| Technical Service Embedding | Metropolitan batching operation teams optimize dosing protocols and lock in multi-year supply agreements. |
| Emission Control Retrofit | Gulf Coast facilities face EPA NESHAP compliance decisions requiring capital deployment toward formaldehyde abatement. |
| Mountain West Expansion | Colorado and Arizona data center construction corridors lack embedded admixture optimization infrastructure. |
| Digital Platform Development | Direct-to-contractor e-procurement channels monetize technical service among mid-sized infrastructure buyers. |
Research Approach
The analysis maps polycarboxylate, sulfonated naphthalene, lignosulfonate, and hybrid formulation sub-sectors, each validated through technical service directors, ready-mix procurement managers, state DOT specification engineers, and polymer synthesis plant managers. Primary interview intelligence triangulates against customs trade data, American Concrete Institute technical bulletins, EPA enforcement records, SEC 10-K filings from listed construction chemical producers, and AASHTO specification adoption databases. Bottom-up volume modeling from individual batching operations reconciles with top-down federal infrastructure spending allocation analysis.
Assumptions held fixed include Infrastructure Investment and Jobs Act funding trajectories, EPA NESHAP enforcement intensity, and polycarboxylate polymer yield curves; variables tested across olefins price scenarios and state DOT specification adoption timelines. Segmentation dimensions span formulation chemistry, technology tier, end-use application intensity, and distribution channel structure. CAGRs derive from regression analysis against historical cement consumption and admixture penetration elasticities. Forecast inputs incorporate chloride permeability specification tightening rates and low-carbon concrete mandate expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in construction employment, interest rate sensitivity for infrastructure financing, and cement price inflation would shift the trajectory. Forecasts reflect documented assumptions regarding federal spending continuity and regulatory enforcement cadence. Quarterly review of state DOT specification bulletins, EPA consent decree filings, and Gulf Coast hurricane season severity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Europe Cyclic Olefin Copolymer Market
Chemicals & Materials
Metal Forging Market
Chemicals & Materials
United States Pressure Sensitive Adhesives (PSA) Market
Chemicals & Materials
Pre-Painted Galvanised Iron (PPGI) Market
Chemicals & Materials
Global Formulation Development Outsourcing Market
Chemicals & Materials
Organometallics Market
Chemicals & Materials
Single-Ply Membranes Market
Chemicals & Materials
Additive Masterbatch Market
Chemicals & Materials
Global Thermal Ceramics Market
Chemicals & Materials
Global Mannosylerythritol Lipids Market
Chemicals & Materials
Functional Composites Market
Chemicals & Materials
Intake Filter Media Market
Chemicals & Materials
Global Lab Automation in Analytical Chemistry Market
Chemicals & Materials
Styrene Market
Chemicals & Materials
C2 Chlorinated Solvents Market
Chemicals & Materials
Metal Removal Fluids Market