
 Encapsulated Sodium Bicarbonate Market | 2026-2036
Encapsulated Sodium Bicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Sodium Bicarbonate Market Foresight
Pharmaceutical formulation is restructuring demand profiles as controlled-release antacid applications expand. Solvay S.A. leverages its integrated soda ash-to-specialty chemicals chain to secure feedstock consistency. Encapsys, LLC anchors North American supply through proprietary microencapsulation technology platforms. Balchem Corporation differentiates via precision nutrition and pharmaceutical-grade encapsulation capabilities.
Encapsulated sodium bicarbonate consists of sodium hydrogen carbonate cores surrounded by protective lipid, polymer, or protein-based coatings, typically ranging from 50 to 500 micrometers in diameter, designed to enable targeted release, moisture protection, and taste masking in industrial formulations. The coating material selection determines dissolution pH thresholds and thermal stability during processing. Powder and granule product types dominate current volume as these forms integrate most efficiently into pharmaceutical tableting and food mixing operations. pH regulation and antacid applications command the widest end-use footprint, while food preservative demand accelerates fastest among application categories as clean-label shelf-life extension gains traction.
FDA pharmaceutical excipient guidelines, EPA chemical processing standards, and EMA good manufacturing practice frameworks govern product purity, batch consistency, and facility compliance across major supply jurisdictions. REACH registration requirements in Europe and FSSAI food additive regulations in India impose additional testing and documentation burdens that filter market participants by technical capability. Stakeholders must monitor evolving encapsulation material sustainability standards and regional clean-label certification thresholds as these criteria increasingly determine contract eligibility with multinational pharmaceutical and food manufacturers.
Market Dynamics
Pharmaceutical formulation developers now specify encapsulation performance thresholds that exceed legacy sodium bicarbonate specifications, forcing coating technology upgrades across the supply base.
Growth Catalysts
- Controlled-release antacid demand:Gastroenterology clinics in the United States increasingly prescribe pH-modulated therapies requiring precision encapsulation.
- Clean-label food preservation:REACH-registered encapsulation materials enable shelf-life extension without synthetic additive declarations in European retail channels.
- Microencapsulation process maturation:Fluidized bed coating advances reduce batch-to-batch dissolution variance below 5% for pharmaceutical excipient applications.
Market Restraints
- Specialty lipid feedstock volatility:Hydrogenated palm stearin and beeswax derivatives face price swings tied to Malaysian and Indonesian export quotas.
- EMA good manufacturing practice compliance costs:Pharmaceutical-grade facility qualification requires capital outlays that exclude smaller toll manufacturers from contract eligibility.
- Uncoated sodium bicarbonate substitution:Cost-sensitive industrial buyers in commodity baking applications bypass encapsulation entirely.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO excipient registration pathways now accommodate imported encapsulated alkalis for domestic formulation.
- Personalized nutrition delivery:Targeted-release sodium bicarbonate cores enable sports hydration products with stomach-buffered electrolyte release.
- FSSAI clean-label alignment:Encapsulation-derived shelf-life extension satisfies India's 2024 additive reduction mandates for packaged foods.
Industry Challenges
- Microencapsulation process engineering talent scarcity:Fluidized bed and coacervation specialists command premium compensation in pharmaceutical manufacturing clusters.
- Multi-jurisdiction dossier harmonization:FDA Type II drug master files, EMA CEP applications, and CDSCO import licenses require parallel documentation streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Sodium Bicarbonate Market |
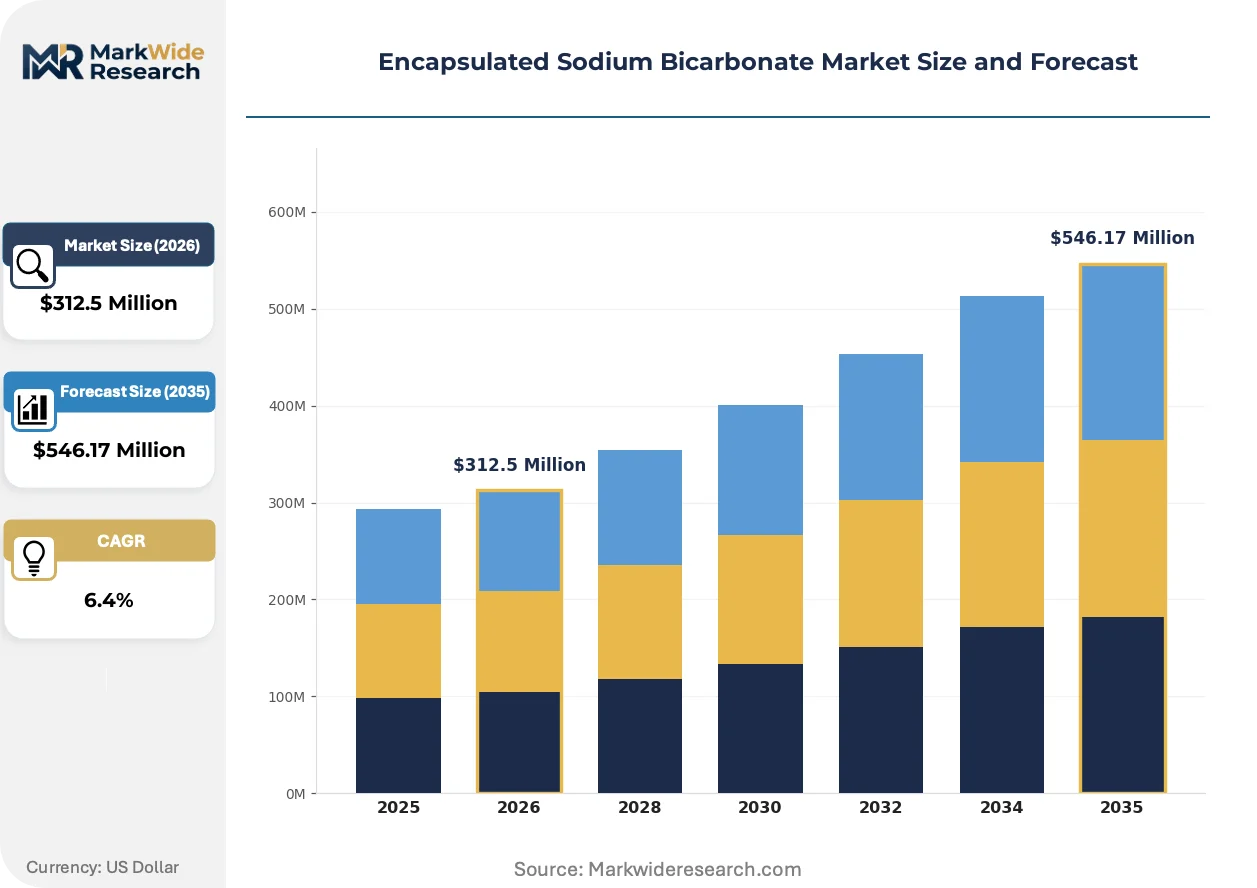
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granule, Powder, Tablet, Capsule End User: Pharmaceuticals, Food Industry, Cosmetics, Agriculture Application: pH Regulation, Antacid, Food Preservative, Cleaning Agent Packaging Type: Bulk Bags, Pouches, Bottles, Sachets |
| Companies Covered | Solvay S.A., Encapsys, LLC, Balchem Corporation, Innophos Holdings, Inc., GAT Food Essentials GmbH, Cargill, Incorporated, Aveka Group, INNOBIO Corporation Limited, Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Sodium Bicarbonate Market Shifts & Advancements
Coating material science and release-mechanism engineering now determine competitive position in pharmaceutical and food-grade supply contracts.
Multilayer polymer-lipid hybrid encapsulation systems are modularizing formulation flexibility for pharmaceutical developers. Solvay and Balchem customers specify discrete dissolution triggers across gastric and intestinal pH zones. This architecture compresses development cycles for combination antacid therapies.
EMA's 2023 revised excipient guidelines now mandate nitrosamine impurity screening for all polymer-coated oral dosage components. Batch release testing protocols have extended lead times by two to four weeks for European pharmaceutical customers. German and Swiss contract manufacturers have absorbed these costs through dedicated analytical chemistry capacity.
Direct procurement from encapsulation specialists is displacing distributor intermediaries among mid-scale pharmaceutical formulators. Buyers in North Carolina and New Jersey now negotiate annual volume contracts with Encapsys and Balchem directly. This channel compression accelerates technical specification alignment but concentrates supplier risk.
Encapsulated Sodium Bicarbonate Market Segmentation
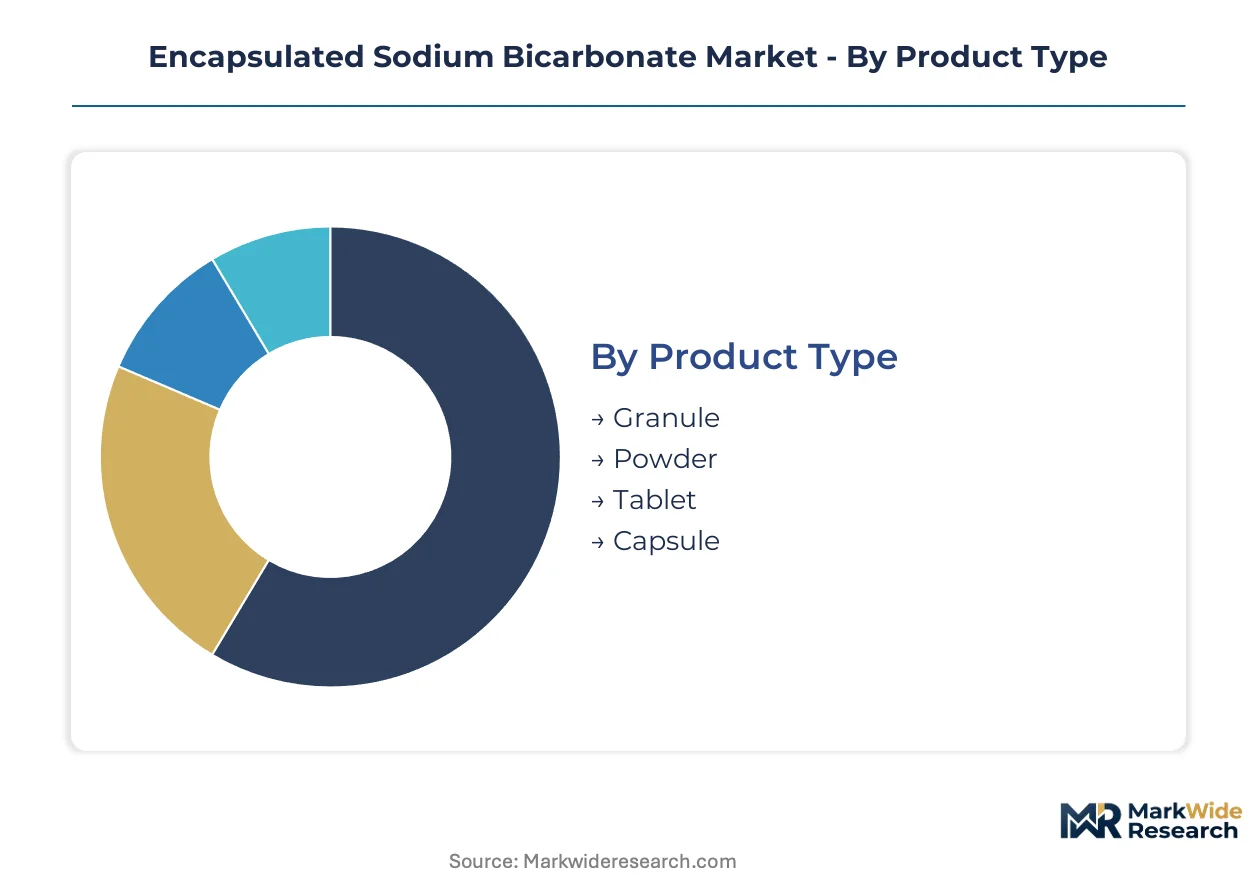
Encapsulated sodium bicarbonate serves distinct performance requirements across pharmaceutical tableting, food processing, and industrial formulations. Segment boundaries reflect coating technology compatibility, release kinetics, and regulatory compliance thresholds that determine contract eligibility with multinational buyers.
Product Type:
Granule and powder formats integrate directly into high-throughput manufacturing lines, while tablets and capsules require downstream conversion by formulators.
- Granule:Spherical agglomerates with lipid or polymer coatings withstand mechanical stress during fluidized bed processing. Pharmaceutical manufacturers in Germany specify granule diameters between 200-500 micrometers for direct-compression tableting operations.
- Powder:Finely milled cores with sub-100 micrometer coatings disperse uniformly in dry food mixes and effervescent formulations. Food processors in the United States favor powder for clean-label leavening systems where rapid dissolution is secondary to shelf-life extension.
- Tablet:Pre-compressed units with enteric coatings bypass gastric degradation for intestinal pH targeting. CDSCO-registered Indian formulators import tablet grades for antacid combination therapies.
- Capsule:Hard-shell gelatin or HPMC enclosures containing coated bicarbonate granules enable dose-flexible nutraceutical applications.
Granule leads volumes today; powder is gaining share fastest.
End User:
Customer procurement patterns diverge sharply between GMP-certified pharmaceutical buyers and cost-optimized food processors.
- Pharmaceuticals:FDA Type II drug master file holders demand batch-to-batch dissolution variance below 5% for antacid excipient applications. EMA CEP documentation requirements filter supplier pools to encapsulation specialists with dedicated analytical chemistry capacity.
- Food Industry:Clean-label shelf-life extension drives substitution of synthetic preservatives with encapsulated bicarbonate in European retail channels. REACH-registered coating materials enable additive-free declarations on packaged baked goods.
- Cosmetics:pH buffering in personal care formulations employs micronized encapsulated grades for controlled alkalinity release in skin creams.
- Agriculture:Slow-release alkalinity modulation in animal feed supplements supports rumen pH management in dairy operations.
Pharmaceuticals commands the premium tier; food industry is expanding most quickly.
Application:
Functional performance requirements determine coating architecture selection across pH-triggered, moisture-activated, and thermal-release mechanisms.
- pH Regulation:Gastric-resistant coatings dissolve at intestinal pH thresholds above 6.5, enabling targeted alkalinity delivery. Solvay's polymer-lipid hybrid systems serve combination therapies requiring discrete gastric and intestinal release zones.
- Antacid:Immediate-release formulations dominate over-the-counter markets, while controlled-release variants gain prescription share for chronic gastroesophageal conditions.
- Food Preservative:Encapsulation-derived shelf-life extension satisfies India's FSSAI additive reduction mandates without synthetic chemical declarations.
- Cleaning Agent:Thermal-activated release in industrial dishwasher formulations protects bicarbonate from premature reaction during storage.
Antacid anchors current demand; food preservative shows the steepest expansion trajectory.
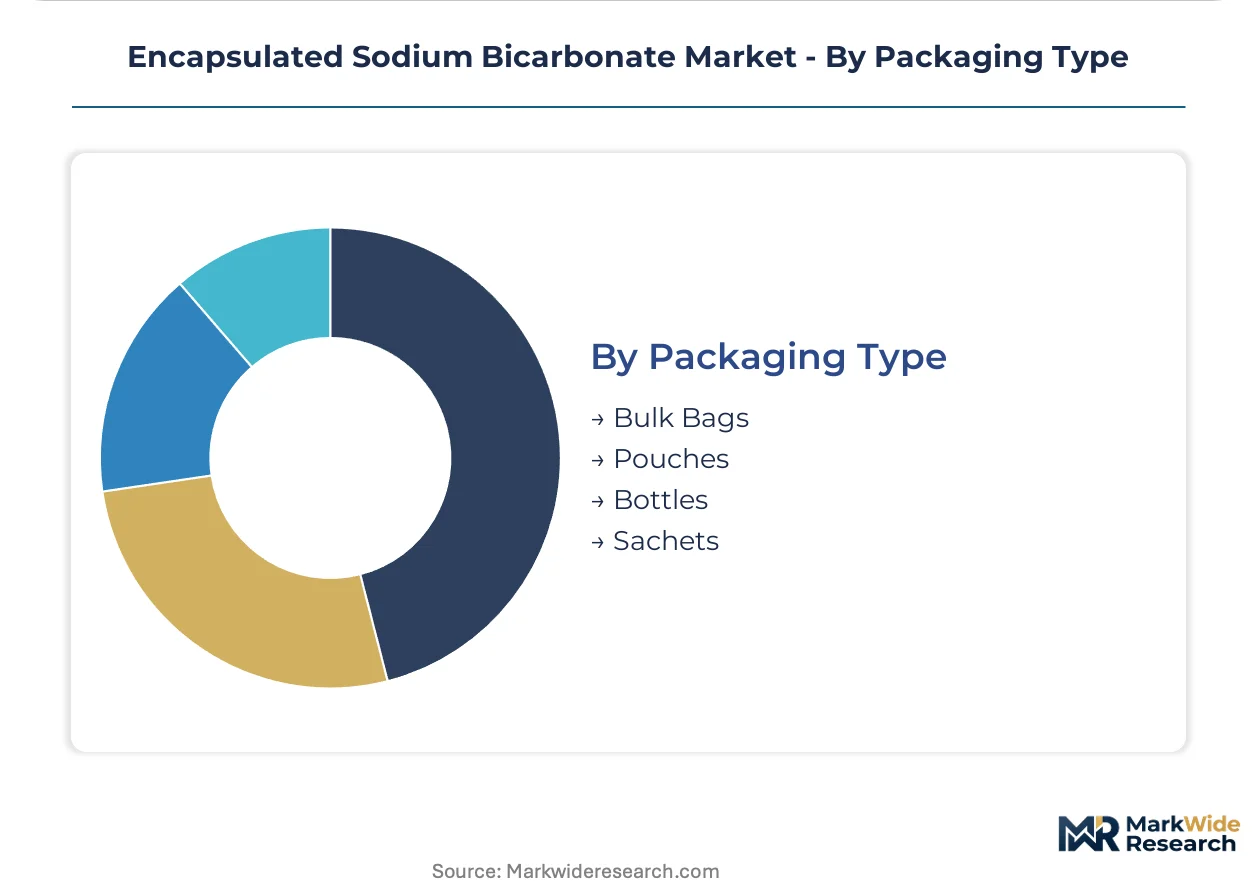
Packaging Type:
Packaging selection correlates with customer scale, with bulk formats serving toll manufacturers and unit-dose formats reaching retail channels.
- Bulk Bags:Multi-wall laminated sacks with moisture barriers protect hygroscopic coated granules during pharmaceutical ingredient distribution. Swiss contract manufacturers specify nitrogen-flushed bulk packaging for EMA-compliant excipient shipments.
- Pouches:Stand-up flexible packaging with high-barrier films serves mid-scale food processors requiring partial lot usage.
- Bottles:Desiccant-capped HDPE containers preserve tablet and capsule integrity through retail shelf life.
- Sachets:Single-serve unit doses support hospitality and travel-sector antacid distribution in emerging markets.
Bulk bags dominate pharmaceutical procurement; sachets are climbing the fastest in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting encapsulated sodium bicarbonate production toward jurisdictions with streamlined excipient registration pathways. Manufacturers in Germany and Switzerland absorb EMA compliance costs through dedicated analytical infrastructure, while Indian and Chinese suppliers capture volume through CDSCO and NMPA process efficiencies. Cost-of-compliance gaps between Western and Asian pharmaceutical regulators now exceed fifteen percentage points in facility qualification expenses.
United States
Gastroenterology clinics in North Carolina and New Jersey prescribe pH-modulated antacid therapies requiring precision encapsulation. FDA Type II drug master file requirements filter supplier pools to specialists with dedicated analytical chemistry capacity. Direct procurement contracts with Encapsys and Balchem displace distributor intermediaries among mid-scale pharmaceutical formulators in these states.
Germany
EMA CEP documentation mandates and revised 2023 excipient guidelines extend batch release testing lead times by two to four weeks. German contract manufacturers in Bavaria and North Rhine-Westphalia absorb nitrosamine impurity screening costs through captive analytical laboratories. REACH-registered coating materials enable additive-free shelf-life extension declarations for European retail channels.
China
NMPA excipient registration reforms accommodate imported encapsulated alkalis for domestic pharmaceutical formulation. Yangtze River Delta chemical clusters in Jiangsu and Zhejiang provinces specialize in hydrogenated palm stearin coating production for export markets. Dual carbon goals pressure coating material suppliers toward bio-based lipid alternatives.
India
CDSCO import license pathways now permit encapsulated sodium bicarbonate for domestic antacid combination therapies. Maharashtra and Gujarat pharmaceutical manufacturing corridors expand excipient toll manufacturing capacity. FSSAI 2024 additive reduction mandates accelerate clean-label encapsulation adoption in packaged food processing.
Switzerland
Swissmedic pharmaceutical-grade facility standards attract encapsulation specialists serving premium European markets. Basel and Zurich chemical clusters maintain nitrogen-flushed bulk packaging infrastructure for EMA-compliant excipient distribution. Contract manufacturers here command fifteen to twenty percent price premiums over German competitors for equivalent specifications.
Encapsulated Sodium Bicarbonate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade supply consolidating around GMP-certified facilities while food-grade procurement fragments across regional toll operators. Three archetypes dominate: integrated chemical conglomerates with captive soda ash feedstock, pure-play microencapsulation technology licensors, and nutrition-focused precision delivery specialists. Competitive moves concentrate on strategic partnerships for coating material supply security and geographic expansion into Indian pharmaceutical manufacturing corridors.
Among European integrated chemical producers, Solvay S.A. exemplifies the feedstock-anchored archetype through its soda ash-to-specialty chemicals chain. Encapsys, LLC and Balchem Corporation occupy distinct positions in North American pharmaceutical and nutrition-grade supply respectively, with the former representing proprietary microencapsulation platform specialists and the latter precision nutrition delivery capabilities. These three companies illustrate how coating technology specialization and regulatory dossier depth determine contract eligibility with multinational formulators.
| Leading Market Players |
|---|
| Solvay S.A. |
| Encapsys, LLC |
| Balchem Corporation |
| Innophos Holdings, Inc. |
| GAT Food Essentials GmbH |
| Cargill, Incorporated |
| Aveka Group |
| INNOBIO Corporation Limited |
| Church & Dwight Co., Inc. |
| Others |
Supply & Pricing Matrix
Hydrogenated palm stearin price benchmarks from Malaysian and Indonesian export markets cascade through encapsulation coating costs, compressing margins for pharmaceutical-grade suppliers while forcing food-grade producers toward synthetic coating substitutions or volume-driven contract structures.
Pricing Analysis
Distributor margins of 12-18 percent separate pharmaceutical excipient pricing from direct-to-OEM food-grade contracts, with EMA CEP-certified batches commanding premiums over FDA Type II file equivalents. Pricing stratifies across GMP-certified pharmaceutical, REACH-registered food, and industrial baking tiers, with cost compression in commodity baking applications intensifying as uncoated sodium bicarbonate substitution accelerates. Pharmaceutical formulators show least price sensitivity due to regulatory switching costs; industrial bakers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle pharmaceutical formulator demand in North Carolina and New Jersey, while distributor networks serve fragmented European food processors. Supply concentrates in the United States, Germany, and China, with coating production drawing from Malaysian palm stearin, Indonesian beeswax derivatives, and German polymer feedstocks. Single-source vulnerability in Southeast Asian lipid supply creates exposure to export quota disruptions. Distribution runs through bulk nitrogen-flushed packaging for pharmaceutical excipients and multi-wall laminated sacks for food-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
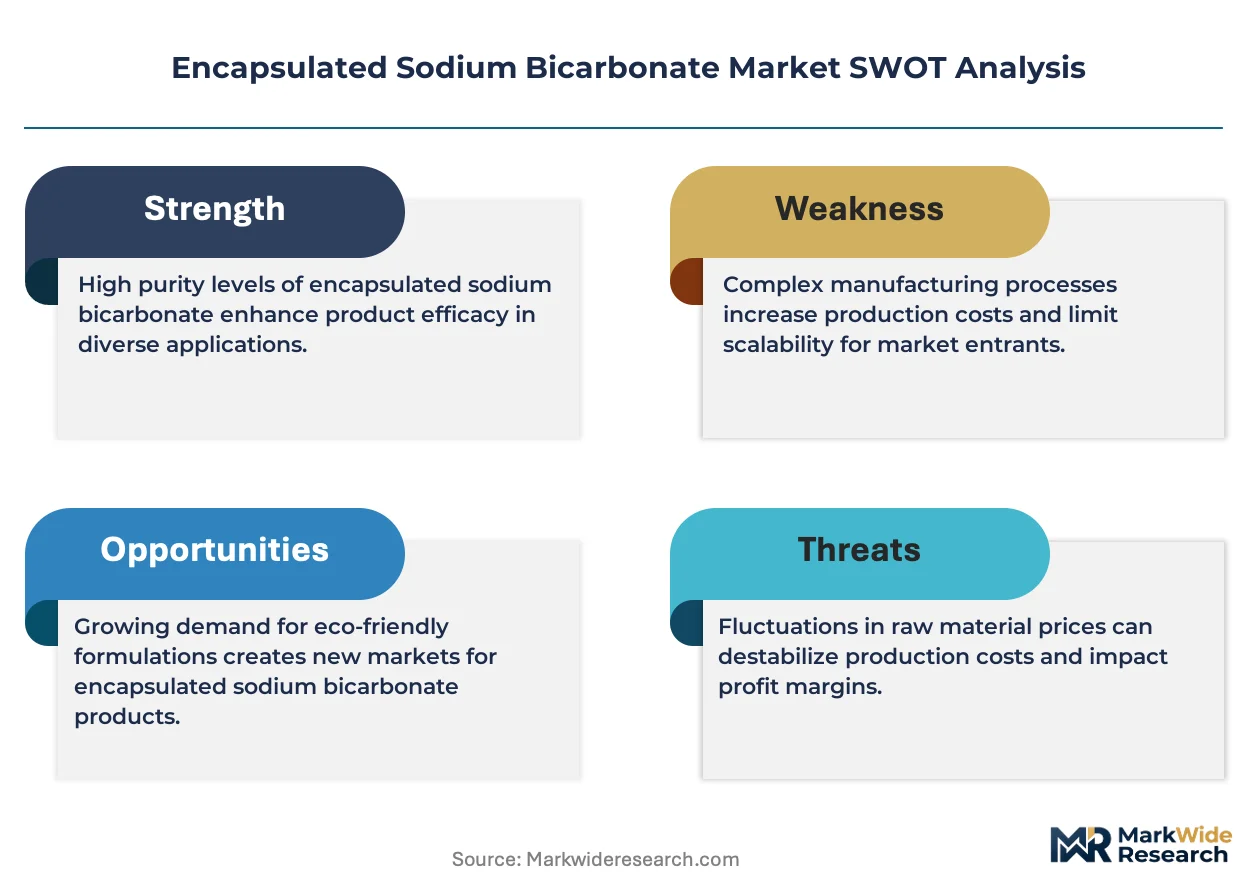
Encapsulated sodium bicarbonate represents a late-cycle quality story as pharmaceutical formulators shift toward multilayer polymer-lipid hybrid systems with sub-5 percent dissolution variance thresholds.
For Market Incumbents: Cement GMP-certified capacity advantages through captive analytical chemistry infrastructure for nitrosamine impurity screening mandated by EMA's 2023 revised excipient guidelines. Deepen backward integration into soda ash feedstock through Solvay-style integrated chemical chains to defend against specialty lipid price volatility and emerging Chinese coating specialists. For New Entrants and Emerging Players: Mid-scale Indian pharmaceutical formulators seeking CDSCO-registered encapsulated alkalis present the most penetrable buyer archetype, with FSSAI clean-label food processors in Maharashtra and Gujarat as secondary targets. Enter through toll manufacturing partnerships with existing GMP facilities rather than greenfield qualification, leveraging coating technology licensing from European microencapsulation specialists. For Investors and Strategic Acquirers: Asymmetric upside sits with precision nutrition delivery specialists possessing pharmaceutical-grade encapsulation capabilities and established EMA/FDA dossier libraries. Five-to-ten year viability hinges on clean-label certification depth rather than commodity volume scale. Monitor EMA batch release testing lead time extensions as signal for analytical chemistry capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash Feedstock | Solvay's integrated chemical chain secures coating material cost stability against Malaysian export quota volatility. |
| GMP-Certified Analytical Chemistry Capacity Addition | German contract manufacturers absorb EMA nitrosamine screening mandates through captive Bavaria-based laboratories. |
| CDSCO Excipient Registration Pathway Expansion | Imported encapsulated alkalis gain domestic formulation eligibility in Maharashtra pharmaceutical corridors. |
| Multilayer Polymer-Lipid Hybrid Technology Licensing | Discrete gastric and intestinal release zones compress development cycles for combination antacid therapies. |
| REACH-Registered Coating Material Sourcing | Clean-label shelf-life extension satisfies FSSAI additive reduction mandates without synthetic chemical declarations. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical formulation executives, food processing procurement leads, and encapsulation technology directors; secondary validation through FDA Type II drug master file repositories, EMA CEP application databases, and CDSCO import license records; plus customs trade data from United States, German, and Indian ports — were reconciled through bottom-up volume triangulation against top-down market sizing.
Segment-level projections across granule, powder, tablet, and capsule product types were modeled against pharmaceutical, food industry, cosmetics, and agriculture end-use demand patterns throughout the forecast period. CAGRs derive from regression analysis of historical coating technology adoption curves and regulatory compliance cost trajectories, with fluidized bed process maturation and clean-label certification thresholds as key forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes with established FDA and EMA filing histories carry tighter precision than emerging food preservative applications in Indian packaged goods. Forecasts reflect assumptions regarding EMA guideline stability, Southeast Asian lipid export policy continuity, and CDSCO registration pathway efficiency. Periodic stress-testing of base assumptions against regulatory announcement timelines and commodity price index movements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Caproic Acid Market