
 Titanium Powder Market | 2026-2036
Titanium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Powder Market Intelligence
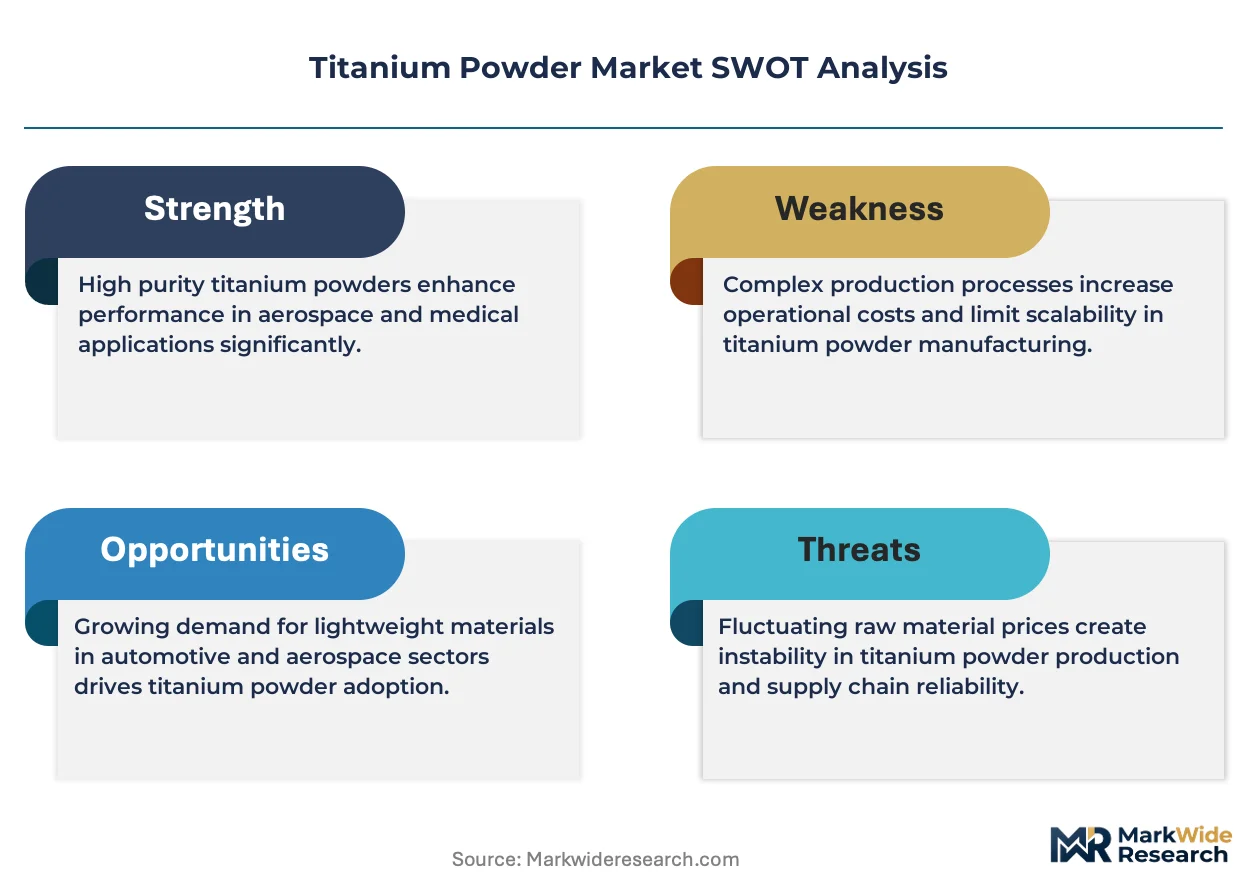
Aerospace procurement is realigning toward additive manufacturing feedstock as engine OEMs and airframers expand powder-bed fusion qualifications. ATI leverages captive titanium sponge capacity to secure long-term supply agreements with defense contractors. Sandvik anchors its position through plasma atomization technology leadership for high-purity spherical powder. Kymera International specializes in hydride-dehydride processing for cost-sensitive industrial applications outside aerospace.
Titanium powder consists of refined metallic particles, typically 15-150 micrometers in diameter, produced through gas atomization, plasma atomization, or hydride reduction of titanium sponge and alloys, serving primarily as feedstock for additive manufacturing, metal injection molding, and thermal spray coatings. Gas atomized powder commands premium positioning in aerospace qualification programs due to superior flowability and low oxygen content. Additive manufacturing represents the fastest-growing application dimension as Tier 1 suppliers qualify titanium powder for flight-critical components. Commercially pure titanium grades occupy mature demand pools in chemical processing and marine hardware where corrosion resistance outweighs strength requirements.
The FAA regulates airworthiness certification of additively manufactured titanium parts through its evolving guidance on powder feedstock qualification and process control. ASTM International standards F2924 and F3001 govern additive manufacturing titanium powder chemistry and density, while ISO/ASTM 52900 defines terminology frameworks that shape cross-border trade documentation. REACH registration requirements in Europe constrain powder import pathways for non-EU producers lacking substance dossiers. Stakeholders must monitor evolving powder reuse protocols and oxygen pickup limits as qualification standards tighten for human-rated space and medical implant applications.
Market Dynamics
The FAA's airworthiness certification pathway for additively manufactured titanium parts is compressing qualification timelines while concentrating demand among defense primes and space launch providers with captive powder supply agreements.
Growth Catalysts
- Defense procurement mandates:The US Department of Defense prioritizes domestic titanium sponge and powder sourcing under the Defense Production Act, anchoring offtake for structural airframe components.
- ASTM F2924 qualification standards:Standardized chemistry and density specifications for additive manufacturing feedstock accelerate multi-source approvals for flight-critical parts.
- Plasma atomization:This production method yields spherical high-purity powder with superior flowability, enabling layer consistency in powder-bed fusion systems for rocket engine components.
Market Restraints
- Titanium sponge supply concentration:Four countries control over 80% of global sponge production, exposing powder manufacturers to feedstock disruption and price volatility.
- REACH registration barriers:European substance dossier requirements constrain non-EU powder producers from accessing EU additive manufacturing supply chains without regulatory partnerships.
- Argon gas dependency:Plasma and gas atomization processes require high-purity argon, with supply bottlenecks during semiconductor manufacturing cycles squeezing powder production margins.
Strategic Opportunities
- Medical implant qualification:ISO/ASTM 52900 terminology frameworks enable cross-border documentation for patient-specific cranial and orthopedic implants using electron beam melting.
- India PLI scheme:Production-linked incentives for aerospace and defense manufacturing attract powder producers to establish atomization capacity near Bangalore and Hyderabad industrial clusters.
- Hydride-dehydride cost positioning:Irregular powder morphology from this process serves metal injection molding and thermal spray markets outside aerospace premium pricing tiers.
Industry Challenges
- Oxygen pickup control:Powder reuse protocols in additive manufacturing systems risk exceeding 0.13% oxygen limits for Ti-6Al-4V, requiring real-time monitoring investments and batch segregation.
- Non-destructive testing integration:Computed tomography qualification for internal porosity in complex geometries extends certification timelines beyond traditional wrought material approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Powder Market |
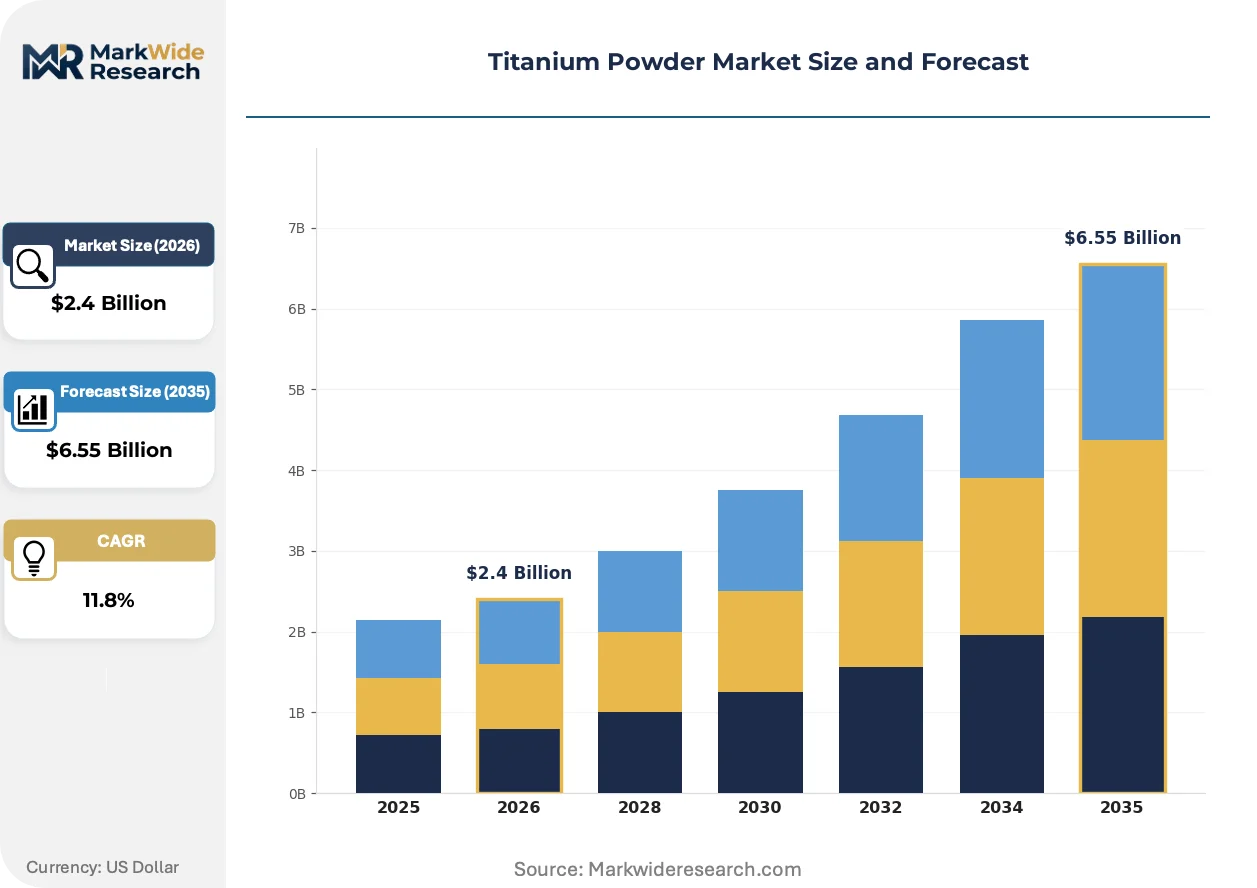
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Particle Metallurgy, Additive Manufacturing, Thermal Spray, Medical Grade: Commercially Pure Titanium, Alloyed Titanium, Grade 5, Grade 23 Application: Aerospace, Automotive, Medical Devices, Marine Form: Gas Atomized, Plasma Atomized, Hydride, Sponge |
| Companies Covered | ADMA Products, ATI, Sandvik, ECKART, Kymera International, MEPCO, AP&C, OSAKA Titanium Technologies, Tronox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Powder Market Strategic Shifts & Innovations
Process control digitization and feedstock traceability systems are restructuring how titanium powder moves from atomization through final part certification.
Plasma atomization is rewriting qualification economics for spherical titanium alloy powder. SpaceX and Relativity Space consume premium-grade feedstock for 3D-printed rocket thrust chambers and turbopump housings. The technology compresses traditional multi-year forging-to-machining cycles into days, reshaping supplier-procurement relationships around powder-bed fusion throughput guarantees.
REACH substance dossier requirements in Europe constrain import pathways for non-EU atomization producers lacking registration partnerships. ECHA enforcement of extended safety data sheet obligations forces powder distributors to document particle size distribution and surface oxide chemistry. Medical implant manufacturers in Germany and Switzerland respond by qualifying dual-source supply from EU-registered atomizers.
Long-term offtake agreements displace spot purchasing among Tier 1 aerospace suppliers. Defense primes now contract directly with titanium sponge producers for backward-integrated powder capacity, bypassing traditional merchant market intermediaries. This concentration is most visible in the United States, where ATI and Howmet Aerospace anchor multi-year supply commitments for F-35 and next-generation bomber programs.
Titanium Powder Market Segmentation
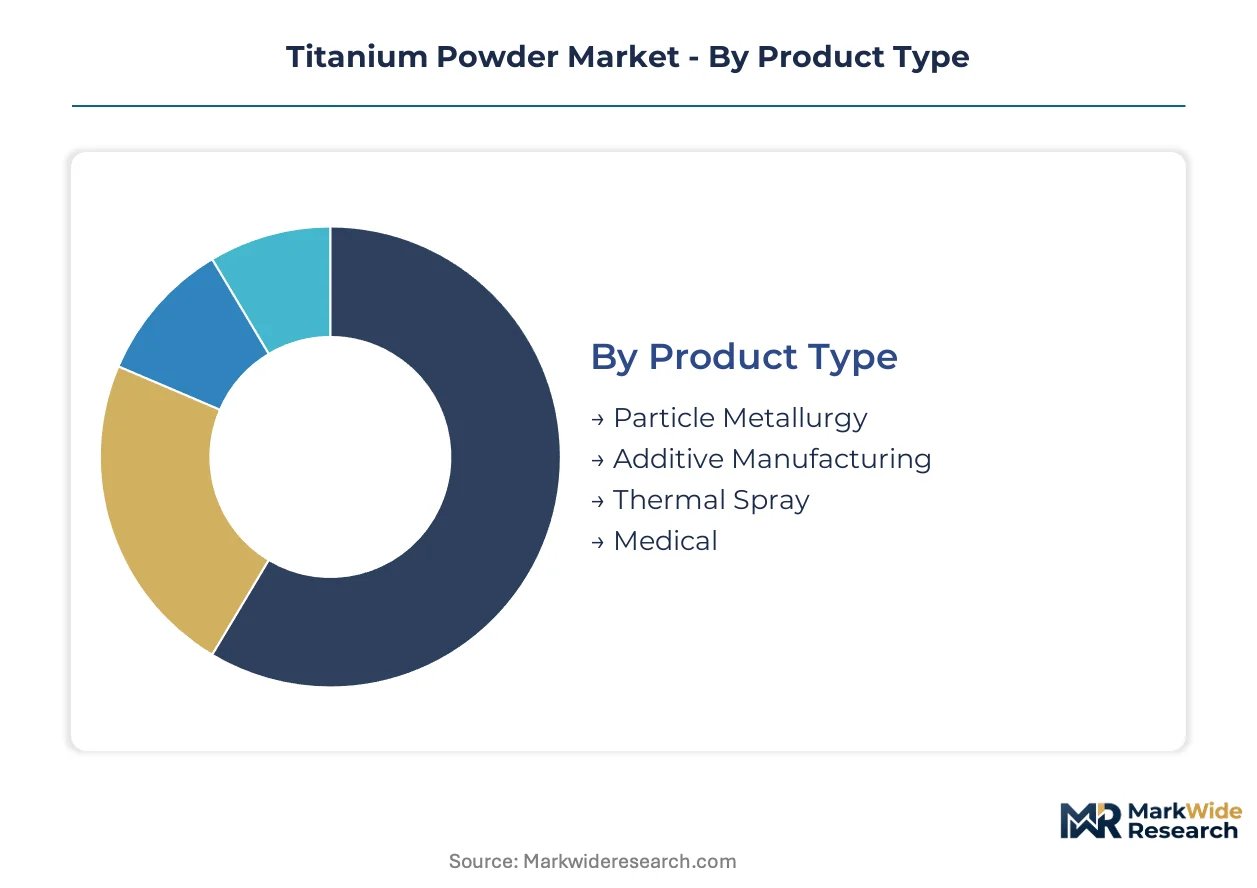
Segmentation in titanium powder markets tracks how atomization technology and qualification requirements split value capture across defense, medical, and industrial supply chains. Capital deployment, certification timelines, and feedstock access determine which segments concentrate producer margins.
Product Type:
Capital intensity varies sharply across production methods, with plasma atomization requiring the heaviest upfront investment in inert gas infrastructure and power systems.
- Additive Manufacturing:Spherical powder with tight particle size distribution serves powder-bed fusion and directed energy deposition systems. Aerospace primes in the United States anchor offtake for flight-critical Ti-6Al-4V components as FAA certification pathways mature. Oxygen pickup limits below 0.13% drive real-time monitoring investments.
- Particle Metallurgy:Irregular morphology from hydride-dehydride processing feeds metal injection molding and press-and-sinter operations. Automotive and industrial tooling applications in Germany and Japan concentrate demand where surface finish requirements are less stringent than aerospace.
- Thermal Spray:Coarse angular powder builds corrosion-resistant coatings for chemical processing equipment and marine hardware. Demand clusters along Gulf Coast petrochemical corridors and North Sea offshore infrastructure.
- Medical:Ultra-high-purity spherical powder for electron beam melting of patient-specific implants. ISO/ASTM 52900 documentation frameworks enable cross-border supply to Swiss and German orthopedic device manufacturers.
Most installed capacity flows through Additive Manufacturing. Expansion is steepest in Medical as implant qualification accelerates.
Grade:
Cost tier stratification separates aerospace-grade alloy premiums from commodity pure titanium serving corrosion-resistant industrial applications.
- Grade 5:Ti-6Al-4V alloy dominates aerospace structural applications with strength-to-weight ratios exceeding 1000 MPa tensile strength. SpaceX and Relativity Space consumption for 3D-printed rocket thrust chambers anchors premium pricing tiers.
- Commercially Pure Titanium:Unalloyed grades 1 through 4 serve chemical processing heat exchangers and marine propulsion components. Japanese and Korean shipbuilders concentrate demand where weldability and seawater corrosion resistance outweigh strength requirements.
- Alloyed Titanium:Ti-5Al-2.5Sn and Ti-6Al-2Sn-4Zr-2Mo variants target elevated-temperature engine applications. Rolls-Royce and Pratt & Whitney qualification programs drive batch consistency requirements.
- Grade 23:Ti-6Al-4V ELI extra-low interstitial formulation meets medical implant biocompatibility standards. FDA 510(k) clearance pathways and ISO 5832-3 compliance constrain supplier pools to atomizers with validated oxygen control.
Pricing stratifies across aerospace alloy, medical ELI, and industrial pure grades. Volume concentration remains heaviest in Grade 5.
Application:
Customer type segmentation reveals how defense procurement mandates concentrate powder offtake differently than commercial medical or automotive demand.
- Aerospace:Structural airframe components and engine parts consume the highest-purity spherical powder. F-35 and next-generation bomber programs in the United States lock in multi-year supply agreements with ATI and Howmet Aerospace.
- Medical Devices:Patient-specific cranial and orthopedic implants require lot-traceable powder with documented particle morphology. German and Swiss manufacturers lead electron beam melting adoption for complex geometries.
- Automotive:Motorsport and luxury vehicle exhaust systems drive limited titanium powder consumption. Formula 1 additive manufacturing of suspension components represents niche demand.
- Marine:Deep-sea pressure hulls and desalination equipment use commercially pure grades. Saudi Arabia and UAE infrastructure investments concentrate Gulf region offtake.
Defense aerospace commands the steepest premium pricing. Medical device qualification is gaining share fastest as implant personalization expands.
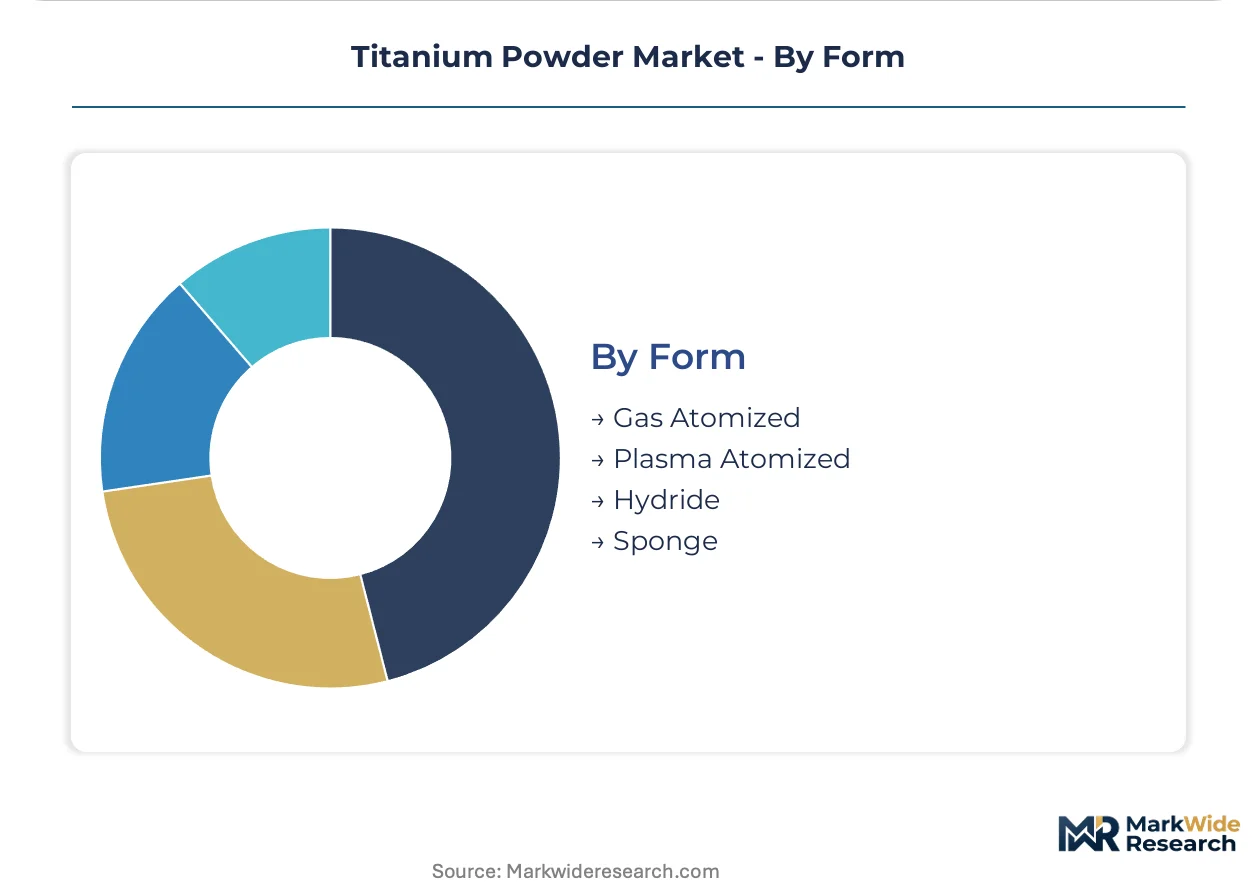
Form:
Supply concentration in atomization technology determines which powder morphologies access qualified supply chains.
- Plasma Atomized:Rotating electrode process yields near-perfect spheres with satellite-free surfaces. Sandvik and Praxair S.T. Technology anchor capacity for space launch and medical implant feedstock.
- Gas Atomized:High-pressure inert gas breakup of molten titanium streams produces flowable powder for powder-bed fusion. Argon supply constraints during semiconductor manufacturing cycles squeeze production economics.
- Hydride:Brittle titanium hydride milling and dehydrogenation creates angular irregular particles for lower-cost metal injection molding. Kymera International specializes in this cost-positioned segment.
- Sponge:Crude titanium from Kroll process reduction serves non-aerospace thermal spray and chemical reduction applications. Chinese and Russian producers dominate merchant sponge trade.
Plasma and gas atomized forms capture the aerospace qualification premium. Hydride processing is climbing fastest in industrial markets outside flight-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Huntsville, Alabama aerospace corridor anchors titanium powder demand as SpaceX and Blue Origin expand rocket engine additive manufacturing capacity. Defense procurement mandates under the Defense Production Act concentrate sponge-to-powder supply chains near Department of Defense prime contractors.
United States
F-35 and next-generation bomber programs drive titanium powder offtake for structural airframe components. FAA airworthiness certification pathways for additively manufactured parts compress qualification timelines for domestic suppliers. The Huntsville-Decatur industrial cluster in Alabama hosts backward-integrated powder capacity serving defense primes.
Germany
Medical implant manufacturers in Baden-Württemberg and Bavaria consume ultra-high-purity spherical powder for electron beam melting of patient-specific orthopedic devices. ECHA REACH substance dossier requirements constrain non-EU powder import pathways without registration partnerships. The Stuttgart-Tübingen medical technology corridor leads European adoption of ISO/ASTM 52900 documentation frameworks.
China
Domestic sponge production from the Kroll process feeds expanding gas atomization capacity for industrial additive manufacturing applications. MIIT industrial standards for titanium alloy powder chemistry shape qualification protocols for aerospace and medical supply chains. The Baoji titanium industrial cluster in Shaanxi Province concentrates hydride-dehydride processing for cost-sensitive metal injection molding markets.
Japan
Shipbuilders in Nagasaki and Kobe concentrate demand for commercially pure titanium grades in marine propulsion and desalination equipment. METI technology roadmaps for advanced materials prioritize powder-bed fusion feedstock development for precision manufacturing. The Chubu region around Nagoya hosts integrated titanium sponge and alloy powder production serving automotive and chemical processing industries.
India
Production-linked incentive schemes for aerospace and defense manufacturing attract atomization capacity investment near Bangalore and Hyderabad industrial clusters. BIS standards for titanium powder particle size distribution and chemistry align with ASTM F2924 specifications for additive manufacturing feedstock. The Karnataka-Telangana corridor emerges as a regional hub for plasma atomization technology serving domestic space launch providers.
Titanium Powder Market Key Industry Players
Backward integration into titanium sponge supply dominates the current landscape as defense primes contract directly with feedstock producers. The vendor base separates into three tiers: integrated sponge-to-powder producers with captive aerospace qualifications, specialized atomization technology providers serving medical and space launch markets, and cost-positioned hydride processors for industrial applications. Strategic archetypes include qualification-heavy defense suppliers, technology-differentiated spherical powder specialists, and volume-driven irregular powder merchants. Capacity expansion and long-term offtake agreements represent the dominant competitive moves as spot purchasing declines among Tier 1 aerospace suppliers.
Among integrated titanium producers, ATI and OSAKA Titanium Technologies occupy positions spanning sponge reduction through powder atomization. Sandvik exemplifies the technology-specialist archetype through plasma atomization leadership for high-purity spherical powder. Kymera International represents the cost-positioned tier, specializing in hydride-dehydride processing for metal injection molding and thermal spray applications outside aerospace premium pricing.
| Leading Market Players |
|---|
| ADMA Products |
| ATI |
| Sandvik |
| ECKART |
| Kymera International |
| MEPCO |
| AP&C |
| OSAKA Titanium Technologies |
| Tronox |
| Others |
Cost & Logistics Intelligence
Defense prime captive supply agreements and sovereign-backed sponge producers anchor pricing discipline across titanium powder tiers. Long-term offtake contracts between ATI and Pentagon programs displace spot purchasing, compressing margin volatility for qualified feedstock while hydride processors compete on cost outside aerospace channels.
Pricing Analysis
Distributor margins collapse for plasma atomized spherical powder as defense primes contract directly with atomizers, eliminating intermediary markups. Three-tier pricing structure across plasma atomized premium, gas atomized standard, and hydride economy levels stratifies by oxygen content and flowability certification. Cost compression in hydride segments intensifies because Chinese sponge oversupply feeds irregular powder merchants. Metal injection molding buyers in automotive tooling exhibit highest price sensitivity; space launch providers show least sensitivity due to qualification lock-in.
Supply Chain Analysis
Inert gas freight costs from Ukrainian and Russian argon sources disrupted plasma atomization economics during semiconductor manufacturing demand spikes. Supply concentrates in the United States, China, and Japan for sponge reduction and atomization capacity. Feedstock draws from Kroll process sponge, high-purity argon, and alloying elements aluminum and vanadium. Single-source vulnerability runs through Ukrainian argon corridors before Russia's invasion rerouted flows. Distribution runs through direct defense prime contracts for qualified powder and merchant distributors for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium powder functions as a stable compounder anchored by defense procurement mandates that insulate qualified suppliers from demand cyclicality. FAA certification pathway maturation for additively manufactured parts sustains premium pricing durability across the projection horizon.
For Market Incumbents: Hedge argon supply exposure through long-term gas purchase agreements or captive recycling infrastructure. Lock in multi-year sponge supply with Russian and Ukrainian alternative sourcing as geopolitical risk persists. Reinforce qualification moats by investing in real-time oxygen monitoring for powder reuse protocols that exceed Ti-6Al-4V limits. For New Entrants and Emerging Players: India's PLI scheme for aerospace and defense manufacturing opens a window for atomization capacity buildout near Bangalore industrial clusters. Target medical implant qualification in Germany and Switzerland where REACH registration barriers constrain non-EU competition. Pursue hydride-dehydride cost positioning for metal injection molding markets outside aerospace premium capture. For Investors and Strategic Acquirers: Valuations sit cheapest among hydride processors lacking aerospace qualification pathways. Five-to-ten year viability favors integrated sponge-to-powder producers with defense prime relationships. Monitor FAA airworthiness certification batch approvals as inflection signal for qualified capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sponge Supply | ATI's captive Kroll reduction secures feedstock for F-35 powder contracts. |
| Plasma Atomization Capacity Expansion | Sandvik's rotating electrode investment serves SpaceX rocket engine demand. |
| REACH Registration Partnership | AP&C's ECHA dossier filing unlocks EU medical implant supply chains. |
| Hydride-Dehydride Cost Positioning | Kymera's irregular powder captures metal injection molding volume outside aerospace. |
| Long-Term Defense Offtake Agreement | Howmet's multi-year bomber program commitment displaces spot purchasing risk. |
Research Approach
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market cluster. Primary interviews combined powder metallurgy executives at ATI and Sandvik, defense procurement officers at Pentagon program offices, and medical device quality managers at German orthopedic manufacturers. Secondary validation drew from FAA airworthiness directives, ECHA REACH substance dossiers, MIIT titanium alloy standards, and SEC filings from integrated titanium producers. Bottom-up atomization capacity estimates triangulated against top-down aerospace demand projections.
Rate-of-change decomposition separates volume growth from price mix effects across the analysis window. Segmentation dimensions modeled include atomization technology, alloy grade tier, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to defense procurement cycle visibility and medical implant qualification timelines. Forecast inputs incorporated SpaceX and Blue Origin rocket production schedules alongside Indian PLI scheme capacity buildout assumptions.
Revisions become necessary when FAA certification timelines accelerate or stall, argon supply disruptions persist beyond rerouting adjustments, or REACH enforcement tightens on powder import documentation. Forecasts reflect assumptions about defense budget continuity and additive manufacturing adoption curves in commercial aerospace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Expanded Metal Foils Market
Metals
Global Titanium Metal Market
Metals
Refined Nickel Market
Metals
Platinum Compounds Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Medical Metal Tubing Market
Metals
Lithium Foil Market
Metals
High Purity Iron Powder Market
Metals
Brazing Strips Market
Metals
Stainless Steel Round Bar Market
Metals
Titanium Market
Metals
Industrial Silver Market
Metals
US Metal Fabrication Market
Metals
Aluminum Welding Market
Metals
India Steel Market
Metals
Global High Purity Titanium Powder Market