
 Thermal Paper Market | 2026-2036
Thermal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Paper Market Analysis
Chemical engineering talent specializing in leuco-dye formulation is bifurcating the competitive landscape, separating legacy producers from next-generation coating innovators. Appvion leverages its integrated pulp-to-coating infrastructure to sustain cost discipline across North American supply chains. Koehler Paper SE anchors European production with thermal coating R&D concentrated at its Kehl facility. Mitsubishi Paper Mills dominates Asian specialty grades through precision control over microcapsule dispersion technology.
Thermal paper comprises a base substrate impregnated or coated with a colorless dye precursor and a developer that react under controlled heat to produce visible marks without ink ribbons, typically operating at activation temperatures between 70°C and 90°C. Direct thermal grades lead transaction receipt volumes due to minimal hardware requirements and single-ply simplicity, while specialty coatings command margin pools in medical imaging and airline baggage tags where archival stability and chemical resistance justify premium positioning. Thermal transfer segments compete in barcode labeling where durability demands exceed the fade tolerance of direct thermal outputs.
REACH restrictions on BPA-containing thermal coatings in Europe and parallel FDA guidance on food-contact paper safety in the United States are accelerating reformulation timelines and tightening supplier qualification protocols. China's GB standards for paper product safety and Japan's JIS specifications for thermal recording materials add further compliance layers for exporters serving multiple jurisdictions. Stakeholders must monitor phenol-free developer patent landscapes and regional certification lag times to avoid supply disruptions during coating chemistry transitions.
Market Dynamics
Formulation chemistry transitions are fragmenting supplier tiers as REACH BPA restrictions and state-level US mandates force coating line reinvestment, separating phenol-free capable mills from legacy operations facing qualification exclusion.
Growth Catalysts
- E-commerce logistics expansion:Parcel sortation and last-mile delivery hubs in China are scaling automated label printing infrastructure, sustaining thermal roll consumption even as physical retail receipt volumes plateau.
- REACH BPA-free mandates:European retailers are accelerating supplier requalification toward phenol-free developer systems, creating replacement demand cycles across existing installed base hardware.
- Leuco-dye formulation advances:Next-generation color stability chemistry is extending archival life in medical imaging and airline baggage applications, opening premium grade segments beyond transactional receipts.
Market Restraints
- Crude oil derivative volatility:Bisphenol-A and phenol-free developer feedstocks track petrochemical indices, compressing coating margin predictability for non-integrated producers.
- China supply concentration:Domestic paper machine upgrades at Shandong and Zhejiang mills have consolidated regional substrate supply, creating single-source vulnerability for European and North American converters.
- Digital receipt substitution:QR-code and app-based proof-of-purchase systems at quick-service restaurants and fuel retailers are eroding low-denomination transaction roll demand in urban markets.
Strategic Opportunities
- India organized retail penetration:Modern trade expansion in tier-two cities is installing POS infrastructure faster than digital payment saturation, sustaining thermal receipt demand growth.
- GB standards compliance exports:Mills achieving dual REACH-China safety certification are capturing requalification windows as multinational brands harmonize supplier pools.
- Smart label integration:RFID inlay lamination with thermal printable facestocks is converging track-and-trace requirements with legacy barcode infrastructure in pharmaceutical cold chain.
Industry Challenges
- Coating chemist scarcity:Leuco-dye microencapsulation expertise concentrates at Kehl, Oji, and select Chinese R&D facilities, constraining formulation talent mobility.
- Dual certification timelines:Parallel FDA food-contact and ECHA REACH dossier preparation extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Paper Market |
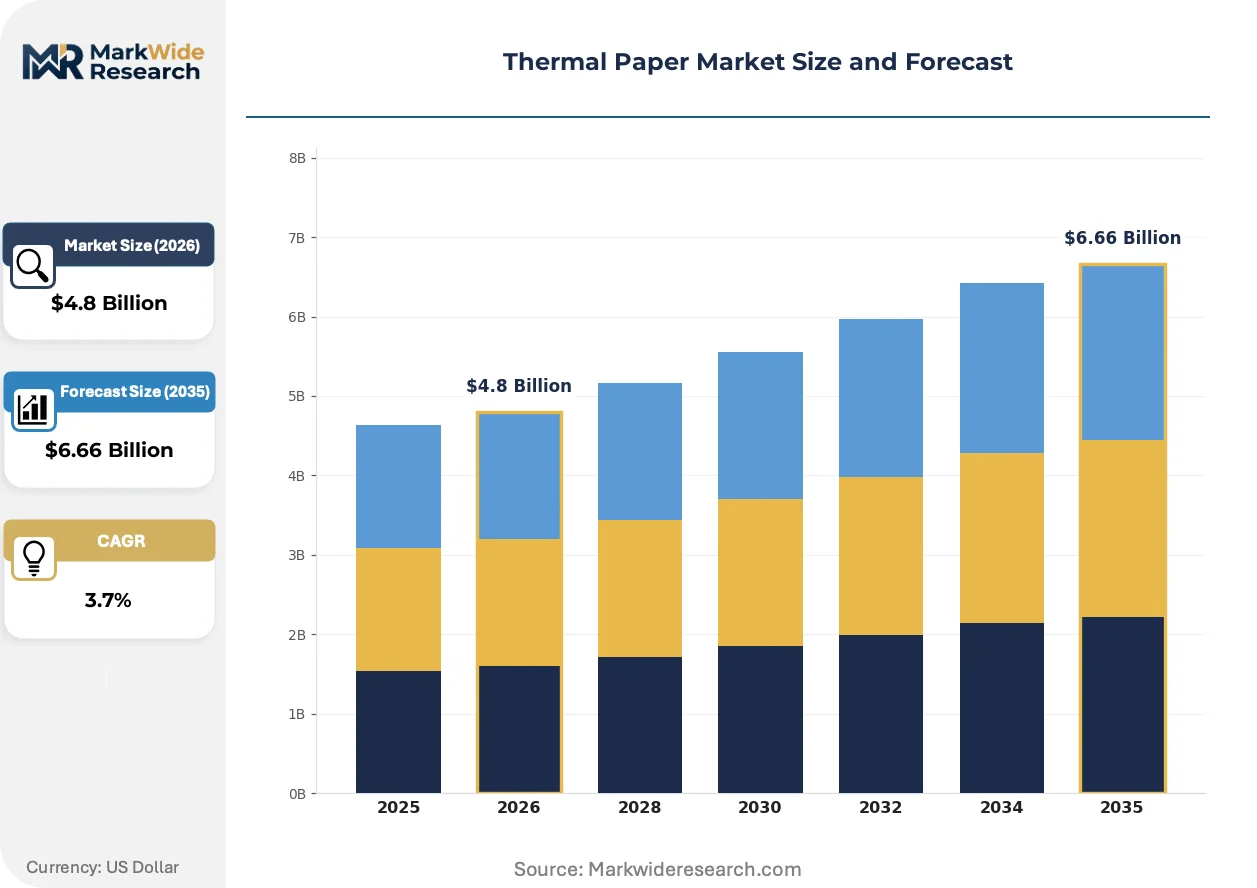
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal, Thermal Transfer, Specialty, Custom End User: Retail, Healthcare, Transportation, Entertainment Thickness: 70 gsm, 80 gsm, 100 gsm, 120 gsm Coating Type: Single Coated, Double Coated, Non-coated, Heat Sensitive |
| Companies Covered | Appvion, Hansol Paper Co. Ltd., Koehler Paper SE, Mitsubishi Paper Mills, Oji Holdings Corporation, Domtar Corporation, Lecta, Jujo Thermal Ltd., Kanzaki Specialty Papers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Paper Market Emerging Trajectories
Phenol-free developer systems are catalyzing coating line reinvestment across three continents, while microcapsule dispersion precision and substrate thermal sensitivity tuning define next-generation competitive capability.
Phenol-free bisphenol-S and Pergafast developer alternatives are supplanting legacy BPA coatings in European and North American receipt grades. Quick-service restaurant chains and grocery retailers are mandating phenol-free specifications in new equipment tenders. This chemistry transition is compressing qualification timelines and favoring integrated pulp-to-coating mills with captive R&D capacity over merchant coating operations.
REACH authorization requirements for BPA in thermal paper entered full enforcement in January 2020, with ECHA monitoring downstream compliance through SCIP database filings. Coating facilities without phenol-free process validation face supply exclusion from EU retail supply chains. German and French retail consortiums are now requiring batch-level migration testing documentation, extending supplier audit burdens.
Consolidated buying at multinational quick-service and fuel retail chains is compressing vendor panels toward dual-qualified phenol-free suppliers with continental logistics coverage. Regional converters with single-technology coating lines are losing shelf position to integrated mills offering REACH-FDA-GB triple certification. This procurement consolidation is most visible in North American and Western European contract renewals, where three-year agreements now specify chemistry compliance milestones.
Thermal Paper Market Segmentation
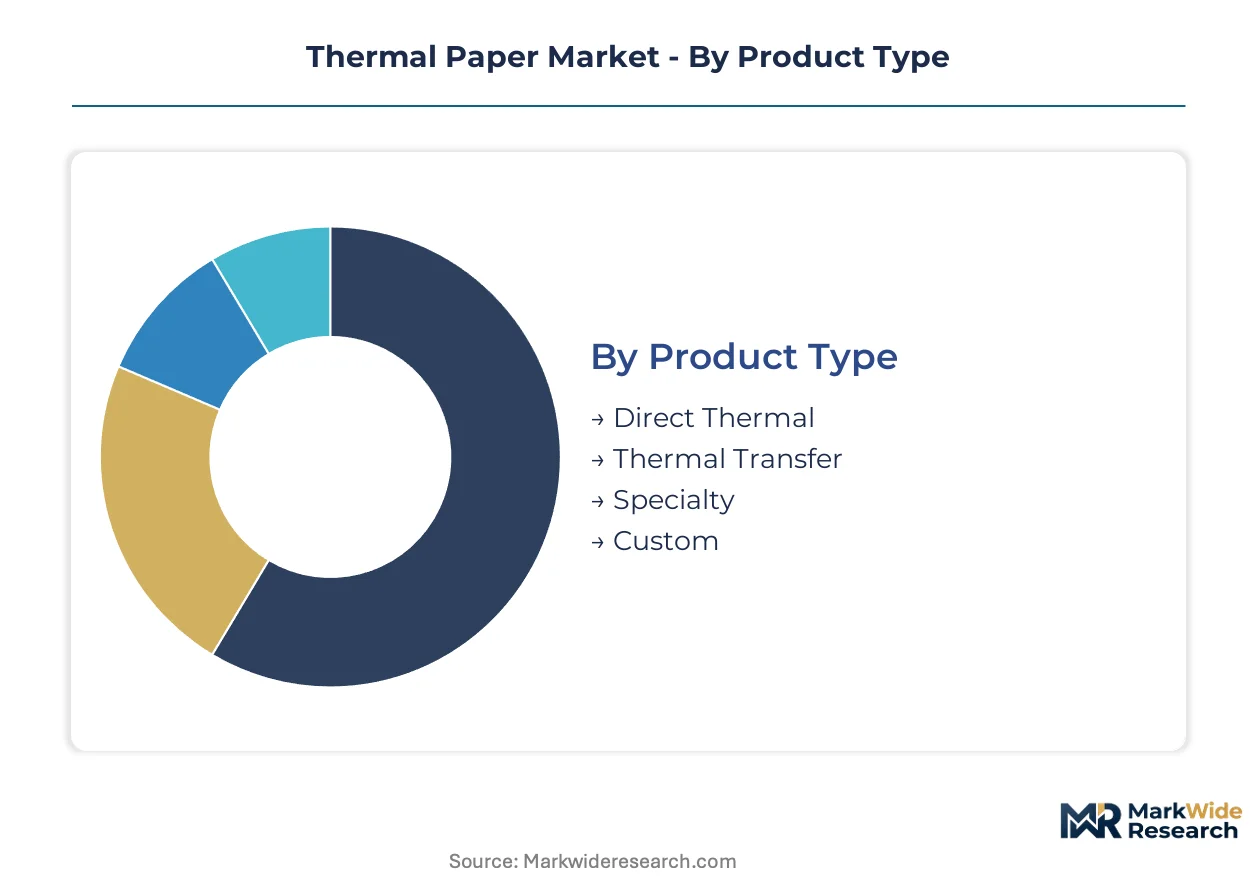
Thermal paper segmentation reveals distinct margin pools and qualification barriers across chemistry grades and end-use specifications. Channel access varies sharply by product type and coating compliance, separating integrated mills from merchant converters.
Product Type:
Direct thermal grades flow through high-volume POS equipment distributors, while specialty and custom grades reach end-users via certified converter networks with formulation documentation.
- Direct Thermal:Single-ply substrates with leuco-dye and developer layers activated at 70°C–90°C without ink ribbons. Grocery and convenience retail in the United States and Germany consume the majority of volumes as BPA-free mandates accelerate requalification cycles toward phenol-free alternatives.
- Thermal Transfer:Receptive coatings designed for wax-resin or resin ribbon transfer, competing in barcode labeling where abrasion resistance exceeds direct thermal durability. E-commerce logistics hubs in China are scaling automated sortation infrastructure that sustains ribbon-based printing despite higher hardware costs.
- Specialty:Archival-stable formulations for medical imaging and airline baggage tracking, commanding premium positioning through extended image life and chemical resistance.
- Custom:Application-specific widths, sensitivities, and backcoatings for OEM equipment integrations and private-label retail programs.
By volume, Direct Thermal leads. By growth pace, Specialty is expanding most quickly on medical imaging and cold-chain logistics demand.
End User:
Customer procurement power concentrates at multinational retail and quick-service chains, compressing vendor panels toward triple-certified suppliers with continental logistics coverage.
- Retail:Point-of-sale receipt printing at grocery, convenience, and fuel outlets anchors baseline consumption. European retailers under ECHA REACH enforcement are excluding non-phenol-free suppliers from contract renewals.
- Healthcare:Medical imaging, prescription labeling, and patient wristband applications require FDA food-contact and archival stability certifications. Diagnostic equipment OEMs in Japan specify JIS-compliant thermal recording materials with batch-level migration documentation.
- Transportation:Airline baggage tags, shipping labels, and parcel tracking consume thermal transfer and specialty grades where mechanical abrasion and temperature cycling tolerance justify premium coatings.
- Entertainment:Lottery tickets, event admission, and gaming receipts demand security features including UV fluorescence and thermal-reactive authentication layers.
Retail captures the largest share of roll volume. Healthcare demonstrates the steepest expansion trajectory on diagnostic infrastructure investment and regulatory compliance layering.
Thickness:
Substrate weight selection correlates with print speed, image durability, and equipment feed compatibility across POS and industrial printer installations.
- 70 gsm:Lightweight grades for high-speed receipt printers in quick-service restaurants and fuel retail where transaction speed outweighs archival requirements.
- 80 gsm:Standard POS grade balancing feed reliability and cost, dominating grocery and convenience store installations across North American and European markets.
- 100 gsm:Mid-weight substrates for dual-ply applications and moderate durability labeling in warehouse and logistics environments.
- 120 gsm:Heavyweight grades for airline baggage tags, outdoor labeling, and applications requiring tear resistance and extended image stability.
Eighty gsm leads in absolute roll kilometers consumed. One hundred twenty gsm is climbing the fastest on transportation and industrial labeling specification upgrades.
Coating Type:
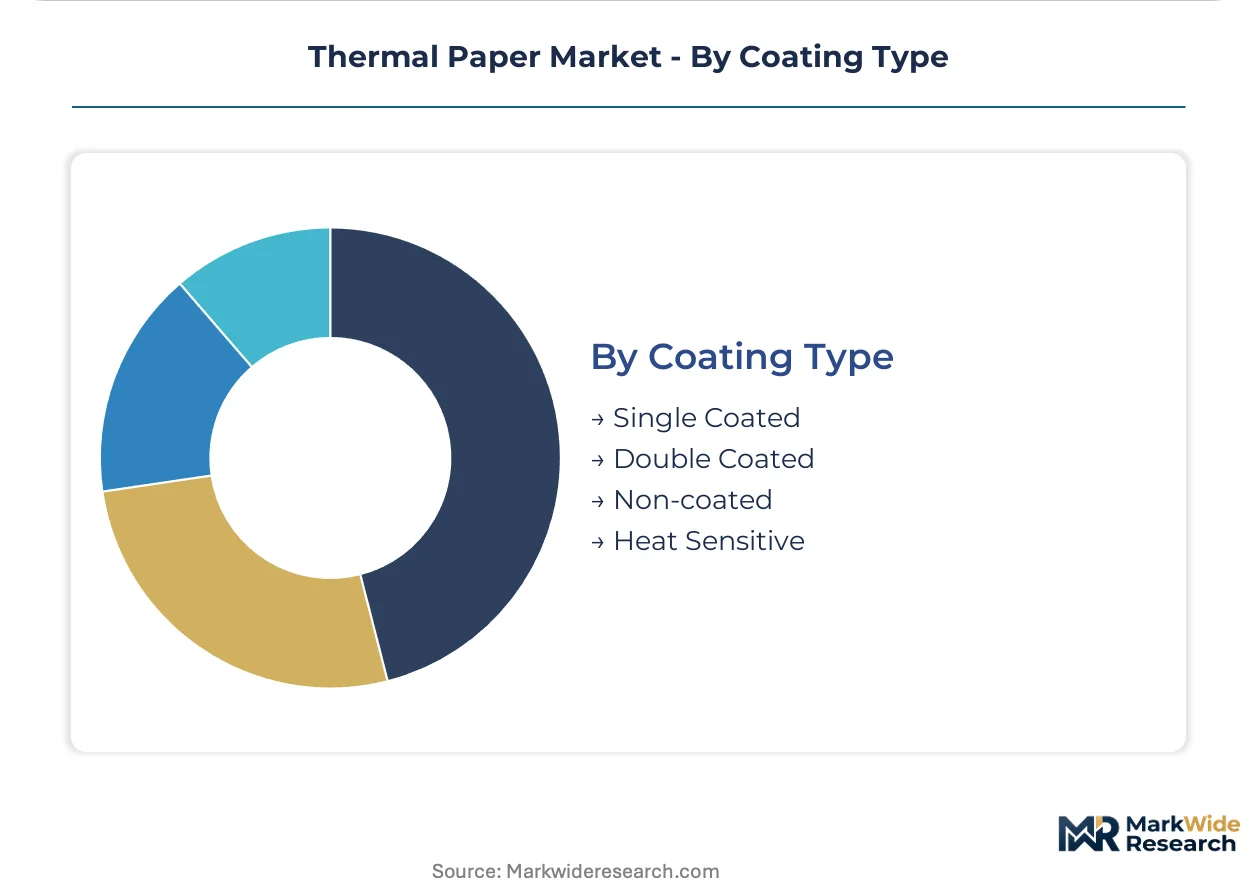
Coating architecture determines chemical compliance pathways, with phenol-free double-coated systems commanding qualification premiums under REACH and state-level U.S. restrictions.
- Single Coated:Developer layer applied to one substrate surface, standard for economy receipt grades in price-sensitive retail segments.
- Double Coated:Separate leuco-dye and developer layers on opposing surfaces, enabling sharper image definition and reduced background discoloration in premium POS and specialty applications.
- Non-coated:Chemically impregnated substrates without surface coating layers, limited to specific legacy equipment and declining in new equipment specifications.
- Heat Sensitive:Substrates with integrated thermal reactivity without discrete coating application, niche applications in security printing and authentication documents.
Single Coated retains volume leadership in emerging markets. Double Coated is gaining share fastest on European phenol-free mandate compliance and image quality specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH enforcement on BPA-containing thermal coatings has restructured procurement patterns across the European Union, with downstream effects rippling through converter networks in North America and Asia.
China
E-commerce logistics hubs in Hangzhou and Shenzhen are scaling automated parcel sortation infrastructure, sustaining thermal label consumption despite physical retail receipt stagnation. GB standards for paper product safety mandate migration testing documentation for all food-contact thermal grades. Shandong and Zhejiang mills are consolidating substrate supply through domestic paper machine upgrades, capturing regional converter demand.
Germany
Quick-service restaurant chains and grocery retail consortiums are mandating phenol-free developer specifications in equipment tenders, accelerating coating line reinvestment. ECHA REACH authorization requirements entered full enforcement with SCIP database monitoring of downstream compliance. The Kehl facility anchors European thermal coating R&D, concentrating leuco-dye formulation expertise for medical imaging and airline baggage applications.
United States
FDA guidance on food-contact paper safety is tightening supplier qualification protocols for receipt grades used in quick-service and fuel retail. State-level BPA restrictions in California and New York are redirecting formulation investments toward phenol-free alternatives. Appvion leverages integrated pulp-to-coating infrastructure across North American supply chains to sustain cost discipline during chemistry transitions.
Japan
Diagnostic equipment OEMs specify JIS-compliant thermal recording materials with batch-level migration documentation for medical imaging applications. METI standards for chemical substance management layer additional compliance requirements on coating facilities serving pharmaceutical and healthcare end-users. Mitsubishi Paper Mills dominates specialty grade production through precision control over microcapsule dispersion technology at domestic facilities.
India
Modern trade expansion in tier-two cities is installing POS infrastructure faster than digital payment saturation, sustaining thermal receipt demand growth. BIS certification requirements for paper product safety are harmonizing with multinational brand supplier qualification standards. Maharashtra and Gujarat retail clusters are driving specification upgrades toward phenol-free grades as organized retail penetration deepens.
Thermal Paper Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in thermal paper manufacturing. The upper tier controls captive pulp supply and in-house coating R&D, while merchant converters rely on external substrate sourcing. Three archetypes define competitive positioning: integrated pulp-to-coating mills with phenol-free process validation; specialty grade specialists concentrating microencapsulation expertise; and regional converters serving price-sensitive emerging markets. Capacity expansion and chemistry transition partnerships represent the dominant competitive moves as qualification timelines compress under regulatory pressure.
Within the integrated mill tier, Appvion and Koehler Paper SE exemplify backward integration strategies that anchor cost structures during feedstock volatility. Mitsubishi Paper Mills occupies a position among specialty grade innovators where microcapsule dispersion precision commands premium positioning. Hansol Paper Co. Ltd. represents the Asian manufacturing scale archetype, with Korean industrial paper production concentrated around chemical coating expertise and export-oriented logistics infrastructure.
| Leading Market Players |
|---|
| Appvion |
| Hansol Paper Co. Ltd. |
| Koehler Paper SE |
| Mitsubishi Paper Mills |
| Oji Holdings Corporation |
| Domtar Corporation |
| Lecta |
| Jujo Thermal Ltd. |
| Kanzaki Specialty Papers Inc. |
| Others |
Supply Flow & Price Mechanics
Paper machine capacity utilization at Shandong and Zhejiang mills shapes both regional supply concentration and transoceanic price floors, with integrated coating operations commanding premium positioning over merchant converters dependent on spot substrate markets.
Pricing Analysis
Chinese domestic pricing for direct thermal substrates runs 15-20 percent below landed European equivalents, compressing margin pools for non-integrated Western converters. Three-tier pricing structure across phenol-free certified, legacy BPA-compliant, and economy non-food-contact grades separates qualification-burdened medical imaging rolls from commodity receipt stock. Cost compression in standard POS grades is intensifying because Shandong mills are absorbing leuco-dye formulation capabilities previously sourced from Japanese specialty chemical houses. Quick-service restaurant procurement teams demonstrate highest price sensitivity, while diagnostic equipment OEMs in Japan exhibit lowest sensitivity due to JIS certification lock-in.
Supply Chain Analysis
Bisphenol-A and phenol-free developer feedstock transit through Rotterdam and Singapore petrochemical hubs creates coating margin vulnerability when crude derivative indices spike. Substrate supply concentrates in China, Japan, and South Korea, with European and North American converters drawing from Asian base paper imports. Raw material dependencies rest on crude oil derivatives, wood pulp from Nordic and Canadian sources, and microencapsulated leuco-dye concentrates from Kehl and Oji R&D facilities. Single-source vulnerability runs through Shandong mill clusters that consolidated regional capacity through 2020-2024 machine upgrades. Distribution runs through certified converter networks with REACH-FDA-GB triple documentation, bypassing spot merchants in regulated end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal paper coating chemistry transitions are accelerating service-attach revenue from formulation documentation, batch-level migration testing, and hardware recalibration services expanding faster than commoditized roll volume.
For Market Incumbents: Fortify phenol-free process validation at captive R&D facilities to exclude legacy-coated merchant competitors from EU retail contract renewals under ECHA REACH enforcement. Deepen backward integration into leuco-dye microencapsulation to reduce dependency on Kehl and Oji formulation houses. Anchor capacity utilization through long-term coating service agreements with multinational quick-service chains specifying chemistry compliance milestones. For New Entrants and Emerging Players: Dual REACH-China GB certification fast-track positions new coating facilities to capture requalification windows as multinational brands harmonize supplier pools across jurisdictions. Target India's tier-two city modern trade expansion where POS infrastructure installation outpaces digital payment saturation. Pursue pharmaceutical cold chain partnerships combining thermal printable facestocks with RFID inlay lamination as the go-to-market angle. For Investors and Strategic Acquirers: Specialty grade converters with JIS-compliant medical imaging certifications and microcapsule dispersion expertise represent the priority acquisition archetype for premium positioning in diagnostic equipment supply chains. Long-term viability frames around chemistry transition completion rather than substrate scale, with phenol-free formulation IP determining competitive durability. Watch for ECHA SCIP database filing acceleration as the inflection signal indicating downstream compliance pressure intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Phenol-Free Coating Line Reinvestment | ECHA REACH enforcement excludes legacy BPA operations from EU retail procurement panels. |
| Dual Certification Achievement | REACH-GB alignment captures multinational brand supplier harmonization windows. |
| Leuco-Dye Microencapsulation R&D | Precision dispersion technology commands premium positioning in medical imaging grades. |
| Integrated Pulp-to-Coating Expansion | Captive substrate supply anchors cost discipline during petrochemical feedstock volatility. |
| Smart Label Integration Partnership | RFID-thermal convergence addresses pharmaceutical cold chain track-and-trace requirements. |
Methodological Framework
A spread of perspectives from coating chemists at integrated mills, procurement directors at multinational retail chains, thermal printer OEM technical leads, and regulatory affairs specialists at ECHA-notified bodies converged on the working assumptions around phenol-free formulation transition timelines. Primary interview insights combined with secondary validation from ECHA SCIP database filings, FDA food-contact guidance documents, China GB standards publications, and customs trade data tracking substrate flows from Shandong and Zhejiang ports. Bottom-up roll consumption estimates by end-use segment triangulated against top-down coating capacity assessments across Kehl, Oji, and Chinese facilities.
Segmentation dimensions modeled include coating chemistry tier, end-use application, substrate thickness specification, and regional regulatory compliance cluster across the projection horizon. CAGRs derived from equipment installation rates, e-commerce logistics infrastructure scaling, and chemistry transition replacement cycles. Industry-specific forecast inputs incorporated diagnostic imaging equipment shipment data and quick-service restaurant POS hardware refresh schedules.
The analysis sits within stated boundaries; outcomes outside phenol-free formulation cost parity, REACH enforcement intensity, or digital receipt substitution rates would require recalibration. Forecasts reflect assumptions around coating line reinvestment completion and supplier qualification timeline compression. Revision becomes warranted when BPA-free developer patent litigation or Chinese environmental enforcement crosses thresholds altering substrate supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Leatheroid Paper Market
Paper Products
Metallized Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Recording Chart Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Paper Making Machine Market
Paper Products
Graphic Paper Market
Paper Products
Wood-Based Panel Market
Paper Products
Clay Coated Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
NCR Laser Paper Market
Paper Products
Decor Paper Market