
 Global Polyurethane Screen Panels Market | 2026-2036
Global Polyurethane Screen Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyurethane Screen Panels Market Intelligence
A shift from traditional mining separation toward waste recycling applications is rebalancing the end-user portfolio for polyurethane screen panel manufacturers. Metso Outotec leverages its extensive installed base in the mining sector to maintain a strong market position. Sandvik AB competes on the basis of integrated screening solutions and material science expertise. Meanwhile, Trelleborg AB differentiates through its focus on customized polymer engineering for high-wear environments.
Polyurethane screen panels are wear-resistant screening media molded from thermosetting or thermoplastic polyurethane. They feature precisely engineered apertures designed for the efficient classification and separation of bulk materials like minerals, aggregates, and recycled waste. Modular panels represent the largest product category, offering operational flexibility and simplified replacement for end users in mining and construction. Within material compositions, reinforced polyurethane is gaining share due to its superior tensile strength and resistance to high-impact loads in quarry screening.
Worker safety standards, such as those enforced by the US Occupational Safety and Health Administration (OSHA), influence panel design to reduce noise and dust exposure. Material composition is governed by regulations like Europe's REACH, which restricts certain chemical substances used in polyurethane production. In China, environmental directives from the Ministry of Ecology and Environment (MEE) promote the use of durable screens to minimize industrial waste. Supplier selection will increasingly hinge on demonstrating compliance with these varied international standards and proving material longevity.
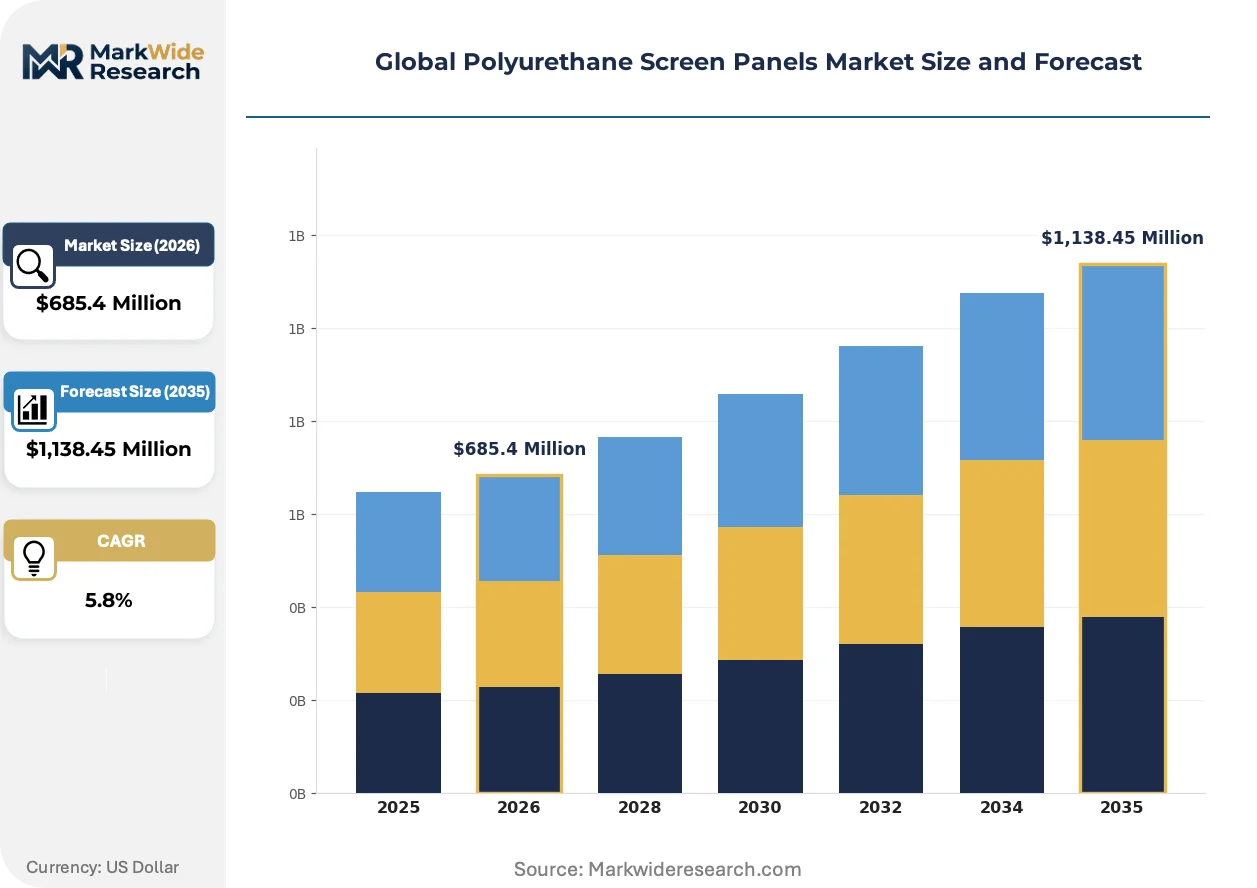
Market Dynamics
The convergence of stringent environmental regulations and the operational demands of emerging end-uses like waste recycling is fundamentally altering material science requirements and competitive benchmarks for polyurethane screen panel manufacturers.
Growth Catalysts
- Waste Recycling Expansion:Growth in municipal solid waste and construction demolition waste recycling facilities creates consistent demand for durable, high-efficiency sorting media capable of handling diverse and abrasive feed materials.
- Regulatory Mandates for Durability:Environmental directives, such as those from China's Ministry of Ecology and Environment (MEE), promote the use of longer-lasting industrial components to minimize landfill waste, favoring robust polyurethane panels.
- Australian Mining Sector:The extensive scale of mining and aggregates processing in Australia continues to drive demand for high-performance screen panels that can withstand harsh conditions and maximize operational uptime in remote locations.
Market Restraints
- Raw Material Price Volatility:The cost of polyurethane precursors, such as MDI and polyols, is closely linked to fluctuating petrochemical prices, which introduces cost uncertainty and margin pressure for panel manufacturers.
- Substitution from Alternative Media:In certain applications, particularly for fine screening or lower-impact processes, polyurethane panels face competition from lower-cost alternatives like high-tensile woven wire or rubber screens.
- Chemical Regulation Compliance:Adherence to chemical safety regulations like Europe's REACH framework adds complexity and cost to product development and manufacturing, restricting the use of certain performance-enhancing additives.
Strategic Opportunities
- Urban Mining Applications:Developing specialized screen panels for urban mining, including the recovery of metals from incinerator bottom ash and e-waste, presents a significant growth avenue for material science innovation.
- Smart Panel Integration:Embedding sensors within polyurethane panels for real-time wear monitoring and predictive maintenance offers a new service-based model and a strong differentiator in a component-focused market.
- Southeast Asian Infrastructure Growth:Expansion into developing markets in Southeast Asia, where major infrastructure and mining projects are underway, provides an opportunity to displace traditional screening media with more efficient polyurethane solutions.
Industry Challenges
- Manufacturing Customization Strain:The demand for application-specific, custom-molded panels creates significant operational complexity, straining production scheduling and engineering resources for manufacturers of all sizes.
- Multi-Jurisdictional Compliance:Navigating and documenting compliance with a patchwork of international standards, from US OSHA worker safety rules to European environmental laws, requires substantial administrative investment and expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyurethane Screen Panels Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibrating Panels, Fixed Panels, Mobile Panels, Modular Panels Application: Mining Separation, Quarry Screening, Waste Recycling, Aggregates Sorting, Biomass Processing Material Composition: Thermoplastic Polyurethane, Thermosetting Polyurethane, Reinforced Polyurethane, High-Density Polyurethane End User Industry: Mining Companies, Construction Firms, Recycling Facilities, Agriculture Processors |
| Companies Covered | Derrick Corporation, MAJOR Wire Industries, Trelleborg AB, Eurogomma, ASGCO, Metso Outotec, GKD Group, TEMA ISENMANN, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyurethane Screen Panels Market Strategic Shifts & Innovations
Material science advancements are converging with digital monitoring capabilities, pushing polyurethane screen panels beyond simple wear parts toward becoming intelligent components within a connected processing plant. This evolution prioritizes total system efficiency over individual component cost.
Reinforced polyurethane composites, which embed materials like steel or advanced polymers, provide superior tensile strength and impact resistance. These composites are being rapidly adopted in primary screening stages within hard rock quarrying and aggregates processing. This advanced material is absorbing the high-impact stress that previously caused premature failure in standard panels, thereby extending replacement cycles and reducing operational downtime.
Worker safety mandates, such as noise exposure limits set by the US Occupational Safety and Health Administration (OSHA), are influencing panel design. This pressure leads manufacturers to engineer panels with specific durometers and compositions that dampen noise during operation compared to metallic screens. The mining and enclosed-space recycling sectors are most affected, prioritizing noise-reducing polyurethane formulations to improve workplace conditions.
End-users are increasingly evaluating screen panels not as standalone components but as integral parts of a complete screening system's performance and total cost of ownership. This shift disrupts the traditional price-per-panel procurement model, favoring suppliers who can demonstrate efficiency gains through material science. This trend is most visible in large-scale mining operations where equipment downtime carries significant financial penalties.
Global Polyurethane Screen Panels Market Segmentation
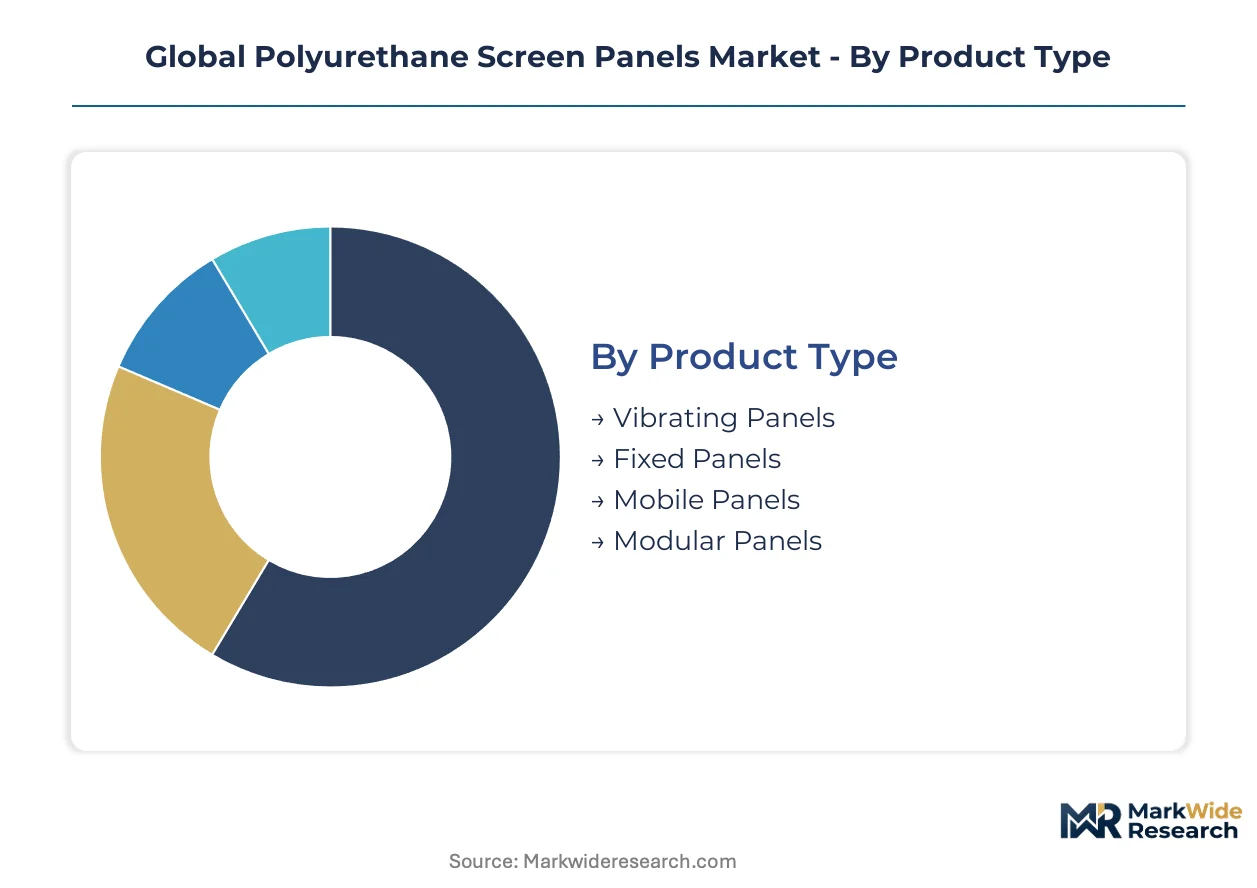
The polyurethane screen panels market is segmented to provide a granular understanding of product variations, application demands, material advancements, and end-user requirements. Analyzing these distinct segments helps manufacturers tailor product development and market strategies to specific operational needs and evolving industry trends.
Product Type:
Product type segmentation reveals how volume and premium offerings shape competitive positioning across different screening solutions.
- Modular Panels:These panels feature standardized dimensions and interlocking designs, allowing for easy installation and replacement in various screening equipment. Their operational flexibility and reduced downtime make them highly sought after in large-scale mining operations and construction aggregate processing across Australia.
- Vibrating Panels:Engineered for high-frequency screening, these panels are designed to withstand constant vibration and abrasive material flow, often incorporating specific aperture designs for fine material separation. Demand for these panels is concentrating in waste recycling facilities requiring efficient separation of diverse feed materials.
- Fixed Panels:These robust, non-moving panels are typically used in static screening applications where material flow is consistent and less aggressive, often found in smaller-scale aggregates plants.
- Mobile Panels:Designed for portable screening plants, these panels offer flexibility for on-site processing in construction and quarrying, catering to projects with varying locations.
Today's leader: Modular Panels. Tomorrow's challenger: Vibrating Panels.
Application:
Application demands dictate specific performance characteristics, influencing material selection and panel design for diverse industrial processes.
- Waste Recycling:Panels in this application handle highly abrasive and diverse materials, requiring superior wear resistance and precise aperture sizes for efficient municipal solid waste and construction demolition waste sorting. Europe's circular economy directives are driving significant investment in these specialized solutions.
- Mining Separation:Utilized in mineral processing, these panels endure extreme impact and abrasion from ore and rock, necessitating robust construction and optimal open area for high throughput. Major mining companies in Canada and South Africa depend on these panels for primary and secondary screening.
- Quarry Screening:Panels for quarry operations separate crushed rock and aggregates by size, demanding durability against heavy impact and consistent performance to meet construction material specifications.
- Aggregates Sorting:This segment involves classifying sand, gravel, and crushed stone for construction and road building, requiring panels that maintain aperture integrity under continuous abrasive flow.
- Biomass Processing:Screens in biomass applications separate organic materials like wood chips or agricultural waste, needing resistance to organic acids and consistent sizing for fuel or compost production.
The largest application segment remains Mining Separation, while Waste Recycling exhibits the steepest expansion trajectory.
Material Composition:
Material properties define the durability, flexibility, and wear resistance of screen panels, driving differentiation across various operational environments.
- Reinforced Polyurethane:These composites embed materials like steel or advanced polymers, providing superior tensile strength and impact resistance crucial for primary screening stages in hard rock quarrying. This composition absorbs high-impact stress, extending panel lifespan in demanding environments.
- Thermosetting Polyurethane:Characterized by irreversible chemical bonds, these panels offer excellent heat resistance and rigidity, making them suitable for heavy-duty applications where structural integrity is paramount. Mining operations in remote regions often rely on their consistent performance.
- Thermoplastic Polyurethane:Offering greater flexibility and recyclability, these panels are often used in lighter-duty applications or where specific vibration dampening properties are required.
- High-Density Polyurethane:This formulation provides enhanced abrasion resistance and structural integrity, extending service life in applications with high wear rates, such as abrasive aggregates sorting.
The most established material composition is Thermosetting Polyurethane, with Reinforced Polyurethane rapidly gaining market share.
End User Industry:
End-user industry requirements shape the functional specifications of polyurethane screen panels, aligning product features with specific operational demands and regulatory landscapes.
- Recycling Facilities:These facilities demand panels capable of efficiently separating diverse and often contaminated waste streams, requiring high wear resistance and specific aperture designs for material recovery. Environmental directives from China's MEE promote durable screens in these operations.
- Mining Companies:As major consumers, mining companies require extremely robust and durable panels that can withstand harsh conditions, minimize downtime, and maximize operational uptime in large-scale mineral processing. Metso Outotec maintains a strong market position serving this sector.
- Construction Firms:Used for screening aggregates, sand, and gravel, these firms prioritize panels that offer consistent sizing and durability for various building materials.
- Agriculture Processors:This segment utilizes panels for separating grains, seeds, and other agricultural products, requiring precise sizing and resistance to organic materials.
Mining Companies constitute the largest end-user group, while Recycling Facilities are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Varying environmental and safety standards influence manufacturing locations and material sourcing for polyurethane screen panels. This creates cost-of-compliance gaps and opportunities for regulatory arbitrage across different regions, impacting global supply chain configurations. Demand drivers for these panels differ significantly by geography.
United States
Demand for polyurethane screen panels in the United States stems from robust construction activity and expanding waste recycling operations. OSHA worker safety standards influence panel design, prioritizing noise reduction and dust suppression in screening equipment. Manufacturing clusters in the Midwest, particularly around states like Illinois and Ohio, serve as key production centers for industrial components and machinery.
Australia
Australia's extensive mining and aggregates processing operations drive consistent demand for high-performance screen panels. Strict mining safety regulations, enforced by state authorities, necessitate durable materials that minimize operational downtime in harsh conditions. The Perth region, a hub for mining equipment and services, sees significant procurement activity for advanced screening solutions.
China
China's rapid infrastructure development and growing emphasis on circular economy initiatives fuel demand for durable screening media in waste recycling and construction. Environmental directives from the Ministry of Ecology and Environment (MEE) promote longer-lasting industrial components to reduce waste generation. The Yangtze River Delta region, a major industrial and manufacturing zone, hosts numerous producers and consumers of polyurethane panels.
Germany
Germany represents a significant market due to its advanced manufacturing base and commitment to high-efficiency recycling. Europe's REACH framework governs chemical substances used in polyurethane production, influencing material composition and product development. The Ruhr region, historically an industrial powerhouse, continues to be a center for heavy industry and materials science innovation, including specialized screening solutions.
Global Polyurethane Screen Panels Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the polyurethane screen panels market. The market exhibits a tiered structure, with established global players competing alongside regional manufacturers and specialized material science firms. Integrated solutions providers represent one strategic archetype, while another focuses on customized polymer engineering for high-wear applications. Companies pursue strategic partnerships for technology co-development and geographic expansion into emerging markets.
Metso Outotec, a Finnish company, and Sandvik AB, a Swedish industrial group, represent integrated solutions providers with extensive installed bases in mining and aggregates processing. Trelleborg AB, another Swedish company, exemplifies a specialist in polymer engineering, focusing on customized solutions for high-wear environments. These companies anchor different segments of the market through their distinct product and service offerings.
| Leading Market Players |
|---|
| Derrick Corporation |
| MAJOR Wire Industries |
| Trelleborg AB |
| Eurogomma |
| ASGCO |
| Metso Outotec |
| GKD Group |
| TEMA ISENMANN |
| Sandvik AB |
| Others |
Cost & Logistics Intelligence
Skilled labor concentrations in specialized molding and polymer engineering facilities, particularly in Germany and the US, drive higher pricing tiers for custom polyurethane screen panels. These regional labor-cost differentials directly influence the premium charged for advanced material compositions.
Pricing Analysis
Direct-to-OEM discounts are common for large-volume purchases by mining companies and construction firms. The dominant pricing model remains per-unit transactional, with long-term contracts securing stable supply. Price differentiation stems from panel customization levels and the integration of advanced features like embedded sensors. Pricing softness reflects competition from lower-cost alternative screening media. Waste recycling facilities, driven by budget constraints, represent the most price-sensitive buyer segment.
Supply Chain Analysis
Environmental directives from China's MEE and Europe's REACH framework reshape sourcing decisions for polyurethane precursors. Geographic supply concentration for MDI and polyols centers heavily in China and the Middle East, drawing from petrochemical production hubs. Single-source vulnerability for specialized additives presents a structural risk to manufacturers. Distribution runs through a hybrid model, combining direct sales to large end-users with regional distributor networks for smaller construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market acts as a regulatory compounder, with environmental directives from China's Ministry of Ecology and Environment promoting longer-lasting industrial components. These mandates actively accelerate demand for durable polyurethane screen panels.
For Market Incumbents: To counter raw material price volatility, incumbents like Metso Outotec should deepen backward integration into specialized polyurethane precursor production. Investing in advanced material science R&D for reinforced composites offers a lever to differentiate against lower-cost alternatives. Expanding service contracts that include predictive maintenance for smart panels reinforces customer loyalty and captures aftermarket value.
For New Entrants and Emerging Players: Enter via specialized niches such as urban mining applications, focusing on e-waste or incinerator bottom ash recovery. The waste recycling segment, with its expanding infrastructure in Europe, presents the most penetrable geography due to specific regulatory drivers. A go-to-market angle centered on custom polymer engineering for challenging separation tasks can differentiate offerings.
For Investors and Strategic Acquirers: Integrated solutions providers like Sandvik AB are the most active acquirers in this space, seeking to broaden their screening technology portfolios. Over the next 5-10 years, companies specializing in smart panel integration or advanced composite materials will be attractive targets. The signal to watch is a significant increase in patent filings for sensor-embedded screening media.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Develops next-generation reinforced polyurethane composites for extreme wear applications in hard rock quarrying. |
| Smart Panel Integration | Embeds sensors in panels for real-time wear monitoring, enabling predictive maintenance for mining companies. |
| Geographic Expansion | Targets Southeast Asian infrastructure projects to displace traditional screening media with efficient polyurethane solutions. |
| Waste Recycling Specialization | Designs tailored screening solutions for diverse municipal solid waste and construction demolition waste streams. |
| Sustainability Certification | Obtains certifications like Europe's REACH compliance to meet stringent environmental regulations for polymer production. |
Research Approach
Coverage spans Australia, Europe, North America, and Asia-Pacific, with primary inputs from each major market. This study combined in-depth interviews with industry stakeholders such as plant managers, procurement leads, and R&D directors. Secondary validation drew from technical journals, patent databases, and regulatory filings from US OSHA and Europe's REACH. Bottom-up market sizing was triangulated with top-down validation of overall market demand.
Rate-of-change decomposition modeled market dynamics across the analysis window by product type, application, material composition, and end-user industry. Regional regulatory frameworks, such as China's MEE directives, were also integrated as a key dimension. Compound annual growth rates were derived from historical data trends and projected demand shifts. Key inputs included anticipated infrastructure spending and waste generation volumes.
Inputs from major manufacturers and end-users were available through the study window; gaps in emerging market data introduce uncertainty bands. Forecasts reflect assumptions regarding raw material price stability and global economic growth. Geopolitical shifts or unforeseen regulatory changes could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Industrial Drum Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Paint Knife Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Weatherstrip Seal Market