
 Egypt Construction Chemicals Market | 2026-2036
Egypt Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Construction Chemicals Market Insights
ES 4756-1 cement additive certification is unwinding the competitive set as smaller blenders lose batch-approval privileges. Sika Egypt leverages its Swiss parent lab network to fast-track ES mark renewals. BASF SE anchors its position through captive supply of polycarboxylate ether superplasticizers from its Ludwigshafen base. Dow Chemical Egypt competes on acrylic polymer dispersion consistency for tile adhesive formulations.
Construction chemicals comprise admixtures, protective coatings, bonding agents, and repair mortars formulated with Portland cement, silica fume, and synthetic polymers to modify hydration kinetics, permeability, and mechanical durability in built structures. Polymer-modified systems dominate value pools due to specification premiums on waterproofing and repair jobs across Egypt's coastal and delta zones. Infrastructure application leads volume as the Suez Canal Economic Zone and high-speed rail corridors specify high-performance grouts and fiber-reinforced shotcrete. Water-resistant technology grows fastest among contractors facing Nile Delta water table challenges and Red Sea humidity exposure.
Egypt's Housing and Building National Research Center enforces ES standards that gate admixture imports and local production licenses. The Egyptian Organization for Standardization and Quality aligns with ISO 9001 and ISO 14001 frameworks that multinational suppliers like Mapei Egypt and RPM International Inc. must maintain for public tender eligibility. Stakeholders should monitor how ES 4756-3 testing protocol revisions affect polymer content thresholds and import substitution incentives.
Market Dynamics
ES 4756 certification tightening is restructuring Egypt's construction chemicals competitive landscape by stripping smaller blenders of batch-approval privileges and forcing accelerated reformulation cycles among remaining players.
Growth Catalysts
- New Administrative Capital megaprojects:Greater Cairo's administrative capital development specifies polymer-modified waterproofing at scale, pulling admixture volumes from certified suppliers.
- Suez Canal Economic Zone infrastructure:High-performance grout and fiber-reinforced shotcrete specifications from the zone's engineering authority drive specialty chemical procurement.
- ES mark harmonization with ISO frameworks:Egyptian Organization for Standardization and Quality alignment with ISO 9001 and ISO 14001 enables multinational suppliers to compete for public tenders.
Market Restraints
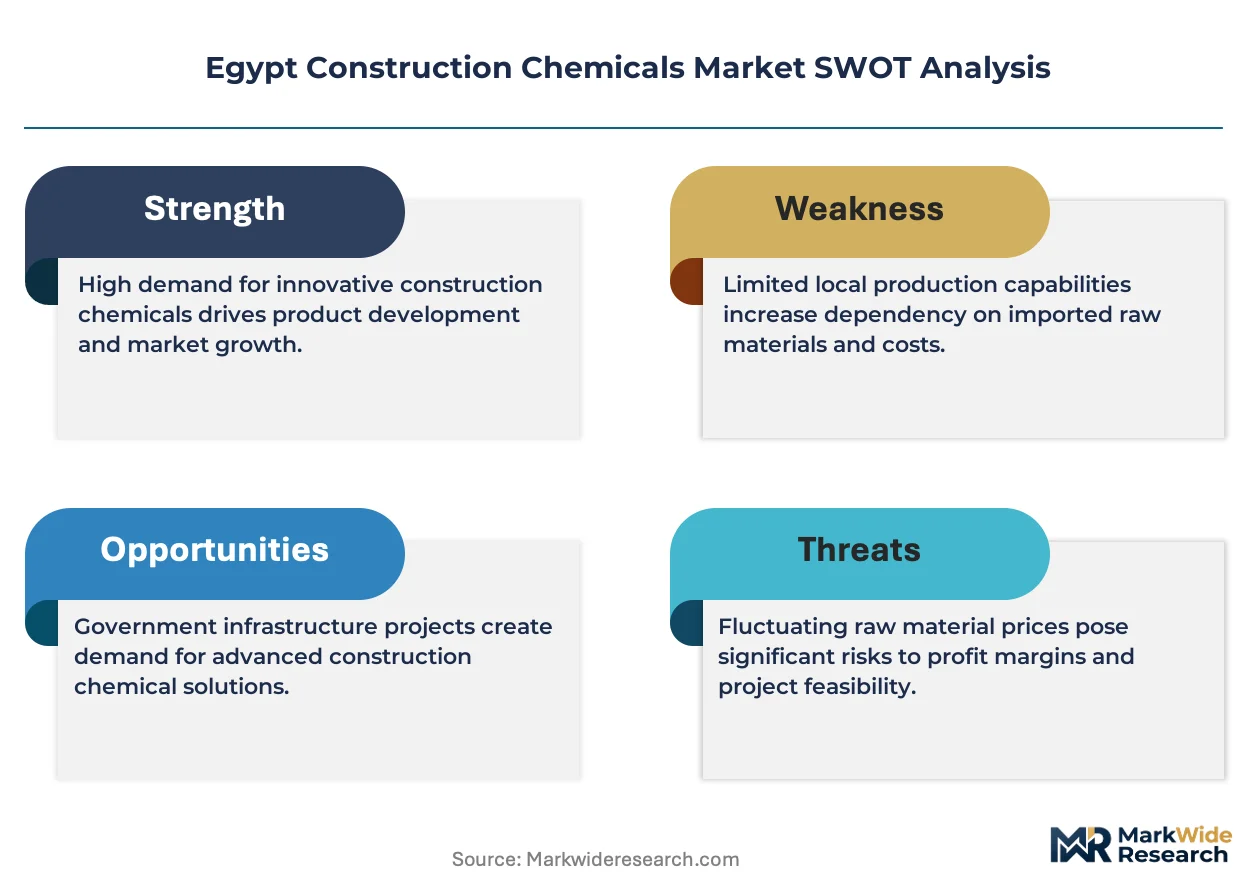
- Petrochemical feedstock volatility:Acrylic monomer and polycarboxylate ether precursor costs fluctuate with naphtha cracking margins, compressing formulation margins for local blenders.
- Import dependency for polymer dispersions:Captive supply from Ludwigshafen and other European production hubs concentrates pricing power with integrated multinationals.
- Nile Delta water table chemistry:High sulfate and chloride content in groundwater limits standard Portland cement modifier efficacy, forcing costly custom formulations.
Strategic Opportunities
- Alexandria port rehabilitation corridors:Maritime infrastructure exposure to Mediterranean humidity creates specification pull for marine-grade protective coatings and cathodic protection systems.
- Red Sea coastal tourism developments:Resort construction along the Red Sea coastline specifies humidity-resistant tile adhesives and sealants with elevated polymer loading.
- ES 4756-3 protocol revision anticipation:Stakeholders pre-positioning reformulated products ahead of polymer content threshold adjustments can capture first-mover certification advantage.
Industry Challenges
- Batch-approval timeline compression:HBRC laboratory testing queues extend certification cycles to 14-18 weeks, delaying commercial launches.
- Polymer dispersion cold-chain integrity:Acrylic emulsion transport from Alexandria port to Upper Egypt project sites requires temperature-controlled logistics investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Construction Chemicals Market |
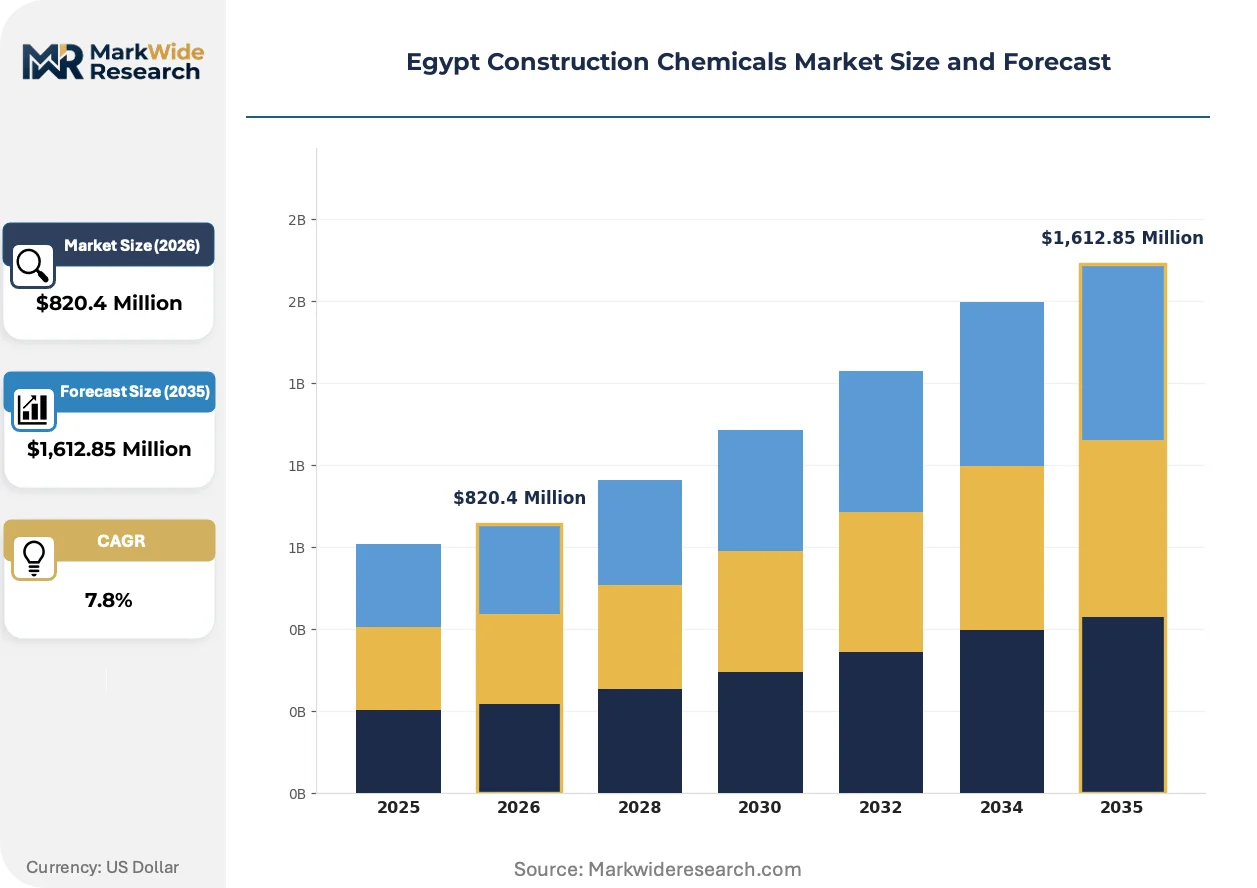
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,612.85 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement Additives, Surface Treatment Solutions, Grouts, Adhesives Application: Infrastructure, Residential, Commercial, Industrial End User: Contractors, Engineers, Architects, Builders Technology: Polymer Modified, Water-Resistant, Self-Leveling, Fiber Reinforced |
| Companies Covered | Dow Chemical Egypt, United Paints and Chemicals Drymix S.A.E, Sika Egypt, Bostik Egypt, NCC X-Calibur, BASF SE, Pidilite Industries Egypt, RPM International Inc., Mapei Egypt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Construction Chemicals Market Trends and Innovations
Reformulation cycles are accelerating across Egypt's construction chemicals sector as certification standards tighten and project specifications demand higher-performance systems. Three interconnected developments are reshaping competitive positioning.
Silica fume-based high-performance concrete admixtures are displacing conventional fly ash extenders in Nile Delta foundation work. Contractors on the high-speed rail corridors specify these systems for sulfate resistance. The shift is compressing volumes for traditional pozzolanic suppliers while rewarding blenders with captive microsilica sourcing.
ES 4756-1 additive certification protocols now require third-party laboratory verification for every reformulated batch. The Housing and Building National Research Center tightened these rules in response to infrastructure failure audits. Multinational suppliers with in-house HBRC-accredited testing facilities are capturing specification share from smaller competitors.
Project developers now unbundle after-sales technical service from material supply contracts. Large residential developers in the New Administrative Capital source chemicals through procurement platforms while hiring independent application consultants. This bifurcation is visible across Greater Cairo's megaproject clusters where developer procurement teams separate product specification from installation supervision.
Egypt Construction Chemicals Market Segmentation
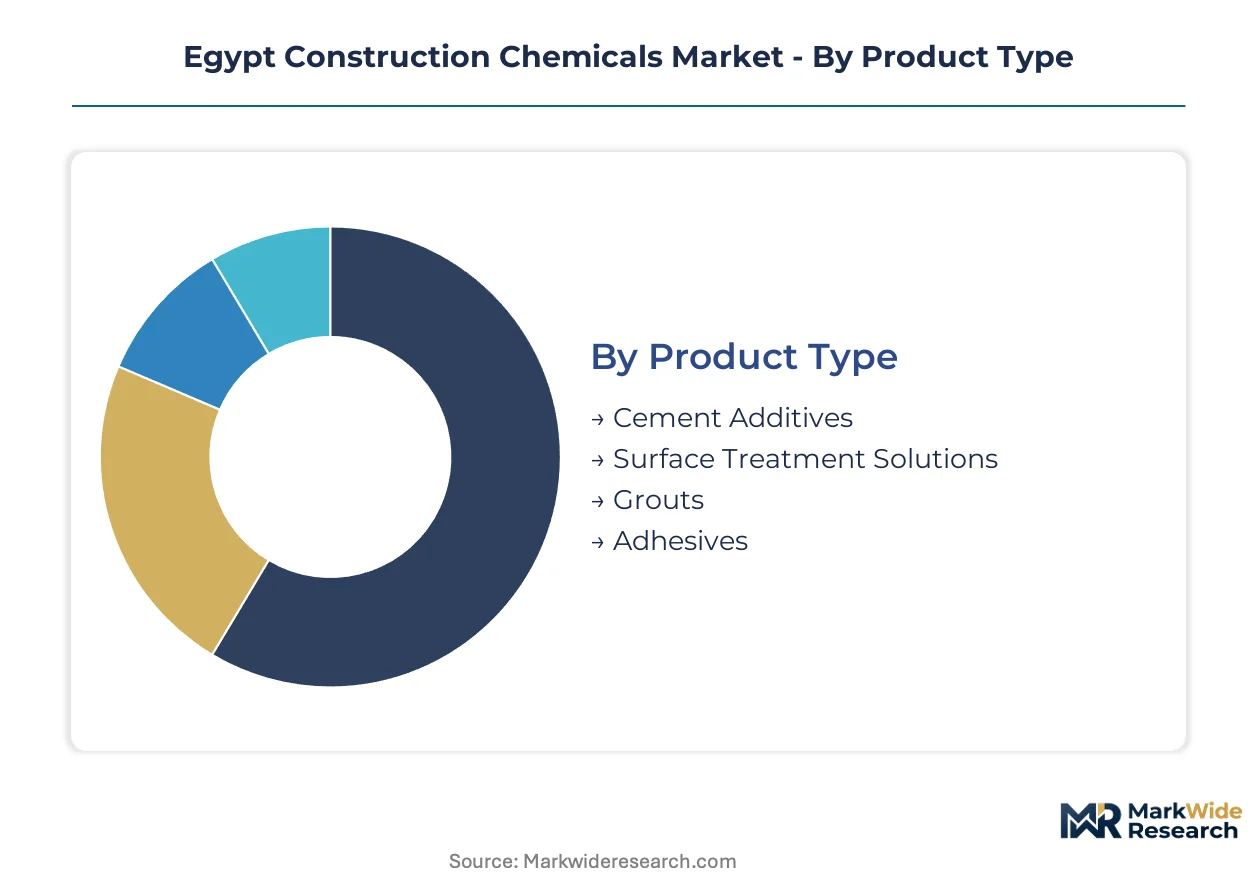
Segmentation in Egypt's construction chemicals sector tracks how ES certification tiers, polymer loading specifications, and project scale requirements split procurement decisions across distinct technical and commercial boundaries. Understanding these divisions reveals where specification premiums concentrate and which reformulation investments yield competitive advantage.
Product Type:
ES 4756-1 certification tiers separate commodity-grade from performance-grade formulations, with polymer content thresholds determining batch-approval privileges and public tender eligibility.
- Cement Additives:Polycarboxylate ether superplasticizers and retarders modify hydration kinetics for high-performance concrete in the New Administrative Capital's megaproject foundations. HBRC batch-approval requirements favor suppliers with captive precursor supply from integrated European production hubs.
- Surface Treatment Solutions:Acrylic-based waterproofing membranes and epoxy coatings protect concrete substrates against Nile Delta sulfate attack and Red Sea humidity exposure. Demand clusters in Alexandria's port rehabilitation corridors where marine-grade specifications command premium pricing.
- Grouts:Cementitious and epoxy injection systems for structural void filling and anchoring.
- Adhesives:Polymer-modified tile adhesives and bonding agents for finishing applications.
Established volume favors cement additives; emerging adoption favors surface treatment solutions.
Application:
Project scale and public-sector procurement rules create divergent specification requirements across Egypt's construction pipeline.
- Infrastructure:Suez Canal Economic Zone specifications drive high-performance grout and fiber-reinforced shotcrete procurement for port, rail, and logistics corridor development. The zone's engineering authority mandates third-party testing protocols that concentrate supply among certified multinationals.
- Residential:Greater Cairo's New Administrative Capital developments specify polymer-modified waterproofing at scale for high-rise foundations and basement structures. Developer procurement platforms now unbundle material supply from application supervision.
- Commercial:Mixed-use developments and retail complexes in Alexandria and Cairo.
- Industrial:Manufacturing facility construction with chemical-resistant flooring requirements.
Infrastructure commands the steepest specification premiums; residential delivers the deepest volume pools.
End User:
Technical decision-making authority varies by project delivery model, with design-build contracts consolidating specification power differently than traditional tender processes.
- Contractors:Direct procurement responsibility for material batches on infrastructure and residential megaprojects. ES mark compliance requirements drive preferred supplier relationships with certified blenders holding HBRC-accredited testing capabilities.
- Engineers:Performance specification authorship for high-speed rail and port rehabilitation projects. Technical service unbundling trends see engineers hiring independent application consultants separate from material suppliers.
- Architects:Aesthetic and durability specification for commercial facade and interior systems.
- Builders:Execution-focused procurement for standardized residential construction.
Contractors control the largest procurement volumes; engineers command the highest-performance specifications.
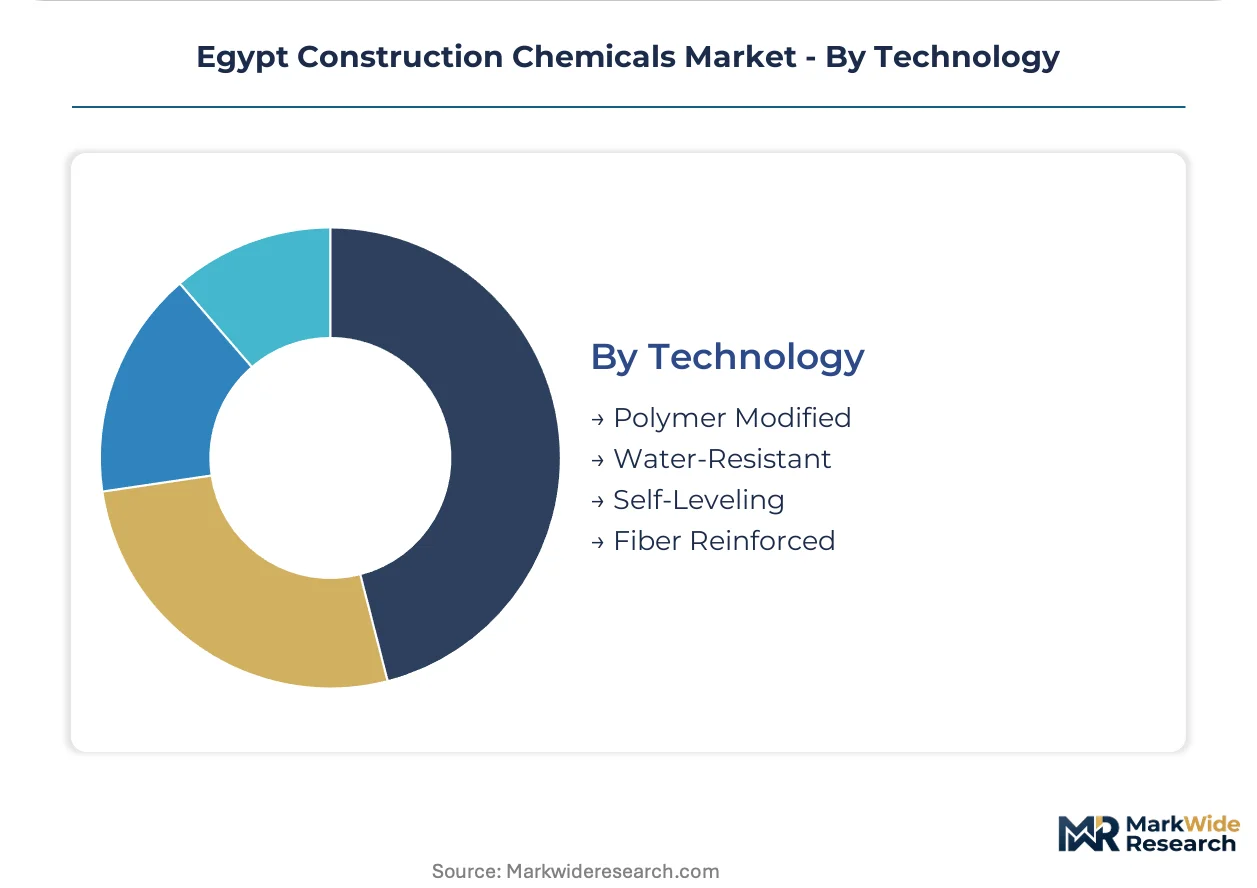
Technology:
Polymer chemistry sophistication determines resistance to Egypt's specific environmental stressors including groundwater sulfate, coastal chloride, and desert thermal cycling.
- Polymer Modified:Styrene-butadiene and acrylic latex dispersions enhance cementitious matrix flexibility and adhesion. Alexandria port rehabilitation and Red Sea tourism developments specify elevated polymer loading for humidity and salt spray resistance.
- Water-Resistant:Crystalline admixtures and hydrophobic pore blockers address Nile Delta water table challenges. High sulfate content in delta groundwater limits standard Portland cement efficacy, forcing custom formulation development.
- Self-Leveling:Cementitious underlayments with controlled rheology for interior flooring applications.
- Fiber Reinforced:Polypropylene and steel fiber additions for shotcrete and repair mortar durability.
Polymer modified systems dominate specification premiums; water-resistant technology is gaining share fastest in delta and coastal zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around state-backed megaproject developers in Greater Cairo, port authorities in Alexandria, and Suez Canal engineering consortiums. Procurement power pools with contractors holding HBRC batch-approval privileges. Specification authority fragments across engineering consultancies and developer procurement platforms.
Greater Cairo
The New Administrative Capital megaproject specifies polymer-modified waterproofing for high-rise foundations and basement structures. Egypt's Housing and Building National Research Center enforces ES 4756-1 certification for all admixture batches supplied to public works. Contractor procurement teams in East Cairo unbundle material supply from application supervision.
Alexandria Governorate
Port rehabilitation corridors drive marine-grade protective coating demand for Mediterranean humidity exposure. The Egyptian Organization for Standardization and Quality aligns local standards with ISO 9001 frameworks for tender eligibility. Maritime infrastructure clusters along the Western Harbor specify cathodic protection systems and elevated polymer loading.
Suez Canal Economic Zone
High-speed rail and logistics corridor development specifies fiber-reinforced shotcrete and high-performance grout. The zone's engineering authority mandates third-party testing protocols that concentrate supply among certified multinationals. Industrial cities around Port Said and Ismailia anchor specialty chemical procurement volumes.
Red Sea Coastal Zone
Tourism resort construction specifies humidity-resistant tile adhesives and sealants for salt spray exposure. New urban communities along the coastline enforce performance specifications exceeding standard ES grades. Hurghada and Sharm El Sheikh development zones pull elevated polymer content formulations from certified suppliers.
Nile Delta Region
High sulfate and chloride groundwater chemistry forces custom formulation development for foundation work. The Housing and Building National Research Center tightened admixture certification rules in response to infrastructure failure audits. Mansoura and Tanta construction clusters drive crystalline admixture adoption for water table challenges.
Egypt Construction Chemicals Market Competitive Landscape
Player mix skews toward multinational chemical conglomerates with captive European supply chains and local blenders holding HBRC-accredited testing facilities. Market structure consolidates around integrated suppliers commanding polymer dispersion import channels and certified batch-approval privileges. Two strategic archetypes dominate: multinationals leveraging parent-company R&D networks and regional specialists optimizing logistics for Upper Egypt project sites. Competitive moves center on reformulation cycle acceleration ahead of ES 4756-3 protocol revisions and temperature-controlled distribution infrastructure investment.
Among Switzerland-based integrated suppliers, Sika Egypt exemplifies the multinational archetype with parent-lab network access for fast-track certification renewals. BASF SE anchors the polymer precursor tier through captive polycarboxylate ether supply from its Ludwigshafen production base. Dow Chemical Egypt occupies a position emphasizing acrylic polymer dispersion consistency for formulation partners. These three represent distinct competitive vectors: certification velocity, upstream chemical integration, and dispersion quality standardization.
| Leading Market Players |
|---|
| Dow Chemical Egypt |
| United Paints and Chemicals Drymix S.A.E |
| Sika Egypt |
| Bostik Egypt |
| NCC X-Calibur |
| BASF SE |
| Pidilite Industries Egypt |
| RPM International Inc. |
| Mapei Egypt |
| Others |
Pricing and Supply Chain Analysis
Captive precursor capacity utilization at Ludwigshafen and other European hubs concentrates polymer dispersion supply among integrated multinationals, compressing margin floors for Egyptian blenders dependent on import channels. This scale asymmetry shapes both batch-approval pricing power and the cost-plus structures governing public tender participation.
Pricing Analysis
Cost-plus contracts with naphtha-indexed acrylic monomer adjustments dominate procurement between multinationals and state-backed megaproject developers. Pricing stratifies across ES 4756-1 certification grades, with HBRC-accredited suppliers commanding premiums over uncertified blenders. Cost compression in standard-grade admixtures is intensifying because petrochemical feedstock volatility transfers margin pressure downstream. Residential developers in Greater Cairo exhibit the highest price sensitivity, while Suez Canal infrastructure authorities prioritize performance over unit economics.
Supply Chain Analysis
Alexandria port cold-chain infrastructure underwrites acrylic emulsion integrity for Upper Egypt project sites, creating a logistics chokepoint that concentrates distribution control. Supply draws from Germany, Switzerland, and Italy for polycarboxylate ether precursors and polymer dispersions. Raw material dependencies include naphtha-derived acrylic monomers, ethylene oxide for surfactant synthesis, and specialty silica fume for high-performance concrete. Single-source vulnerability from Ludwigshafen captive supply creates pricing power asymmetry. Distribution runs through HBRC-accredited blending facilities in Greater Cairo and Alexandria before last-mile deployment to construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service unbundling from material supply contracts represents a faster-expanding revenue layer than commodity admixture sales, creating attach opportunities for certified suppliers with application engineering capabilities.
For Market Incumbents: Fortify batch-approval privileges through accelerated HBRC laboratory accreditation and captive microsilica sourcing for sulfate-resistant formulations. ES 4756-3 protocol revisions threaten certification velocity advantages held by Sika Egypt and BASF SE. Backward integration into temperature-controlled distribution infrastructure secures cold-chain integrity for acrylic emulsion last-mile delivery. For New Entrants and Emerging Players: Lead with crystalline admixture formulations targeting Nile Delta water table challenges where custom specification demand outstrips certified supply. Upper Egypt construction clusters remain penetrable for regional specialists optimizing logistics outside Greater Cairo-Alexandria corridors. Partner with independent application consultants unbundled from multinational material contracts to bypass procurement platform gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors blenders with HBRC-accredited testing facilities and established polymer dispersion import channels over pure formulation startups. Long-term viability rests on certification moat durability and reformulation cycle acceleration capabilities. Watch ES 4756-3 implementation timing as the inflection signal determining which suppliers capture first-mover threshold compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive polycarboxylate ether production from Ludwigshafen insulates margin compression from naphtha volatility. |
| HBRC Laboratory Accreditation Investment | In-house testing facilities compress batch-approval timelines from 18 weeks to competitive sub-10 week cycles. |
| Temperature-Controlled Distribution Buildout | Cold-chain infrastructure secures acrylic emulsion integrity for Red Sea coastal and Upper Egypt project sites. |
| Technical Service Unbundling Response | Standalone application consulting capabilities capture procurement platform separation trends in New Administrative Capital. |
| ES 4756-3 Pre-Positioning Reformulation | Polymer content threshold anticipation enables first-mover certification advantage ahead of protocol enforcement. |
Research Methodology
A spread of perspectives from admixture plant managers, procurement leads at New Administrative Capital developers, HBRC certification officers, and Alexandria port logistics operators converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with downstream contractors and technical directors at multinational formulation facilities. Secondary validation drew from Egyptian Organization for Standardization and Quality regulatory filings, customs import records for polymer dispersions, Housing and Building National Research Center certification databases, and Suez Canal Economic Zone procurement disclosures. Bottom-up project pipeline aggregation and top-down chemical consumption intensity modeling triangulated segment-level outputs.
Segmentation dimensions modeled include ES certification tier, polymer loading specification, project scale category, and regional construction corridor type across the projection horizon. CAGRs derive from intensity-factor scaling against cement consumption forecasts and infrastructure investment pipeline tracking. Industry-specific inputs incorporate HBRC batch-approval queue dynamics, naphtha cracking margin sensitivity for acrylic precursor costs, and silica fume substitution elasticity in Nile Delta sulfate environments.
The analysis sits within stated boundaries; outcomes outside sustained ES standard enforcement, stable petrochemical feedstock pricing, or continued megaproject execution would require recalibration. Forecasts reflect documented assumptions about certification timeline compression and import channel concentration. Practitioners should keep alternative scenarios live as Housing and Building National Research Center protocol revisions and Suez Canal Economic Zone procurement authority shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
United States Construction Chemicals Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
1, 4 Butanediol Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Chlorosilane Market
Chemicals
Barbituric Acid Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Penoxsulam Market
Chemicals
Europe Methanol Market