
 Sodium Naphthalene Sulphonate Formaldehyde Market | 2026-2036
Sodium Naphthalene Sulphonate Formaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Naphthalene Sulphonate Formaldehyde Market Outlook
Modular dosing systems for concrete admixtures is restructuring how contractors specify Sodium Naphthalene Sulphonate Formaldehyde across ready-mix and precast operations. SHANDONG WANSHAN CHEMICAL leverages backward integration into naphthalene feedstock to control raw material costs. BASF SE anchors its position through formulation leadership in high-range water reducers. Himadri Speciality Chemical Ltd. dominates Indian supply chains with dedicated logistics networks serving dam and highway projects.
Sodium Naphthalene Sulphonate Formaldehyde is a polycondensate of naphthalene, formaldehyde, and sulphonic acid groups, typically supplied with a sulphonation degree exceeding 90 percent and a molecular weight distribution optimized for cement particle dispersion. The compound functions primarily as a superplasticizer, reducing water-to-cement ratios by 15 to 25 percent while maintaining slump in commercial concrete. Powder formulations lead volume shipments due to stability in bulk transport and extended shelf life under tropical storage. Liquid grades capture margin pools in ready-mix plants seeking automated dosing compatibility. Construction applications anchor demand, though coatings processors are testing modified grades for pigment dispersion.
China's SAMR enforces GB 8076 standards for concrete admixture performance, while India's BIS mandates IS 9103 compliance for superplasticizer efficacy in government infrastructure. EPA regulations in the United States limit formaldehyde emissions during manufacturing, pushing producers toward closed-loop condensation reactors. REACH registration in Europe requires full toxicological dossiers for naphthalene derivatives, elevating compliance costs for non-EU exporters. Stakeholders must monitor how carbon-border adjustment mechanisms reshape cost competitiveness between Chinese synthesis hubs and regional formulation plants.
Market Dynamics
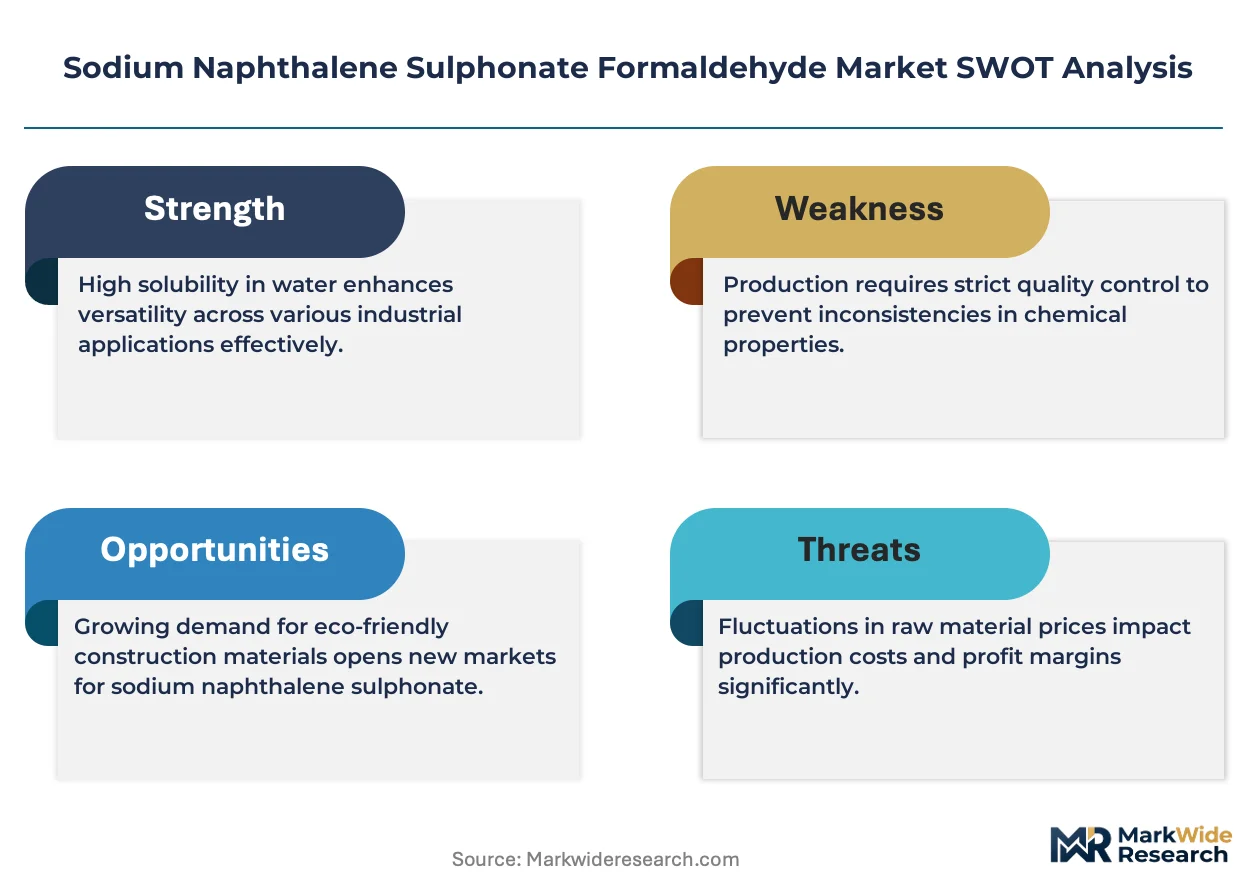
REACH registration requirements in Europe are forcing non-EU producers to consolidate naphthalene sulphonate supply chains around certified synthesis hubs, compressing the viable supplier base for formaldehyde-based superplasticizers.
Growth Catalysts
- GB 8076 standards alignment:China's SAMR enforcement of concrete admixture performance benchmarks is accelerating quality upgrades across precast manufacturing clusters in coastal provinces.
- Precast concrete scaling:Infrastructure budgets in India and the United States are widening procurement of powder-form superplasticizers for highway and dam projects requiring extended workability windows.
- Carbon-border adjustment mechanisms:Emerging EU trade instruments are redirecting sourcing decisions toward regional formulation plants with verified emission footprints.
Market Restraints
- Naphthalene feedstock volatility:Crude oil-linked pricing for naphthalene derivatives creates margin compression for producers lacking backward integration into coal-tar distillation.
- Formaldehyde emission caps:EPA regulations in the United States mandate closed-loop condensation reactor investments that elevate capital intensity for new market entrants.
- Polycarboxylate ether displacement:Next-generation superplasticizers with superior slump retention are capturing specification share in high-performance concrete segments.
Strategic Opportunities
- Coatings pigment dispersion:Modified sulphonate grades are penetrating industrial paint formulations seeking cost-effective dispersant alternatives to lignosulphonates.
- Modular dosing system integration:Automated admixture delivery platforms in ready-mix plants create specification pull for liquid-grade products with calibrated rheology profiles.
- IS 9103 compliance pathways:India's BIS superplasticizer efficacy mandates for government infrastructure are opening dedicated supply contracts for certified domestic producers.
Industry Challenges
- Sulphonation degree control:Achieving consistent 90-plus percent sulphonation across batch runs requires specialized process engineering talent scarce in emerging manufacturing hubs.
- REACH dossier compilation:Full toxicological documentation for naphthalene derivatives demands 18-to-24-month regulatory timelines that delay European market access for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Naphthalene Sulphonate Formaldehyde Market |
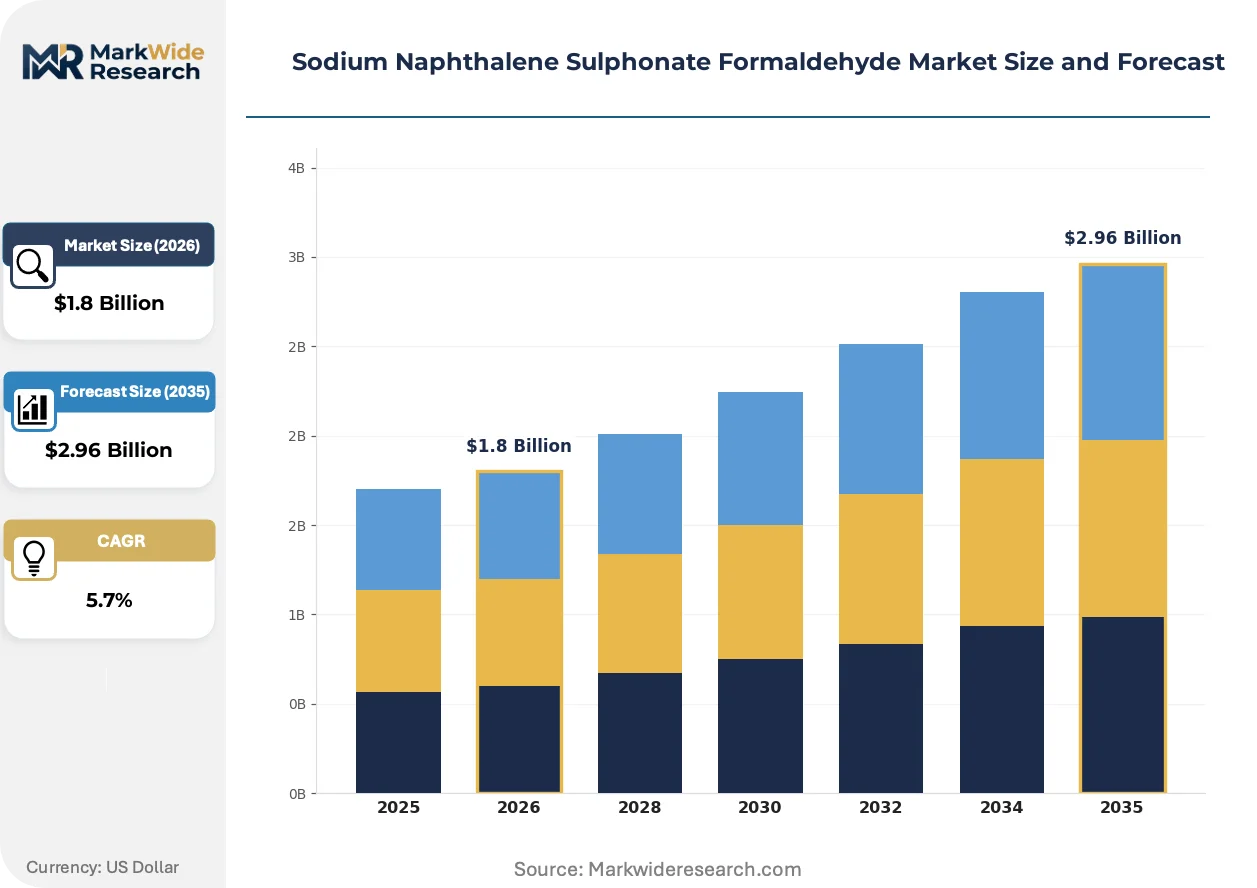
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granular, Pellets Application: Construction, Coatings, Plastics, Pharmaceuticals End User: Manufacturers, Contractors, Distributors, Retailers Technology: Formulation, Synthesis, Processing, Quality Control |
| Companies Covered | SHANDONG WANSHAN CHEMICAL CO., LTD., Wuhan Xinyingda Chemicals Co., Ltd., MUHU (China) Construction Materials Co., Ltd., Huntsman International LLC, Himadri Speciality Chemical Ltd., Kao Corporation, Sure Chemical Co., Ltd. Shijiazhuang, BASF SE, JFE Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Naphthalene Sulphonate Formaldehyde Market Strategic Shifts
Digital formulation platforms and closed-loop synthesis technologies are compressing development cycles for Sodium Naphthalene Sulphonate Formaldehyde derivatives while tightening purity specifications across construction chemical supply chains.
Low-formaldehyde condensation protocols are integrating molecular weight distribution control with real-time process analytics. Major concrete admixture blenders in Germany and Japan are adopting these systems to preempt REACH substance restrictions. The technology is integrating predictive quality modeling that reduces batch rejection rates and accelerates certification timelines for export-grade powder formulations.
ECHA's updated guidance on polymer registration is reclassifying certain sulphonate condensation products, triggering reformulation investments among Asian exporters serving European construction markets. Blenders with existing REACH dossiers are capturing specification share as competitors face 12-to-18-month compliance gaps. Precast concrete manufacturers in Poland and the Netherlands are now requiring registration verification in supplier qualification protocols.
Specification consolidation around performance-graded admixtures is compressing the viable supplier base for commodity sulphonates. Ready-mix procurement teams in China's Yangtze River Delta are consolidating annual contracts with dual-certified producers offering both powder stability and liquid dosing compatibility. This pattern is most visible in municipal infrastructure projects where automated batching systems penalize rheology inconsistency through penalty clauses and accelerated supplier rotation.
Sodium Naphthalene Sulphonate Formaldehyde Market Segmentation
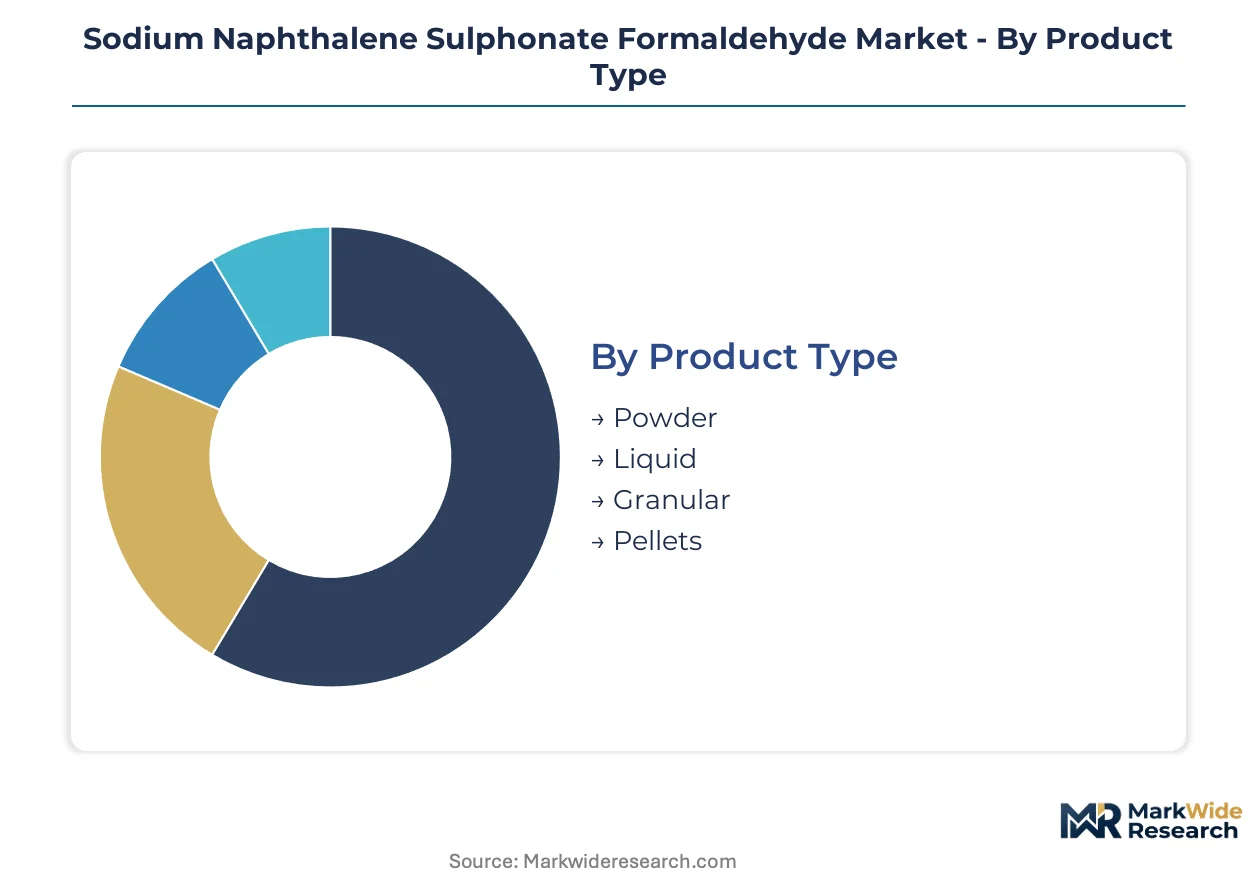
Segmentation in Sodium Naphthalene Sulphonate Formaldehyde markets reveals how physical form, end-use chemistry, and supply chain position determine margin capture. Buyers select grades based on storage logistics, dosing automation compatibility, and regional regulatory certification status.
Product Type:
Procurement teams prioritize stability under tropical storage conditions and transport economics when specifying physical form.
- Powder:Spray-dried formulations with moisture content below 5 percent dominate bulk shipments to precast concrete plants. China's coastal manufacturing provinces account for the heaviest offtake as infrastructure budgets widen and GB 8076 compliance becomes mandatory for government tenders.
- Liquid:Aqueous solutions with calibrated solids content enable automated dosing in ready-mix batching systems. Indian dam and highway projects are expanding procurement of liquid grades where extended workability windows justify higher per-unit logistics costs.
- Granular:Intermediate moisture resistance suits regional distribution hubs lacking climate-controlled warehousing.
- Pellets:Dust-free handling properties attract specialty coatings processors seeking precise metering in pigment dispersion applications.
Powder leads on scale; liquid gains share fastest in automated dosing environments.
Application:
End-use chemistry dictates sulphonation degree requirements and molecular weight distribution targets.
- Construction:Superplasticizer functionality reducing water-to-cement ratios by 15 to 25 percent anchors volume demand. Precast concrete output scaling in China's Yangtze River Delta and India's highway corridor projects concentrate procurement of certified grades.
- Coatings:Modified sulphonate grades disperse pigments in industrial paint formulations at lower cost than lignosulphonates. German and Japanese blenders are testing REACH-compliant condensation protocols for this segment.
- Plastics:Niche processing aid applications in thermoset molding compounds require specialized molecular weight fractions.
- Pharmaceuticals:High-purity grades with full toxicological dossiers serve excipient and intermediate synthesis under FDA and EMA scrutiny.
Construction commands absolute volume; coatings represents the steepest expansion trajectory as dispersant substitution accelerates.
End User:
Supply chain position determines specification authority and contract structure.
- Manufacturers:Integrated concrete admixture blenders in the United States, China, and India source bulk powder for captive formulation. Backward integration into naphthalene feedstock separates margin leaders from price-takers in this tier.
- Contractors:Municipal infrastructure and highway project owners in India's BIS-mandated procurement channels specify certified superplasticizers directly, bypassing traditional distributor markup.
- Distributors:Regional stockists manage inventory for mid-sized ready-mix plants lacking direct import capacity.
- Retailers:Small-package sales serve maintenance repair and operations segments in construction chemicals.
Manufacturers concentrate purchasing power; contractors are gaining specification authority through government tender mandates.
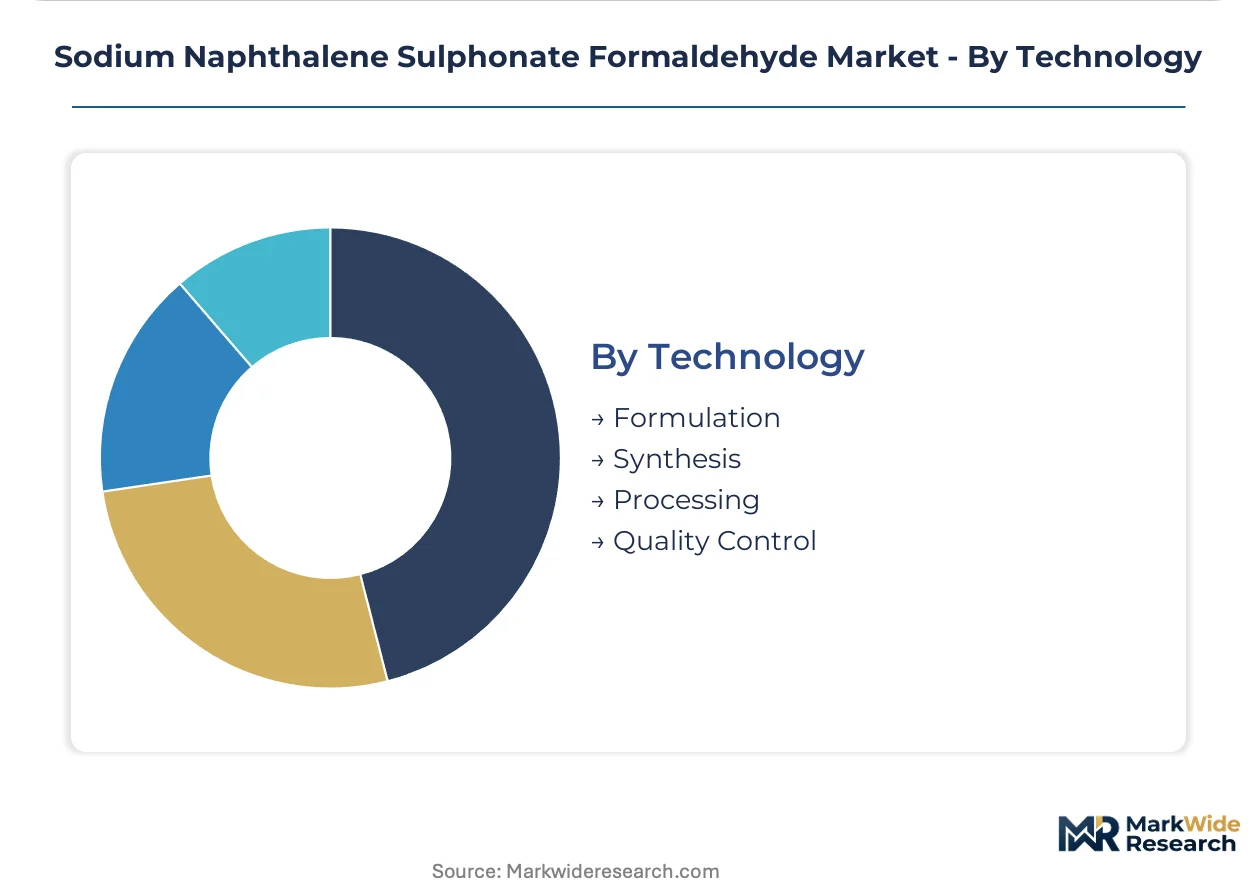
Technology:
Process control capabilities separate certified suppliers from commodity competitors.
- Formulation:Blending protocols integrate Sodium Naphthalene Sulphonate Formaldehyde with complementary admixtures to achieve slump retention targets. Japanese and German blenders lead in predictive quality modeling that reduces batch rejection.
- Synthesis:Sulphonation degree exceeding 90 percent requires specialized condensation reactor engineering. Closed-loop systems addressing EPA formaldehyde emission caps are becoming mandatory for US market access.
- Processing:Spray-drying and granulation equipment determines powder flow properties and shelf stability.
- Quality Control:Real-time analytics during condensation enable molecular weight distribution optimization. REACH dossier compilation for naphthalene derivatives demands 18-to-24-month investment in toxicological documentation.
Formulation commands premium pricing; synthesis investments act as the primary barrier to European and North American market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates pioneered industrial sulphonation chemistry during the early twentieth century, establishing the condensation protocols that Chinese and Indian producers now scale for infrastructure-grade superplasticizers.
China
Precast concrete output in Jiangsu and Zhejiang provinces drives powder-form procurement as municipal infrastructure budgets expand. SAMR enforces GB 8076 admixture performance standards that disqualify uncertified suppliers from government tenders. Manufacturing clusters in Shandong province leverage captive naphthalene feedstock from coal-tar distillation to control input costs.
India
Dam and highway projects across Maharashtra and Gujarat specify certified superplasticizers for extended workability windows in mass concrete pours. BIS mandates IS 9103 compliance for government infrastructure procurement, creating dedicated supply channels for domestic producers. Logistics networks serving the Delhi-Mumbai Industrial Corridor concentrate distribution capacity for liquid-grade products.
United States
Ready-mix plants in Texas and California adopt automated dosing systems that favor liquid formulations with calibrated rheology profiles. EPA regulations cap formaldehyde emissions during condensation, requiring closed-loop reactor investments that elevate capital barriers for new entrants. Gulf Coast petrochemical corridors supply naphthalene derivatives for captive admixture blending.
Germany
Predictive quality modeling in admixture formulation reduces batch rejection rates for export-grade powder destined to European construction markets. ECHA's updated polymer registration guidance triggers reformulation investments among blenders seeking REACH dossier compliance. Industrial chemical clusters in North Rhine-Westphalia integrate real-time process analytics into sulphonation degree control.
Japan
High-performance concrete specifications in Tokyo and Osaka metropolitan projects test modified sulphonate grades against polycarboxylate ether alternatives. METI-backed research programs advance low-formaldehyde condensation protocols with molecular weight distribution optimization. Chubu region chemical producers supply precision-grade dispersants for coatings applications beyond construction.
Sodium Naphthalene Sulphonate Formaldehyde Market Competitive Environment
The competitive structure tilts toward backward-integrated chemical conglomerates with captive naphthalene supply and specialized condensation engineering capabilities. Three archetypes dominate: coal-tar distillers controlling feedstock economics, formulation specialists commanding premium pricing through REACH-certified dossiers, and regional blenders capturing government tender volumes via BIS or GB standard alignment. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers secure naphthalene offtake agreements and dosing system integration contracts.
Among Chinese chemical producers, SHANDONG WANSHAN CHEMICAL CO., LTD. exemplifies the feedstock-integrated archetype through its Shandong base, while BASF SE occupies a position representing European formulation leadership with established REACH dossiers. Himadri Speciality Chemical Ltd. anchors the India-centric specialist tier, with its corporate structure indicating dedicated logistics capabilities for infrastructure project supply.
| Leading Market Players |
|---|
| SHANDONG WANSHAN CHEMICAL CO., LTD. |
| Wuhan Xinyingda Chemicals Co., Ltd. |
| MUHU (China) Construction Materials Co., Ltd. |
| Huntsman International LLC |
| Himadri Speciality Chemical Ltd. |
| Kao Corporation |
| Sure Chemical Co., Ltd. Shijiazhuang |
| BASF SE |
| JFE Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Government infrastructure contractors in India and China concentrate procurement authority through BIS-mandated and GB 8076-certified tender channels, anchoring a contract-based pricing model where certification tier and volume scale determine effective rates. Powder-form superplasticizers trade on long-term offtake agreements while liquid grades command project-specific premiums for automated dosing compatibility.
Pricing Analysis
Three-tier pricing structure across REACH-certified premium, GB/IS-compliant standard, and uncertified economy grades separates margin pools. Price differentiation rests on sulphonation degree consistency and formaldehyde emission compliance under EPA caps. Cost compression in the economy tier is intensifying because polycarboxylate ether substitutes capture high-performance concrete specifications. Municipal contractors exhibit highest price sensitivity; coatings processors seeking pigment dispersants show lowest.
Supply Chain Analysis
Dual-sourcing mandates from precast concrete manufacturers in China's Yangtze River Delta and India's Delhi-Mumbai Industrial Corridor require qualified suppliers in both Shandong and Maharashtra manufacturing clusters. Naphthalene feedstock draws from coal-tar distillation in China and petrochemical corridors in the United States. Single-source vulnerability concentrates around Shandong province's captive feedstock integration. Distribution runs through regional admixture blenders serving ready-mix plants with automated batching systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Sodium Naphthalene Sulphonate Formaldehyde hinges on backward integration into naphthalene feedstock and the premium-tier shift toward REACH-compliant condensation protocols for European coatings applications.
For Market Incumbents: Lock in naphthalene offtake agreements with coal-tar distillers in Shandong and North Rhine-Westphalia to defend against feedstock volatility. Invest in closed-loop condensation reactor engineering to preempt EPA formaldehyde emission caps and secure specification share in automated dosing system integrations.
For New Entrants and Emerging Players: Launch via IS 9103 certification pathways for Indian dam and highway procurement channels where BIS mandates create dedicated supply windows. Target coatings pigment dispersion applications in Germany and Japan where lignosulphonate substitution accelerates and REACH dossier gaps among Asian exporters delay competitor entry.
For Investors and Strategic Acquirers: Coal-tar chemical conglomerates with captive naphthalene supply are the most active acquirer in this space, consolidating backward-integrated positions across five-to-ten year infrastructure buildout cycles. Acquisition targets center on regional blenders with dual GB/BIS certification and established logistics networks. The signal to watch is carbon-border adjustment mechanism implementation timing reshaping cost competitiveness between Chinese synthesis hubs and European formulation plants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive naphthalene supply from coal-tar distillation insulates margin from crude-linked feedstock volatility. |
| REACH Dossier Investment | Full toxicological documentation for naphthalene derivatives unlocks specification share in European coatings procurement. |
| Closed-loop Reactor Upgrade | EPA formaldehyde emission compliance enables US market access and automated dosing system partnerships. |
| Coatings Grade Development | Modified sulphonate formulations penetrate industrial paint dispersant applications beyond construction anchors. |
| Logistics Network Expansion | Dedicated distribution capacity along India's Delhi-Mumbai Industrial Corridor captures BIS-mandated infrastructure tenders. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged concrete admixture plant managers, procurement leads at precast manufacturers, distribution channel partners, and technical R&D directors at condensation reactor operators. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and BIS/SAMR regulatory filings. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across physical form, end-use chemistry, and supply chain position shaped the analytical framework. Modeled dimensions included grade tier, construction versus coatings application, and regional production hub classification. CAGRs were derived from trend extrapolation against infrastructure budget trajectories and regulatory compliance timelines. Forecast inputs incorporated naphthalene feedstock price indices and precast concrete output scaling in coastal Chinese provinces.
Several conditions sit outside the modeled scope, including abrupt REACH substance restrictions, polycarboxylate ether substitution acceleration beyond high-performance concrete segments, and geopolitical disruptions to coal-tar naphthalene supply chains. Forecasts reflect documented assumptions about GB 8076 and IS 9103 enforcement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Cetanol Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Surfactants Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Emulsifying Wax Market
Surfactants
Alkylamines Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Lauramide DEA Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Global Saponin Market
Surfactants
Glycol Monostearate Market