
 Brazil Commercial Printing Market | 2026-2036
Brazil Commercial Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Commercial Printing Market Insights
ISO 12647 color certification is rotating as the primary qualification threshold for commercial printers serving brand-conscious corporate accounts. Pancrom Indústria Gráfica Ltda leverages its São Paulo facility network to dominate high-volume offset contracts for national consumer goods brands. HP competes through digital press installations that anchor on-demand production for advertising agencies requiring variable data capabilities. Heidelberger Druckmaschinen AG sustains technology leadership via sheetfed press distribution and service infrastructure across Brazilian industrial cities.
Brazil commercial printing encompasses the mechanical reproduction of text and images onto paper, cardboard, plastic films, and synthetic substrates using ink transfer systems operating at resolutions from 150 to 2400 dpi, primarily serving advertising, packaging, publishing, and corporate communication needs. Offset printing occupies the largest installed base among printing technology categories, though digital printing captures accelerating share in short-run corporate collateral and personalized direct mail services where job turnaround requirements compress below 48 hours. Brochures and business cards within product type segments generate stable volume, while print management and bundling services concentrate margin pools by integrating design, logistics, and fulfillment into single-source contracts.
ANVISA enforces pharmaceutical and food contact labeling standards that dictate substrate migration limits and ink composition for printed packaging entering Brazilian distribution. The Brazilian Institute of Metrology, Standardization and Industrial Quality (INMETRO) administers conformity assessment procedures for imported printing equipment, shaping capital expenditure timelines for domestic converters. ABNT technical standards for graphic technology and environmental compliance from IBAMA influence waste disposal protocols and solvent recovery investments. Stakeholders must monitor pending updates to extended producer responsibility frameworks for printed paper products, as these will determine whether integrated collection and recycling services become mandatory cost components or competitive differentiators.
Market Dynamics
Digital press installations are fragmenting job volumes across São Paulo converter clusters, compressing offset run lengths while ANVISA pharmaceutical labeling mandates tighten substrate compliance requirements for packaging converters serving southeastern Brazil's manufacturing corridor.
Growth Catalysts
- ANVISA pharmaceutical labeling mandates:Tightened substrate migration limits and ink composition standards for printed packaging entering Brazilian distribution channels are forcing converters to upgrade certification and capture premium-margin healthcare contracts.
- Retail chain print procurement expansion:Brazilian retail chains are expanding in-store promotional material volumes, driving demand for high-volume offset and digital hybrid production with sub-48-hour turnaround requirements.
- São Paulo converter cluster density:Concentrated converter infrastructure in São Paulo state enables logistics-cost advantages and same-day proofing services for brand-conscious corporate accounts in southeastern Brazil.
Market Restraints
- Imported equipment capital intensity:INMETRO conformity assessment procedures for imported printing equipment extend capital expenditure timelines, delaying digital press adoption for mid-tier Brazilian converters.
- Substrate cost volatility:Fluctuating pulp and petroleum-derived synthetic substrate prices compress margin predictability for high-volume brochure and packaging printers.
- Electronic substitution pressure:Corporate communication budgets are rotating toward digital channels, displacing stable-volume business card and stationery orders that historically anchored commercial print revenue.
Strategic Opportunities
- Extended producer responsibility frameworks:Pending IBAMA updates to printed paper product collection mandates will create competitive differentiation for converters integrating recycling services into single-source contracts.
- Variable data on-demand production:HP digital press installations are enabling advertising agencies to execute personalized direct mail campaigns with real-time data insertion, opening short-run premium pricing tiers.
- ISO 12647 certification scarcity:Limited certified capacity among Brazilian commercial printers creates margin expansion for early adopters serving multinational brand accounts with strict color consistency requirements.
Industry Challenges
- Prepress technician skill scarcity:Shortage of operators proficient in color management software and digital workflow integration is constraining throughput at hybrid offset-digital facilities.
- Legacy MIS system integration:Proprietary shop-floor data systems from Heidelberger Druckmaschinen AG and competing press manufacturers create friction in unified production scheduling across multi-vendor equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Commercial Printing Market |
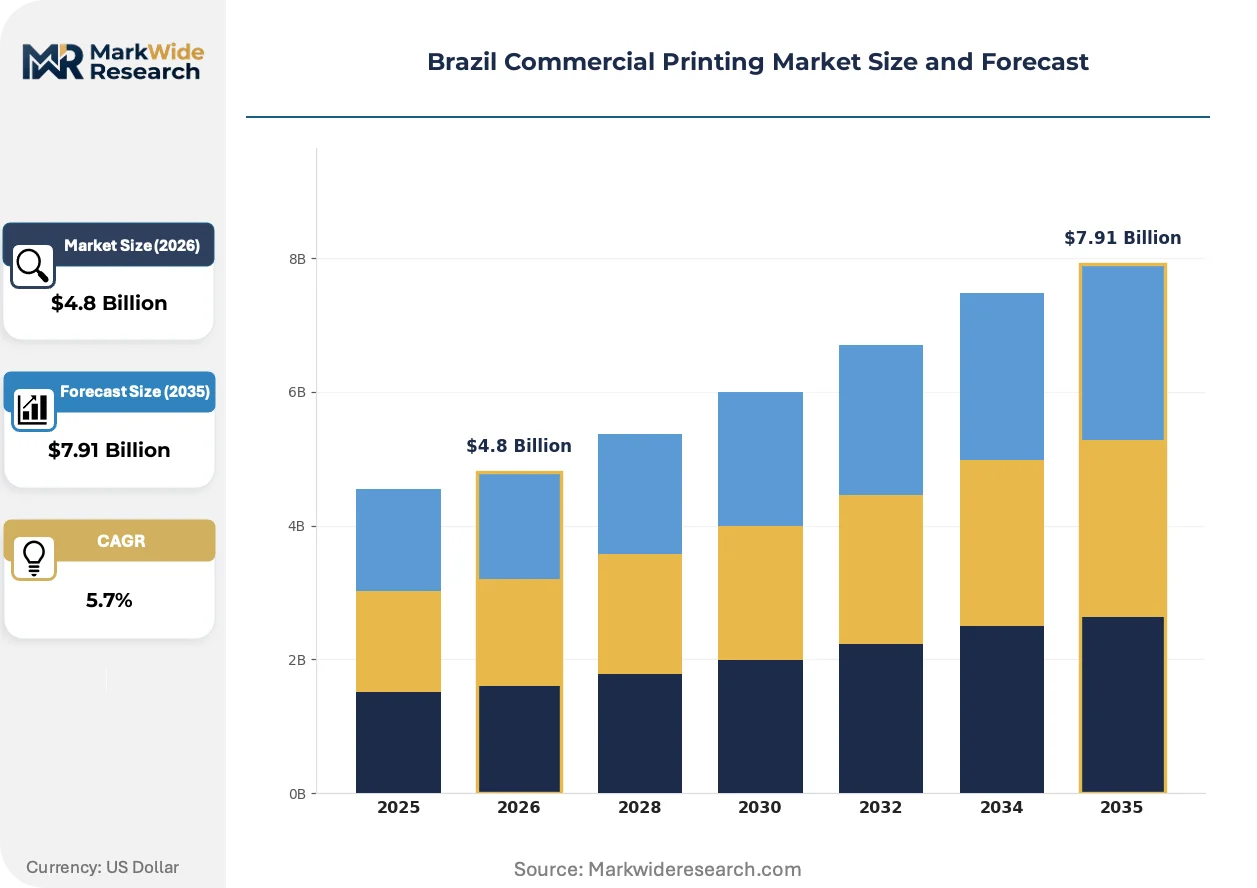
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brochures, Catalogs, Flyers, Business Cards Printing Technology: Offset Printing, Digital Printing, Flexographic Printing, Screen Printing End User: Retail Sector, Educational Institutions, Corporations, Advertising Agencies Service Type: Design Services, Print Management, Direct Mail Services, Bundling Services |
| Companies Covered | Pancrom Indústria Gráfica Ltda, Copy House a Gráfica Digital do Rio, Gráfica Gonçalves, FastPrint, 24 Rei Gráfica, 2Press Gráfica, Heidelberger Druckmaschinen AG, Nilpeter, HP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Commercial Printing Market Trends and Innovations
Production workflows are fragmenting across Brazil's commercial printing landscape as digital press capabilities compress job turnaround expectations and regulatory compliance requirements reshape substrate selection criteria for packaging converters.
High-speed inkjet technology is fragmenting traditional offset volume pools by enabling cost-competitive short-run production with variable data capabilities. Advertising agencies and direct mail specialists in São Paulo are adopting these systems for campaigns requiring regional personalization. The structural consequence is compressing minimum efficient scale for commercial print jobs below 5,000 impressions.
ANVISA pharmaceutical and food contact labeling standards are dictating substrate migration limits and ink composition requirements for printed packaging entering Brazilian distribution. Converters serving healthcare and food processing verticals must maintain dual inventory streams: compliant substrates for regulated applications and standard stocks for general commercial work. São Paulo-based packaging specialists are responding by securing ANVISA pre-approval documentation for substrate-ink combinations.
Corporate procurement departments are consolidating print spend under integrated print management contracts that bundle design, production, logistics, and fulfillment into single-source agreements. This purchasing model is displacing transactional relationships with multiple specialized vendors. The shift is most visible among multinational consumer goods brands operating manufacturing facilities in southeastern Brazil's industrial corridor.
Brazil Commercial Printing Market Segmentation
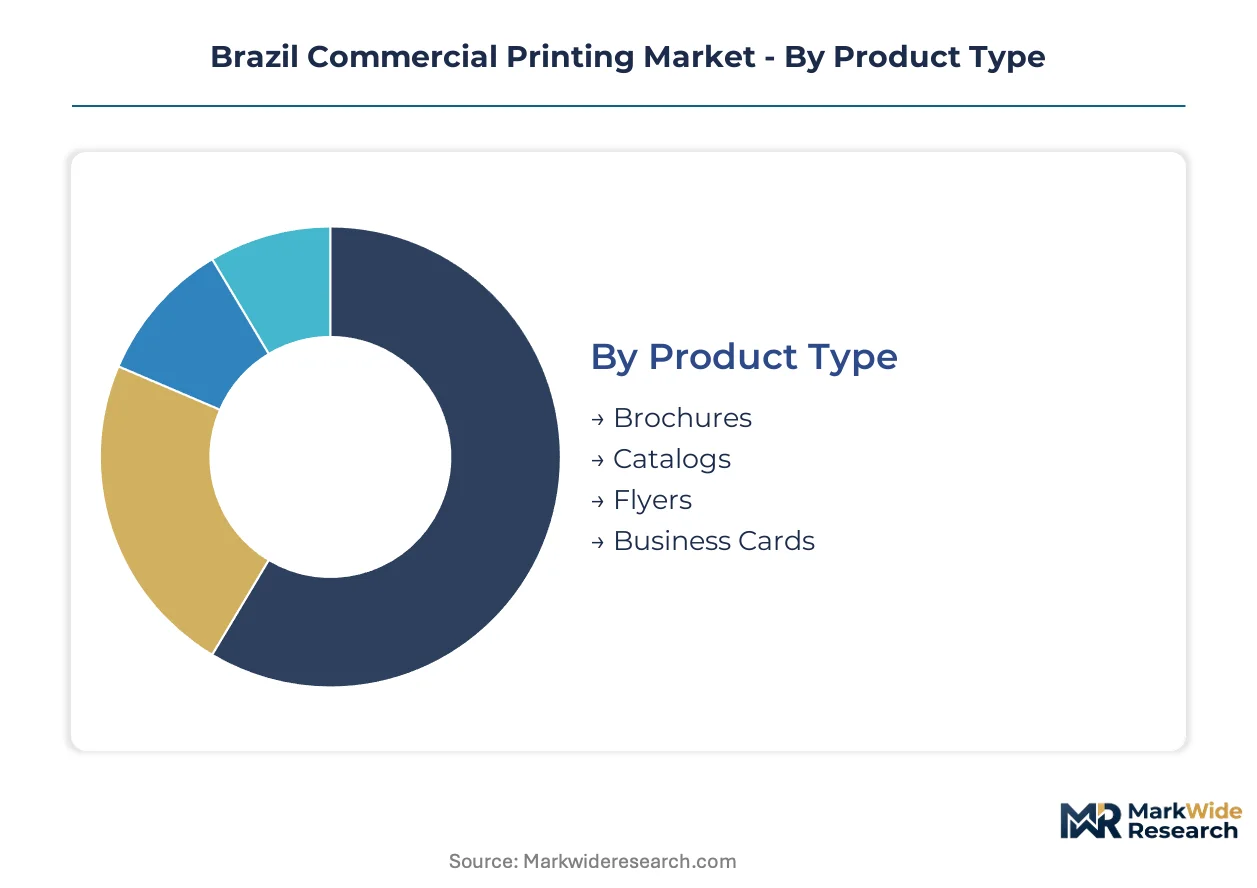
Brazil's commercial printing market fragments across four dimensions that determine equipment investment profiles and margin capture. Product type and printing technology dictate capital intensity, while end user concentration and service bundling shape contract structures and pricing power.
Product Type:
Domestic demand dominates all four product categories, with São Paulo-based converters capturing the majority of national volume. Export flows remain minimal given Brazil's cost position relative to Asian suppliers.
- Brochures:Multi-page collateral printed on coated stocks from 90 to 300 gsm serves corporate marketing departments and retail chains. Pharmaceutical manufacturers in São Paulo's manufacturing corridor drive premium specification demand under ANVISA compliance requirements.
- Catalogs:High-page-count publications with perfect binding or saddle stitching anchor offset press utilization at major São Paulo facilities. Retail sector procurement consolidation is compressing print runs while expanding versioning requirements for regional distribution.
- Flyers:Single-sheet promotional materials on uncoated or lightweight coated stocks generate high-volume, low-margin work. Demand concentrates among fast-moving consumer goods brands executing point-of-sale campaigns.
- Business Cards:Standardized 85x55mm format with spot UV or foil finishing requirements. Corporate communication budget rotation toward digital channels is displacing stable stationery orders.
Brochures command the established base. The steepest expansion runs through catalogs as retail versioning requirements multiply.
Printing Technology:
Capital cost tiers separate the four technologies, with imported equipment intensity creating distinct entry barriers for Brazilian converters.
- Offset Printing:Sheetfed and web offset systems dominate high-volume commercial work with minimum efficient scale above 5,000 impressions. São Paulo converter clusters maintain the largest installed base serving southeastern Brazil's manufacturing corridor.
- Digital Printing:Electrophotographic and inkjet systems enable sub-48-hour turnaround with variable data insertion. Advertising agencies in São Paulo are accelerating adoption for personalized direct mail campaigns.
- Flexographic Printing:Rotary relief printing on continuous webs serves packaging converters with substrate versatility across paper, film, and corrugated. ANVISA pharmaceutical labeling mandates are tightening ink and substrate compliance investments.
- Screen Printing:Stencil-based ink deposition for specialty substrates including textiles, glass, and plastics. Niche applications in promotional products and industrial labeling sustain limited converter capacity.
Offset printing anchors the installed capacity base. Digital printing climbs fastest as run lengths compress and turnaround expectations tighten.
End User:
Customer type determines pricing power, with multinational accounts extracting volume discounts while local specialists pay premiums for speed and customization.
- Retail Sector:National and regional chains procure in-store promotional materials with seasonal volume spikes. Print management consolidation is displacing transactional vendor relationships.
- Educational Institutions:Universities and private schools require course materials, certificates, and admissions collateral with academic calendar timing constraints. Budget pressures are extending payment terms.
- Corporations:Multinational consumer goods brands operating in southeastern Brazil drive ISO 12647 color certification requirements. Single-source contracts bundling design, production, and fulfillment are capturing procurement spend.
- Advertising Agencies:Creative shops demand rapid prototyping and variable data capabilities for campaign testing. Digital press access determines vendor selection.
Corporations anchor contract value. Advertising agencies expand most quickly as real-time personalization requirements spread.
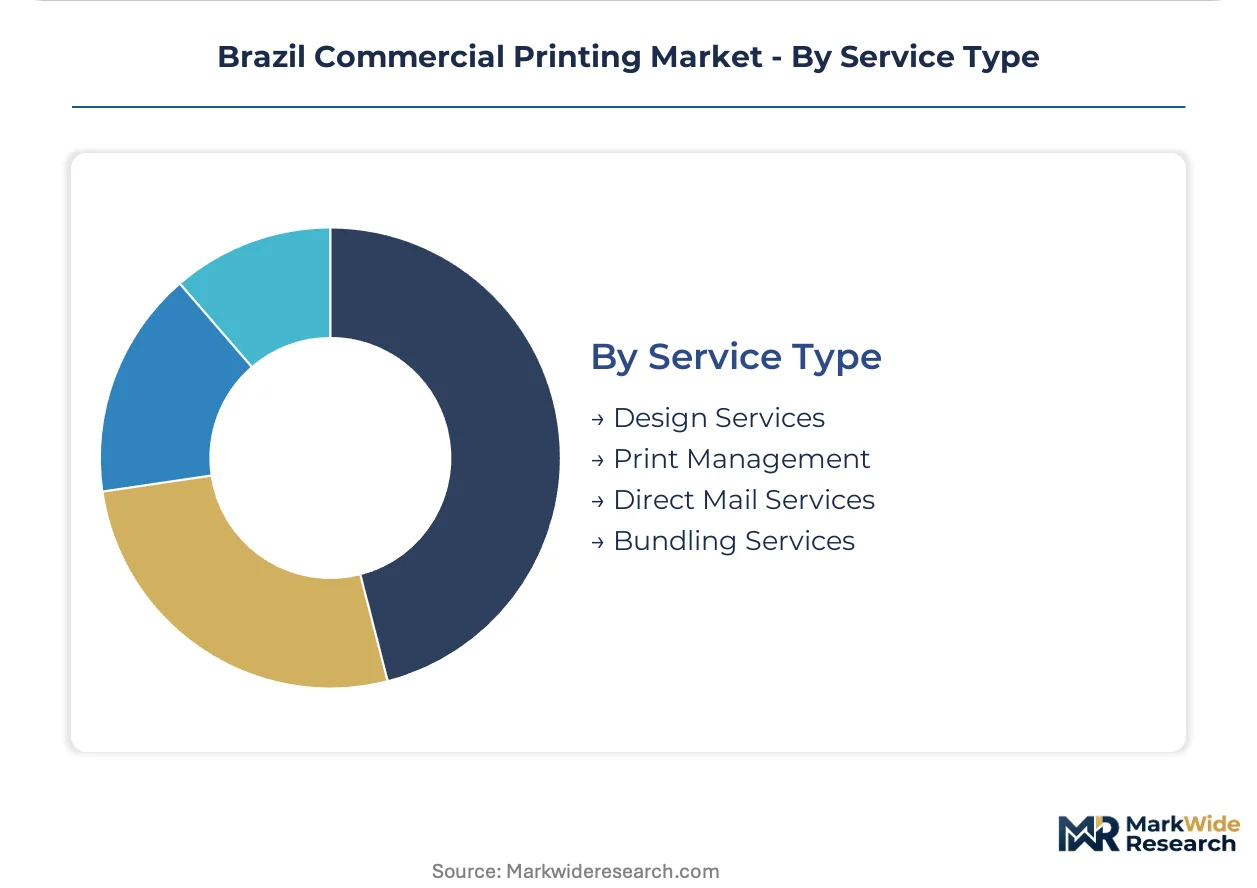
Service Type:
Margin capture improves with service integration, separating pure production houses from full-service providers.
- Design Services:Prepress creative work including layout, color management, and file preparation. ANVISA-compliant packaging design commands specialist premiums.
- Print Management:Centralized procurement coordination across multiple production sites and vendor relationships. Corporate accounts are consolidating spend under integrated contracts.
- Direct Mail Services:Variable data printing combined with postal optimization and distribution logistics. São Paulo agencies are expanding database-driven campaign execution.
- Bundling Services:Integration of design, production, warehousing, and fulfillment into single-source agreements. Extended producer responsibility frameworks may mandate collection and recycling additions.
Print management captures the largest contract value. Bundling services gain share fastest as procurement departments consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal tax incentives for industrial modernization in Brazil's Southeast region are accelerating digital press adoption among São Paulo-based converters. State-level environmental compliance mandates from IBAMA are reshaping capital allocation patterns across sub-regional production clusters.
São Paulo
Pharmaceutical manufacturers in the São Paulo manufacturing corridor drive premium specification demand under ANVISA compliance requirements. The state's national printing equipment import regulations through INMETRO conformity assessment procedures extend capital expenditure timelines for mid-tier converters. Greater São Paulo's converter clusters serve southeastern Brazil's manufacturing corridor with same-day proofing services for brand-conscious corporate accounts.
Minas Gerais
Educational institutions across Belo Horizonte and interior cities require course materials with academic calendar timing constraints. State procurement regulations favor local content requirements for printed materials in public education contracts. Triângulo Mineiro's emerging industrial parks are attracting packaging converters serving food processing verticals with regional distribution networks.
Rio de Janeiro
Tourism and hospitality sectors in Rio de Janeiro metropolitan area generate demand for promotional materials with seasonal volume spikes. Municipal environmental licensing from state-level environmental agencies shapes waste disposal protocols for commercial printers. Baixada Fluminense converter zones specialize in fast-turnaround flyer production for fast-moving consumer goods brands.
Rio Grande do Sul
Agribusiness marketing departments in Porto Alegre and surrounding regions procure technical catalogs and export documentation with strict color consistency requirements. State-level industrial development programs subsidize ISO certification costs for small and medium commercial printers. Serra Gaúcha's furniture and footwear manufacturing clusters sustain specialized packaging converter demand.
Paraná
Automotive parts suppliers in Curitiba's industrial district require traceable labeling solutions with substrate compliance for export markets. Federal highway infrastructure investments are improving logistics connectivity between Paraná converter facilities and São Paulo distribution channels. Londrina and Maringá printing houses are capturing agricultural input catalog contracts from cooperative marketing associations.
Brazil Commercial Printing Market Competitive Landscape
Listed equipment manufacturers compete with private domestic specialists across technology distribution and service provision. The vendor base separates into three tiers: multinational press manufacturers with Brazilian distribution infrastructure, large-format domestic converters with national account relationships, and regional specialists serving metropolitan markets. Strategic archetypes include scale-driven offset houses, digital-first hybrid operators, and compliance-focused packaging specialists. Equipment manufacturers defend position through service network density while domestic converters pursue print management consolidation.
Among German-originated equipment suppliers, Heidelberger Druckmaschinen AG occupies a position representing precision manufacturing archetypes with established Brazilian industrial city presence. HP exemplifies digital technology providers anchoring variable data capabilities for advertising agency relationships. Within domestic converter tiers, Pancrom Indústria Gráfica Ltda represents high-volume offset specialists leveraging São Paulo facility networks for national consumer goods contracts. These named entities illustrate competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Pancrom Indústria Gráfica Ltda |
| Copy House a Gráfica Digital do Rio |
| Gráfica Gonçalves |
| FastPrint |
| 24 Rei Gráfica |
| 2Press Gráfica |
| Heidelberger Druckmaschinen AG |
| Nilpeter |
| HP |
| Others |
Pricing and Supply Chain Analysis
Digital ink formulations substituting conventional petroleum-based alternatives are redrawing raw material sourcing maps toward specialty chemical suppliers in Germany and Japan while compressing margin structures for mid-tier Brazilian converters locked into legacy substrate contracts.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 12647-certified São Paulo facilities commanding 15-25% markups over uncertified competitors for multinational brand accounts. Pricing stratifies across ANVISA-compliant packaging specialists, ISO-certified commercial printers, and commodity flyer producers serving fast-moving consumer goods brands. Cost compression in the commodity tier is intensifying because retail procurement consolidation extracts volume discounts from high-volume offset houses. Advertising agencies demonstrate lowest price sensitivity, prioritizing sub-48-hour turnaround and variable data capabilities over unit cost.
Supply Chain Analysis
Port of Santos customs clearance delays constitute the critical chokepoint extending lead times for Heidelberg and HP press components arriving from Germany and USA. Brazil's commercial printing sector draws from China for synthetic substrates, Finland for coated mechanical papers, and domestic pulp mills for uncoated stocks. Single-source vulnerability concentrates in digital press consumables where HP holds dominant aftermarket share. Distribution runs through São Paulo converter clusters serving southeastern Brazil's manufacturing corridor with same-day logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of prepress technicians proficient in color management software and hybrid workflow integration constrains throughput expansion across Brazil's converter base, creating asymmetric returns for training investments.
For Market Incumbents: Fortify ANVISA pre-approval documentation for substrate-ink combinations to lock in pharmaceutical packaging contracts before regulatory deadlines tighten. Deepen São Paulo facility networks to capture print management consolidation from multinational consumer goods brands. Offset volume erosion from electronic substitution by bundling design, logistics, and fulfillment into single-source agreements that raise switching costs. For New Entrants and Emerging Players: Differentiate on ANVISA compliance specialization for healthcare verticals where incumbent capacity remains limited and pricing power persists. Target Minas Gerais educational institutions and Paraná automotive suppliers with regional same-day proofing services absent from São Paulo-centric competitors. Pursue ISO 12647 certification as the primary qualification threshold for corporate account access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hybrid offset-digital operators with existing certification infrastructure and established brand relationships. Acquisition focus should center on São Paulo-based converters with underutilized digital press capacity and ANVISA-compliant packaging capabilities. Monitor IBAMA extended producer responsibility framework implementation as the signal indicating whether integrated recycling services become mandatory cost components or competitive differentiators.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 12647 Certification Investment | Unlocks multinational brand accounts with strict color consistency requirements and premium pricing tiers. |
| ANVISA Pre-Approval Documentation | Secures pharmaceutical packaging contracts before substrate migration limits tighten compliance barriers. |
| Digital Press Capacity Addition | Captures advertising agency demand for variable data campaigns with sub-48-hour turnaround requirements. |
| Print Management Service Bundling | Consolidates corporate procurement spend by integrating design, production, logistics, and fulfillment. |
| Extended Producer Responsibility Integration | Positions converters for mandatory collection and recycling mandates under pending IBAMA framework updates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with commercial printing executives, prepress operations managers, brand procurement leads, and advertising agency production heads; and secondary validation against ANVISA regulatory filings, INMETRO equipment import records, ABNT technical standards, and IBAMA environmental compliance databases. Bottom-up triangulation across converter capacity surveys and top-down cross-checks against retail print procurement trends anchored volume estimates.
Across the analysis window, the forecasting framework modeled product type segments, printing technology categories, end user verticals, and service bundling tiers to derive growth trajectories. CAGRs emerged from equipment installation trends, regulatory compliance investment cycles, and procurement pattern shifts rather than extrapolated historical rates. Key inputs included digital press adoption curves in São Paulo converter clusters and ANVISA pharmaceutical labeling mandate implementation timelines.
Material uncertainties — pulp and petroleum-derived substrate price volatility, electronic substitution acceleration in corporate communications, and pending extended producer responsibility framework specifications — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and equipment import clearance efficiency. Revision becomes warranted when INMETRO conformity assessment procedures extend capital expenditure timelines beyond converter planning horizons or when IBAMA mandates alter recycling service economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Screen Printing Mesh Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Security Printing Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Waterborne Ink Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Radiation Curable Inks Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Global Low Migration Inks Market