
 Europe Polyether Ether Ketone (Peek) Market | 2026-2036
Europe Polyether Ether Ketone (Peek) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyether Ether Ketone (Peek) Market Insights
German compounders is broadening PEEK resin availability for medical-grade applications across the continent. Victrex plc leverages its Lancashire production base to sustain supply continuity for European aerospace tier-1 suppliers. Syensqo anchors its position through specialized polymer formulations targeting semiconductor manufacturing equipment. Evonik Industries AG differentiates via high-purity grades serving implantable medical device producers in Switzerland and the Netherlands.
Polyether ether ketone is a semi-crystalline thermoplastic belonging to the polyaryletherketone family, with a melting point near 343°C and excellent resistance to thermal degradation and chemical attack. Its molecular structure of alternating ether and ketone linkages provides the stiffness and creep resistance required for load-bearing metal replacement in harsh environments. PEEK granules dominate volume flows as the feedstock of choice for injection molding operations serving automotive under-hood and transmission components. Carbon-filled grade commands premium positioning where electrostatic discharge protection and dimensional stability prove critical for electronics and aerospace applications. Medical-grade PEEK rods represent the fastest-growing product configuration as spinal implant and dental abutment manufacturers scale machining operations.
EMA medical device regulations and REACH chemical compliance frameworks shape material qualification timelines and biocompatibility testing protocols for European PEEK suppliers. CE marking requirements under the EU MDR extend certification burdens to compounders serving orthopedic and cardiovascular device markets. Germany's KBA and France's ANSM enforce polymer traceability standards that filter subscale producers from automotive and medical supply chains. Stakeholders must monitor evolving CSRD disclosure rules and the EU AI Act's quality system implications for smart manufacturing lines processing high-performance polymers.
Market Dynamics
The EU Green Deal's material efficiency mandates are forcing metal substitution across European aerospace and automotive supply chains, compressing qualification timelines for high-performance polymers while concentrating procurement power among tier-1 integrators.
Growth Catalysts
- EU Green Deal mandates:Binding material efficiency targets for transport and energy sectors accelerate PEEK adoption as a lightweight metal replacement in structural components.
- EMA medical device regulations:Streamlined biocompatibility pathways under the EU MDR reduce time-to-market for implantable PEEK devices in spinal and dental applications.
- German automotive cluster concentration:Stuttgart and Munich engineering centers specify carbon-filled PEEK grades for transmission and thermal management systems.
Market Restraints
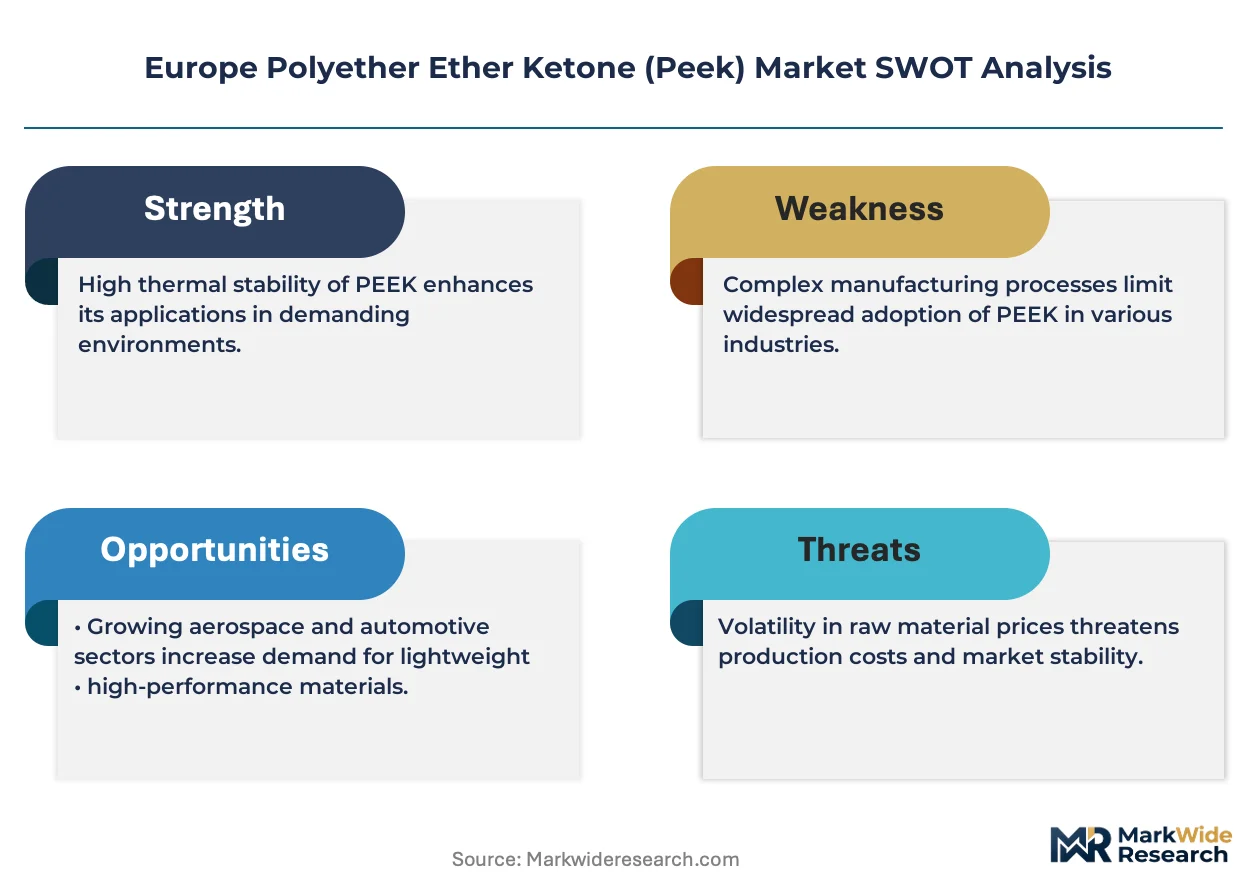
- Fluoropolymer feedstock volatility:PEEK resin production depends on difluorobenzophenone monomers subject to ECHA supply chain scrutiny and import cost fluctuations.
- Lancashire production concentration:A single UK site dominates European virgin PEEK supply, creating geographic vulnerability to logistics disruptions.
- Titanium alloy substitution threat:Additive manufacturing cost reductions in medical implants limit PEEK penetration in load-bearing orthopedic segments.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Underpenetrated Central European automotive tooling markets offer injection molding expansion for under-hood PEEK components.
- Semiconductor equipment fabrication:Wafer handling and chamber components represent emerging high-purity PEEK demand from Dutch and German lithography tool builders.
- CSRD disclosure rules:Mandatory supply chain carbon reporting advantages PEEK over aluminum in ESG-weighted procurement decisions.
Industry Challenges
- Polymer processing expertise scarcity:Injection molding technicians capable of managing PEEK's 343°C melt window and crystallization control remain concentrated in Germany and Switzerland.
- EU MDR certification timelines:Extended CE marking documentation burdens delay compounder qualification for cardiovascular device supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyether Ether Ketone (Peek) Market |
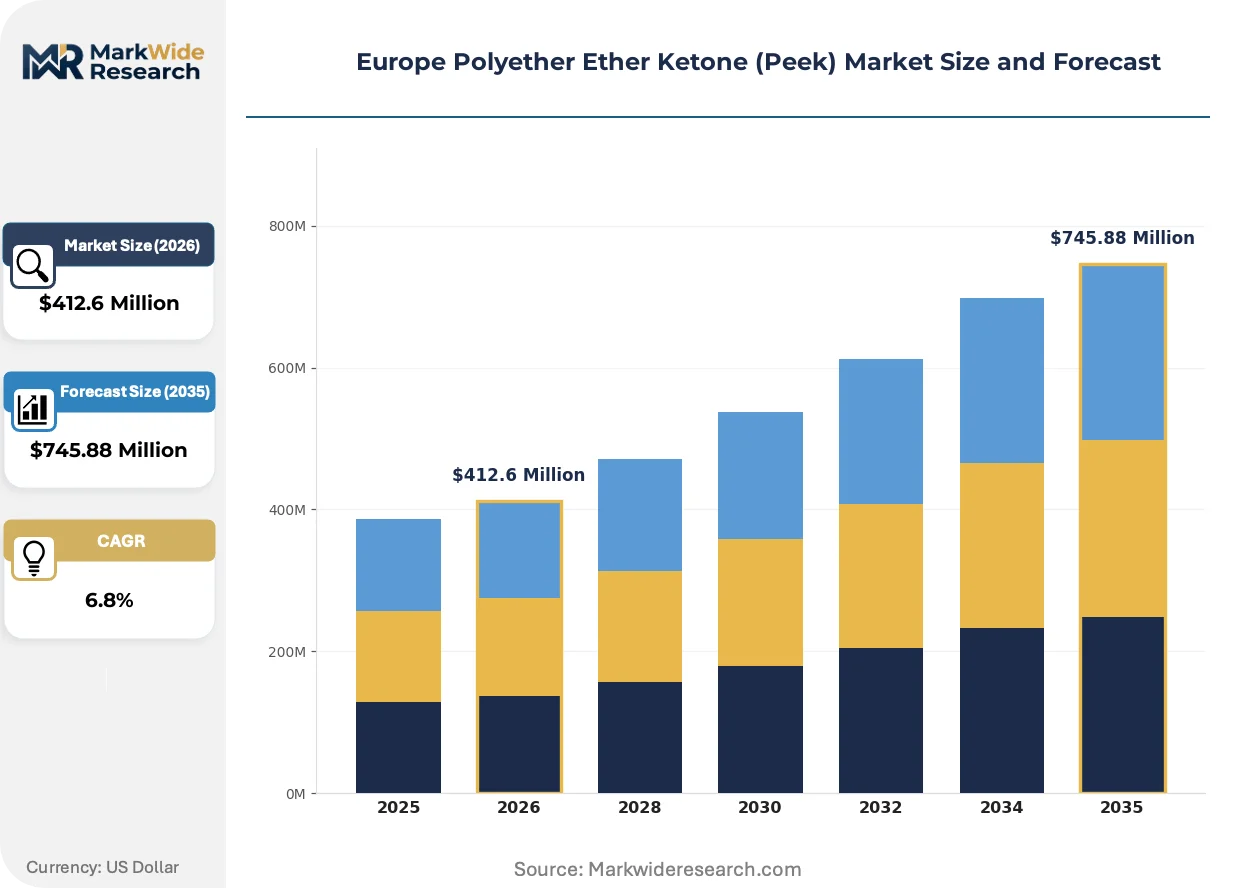
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEEK Granules, PEEK Sheets, PEEK Rods, PEEK Films End User: Aerospace, Automotive, Electronics, Medical Application: Injection Molding, 3D Printing, Coatings, Insulation Grade: Standard Grade, Glass-Filled Grade, Carbon-Filled Grade, High-Temperature Grade |
| Companies Covered | Victrex plc, Syensqo, Evonik Industries AG, Arkema, Ensinger GmbH, Solvay, SABIC, DAIKIN COMPOUNDING ITALY S.p.A, Freudenberg, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyether Ether Ketone (Peek) Market Trends and Innovations
PEEK formulation science is converging with additive manufacturing process control, reshaping how European medical device and aerospace suppliers approach near-net-shape production economics.
Continuous carbon fiber-reinforced PEEK composites are converging with automated fiber placement systems in aerospace structural applications. Airbus tier-1 suppliers in Toulouse and Hamburg are qualifying these materials for wing and fuselage brackets. The technology is converging with out-of-autoclave curing methods, compressing lead times against thermoset alternatives.
REACH chemical compliance frameworks are tightening scrutiny on per- and polyfluoroalkyl substance traces in polymer feedstocks. ECHA's restriction roadmap is forcing compounders to requalify catalyst systems and purification protocols. Medical-grade producers in Switzerland and the Netherlands face the steepest revalidation burdens under this evolving regime.
Direct resin distribution from compounders to machining houses is displacing traditional distributor networks for medical-grade PEEK rod and plate. Swiss spinal implant manufacturers now source certified stock through verified supply agreements rather than regional plastics wholesalers. This channel compression is most visible in the Jura Arc cluster, where dental abutment producers demand lot-traceable material with sub-48-hour delivery guarantees.
Europe Polyether Ether Ketone (Peek) Market Segmentation
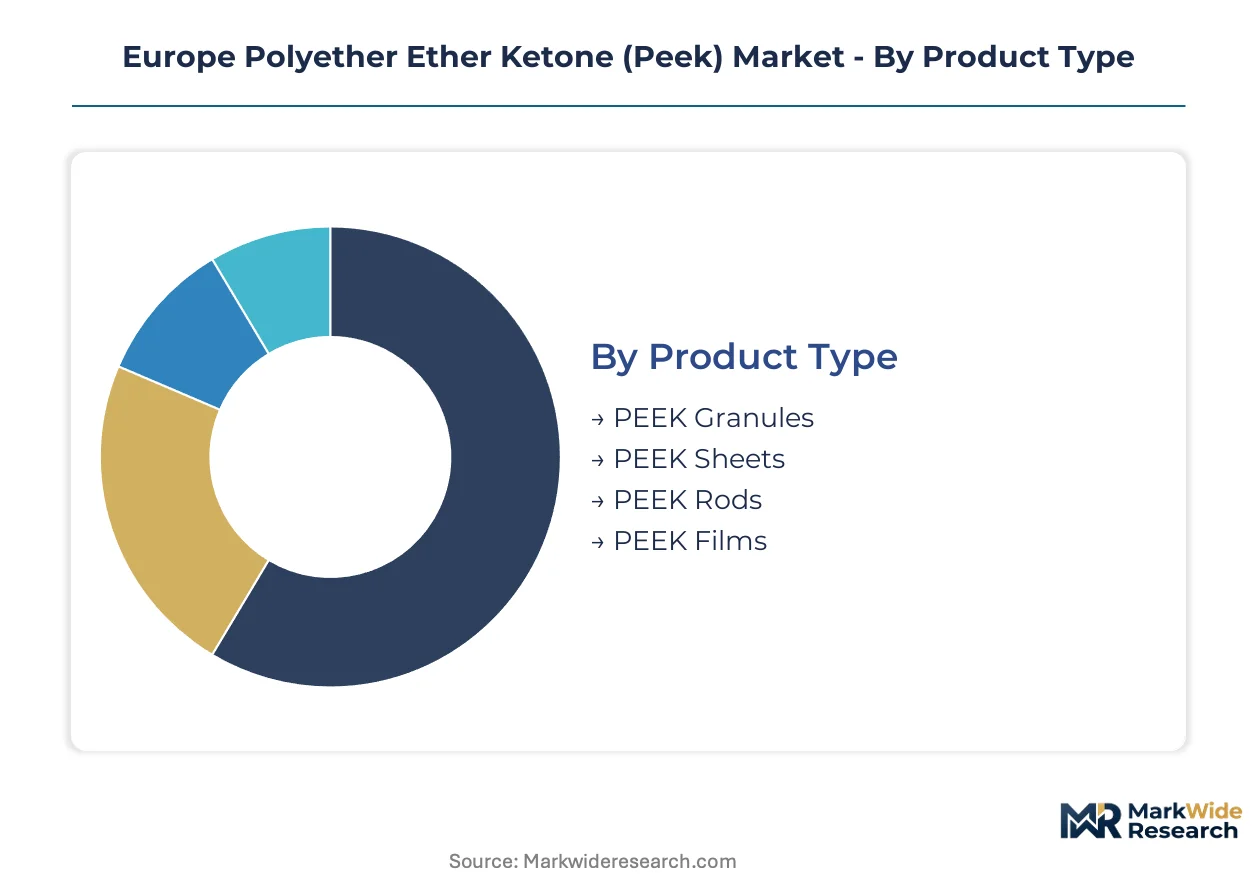
PEEK's molecular versatility enables precise matching of form factors and performance grades to end-use thermal, mechanical, and regulatory requirements across European aerospace, automotive, and medical supply chains.
Product Type:
Granules dominate volume flows while rods command premium positioning in medical machining applications.
- PEEK Granules:Semi-crystalline feedstock with 343°C melt point serves injection molding operations for automotive under-hood and transmission components. Stuttgart and Munich engineering centers specify carbon-filled variants for thermal management systems facing EU Green Deal weight reduction mandates.
- PEEK Rods:Solid cylindrical stock machined into spinal implants and dental abutments. Swiss spinal implant manufacturers in the Jura Arc cluster demand lot-traceable rod with sub-48-hour delivery guarantees under EU MDR biocompatibility protocols.
- PEEK Sheets:Flat stock for thermoformed aerospace interior panels and semiconductor equipment shrouds.
- PEEK Films:Thin-gauge material for electrical insulation and speaker diaphragms in premium automotive audio systems.
Today's leader: PEEK Granules. Tomorrow's challenger: PEEK Rods.
End User:
Medical applications generate the steepest margin premiums while automotive delivers volume scale.
- Medical:Implantable device manufacturers in Switzerland and the Netherlands drive demand for high-purity grades. EU MDR streamlined biocompatibility pathways reduce time-to-market for spinal and dental applications, though extended CE marking documentation burdens delay compounder qualification.
- Aerospace:Tier-1 suppliers in Toulouse and Hamburg qualify continuous carbon fiber-reinforced PEEK for wing and fuselage brackets. Airbus manufacturing centers accelerate adoption as lightweight metal replacement under material efficiency mandates.
- Automotive:Germany's KBA enforces polymer traceability standards that filter subscale producers from under-hood component supply chains.
- Electronics:Dutch and German lithography tool builders specify high-purity PEEK for wafer handling and chamber components.
Medical commands the highest unit economics. Aerospace offers the most durable expansion trajectory.
Application:
Injection molding anchors current capacity utilization while additive manufacturing reshapes near-net-shape production economics.
- Injection Molding:Primary forming method for automotive transmission components requiring tight dimensional tolerance. Polymer processing expertise scarcity constrains expansion—technicians capable of managing PEEK's crystallization control remain concentrated in Germany and Switzerland.
- 3D Printing:Laser sintering and filament deposition enable patient-specific spinal implants and aerospace brackets without tooling investment. EMA medical device regulations and REACH frameworks shape material qualification timelines for printed medical components.
- Coatings:Powder and dispersion forms protect chemical processing equipment from corrosive attack.
- Insulation:Wire and cable jacketing for high-temperature electrical applications in electric vehicle powertrains.
Injection molding defends volume leadership. 3D printing captures the steepest technology premium.
Grade:
Standard grades serve cost-sensitive automotive while filled variants penetrate metal substitution opportunities.
- Carbon-Filled Grade:Electrostatic discharge protection and dimensional stability critical for semiconductor manufacturing equipment and aerospace structural brackets. Premium positioning reflects raw material cost and compounding complexity under ECHA supply chain scrutiny.
- Medical-Grade (Standard Grade subset):High-purity resin for implantable devices meeting biocompatibility testing protocols. Evonik Industries AG differentiates via grades serving Swiss and Dutch orthopedic producers.
- Glass-Filled Grade:Enhanced stiffness for pump housings and valve components in chemical processing.
- High-Temperature Grade:Extended thermal stability for oil and gas downhole applications.
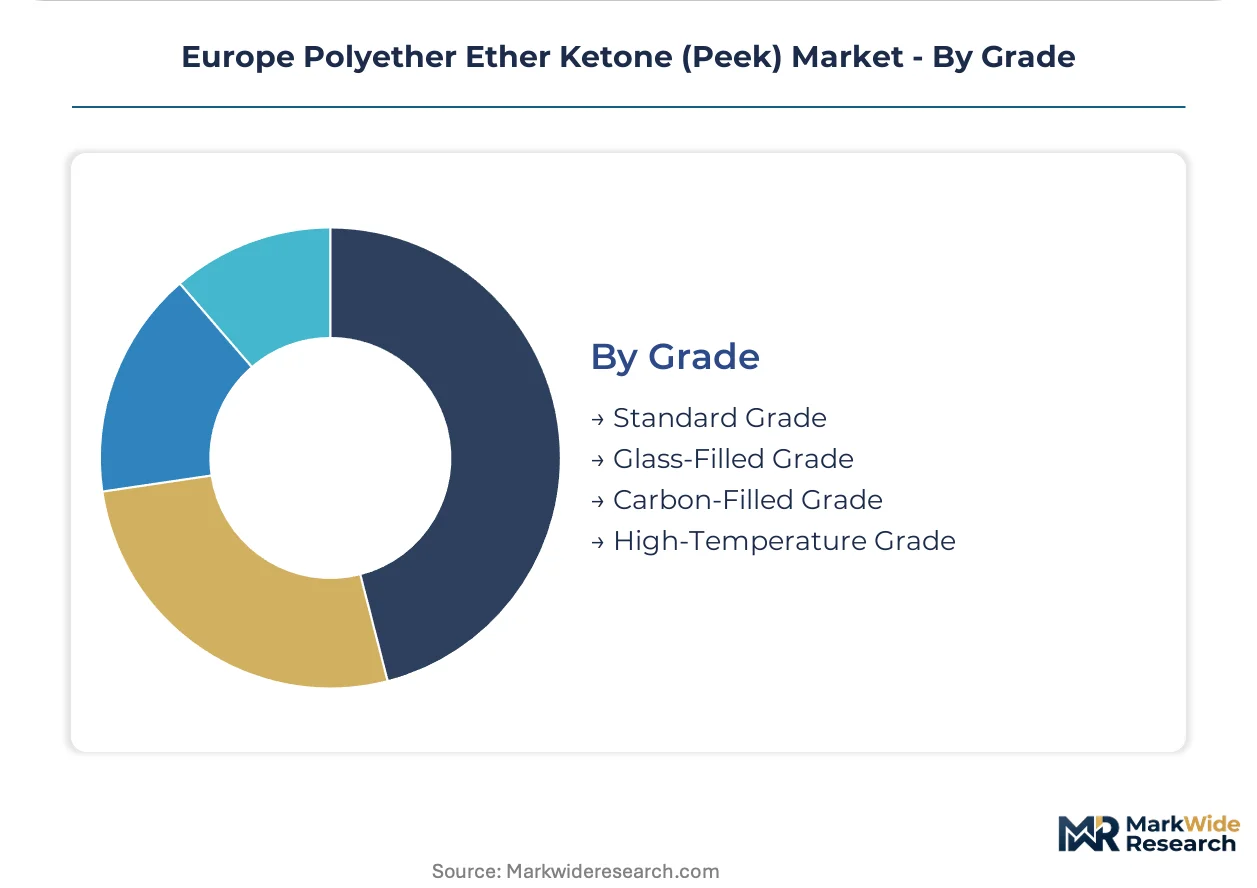
Carbon-filled grade leads premium substitution. Medical-grade variants expand most quickly under EU MDR implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as compounders migrate toward jurisdictions with streamlined REACH compliance and lower ECHA revalidation burdens. The EU Green Deal's binding material efficiency targets are accelerating this shift, concentrating virgin resin capacity in established chemical clusters while downstream machining disperses toward medical device manufacturing centers.
Germany
KBA-enforced polymer traceability standards filter subscale producers from automotive supply chains serving Stuttgart and Munich engineering centers. The EU Green Deal's transport sector mandates compress qualification timelines for carbon-filled PEEK grades in thermal management systems. Bavaria's automotive cluster anchors injection molding operations for under-hood components.
United Kingdom
Lancashire's virgin PEEK production base sustains supply continuity for European aerospace tier-1 suppliers despite post-Brexit customs friction. ECHA supply chain scrutiny on difluorobenzophenone monomers creates import cost volatility for UK compounders. The North West England chemical corridor retains concentration in high-performance polymer resin output.
France
ANSM medical device regulations enforce biocompatibility testing protocols that extend certification timelines for implantable PEEK producers. Airbus manufacturing centers in Toulouse accelerate adoption of continuous carbon fiber-reinforced PEEK for wing brackets under material efficiency mandates. The Occitanie aerospace cluster qualifies out-of-autoclave curing methods against thermoset alternatives.
Switzerland
Swissmedic oversight of implantable devices drives demand for high-purity medical-grade rods among Jura Arc spinal implant manufacturers. CSRD disclosure rules advantage PEEK over aluminum in ESG-weighted procurement decisions for orthopedic producers. The Basel-Zurich corridor concentrates machining expertise for dental abutment applications.
Netherlands
Dutch lithography tool builders specify high-purity PEEK grades for wafer handling components in semiconductor manufacturing equipment. EMA streamlined biocompatibility pathways under EU MDR reduce time-to-market for cardiovascular device compounders. The Eindhoven-Twente region anchors demand from ASML's supply chain for electrostatic discharge protection materials.
Europe Polyether Ether Ketone (Peek) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue medical-grade specialization and additive manufacturing feedstocks. The market exhibits moderate consolidation around resin compounders with captive monomer supply, while downstream machining houses fragment across orthopedic clusters. Three archetypes dominate: integrated resin-to-rod producers, specialized medical-grade compounders, and regional distributors compressing channel layers. Capacity expansion and direct distribution agreements constitute the primary competitive vectors as qualification timelines lengthen under EU MDR implementation.
Within the integrated producer tier, Victrex plc anchors European virgin resin supply from its Lancashire production base, while Syensqo exemplifies the specialized compounder archetype through semiconductor-focused formulations. Evonik Industries AG occupies a position representing high-purity medical-grade differentiation for implantable device markets. These three entities collectively illustrate the strategic segmentation between scale-driven resin production, application-specific compounding, and regulatory-intensive medical certification.
| Leading Market Players |
|---|
| Victrex plc |
| Syensqo |
| Evonik Industries AG |
| Arkema |
| Ensinger GmbH |
| Solvay |
| SABIC |
| DAIKIN COMPOUNDING ITALY S.p.A |
| Freudenberg |
| Others |
Pricing and Supply Chain Analysis
EU MDR procurement consolidation among Jura Arc spinal implant manufacturers is compressing distributor margins and forcing compounders toward direct-to-machining-house contracts with lot-traceability guarantees. This channel compression concentrates pricing power with integrated resin-to-rod producers capable of sub-48-hour medical-grade delivery.
Pricing Analysis
Distributor margin compression now defines European PEEK pricing architecture as direct compounder-to-OEM agreements displace regional plastics wholesalers. Three-tier pricing structure across medical-grade, carbon-filled, and standard automotive grades reflects certification burden and raw material purity differentials. Cost compression in medical-grade rod is intensifying because Swiss and Dutch implant manufacturers demand sub-48-hour delivery with full lot traceability. Automotive processors in Stuttgart and Munich exhibit highest price sensitivity due to volume scale and metal substitution cost benchmarks, while semiconductor equipment builders in Eindhoven accept premium positioning for electrostatic discharge protection grades.
Supply Chain Analysis
Polymer processing technician scarcity in Germany and Switzerland constrains molding capacity expansion despite demand acceleration from EU Green Deal mandates. Virgin resin production concentrates in the United Kingdom, Germany, and Belgium, with difluorobenzophenone monomer supply drawing from ECHA-scrutinized import channels. Single-source vulnerability at the Lancashire production base creates geographic concentration risk for European aerospace tier-1 suppliers. Distribution runs through direct compounder agreements for medical-grade rod and regional distributor networks for automotive granule volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-compliant resin production in the United Kingdom and downstream machining in Switzerland offers margin capture opportunities as regulatory revalidation burdens diverge across jurisdictions.
For Market Incumbents: Anticipate titanium alloy additive manufacturing cost reductions in load-bearing orthopedic segments by deepening captive monomer supply and accelerating EU MDR certification timelines for cardiovascular device compounders. Defensive positioning requires backward integration into difluorobenzophenone purification protocols and capacity expansion in Central European automotive tooling corridors. For New Entrants and Emerging Players: Capture underpenetrated injection molding demand in Poland and Czech Republic automotive clusters where EU Green Deal weight reduction mandates outpace local compounding capacity. Semiconductor equipment fabrication for Dutch lithography tool builders offers the most penetrable white-space target, with high-purity grade specialization as the optimal go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized medical-grade compounders possessing EU MDR certification infrastructure and Jura Arc machining house relationships. Long-term viability hinges on regulatory moat durability rather than resin scale economics. Watch ECHA restriction roadmap implementation on fluoropolymer feedstocks as the critical inflection signal for integrated producer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive difluorobenzophenone production insulates Victrex plc from ECHA import volatility. |
| EU MDR Certification Acceleration | Streamlined CE marking pathways reduce compounder qualification delays for Swiss spinal implant supply chains. |
| Central European Capacity Expansion | Poland and Czech Republic injection molding addresses automotive cluster demand from Stuttgart and Munich engineering centers. |
| Direct Distribution Channel Compression | Lot-traceable rod agreements with Jura Arc machining houses displace regional plastics wholesalers. |
| Semiconductor Equipment Grade Development | High-purity formulations target ASML supply chain requirements for wafer handling components. |
Research Methodology
Bottom-up automotive and medical device demand modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with polymer processing technicians, automotive Tier 1 procurement managers, biomedical engineers at Swiss implant manufacturers, and EMA regulatory affairs specialists combined with secondary validation from ECHA restriction roadmaps, EU MDR implementation guidance, Cefic high-performance polymer reports, and customs trade data on difluorobenzophenone monomer flows. Triangulation across supply-side capacity announcements and demand-side specification changes ensures convergence.
Historical trendline analysis of PEEK adoption rates in aerospace structural brackets and spinal implant applications established baseline penetration curves across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, application method, and regional production hub dimensions. CAGRs derived from fitted adoption curves adjusted for EU Green Deal mandate acceleration and EU MDR biocompatibility pathway streamlining. Industry-specific inputs included KBA polymer traceability enforcement timelines and ANSM medical device certification backlog data.
ECHA regulatory restriction implementation, titanium alloy additive manufacturing cost trajectories, and fluoropolymer feedstock import disruption are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation of resin demand projections and medical-grade penetration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Coating Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Global Beeswax Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Global PE Films Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Global PU Films Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Acrylic Fine Particle Market