
 Global Lignosulfonate Based Concrete Admixtures Market | 2026-2036
Global Lignosulfonate Based Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lignosulfonate Based Concrete Admixtures Market Foresight
Project finance tied to large infrastructure concessions is narrowing the field of admixture suppliers capable of underwriting multi-year performance contracts. BASF SE leverages its integrated chemical production network to secure raw material certainty across regions. Borregaard LignoTech anchors its position through captive lignin sourcing from Scandinavian pulp operations. Sika AG competes on specification depth, embedding its formulations directly into contractor engineering standards.
Lignosulfonate based concrete admixtures comprise sulfonated lignin derivatives extracted from sulfite pulping liquors, typically functioning as dispersants and water reducers with dosage rates between 0.1% and 0.3% by cement weight to enhance concrete workability and compressive strength development. Modified lignosulfonates command widening specification margins as contractors demand extended slump retention in hot-climate pours. Calcium lignosulfonates dominate volume flows in emerging markets where cost sensitivity shapes procurement. Ready-mix manufacturers represent the fastest-growing end user industry as centralized batching operations standardize admixture dosing protocols.
REACH registration requirements in Europe and GB standards enforcement through SAMR in China constrain market entry for uncertified formulations, while EPA industrial chemical oversight in the United States shapes manufacturing discharge protocols. ECHA substance evaluation cycles are extending compliance timelines for imported lignosulfonate products into European construction supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation redesign costs that erode contract profitability.
Market Dynamics
Multi-year infrastructure concessions are concentrating procurement power among admixture suppliers capable of underwriting performance guarantees across volatile raw material cycles.
Growth Catalysts
- GB Standards Enforcement:SAMR's tightening of cement additive specifications in China is disqualifying uncertified competitors and consolidating volume among compliant producers.
- Hot-Climate Performance Demand:Modified lignosulfonate formulations with extended slump retention are capturing specification share in Southeast Asian highway projects facing tropical pour conditions.
- Centralized Batching Expansion:Ready-mix concrete manufacturers in India are standardizing admixture dosing protocols, creating pull-through demand for calibrated lignosulfonate supply contracts.
Market Restraints
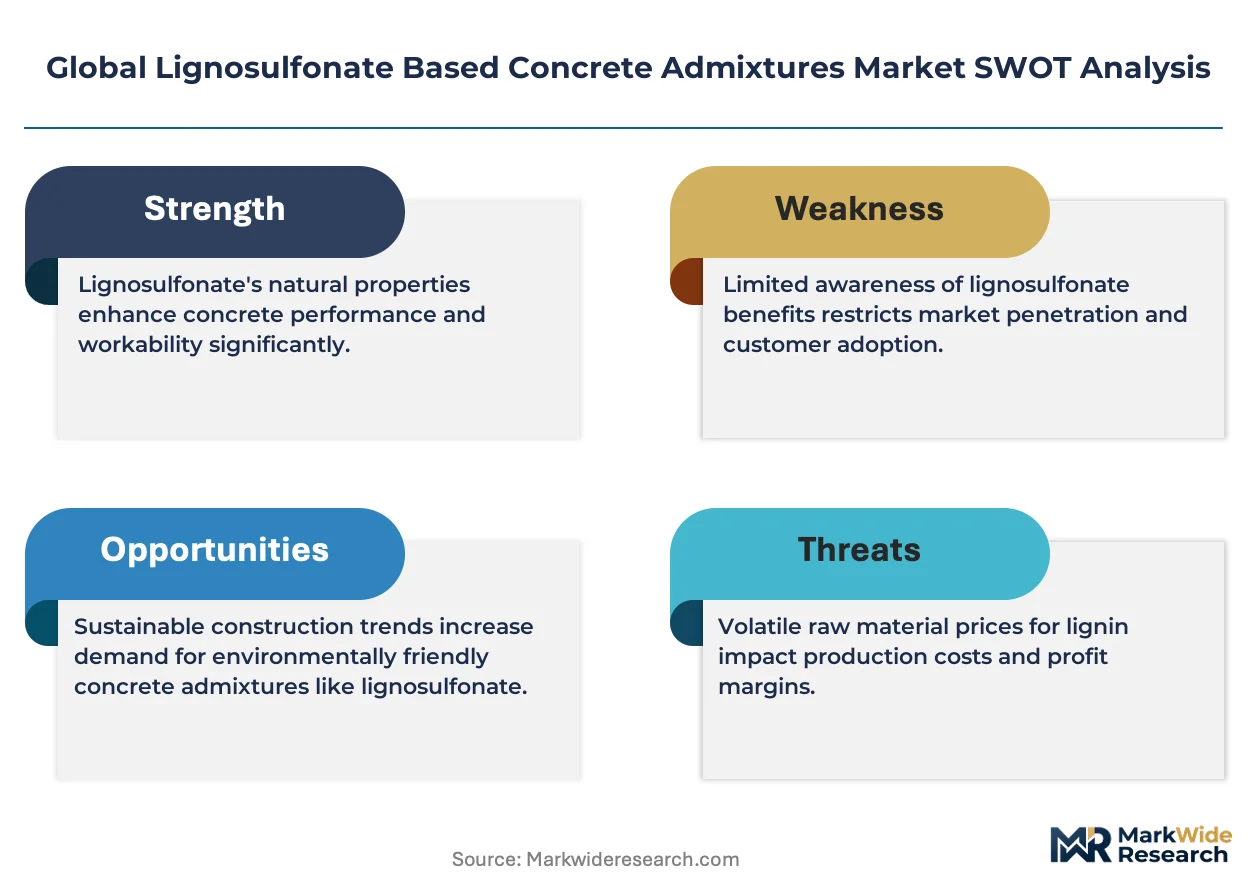
- Captive Lignin Supply Concentration:Scandinavian pulp operations control sulfite liquor feedstock access, creating geographic chokepoints for non-integrated admixture producers.
- Polycarboxylate Ether Substitution:High-performance water reducers are displacing calcium lignosulfonates in premium specification segments where slump retention requirements exceed 90 minutes.
- REACH Registration Friction:ECHA substance evaluation cycles are extending compliance timelines for imported lignosulfonate products, delaying European market entry for new suppliers.
Strategic Opportunities
- Indonesia Infrastructure Pipeline:National highway and urban metro projects are scaling bulk procurement of water-reducing formulations with multi-year offtake structures.
- EU Green Deal Alignment:Bio-based admixture credentials are unlocking specification preference in publicly financed construction tenders across Germany and France.
- Digital Dosing Integration:IoT-enabled batching systems are creating channel openings for admixture suppliers offering real-time performance telemetry alongside chemical supply.
Industry Challenges
- Formulation Redesign Costs:Regulatory divergence between REACH, GB standards, and EPA discharge protocols is forcing parallel certification tracks that erode contract profitability.
- Performance Guarantee Underwriting:Multi-year infrastructure concessions require suppliers to backstop compressive strength development claims across variable cement quality and climate exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lignosulfonate Based Concrete Admixtures Market |
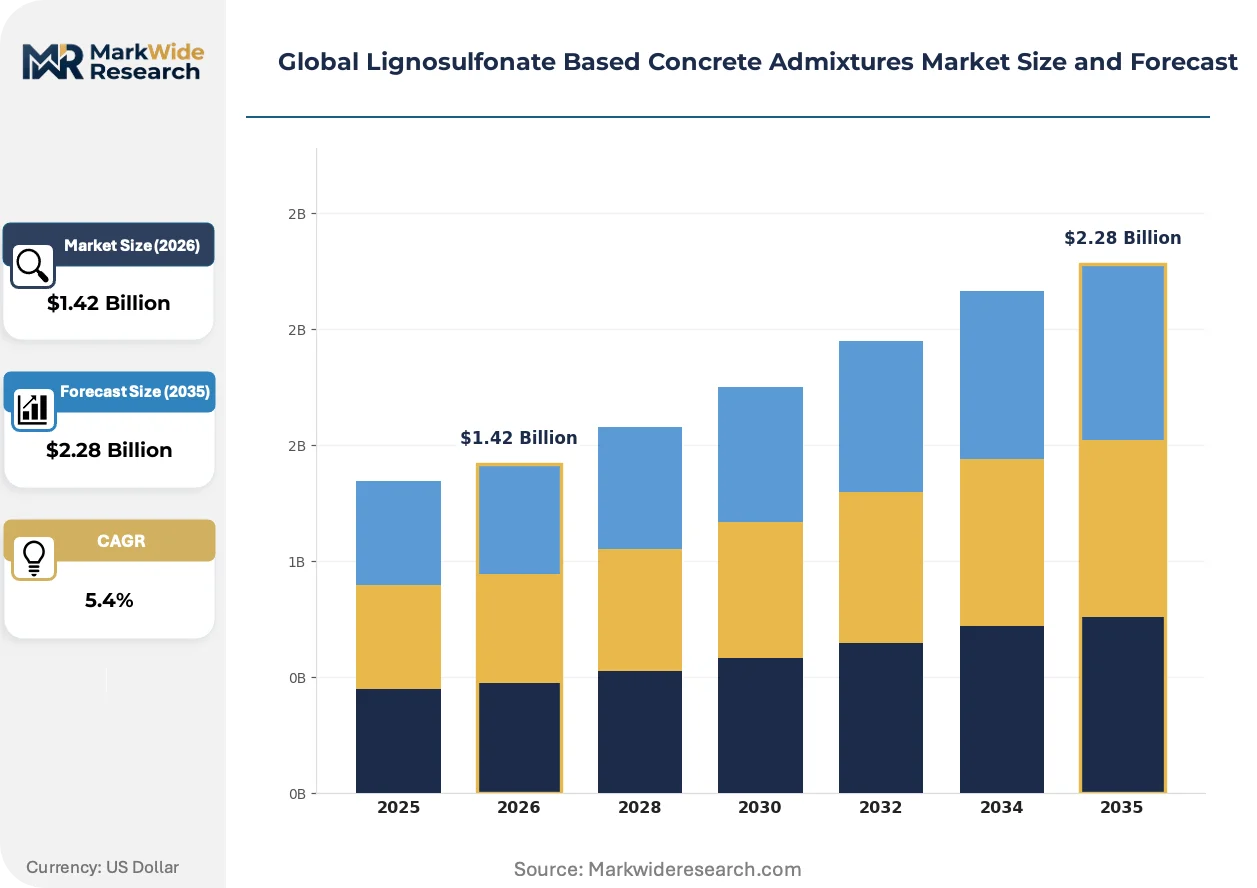
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lignosulfonates, Modified Lignosulfonates, Calcium Lignosulfonates, Sodium Lignosulfonates Application: Weight Reduction, Retardation, Water Reduction, Workability Improvement, Anti-Foaming End User Industry: Building Contractors, Infrastructure Developers, Ready-Mix Manufacturers, Civil Engineering Firms Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesale Suppliers |
| Companies Covered | BASF SE, Borregaard LignoTech, Sika AG, W.R. Grace & Co., CICO Technologies Limited, Fosroc International, CHRYSO Group, Pidilite Industries Limited, Mapei International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lignosulfonate Based Concrete Admixtures Market Shifts & Advancements
Admixture chemistry and supply chain architecture are evolving in response to specification tightening in public infrastructure and the digitization of concrete batching operations.
Modified lignosulfonate technology is migrating from standard dispersant functions toward extended-set formulations engineered for tropical pour conditions. Contractors in Indonesia and Vietnam are specifying these variants for highway segments requiring 120-minute slump retention. The shift is compressing market share for unmodified calcium lignosulfonates in premium application tiers.
ECHA's REACH registration requirements are reshaping European supply chain access for imported lignosulfonate products. Substance evaluation cycles now extend 18-24 months for new market entrants, creating compliance backlogs that favor incumbent registrants. Asian exporters are responding by prioritizing GB standard certification for China domestic volume over European market development.
Centralized procurement by ready-mix manufacturers is consolidating specification-setting power away from individual contractors. Large batching operations in India are unbundling admixture supply from engineering services, compressing supplier margins while demanding calibrated dosing equipment integration. This pattern is most visible in Mumbai and Delhi metropolitan construction corridors where national highway spillover demand concentrates volume.
Global Lignosulfonate Based Concrete Admixtures Market Segmentation
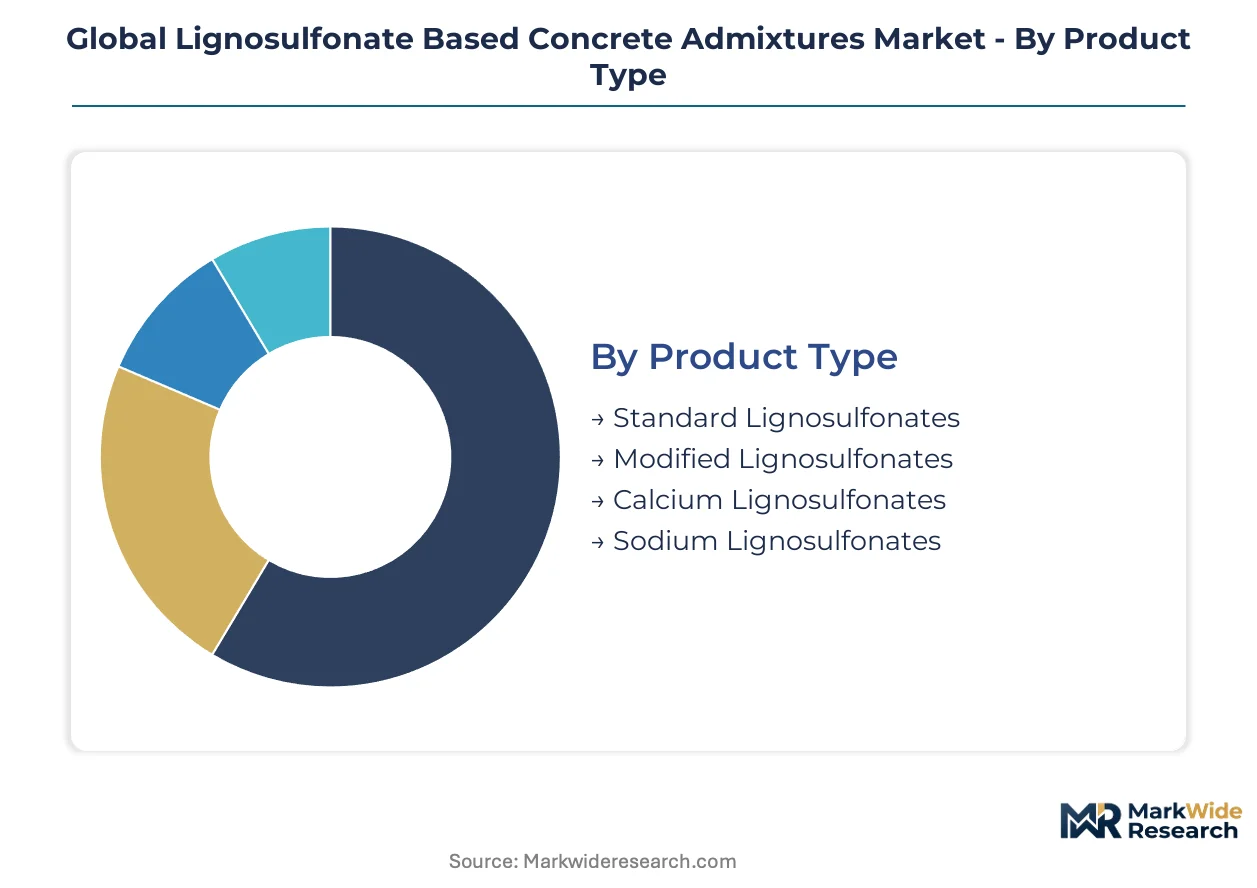
Segmentation in lignosulfonate admixtures reveals how procurement power, specification depth, and supply chain architecture fragment across product chemistry, application function, and customer type. Understanding these fault lines clarifies where margin pools concentrate and where volume commoditizes.
Product Type:
Use-case spectrum spans cost-driven bulk applications to specification-critical infrastructure pours, with chemistry modifications determining performance ceilings and price positioning.
- Standard Lignosulfonates:Unmodified sulfonated lignin derivatives serve as baseline dispersants in routine concrete production. Demand concentrates in India's national highway program where contractors prioritize cost efficiency over extended slump retention for standard pour cycles.
- Modified Lignosulfonates:Chemically engineered variants incorporate grafted polymer chains to extend set retardation and slump retention to 120 minutes. Indonesia's tropical highway segments specify these formulations to combat accelerated hydration in ambient temperatures exceeding 35°C.
- Calcium Lignosulfonates:Calcium salt derivatives dominate emerging market volume flows due to favorable cost-positioning and compatibility with ordinary Portland cement chemistries prevalent in Southeast Asia.
- Sodium Lignosulfonates:Sodium salt forms offer superior solubility in cold-water batching operations, finding niche specification in high-altitude construction across the Himalayan corridor.
Established volume favors Calcium Lignosulfonates; emerging adoption favors Modified Lignosulfonates.
Application:
Margin concentration tracks specification intensity, with multi-functional formulations commanding premium positioning over single-mechanism additives.
- Water Reduction:Core dispersant function enabling 8-12% cement reduction while maintaining compressive strength targets. India's ready-mix sector standardizes this specification across Mumbai and Delhi metropolitan corridors.
- Retardation:Set-delay chemistry critical for mass concrete pours and hot-climate placement. Vietnam's coastal infrastructure projects mandate retardation admixtures for continuous deck pours exceeding 500 cubic meters.
- Workability Improvement:Slump enhancement without water addition, specified for congested reinforcement zones in urban high-rise construction.
- Weight Reduction:Density-modifying formulations for structural lightweight concrete in seismic-design applications.
- Anti-Foaming:Air-entraining control agents preventing strength degradation from excessive void content in high-performance mixes.
Water Reduction captures the deepest procurement volume; Retardation applications are climbing the fastest as tropical infrastructure scales.
End User Industry:
Customer scale and specification authority determine contract structure, with centralized batching operations displacing fragmented contractor procurement.
- Ready-Mix Manufacturers:Centralized batching plants with automated dosing systems generate pull-through demand for calibrated admixture supply contracts. India's top five ready-mix producers now specify multi-year offtake agreements with telemetry integration requirements.
- Infrastructure Developers:Large concession holders underwrite performance guarantees across multi-year projects, narrowing supplier qualification to integrated chemical producers with balance sheet capacity.
- Building Contractors:Fragmented residential and commercial construction segments rely on distributor networks for spot procurement of standard formulations.
- Civil Engineering Firms:Specialized bridge and tunnel contractors specify custom retardation blends for technically demanding pour sequences.
Ready-Mix Manufacturers consolidate procurement authority; Infrastructure Developers concentrate specification-setting power for premium formulations.
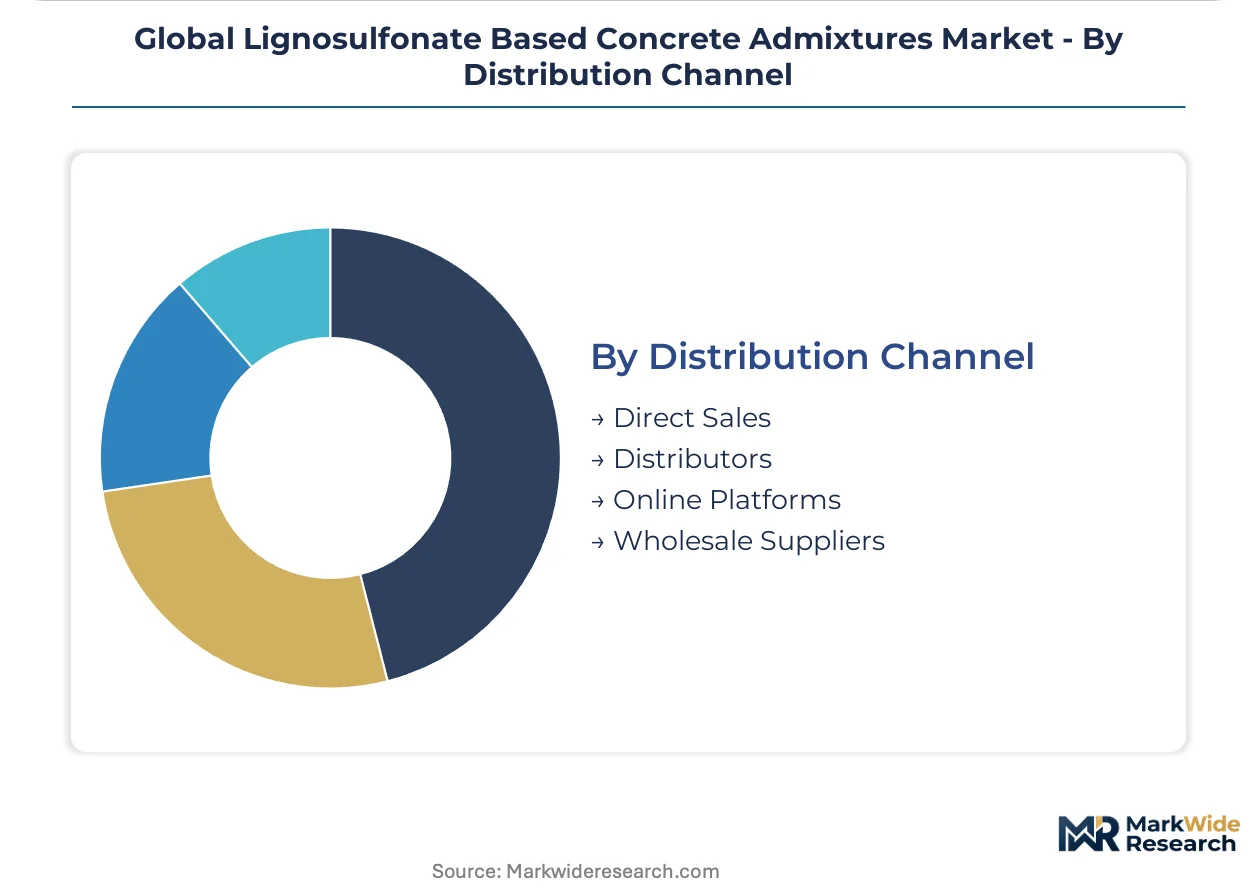
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic concentration of demand.
- Direct Sales:Account-managed relationships serving ready-mix majors and infrastructure concession holders with embedded technical support and performance telemetry.
- Distributors:Regional chemical distributors hold inventory positions for contractor spot demand across secondary cities in India and Indonesia.
- Wholesale Suppliers:Bulk material handlers serving small-batch concrete producers with standard calcium lignosulfonate formulations.
- Online Platforms:Emerging digital procurement channels for standardized product grades with transparent pricing and documented certification.
Direct Sales anchors premium formulation access; Distributors retain relevance for geographically dispersed contractor demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ready-mix manufacturers and infrastructure concession holders concentrate procurement power across four distinct national markets. Each geography presents unique regulatory barriers and demand clustering that shapes supplier qualification requirements.
China
National highway expansion and urban metro construction drive bulk admixture consumption in the Yangtze River Delta. SAMR enforces tightening GB standards on cement additives, disqualifying uncertified producers from state-financed projects. Shanghai's centralized batching corridor standardizes dosing protocols for water-reducing formulations.
India
The national highway program and Delhi-Mumbai metro networks generate multi-year offtake demand for calcium lignosulfonates. BIS certification requirements constrain import channels while favoring domestic compounders. Mumbai's ready-mix corridor consolidates specification-setting authority among five major producers.
Indonesia
Tropical highway segments mandate modified lignosulfonate formulations with 120-minute slump retention for ambient temperatures exceeding 35°C. The country's infrastructure regulator imposes performance guarantees on multi-year concession contracts. Java's urban metro projects anchor procurement concentration in Jakarta and Surabaya metropolitan zones.
Germany
Public construction tenders under the EU Green Deal prioritize bio-based admixture credentials for infrastructure finance eligibility. ECHA REACH registration cycles extend 18-24 months for imported lignosulfonate products, favoring incumbent European registrants. The Rhine-Ruhr industrial corridor hosts specification engineering for extended-set formulations.
United States
EPA industrial chemical discharge protocols shape manufacturing compliance costs for sulfite liquor processing operations. Federal highway funding streams require certified admixture documentation for bridge and interstate projects. Texas and California metropolitan construction corridors concentrate ready-mix batching capacity and dosing standardization.
Global Lignosulfonate Based Concrete Admixtures Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three identifiable tiers. Integrated chemical producers with captive lignin supply anchor the premium segment through performance guarantee underwriting. Regional compounders serving spot contractor demand occupy a fragmented mid-tier. Technology licensors and formulation specialists complete the base. Dominant competitive moves include backward integration into sulfite pulp feedstock and multi-year offtake contracting with telemetry-enabled dosing systems.
Among European-anchored integrated producers, BASF SE and Borregaard LignoTech exemplify the captive-supply archetype through in-house lignin derivative production. Sika AG occupies a position within the specification-engineering tier, embedding formulations directly into contractor engineering standards. These three entities represent distinct strategic postures: chemical network integration, raw material upstream control, and technical service depth.
| Leading Market Players |
|---|
| BASF SE |
| Borregaard LignoTech |
| Sika AG |
| W.R. Grace & Co. |
| CICO Technologies Limited |
| Fosroc International |
| CHRYSO Group |
| Pidilite Industries Limited |
| Mapei International |
| Others |
Supply & Pricing Matrix
The Scandinavian sulfite pulping corridor around Sarpsborg and Kristiansand anchors global lignosulfonate feedstock availability. Captive integration at these Nordic mills translates directly into pricing power over non-integrated compounders in Asia and North America.
Pricing Analysis
Certification level creates the primary spread between REACH-registered formulations and uncertified imports. Three-tier pricing structure across premium, standard, and economy levels tracks compliance depth: extended-set modified lignosulfonates command specification premiums for tropical highway projects, while standard calcium salts face cost compression from polycarboxylate ether substitution in premium tiers. Ready-mix manufacturers in India exhibit highest price sensitivity due to unbundled procurement models, whereas infrastructure concession holders absorb premium pricing for performance-guaranteed supply.
Supply Chain Analysis
Contract manufacturing concentration rests with Scandinavian pulp-integrated producers and Indian domestic compounders serving BIS-certified channels. Raw material flows draw from sulfite liquor streams in Norway, Sweden, and Finland, with secondary sourcing from Brazilian eucalyptus pulping operations. Single-source vulnerability concentrates in Nordic sulfite feedstock access, where Borregaard and Stora Enso operations control merchant lignin availability. Distribution runs through direct account management for ready-mix majors, supplemented by regional chemical distributors for contractor spot demand in secondary Indian and Indonesian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hot-climate infrastructure deployment accelerates specification migration toward modified formulations. Penetration headroom remains substantial across Southeast Asian batching operations still standardizing admixture dosing protocols.
For Market Incumbents: Entrench specification authority through captive lignin supply and embedded telemetry integration at ready-mix plants. Prioritize backward integration into Scandinavian sulfite liquor streams to defend against polycarboxylate ether substitution in premium tiers. Anchor multi-year offtake structures with Jakarta and Mumbai metropolitan batching corridors before non-integrated compounders achieve REACH registration. For New Entrants and Emerging Players: Build out white-space presence in Indonesia's tropical highway segment where modified lignosulfonate demand outruns certified supply. Target Vietnam's coastal infrastructure corridor for retardation formulation entry, leveraging GB standard certification as a stepping stone. Pursue digital dosing integration partnerships as the primary go-to-market angle, bundling real-time performance telemetry with chemical supply to differentiate from commodity distributors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with captive bio-based feedstock and performance guarantee underwriting capacity. Long-term viability hinges on regulatory moat depth across REACH, GB standards, and EPA discharge protocols. Monitor ECHA substance evaluation cycle backlogs as an inflection signal: extended delays favor incumbent registrants, while accelerated approvals could dilute pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfite Liquor Supply | Captive lignin sourcing from Scandinavian pulp operations secures raw material certainty against feedstock chokepoints. |
| REACH Registration Acceleration | ECHA compliance timelines determine European market access for Asian exporters seeking premium specification share. |
| Digital Dosing System Partnerships | IoT-enabled batching integration creates channel lock-in with India's consolidating ready-mix manufacturers. |
| Extended-Set Formulation R&D | Modified lignosulfonate chemistry for 120-minute slump retention captures tropical infrastructure specification. |
| Multi-Year Offtake Contracting | Performance-guaranteed supply structures align with Indonesia's infrastructure concession financing requirements. |
Research Methodology
A standing panel of ready-mix plant managers, infrastructure procurement leads, admixture technical directors, and ECHA regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from customs trade databases, SEC filings of integrated chemical producers, SAMR GB standard bulletins, and European construction tender databases. Bottom-up volume estimates from national highway and metro project pipelines were triangulated against top-down chemical consumption models.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product chemistry tier, application function, end-user industry concentration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume trajectories incorporating cement consumption forecasts and admixture penetration rates. Key inputs included SAMR enforcement intensity indices, ECHA registration queue status, and tropical infrastructure project award pipelines.
Stress conditions across raw material cost volatility, REACH registration delays, and polycarboxylate ether substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement continuity and infrastructure finance availability. Quarterly review of ECHA substance evaluation cycle lengths, SAMR certification revocation notices, and Indonesian highway concession award velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market