
 Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market | 2026-2036
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market Foresight
Specialty gas distribution is fragmenting as regional producers build direct supply lines to semiconductor fabs. Linde plc leverages its global merchant gas infrastructure to sustain long-term contracts with leading chipmakers. SK Materials anchors East Asian supply through integrated NF3 production tied to domestic display panel manufacturers. Mitsui Chemicals Inc. competes on high-purity fluorine gas specifications for advanced node semiconductor etching.
Nitrogen trifluoride and fluorine gas are high-purity fluorinated compounds used primarily for chamber cleaning and plasma etching in semiconductor fabrication, with NF3 offering a thermal decomposition temperature near 200°C and fluorine gas providing atomic fluorine for reactive ion etching processes. The application dimension shows semiconductors commanding the dominant value share as logic and memory fabs scale 3nm and below processes, while LCD display manufacturing retains volume importance through ongoing OLED transition cycles. Specialty gases within the product type dimension capture expanding margin pools as fabs demand sub-ppb impurity grades for EUV lithography companion steps.
The EPA regulates fluorinated gas emissions under the Clean Air Act in the United States, while the EU F-Gas Regulation mandates phasedown of hydrofluorocarbon and perfluorocarbon equivalents with direct bearing on NF3 reporting obligations. Japan's METI enforces high-pressure gas safety standards that shape fluorine gas cylinder specifications and transport protocols for electronics suppliers. Stakeholders must monitor how tightening fluorinated gas phase-down schedules in multiple jurisdictions reshape capital allocation toward abatement technology and alternative chemistries.
Market Dynamics
The EU F-Gas Regulation's phasedown mandates are forcing semiconductor fabs to reconfigure chamber cleaning chemistries, compressing NF3 consumption windows while accelerating fluorine gas adoption for atomic-level etching precision.
Growth Catalysts
- 3nm Node Scaling:Logic foundries in Taiwan and South Korea require escalating fluorine gas volumes for atomic layer etching of gate-all-around transistors. Sub-ppb purity specifications expand specialty gas margin pools.
- EU F-Gas Phasedown:The regulation mandates hydrofluorocarbon equivalent reductions, directing capital toward abatement retrofits and alternative fluorinated compound qualification programs.
- OLED Display Transition:Korean and Chinese panel manufacturers sustain NF3 demand for chemical vapor deposition chamber maintenance during Gen 8.5+ fab ramp-ups.
Market Restraints
- Fluorine Supply Concentration:Merchant fluorine production clusters in Germany and Japan create geographic vulnerability for fabs outside these zones. Transport of high-pressure fluorine cylinders faces stringent modal restrictions.
- Abatement Capital Intensity:Point-of-use thermal scrubbers and wet scrubber systems for NF3 decomposition require seven-figure installation commitments per fab bay.
- Carbon Tetrafluoride Substitution:Legacy C4F8 etching chemistries retain cost advantages in mature node production, delaying fluorine gas penetration at 28nm and above.
Strategic Opportunities
- Indian Semiconductor Mission:The country's PLI scheme for electronics manufacturing attracts specialty gas distributors to establish localized NF3 blending and cylinder filling infrastructure.
- EUV Resist Processing:Fluorine-based plasma cleaning of EUV pellicles and optics creates incremental demand beyond traditional chamber applications.
- On-Site Fluorine Generation:Electrolytic fluorine cells at fab locations eliminate cylinder logistics and reduce transport-related regulatory exposure.
Industry Challenges
- High-Purity Gas Handling Expertise:Sub-ppb contamination control requires specialized technicians trained in semiconductor-grade cylinder conditioning and valve manifold protocols.
- Multi-Jurisdiction Compliance Synchronization:Fabs operating across EPA, EU F-Gas, and METI jurisdictions face conflicting reporting timelines and emission calculation methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market |
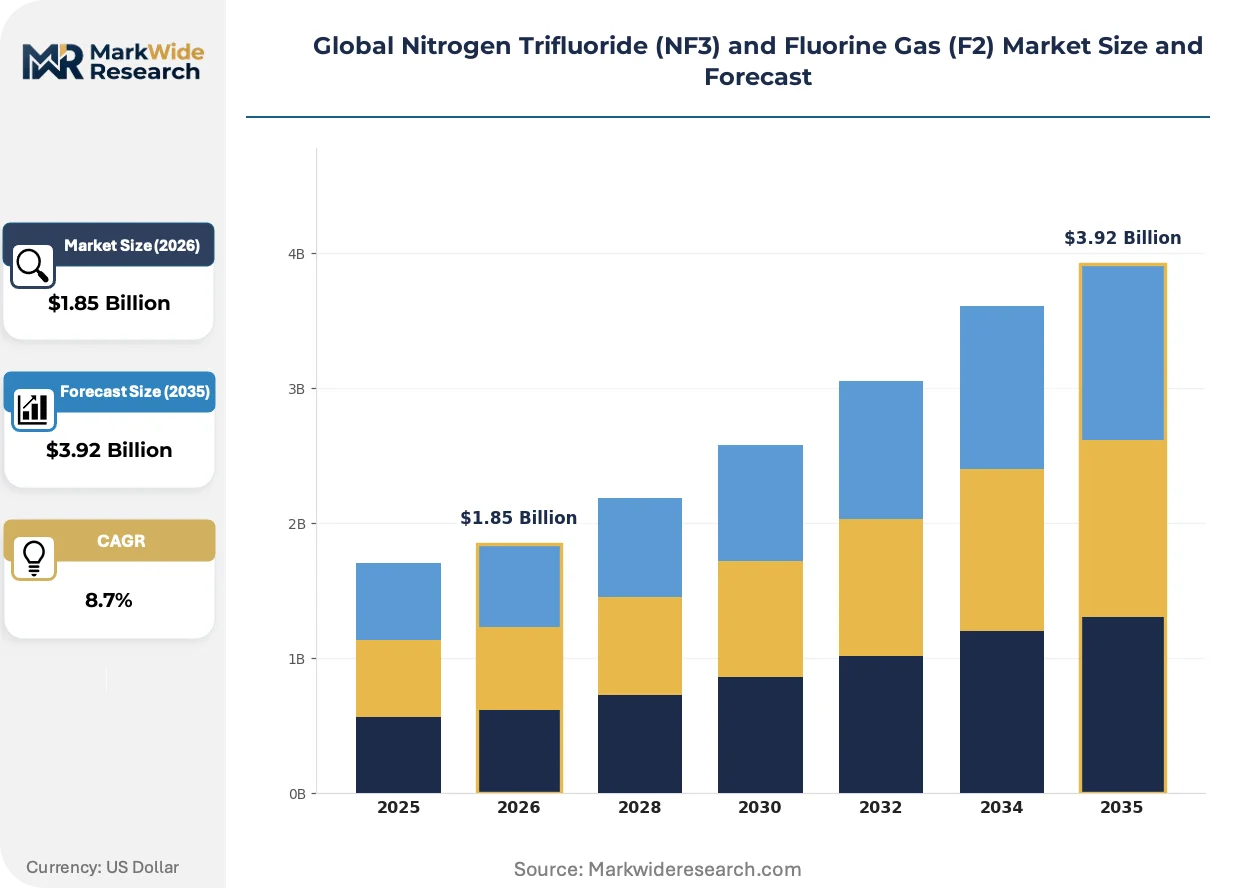
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen Trifluoride, Fluorine Gas, Specialty Gases, Others Application: Semiconductors, LCD Display Manufacturing, Metal Processing, Chemical Synthesis End User: Electronics, Automotive, Chemicals, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Linde plc, SK Materials, Mitsui Chemicals Inc, Central Glass Co. Ltd, Formosa Plastics Corporation, Air Products and Chemicals Inc., OCI Company Ltd, Kanto Denka Kogyo Co. Ltd, Hyosung Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market Shifts & Advancements
Remote plasma source technology and on-site generation systems are fragmenting traditional merchant gas distribution models, while regulatory stringency accelerates chemistry substitution cycles.
Remote plasma cleaning systems utilizing fluorine gas are rendering obsolete conventional thermal NF3 decomposition for chamber cleaning. Memory fabs in South Korea deploy these sources to reduce greenhouse gas emission intensity per wafer pass. The shift compresses NF3 volume commitments in long-term supply agreements.
The EU F-Gas Regulation's 2024-2030 phasedown trajectory tightens hydrofluorocarbon equivalent allocation mechanisms. Semiconductor fabs must now quantify NF3 emissions through mass-balance reporting or install point-of-use abatement. German and French facilities face the steepest reduction trajectories, accelerating fluorine gas qualification for etching applications.
Integrated gas supply contracts now bundle cylinder management, abatement equipment, and emission verification services. Korean foundries negotiate these packages to simplify multi-site compliance. The model displaces transactional cylinder resale and concentrates procurement authority with facilities engineering teams rather than purchasing departments.
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market Segmentation
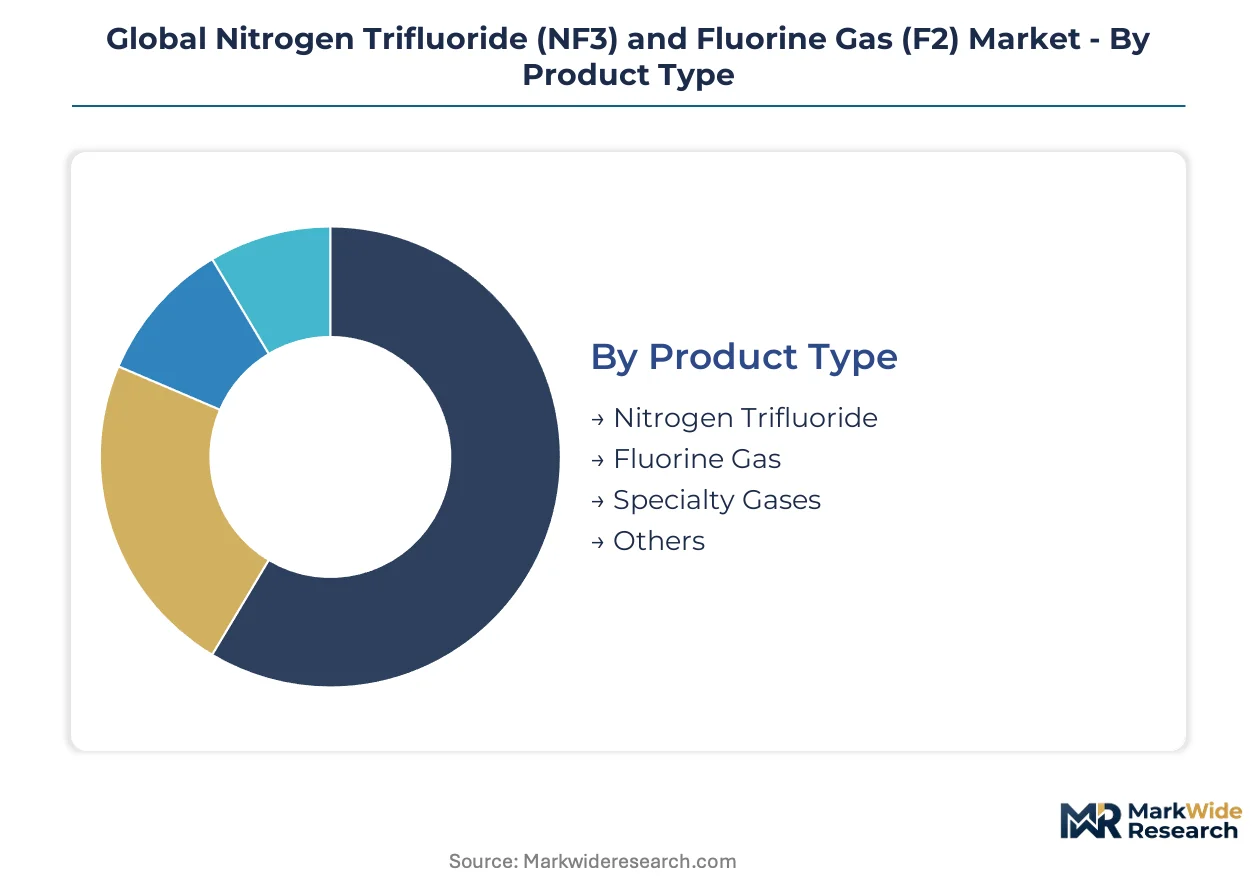
Segmentation in this market tracks how purity specifications, process integration depth, and regulatory exposure reshape procurement patterns across semiconductor and display manufacturing value chains. Understanding these divisions clarifies where margin pools concentrate and how supply relationships restructure.
Product Type:
Use-case spectrum spans thermal chamber cleaning, atomic-level etching precision, and ultra-high-purity companion processes.
- Nitrogen Trifluoride:Thermal decomposition near 200°C enables plasma-enhanced chamber cleaning in memory and logic fabs. South Korean semiconductor facilities anchor consumption volumes through long-term supply agreements tied to 3nm node ramp-ups.
- Fluorine Gas:Atomic fluorine delivery supports reactive ion etching with sub-angstrom precision control. Taiwan foundries drive qualification programs for gate-all-around transistor architectures, displacing legacy chemistries in advanced node production.
- Specialty Gases:Sub-ppb impurity grades serve EUV lithography companion steps and critical surface preparation protocols.
- Others:Blended fluorinated mixtures address niche abatement and process optimization requirements in mature fabs.
Established volume favors Nitrogen Trifluoride; emerging adoption favors Fluorine Gas.
Application:
Process complexity and node geometry determine fluorinated gas selection across manufacturing stages.
- Semiconductors:Logic and memory fabrication commands premium pricing through sub-ppb purity mandates. EUV pellicle cleaning and atomic layer etching expand fluorine gas demand beyond traditional chamber maintenance.
- LCD Display Manufacturing:Gen 8.5+ chemical vapor deposition chambers require NF3 for periodic cleaning during OLED transition cycles. Chinese and Korean panel producers sustain procurement volumes through integrated gas supply contracts.
- Metal Processing:High-purity fluorine enables precision surface treatment for aerospace and medical device alloys.
- Chemical Synthesis:Fluorination reactions in agrochemical and pharmaceutical intermediates utilize cylinder-supplied fluorine gas.
Semiconductors concentrate value capture; display manufacturing sustains volume throughput.
End User:
Customer technical sophistication shapes specification stringency and supplier relationship structures.
- Electronics:Semiconductor and display manufacturers impose the most demanding purity protocols. Integrated gas supply contracts bundle cylinder management, abatement equipment, and emission verification services.
- Automotive:Power electronics and sensor manufacturing drive modest fluorinated gas consumption with standardized purity grades.
- Chemicals:Fluorochemical producers utilize merchant fluorine for captive downstream synthesis operations.
- Pharmaceuticals:API fluorination processes require validated supply chains with batch documentation and audit trails.
Electronics commands supplier attention; pharmaceuticals offers margin expansion through qualification barriers.
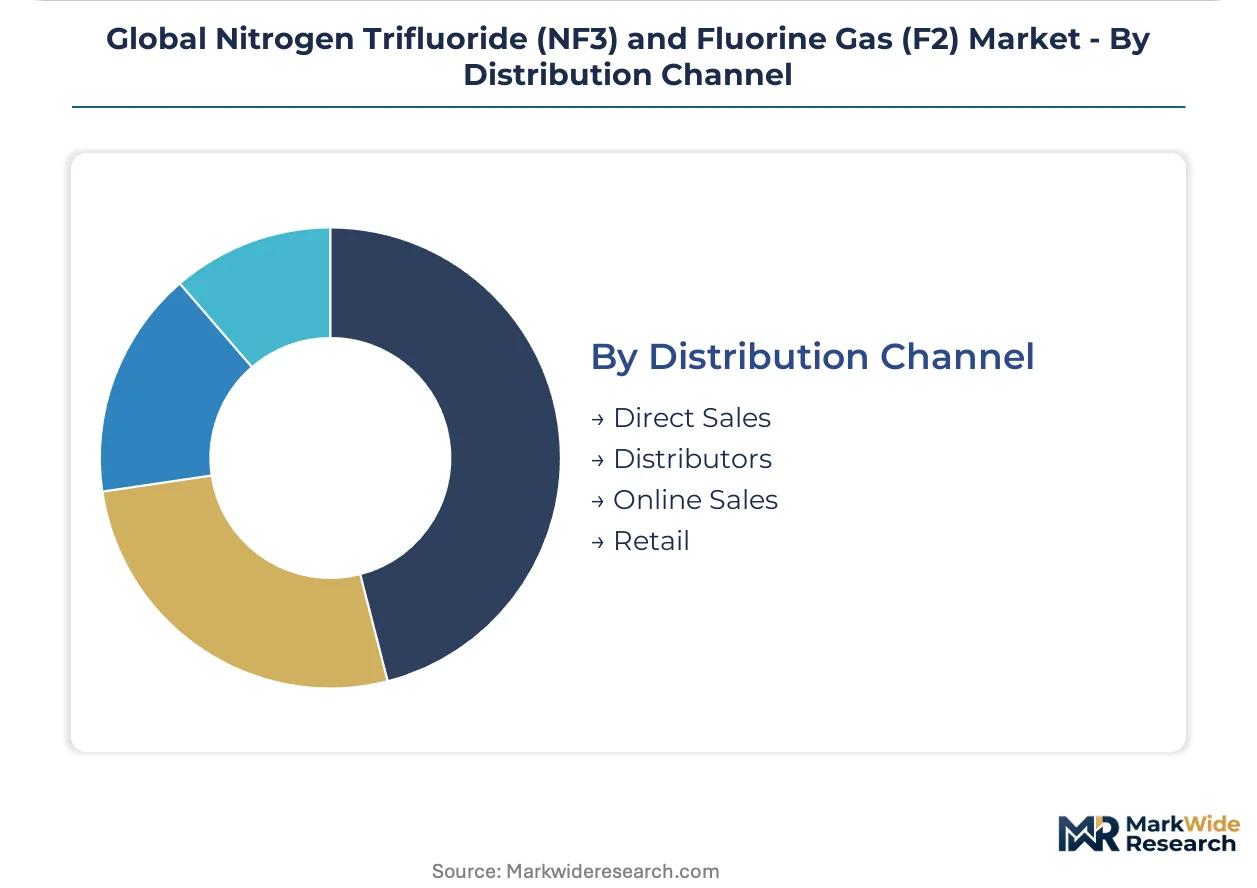
Distribution Channel:
Supply chain configuration balances inventory risk, technical service intensity, and regulatory compliance burden.
- Direct Sales:Long-term contracts with foundries and panel manufacturers include on-site storage, gas management systems, and abatement infrastructure. Linde plc and regional producers compete through integrated service bundling.
- Distributors:Regional gas specialists handle cylinder logistics for smaller semiconductor fabs and metal processors.
- Online Sales:Standard-grade fluorinated compounds for research and pilot-scale chemical synthesis.
- Retail:Limited to small-volume laboratory and educational applications with minimal technical service requirements.
Direct sales deepens customer integration; distributors retain relevance in geographic coverage gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Yantai pipeline corridor underwrites China's fluorinated gas logistics, connecting Bohai Sea production bases to Yangtze River Delta fabs. This infrastructure backbone enables just-in-time delivery to semiconductor clusters without high-pressure cylinder transport.
South Korea
Memory foundries in Pyeongtaek and Yongin drive NF3 consumption for 3nm DRAM and NAND chamber cleaning. The Ministry of Trade, Industry and Energy enforces high-pressure gas safety codes that shape cylinder specifications. Samsung Electronics and SK Hynix anchor demand through integrated gas supply contracts bundling abatement infrastructure.
United States
Logic fabs in Arizona and Texas escalate fluorine gas procurement for gate-all-around transistor etching. The EPA Clean Air Act mandates mass-balance NF3 emission reporting from semiconductor facilities. Intel's Chandler and Austin sites concentrate domestic demand through long-term merchant gas agreements with point-of-use scrubber installations.
Japan
Materials suppliers in Chiba and Ibaraki prefectures sustain captive fluorine production for semiconductor and display customers. METI high-pressure gas safety standards dictate transport protocols for cylinder logistics. Tokyo Electron and Shin-Etsu Chemical anchor procurement through backward-integrated gas management systems at Tsukuba and Kitaibaraki.
Germany
Merchant fluorine production clusters in North Rhine-Westphalia supply fabs across the EU with atomic fluorine for advanced etching. The EU F-Gas Regulation imposes steep hydrofluorocarbon equivalent reduction trajectories through 2030. Infineon's Dresden fab and Bosch's Reutlingen facility face compressed NF3 consumption windows while accelerating fluorine gas qualification programs.
Taiwan
Foundries in Hsinchu and Tainan Science Parks command premium fluorinated gas specifications for EUV lithography companion processes. The National Science and Technology Council coordinates industrial gas safety inspections across science park zones. TSMC's Nanjing and Tainan sites concentrate regional demand through direct sales contracts with sub-ppb purity mandates.
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated gas supply models that bundle cylinder management, abatement equipment, and emission verification services. Merchant gas distributors compete with regional producers building direct fab linkages. Three archetypes dominate: global industrial gas majors with merchant infrastructure, Asian chemical conglomerates with captive electronics demand, and specialty gas specialists focused on sub-ppb purity grades. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Among global industrial gas majors, Linde plc anchors the premium-tier vector through long-term contracts with leading chipmakers. SK Materials exemplifies the Asian conglomerate archetype, leveraging integrated NF3 production tied to domestic display panel manufacturers. Mitsui Chemicals Inc occupies a position within the specialty gas tier, competing on high-purity fluorine gas specifications for advanced node semiconductor etching.
| Leading Market Players |
|---|
| Linde plc |
| SK Materials |
| Mitsui Chemicals Inc |
| Central Glass Co. Ltd |
| Formosa Plastics Corporation |
| Air Products and Chemicals Inc. |
| OCI Company Ltd |
| Kanto Denka Kogyo Co. Ltd |
| Hyosung Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese NF3 production is compressing spot pricing while forcing Korean and Japanese suppliers toward long-term contract anchoring with integrated service bundling. This utilization asymmetry between Bohai Sea production bases and East Asian fab demand clusters reshapes how suppliers compete on price versus technical service depth.
Pricing Analysis
Volume-discount tiering structures separate sub-ppb specialty grades for EUV lithography from standard semiconductor-grade NF3 and commodity fluorine for display manufacturing. Price differentiation hinges on impurity certification thresholds and cylinder management service bundling. Cost compression in standard-grade NF3 is intensifying because Chinese merchant producers are expanding direct-to-fab sales. Memory foundries in South Korea exhibit the lowest price sensitivity due to process-critical purity mandates, while metal processors and chemical synthesis buyers drive hard volume negotiations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for fluorinated gas distributors serving cross-border semiconductor fabs. Merchant fluorine production concentrates in Germany, Japan, and China, while NF3 synthesis clusters in South Korea and China. The supply chain draws from elemental fluorine feedstock, high-pressure cylinder alloys, and abatement catalyst materials. Single-source vulnerability persists for sub-ppb purification technology. Distribution runs through direct sales contracts with integrated gas management systems at major foundries, supplemented by regional distributors for smaller fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Korean and Taiwanese foundries consolidate procurement authority within facilities engineering teams, displacing traditional purchasing departments and demanding bundled abatement-infrastructure contracts.
For Market Incumbents: Build switching-cost moats through captive abatement equipment installations and on-site fluorine generation cells that embed suppliers within fab infrastructure. Deepen cylinder conditioning expertise to defend against emerging Chinese merchant producers competing on price. Expand backward integration into high-purity fluorine feedstock production in Germany and Japan to secure supply continuity against geopolitical disruption. For New Entrants and Emerging Players: Indian semiconductor clusters under the PLI scheme offer white-space penetration with localized NF3 blending infrastructure and cylinder filling operations. Target pharmaceutical fluorination applications with validated batch documentation capabilities that incumbent industrial gas majors underserve. Pursue joint venture structures with domestic chemical distributors to bypass capital-intensive merchant gas infrastructure requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across on-site fluorine generation and point-of-use abatement technology sub-segments, favoring asset-heavy integrated suppliers over pure merchant distributors. Five-to-ten-year viability hinges on regulatory compliance service capabilities rather than commodity gas volume exposure. Acquisition targets should display captive abatement technology IP or exclusive fab-site service contracts. Watch EU F-Gas phasedown enforcement velocity as the critical demand-shift indicator for fluorine gas versus NF3 substitution trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Fluorine Generation Deployment | Eliminates cylinder logistics and reduces EU F-Gas regulatory exposure for German fabs. |
| Integrated Gas Supply Contract Expansion | Bundles abatement infrastructure with NF3 delivery, locking Korean foundries into long-term relationships. |
| Sub-ppb Purity Certification Investment | Captures EUV lithography companion process margins as TSMC and Samsung scale advanced nodes. |
| Indian Localization Partnership | Positions suppliers for PLI-scheme semiconductor manufacturing growth in Gujarat and Tamil Nadu clusters. |
| Abatement Technology Acquisition | Secures thermal scrubber and wet scrubber IP to meet EPA Clean Air Act point-of-use mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with specialty gas procurement managers, fab facilities engineers, and regulatory compliance officers at semiconductor manufacturers, combined with secondary validation through EPA emission filings, EU F-Gas Regulation implementation reports, and METI high-pressure gas safety standards. Semiconductor-grade gas distributor financial disclosures and customs trade data for fluorinated compounds provided additional triangulation anchors. Bottom-up fab consumption estimates and top-down merchant gas revenue analysis were cross-referenced for consistency.
Forecast inputs span product type purity tiers, application process complexity across logic and memory nodes, end-user technical sophistication levels, and distribution channel integration depth. Modeled segmentation tracks NF3 versus fluorine gas substitution dynamics, EUV lithography penetration rates, and regional regulatory phasedown schedules across the analysis window. CAGRs derive from capacity expansion announcements, fab build-out pipelines, and chemistry qualification timelines specific to gate-all-around transistor etching requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese merchant producers or accelerated EU F-Gas enforcement would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Helium Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Argon Gas Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Syngas Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Global Liquid Nitrogen Market