
 Precast Gels Market | 2026-2036
Precast Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Gels Market Analytics
Specialized electrophoresis technician availability is unwinding manufacturing capacity expansion plans across North America and Europe. Thermo Fisher Scientific dominates the high-throughput diagnostics channel through captive distribution networks. Bio-Rad Laboratories anchors the academic research segment with deep product specialization in PAGE systems. Danaher Corporation leverages its Life Sciences platform to extend cross-selling opportunities into pharmaceutical quality control labs.
Precast gels are factory-cast polyacrylamide or agarose matrices with defined pore sizes and buffer compositions, manufactured under controlled conditions to eliminate batch-to-batch variability in protein and nucleic acid separation. These gels serve as standardized consumables in sodium dodecyl sulfate-polyacrylamide gel electrophoresis (SDS-PAGE) and native PAGE workflows, ensuring reproducible molecular weight resolution for research and diagnostic applications. Synthetic gels now lead the product landscape due to their superior mechanical stability and consistent cross-linking density, while hybrid gels represent the fastest-growing category as manufacturers combine natural polymer biocompatibility with synthetic durability. The biotechnology application segment captures the deepest margin pools, driven by process analytical technology requirements in biopharmaceutical development.
The FDA enforces current Good Manufacturing Practice standards for diagnostic-grade precast gels, while the EPA regulates acrylamide monomer disposal from manufacturing facilities; ISO 13485 certification shapes market access for clinical diagnostic applications in Europe and Asia. The EU In Vitro Diagnostic Regulation is elevating conformity assessment burdens for gel suppliers targeting European hospital laboratories. Stakeholders must monitor evolving pharmacopeial monographs and regional chemical substance restrictions to sustain product registration portfolios.
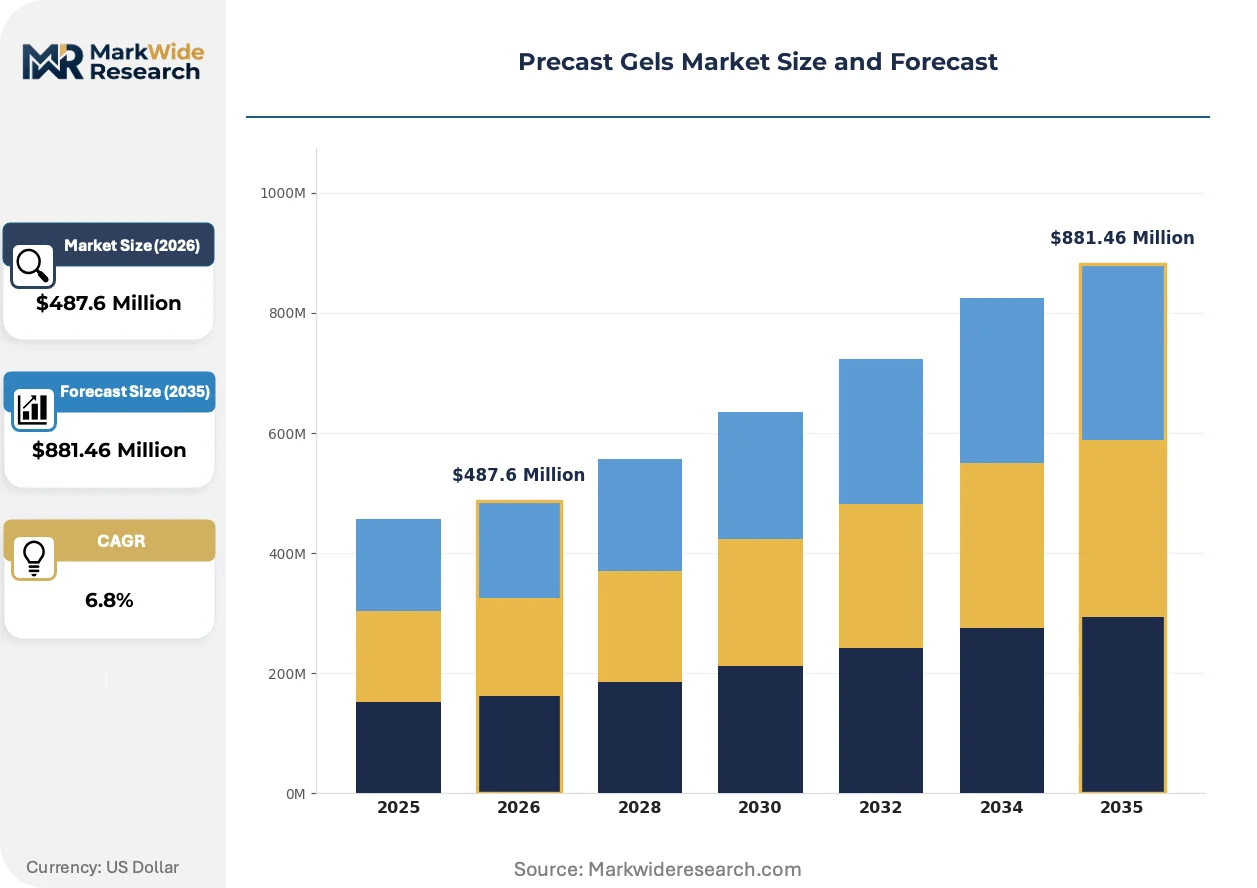
Market Dynamics
Academic research institutes are expanding their procurement of precast gel systems for proteomics workflows, tightening the link between manufacturing capacity and specialized electrophoresis technician availability across North America and Europe.
Growth Catalysts
- Biotechnology process analytical technology requirements:Biopharmaceutical developers are embedding precast gels into quality-by-design frameworks for monoclonal antibody characterization. This institutionalizes consumable pull-through from development into commercial manufacturing.
- FDA Good Laboratory Practice guideline updates:The tightened quality documentation requirements for electrophoresis consumables are forcing laboratory consolidation around prequalified, factory-validated gel suppliers.
- Boston and San Diego biotech corridor concentration:Venture-funded protein therapeutics startups are clustering procurement decisions within these hubs, creating localized demand density that justifies dedicated distribution infrastructure.
Market Restraints
- Acrylamide monomer disposal costs:EPA hazardous waste regulations elevate manufacturing facility compliance burdens, compressing margins for domestic production relative to imported alternatives.
- Specialized technician scarcity:The unwinding of manufacturing capacity expansion plans across North America and Europe traces directly to electrophoresis technician pipeline gaps in vocational training systems.
- Cast-your-own gel persistence in cost-sensitive segments:Academic laboratories with in-house polymerization expertise continue substituting manual preparation for precast purchases where budget constraints override convenience premiums.
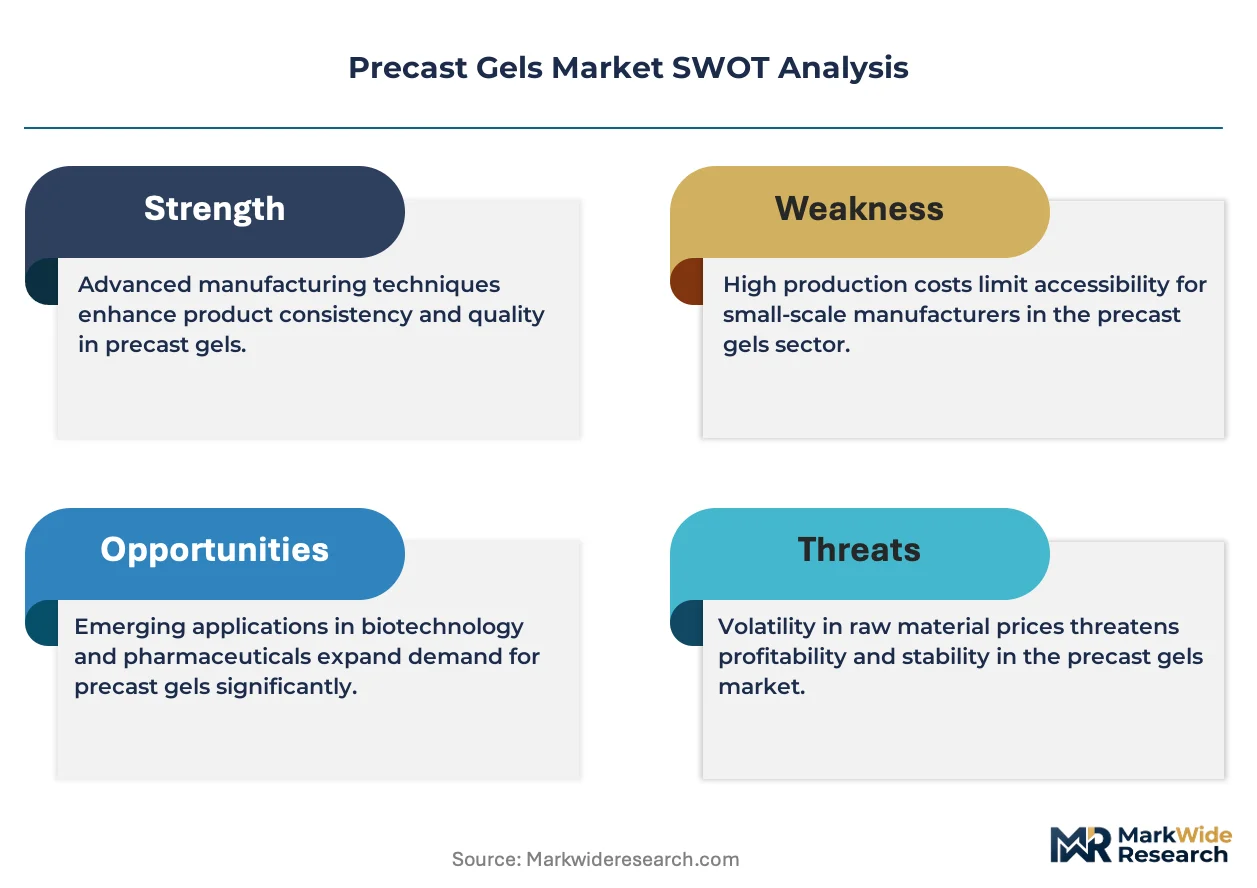
Strategic Opportunities
- EU In Vitro Diagnostic Regulation compliance services:European hospital laboratories face elevated conformity assessment burdens, creating white space for gel suppliers bundling regulatory documentation with product shipments.
- Hybrid gel technology convergence:Manufacturers combining natural polymer biocompatibility with synthetic durability are unlocking cell culture and tissue engineering applications beyond traditional electrophoresis.
- Pharmaceutical quality control lab channel development:Cross-selling opportunities into this segment remain underdeveloped relative to academic anchoring, particularly for suppliers with diagnostic-grade certification.
Industry Challenges
- ISO 13485 certification timeline compression:Clinical diagnostic market access in Europe and Asia requires quality management system validation that stretches 18-24 months, delaying revenue recognition for new entrants.
- Legacy PAGE system integration complexity:Pre-existing Bio-Rad and Thermo Fisher instrument bases create switching friction for alternative gel formats, requiring adapter development and protocol revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Gels Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gels, Synthetic Gels, Hybrid Gels, Bioactive Gels Application: Biotechnology, Pharmaceuticals, Diagnostics, Research End User: Laboratories, Hospitals, Pharmaceutical Companies, Research Institutes Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Danaher Corporation, GenScript, Thermo Fisher Scientific Inc., Takara Bio, Inc., NIPPON Genetics, Bio-Rad Laboratories, Inc., Lonza Group AG, Agilent Technologies, Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Gels Market Evolving Landscape
Synthetic gel formulations are capturing preference share from traditional matrices as manufacturers engineer mechanical stability and cross-linking consistency into standardized consumables.
Gradient pore synthetic gels are supplanting single-percentage formulations in high-resolution proteomics workflows. Core facilities at Massachusetts Institute of Technology and Scripps Research Institute have transitioned procurement to these products. The shift is compressing demand for manual casting expertise while elevating factory quality control to a competitive differentiator.
REACH authorization requirements for acrylamide monomer handling are restructuring European manufacturing footprints. ECHA substance restriction proposals are forcing reformulation investments. German and Swiss suppliers are responding by relocating polymerization steps to non-EU production sites while maintaining EU distribution hubs.
Consolidated procurement through group purchasing organizations is displacing individual laboratory purchasing authority in United States academic medical centers. Thermo Fisher and Bio-Rad field service contracts now bundle gel replenishment with instrument maintenance. This concentration is most visible in Boston's Longwood Medical Area and San Diego's Torrey Pines cluster.
Precast Gels Market Segmentation
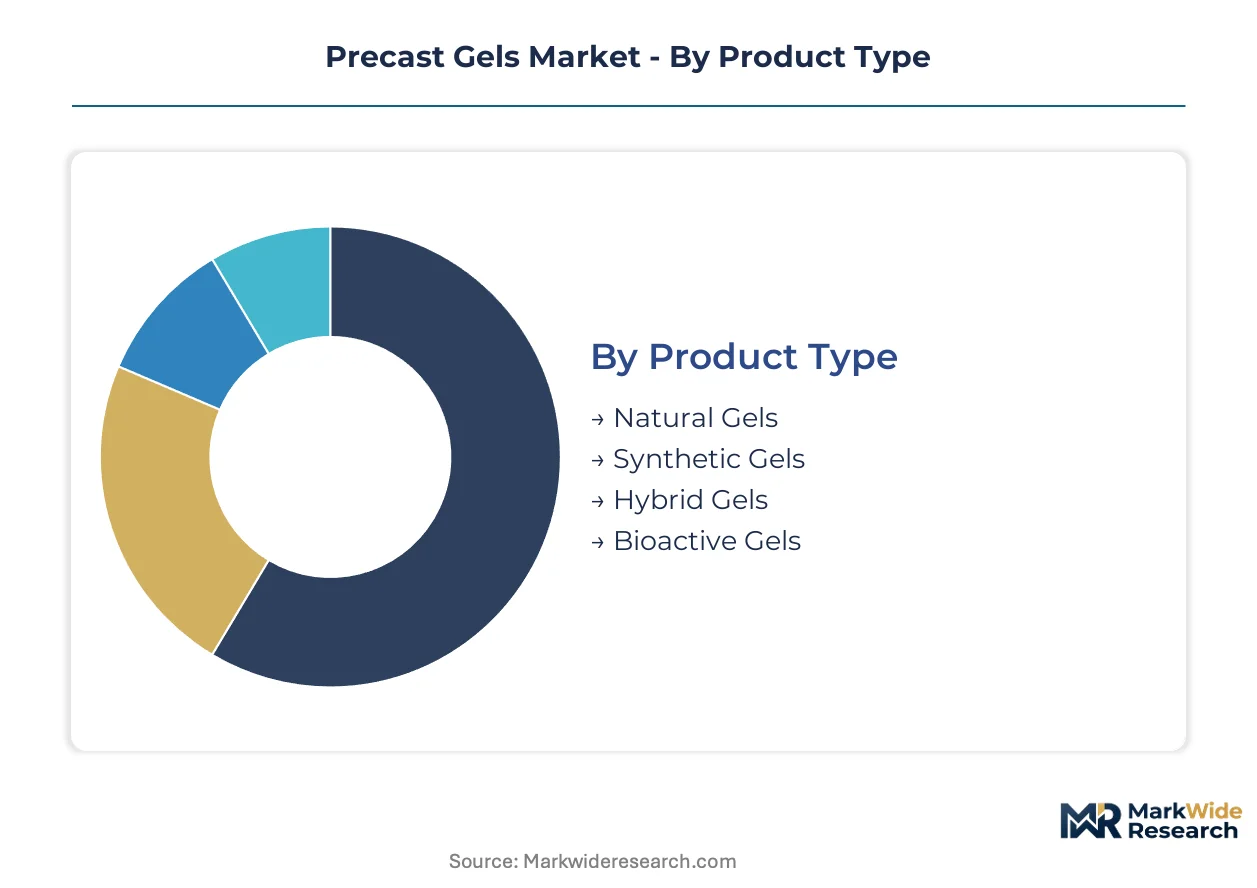
Precast gel procurement patterns diverge sharply across technical specifications, institutional settings, and supply chain configurations. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize certification investments and channel development.
Product Type:
Margin accretion clusters in formulations that resolve the mechanical stability versus biocompatibility tradeoff, with hybrid architectures commanding premium positioning.
- Synthetic Gels:Factory-cast polyacrylamide matrices with defined cross-linking densities deliver batch-to-batch consistency for SDS-PAGE workflows. Massachusetts Institute of Technology core facilities have standardized procurement on gradient-pore synthetic formulations, compressing demand for manual casting expertise while elevating factory quality control to a competitive differentiator.
- Hybrid Gels:Manufacturers combine natural polymer biocompatibility with synthetic durability, unlocking cell culture and tissue engineering applications beyond traditional electrophoresis. Scripps Research Institute has transitioned procurement to these products for high-resolution proteomics workflows, with formulation investments accelerating fastest in this category.
- Natural Gels:Agarose-based matrices retain share in nucleic acid separation protocols where biocompatibility outweighs mechanical handling requirements.
- Bioactive Gels:Functionalized surfaces for specialized cell migration and adhesion studies occupy niche positions in regenerative medicine research.
The dominant share belongs to Synthetic Gels, while Hybrid Gels are closing the gap fastest.
Application:
Process analytical technology mandates in biopharmaceutical development are institutionalizing consumable pull-through from R&D into commercial manufacturing.
- Biotechnology:Monoclonal antibody characterization workflows embed precast gels into quality-by-design frameworks, with Boston and San Diego biotech corridors clustering procurement decisions around validated suppliers.
- Pharmaceuticals:Quality control laboratories require diagnostic-grade certification and ISO 13485 compliance, creating switching friction against academic-anchored suppliers.
- Diagnostics:FDA Good Laboratory Practice guideline updates force consolidation around prequalified, factory-validated gel sources.
- Research:Academic laboratories with in-house polymerization expertise continue substituting manual preparation where budget constraints override convenience premiums.
Biotechnology commands the deepest margin pools, though Pharmaceuticals is expanding most quickly as regulatory documentation bundles gain traction.
End User:
Procurement authority is concentrating through consolidated purchasing mechanisms that favor suppliers with integrated field service capabilities.
- Pharmaceutical Companies:Cross-selling opportunities into quality control labs remain underdeveloped relative to academic anchoring, particularly for suppliers with diagnostic-grade certification.
- Research Institutes:Proteomics workflow expansion drives systematic procurement of precast gel systems, tightening the link between manufacturing capacity and specialized electrophoresis technician availability.
- Laboratories:Group purchasing organization consolidation displaces individual purchasing authority in academic medical centers.
- Hospitals:EU In Vitro Diagnostic Regulation compliance burdens create white space for suppliers bundling regulatory documentation with product shipments.
Pharmaceutical Companies generate the highest per-unit margins, while Research Institutes are gaining share fastest through proteomics infrastructure investment.
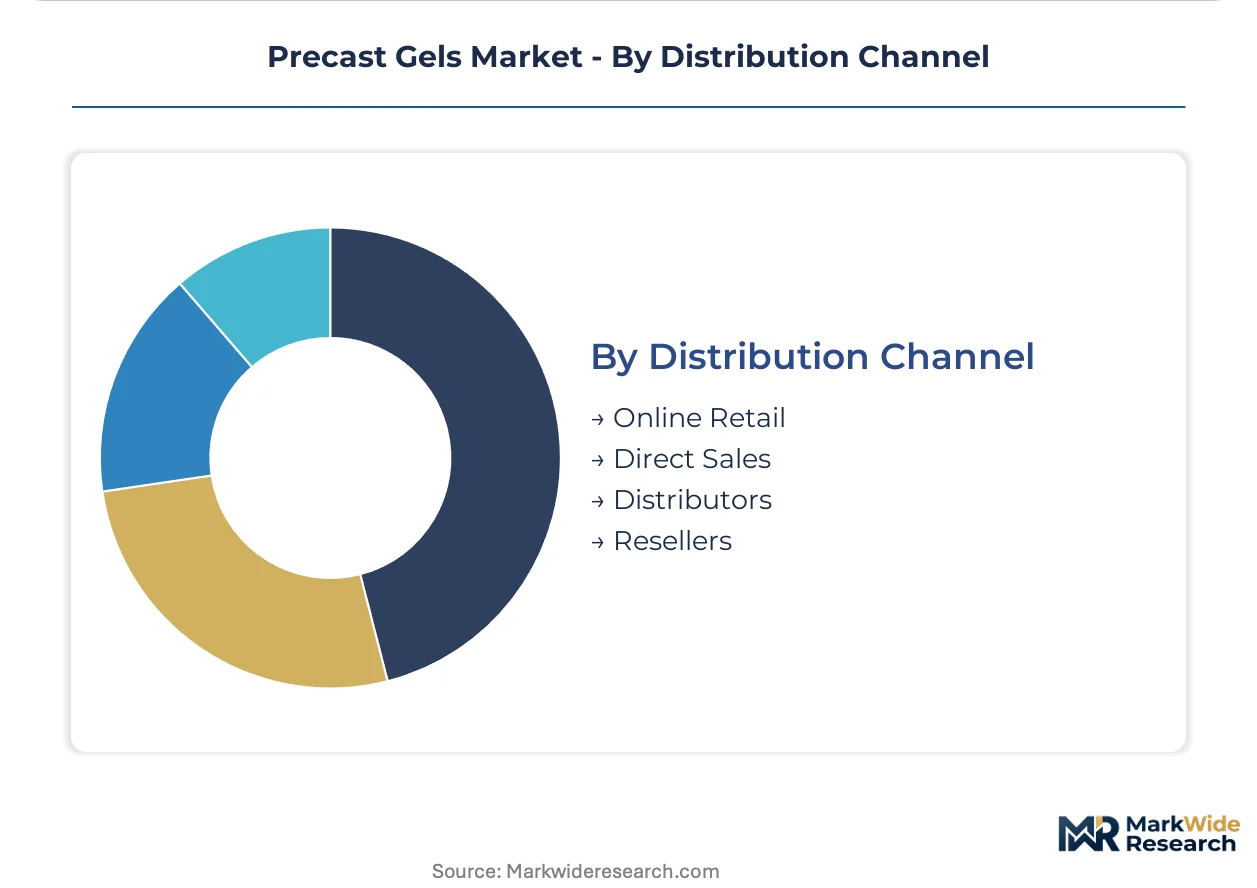
Distribution Channel:
Channel economics reflect the service intensity required for technical validation and regulatory documentation support.
- Direct Sales:Captive distribution networks dominate high-throughput diagnostics channels through bundled instrument maintenance and gel replenishment contracts.
- Distributors:Regional specialists anchor academic research segments with deep product specialization and localized technical support.
- Online Retail:Standardized catalog products with minimal configuration requirements serve cost-sensitive segments.
- Resellers:Secondary channel participants capture residual demand in geographic pockets outside direct coverage footprints.
Direct Sales holds the dominant position, while Distributors are climbing the fastest through regulatory documentation service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulatory frameworks in the United States anchor precast gel demand through quality documentation mandates for electrophoresis consumables. The United States, Germany, Japan, China, and Switzerland concentrate procurement authority and manufacturing capacity for this market.
United States
Boston and San Diego biotech corridors cluster venture-funded protein therapeutics startups around validated precast gel suppliers. FDA Good Laboratory Practice guideline updates force laboratory consolidation toward prequalified, factory-validated sources. The Longwood Medical Area and Torrey Pines cluster demonstrate concentrated procurement through bundled field service contracts.
Germany
REACH authorization requirements for acrylamide monomer handling restructure European manufacturing footprints. ECHA substance restriction proposals force reformulation investments by domestic suppliers. German manufacturers are relocating polymerization steps to non-EU production sites while maintaining EU distribution hubs.
Japan
Academic research institutes expand proteomics infrastructure procurement of precast gel systems. PMDA quality standards shape diagnostic-grade gel requirements for clinical applications. Tokyo and Osaka metropolitan areas concentrate specialized electrophoresis technician training programs that sustain manufacturing capacity.
China
Biotechnology process analytical technology adoption accelerates consumable pull-through from development into commercial manufacturing. NMPA diagnostic consumable regulations elevate documentation burdens for imported gel products. Shanghai and Suzhou biotech parks anchor domestic supplier expansion and foreign joint venture formation.
Switzerland
Pharmaceutical quality control laboratories generate premium-tier demand for ISO 13485-certified precast gel products. Swissmedic regulatory frameworks align with EU In Vitro Diagnostic Regulation conformity assessment requirements. Basel and Zurich pharmaceutical clusters drive cross-selling opportunities from research into validated manufacturing workflows.
Precast Gels Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in precast gel supply. The upper tier combines captive distribution networks with bundled instrument maintenance and consumable replenishment contracts. Mid-scale specialists anchor academic research segments through deep PAGE system expertise. Competitive moves concentrate on regulatory documentation service bundling and hybrid gel formulation investments.
Among diversified life sciences conglomerates, Danaher Corporation, Thermo Fisher Scientific Inc., and Bio-Rad Laboratories, Inc. represent distinct strategic archetypes. Danaher occupies a position leveraging cross-selling platforms into pharmaceutical quality control channels. Thermo Fisher exemplifies high-throughput diagnostics dominance through integrated distribution infrastructure. Bio-Rad anchors academic research specialization with deep historical investment in PAGE system workflows.
| Leading Market Players |
|---|
| Danaher Corporation |
| GenScript |
| Thermo Fisher Scientific Inc. |
| Takara Bio, Inc. |
| NIPPON Genetics |
| Bio-Rad Laboratories, Inc. |
| Lonza Group AG |
| Agilent Technologies, Inc. |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Gradient-pore synthetic formulations displacing single-percentage matrices simultaneously relocate manufacturing toward FDA-registered facilities and compress price premiums for manual-casting alternatives. This substitution dynamic concentrates procurement authority among suppliers with validated quality systems while eroding margins for cast-your-own gel providers.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical quality control channels, with bundled instrument-maintenance contracts locking in consumable replenishment rates. Price differentiation rests on ISO 13485 certification tier and diagnostic-grade validation status, with FDA-registered suppliers commanding sustained premiums. Cost compression in the academic segment intensifies because group purchasing organization consolidation aggregates volume leverage. Research institutes exhibit highest price sensitivity, while biopharmaceutical developers show lowest sensitivity due to regulatory revalidation costs.
Supply Chain Analysis
Acrylamide monomer purification capacity in Germany and Switzerland underwrites European gel manufacturing, though REACH authorization requirements are forcing polymerization steps toward non-EU production sites. Raw material dependencies center on acrylamide monomers, bis-acrylamide cross-linkers, and buffer reagents. Single-source vulnerability concentrates in specialized electrophoresis technician training pipelines across North America. Distribution runs through captive direct sales networks for diagnostics and regional distributors for academic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as biotechnology process analytical technology mandates institutionalize consumable pull-through from development into commercial manufacturing. Hybrid gel technology convergence accelerates penetration into cell culture applications beyond traditional electrophoresis.
For Market Incumbents: Consolidate manufacturing capacity around FDA-registered and ISO 13485-certified facilities to defend against regulatory documentation bundling by emerging competitors. Deepen field service integration through instrument-maintenance contracts that lock in gel replenishment. Prioritize backward integration into acrylamide monomer supply to offset EPA hazardous waste compliance cost compression.
For New Entrants and Emerging Players: Differentiate on EU In Vitro Diagnostic Regulation compliance services bundled with product shipments, targeting European hospital laboratories facing elevated conformity assessment burdens. Penetrate the pharmaceutical quality control segment through diagnostic-grade certification investments, as academic anchoring leaves this channel underdeveloped. Pursue hybrid gel formulation partnerships with cell culture specialists to unlock tissue engineering applications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed laboratory consumables platforms seeking diagnostic-grade certification expansion. Long-term viability hinges on regulatory moat sustainability across the 5-10 year quality management system validation window. Target acquisition archetypes: mid-scale PAGE system specialists with deep academic relationships and untapped pharmaceutical channel development. Monitor FDA Good Laboratory Practice guideline enforcement intensity as inflection indicator for laboratory consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management system validation unlocks clinical diagnostic market access in Europe and Asia. |
| Hybrid Gel Formulation Development | Natural-synthetic polymer convergence opens cell culture and tissue engineering revenue streams. |
| Regulatory Documentation Bundling | EU In Vitro Diagnostic Regulation compliance services differentiate suppliers in hospital laboratory channels. |
| Field Service Contract Expansion | Instrument-maintenance bundling concentrates procurement authority in Boston and San Diego biotech corridors. |
| Non-EU Manufacturing Relocation | REACH authorization avoidance preserves margins while maintaining EU distribution hub presence. |
Research Methodology
Operator-level perspectives from electrophoresis technicians, core facility managers, biopharmaceutical quality control leads, and laboratory procurement officers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EPA enforcement actions, ECHA substance restriction proposals, and ISO certification databases. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Sensitivity analysis tested forecast robustness across acrylamide monomer cost volatility scenarios, regulatory timeline compression assumptions, and technician pipeline gap persistence. Segmentation dimensions modeled include gel formulation architecture, biotechnology versus pharmaceutical versus diagnostic application, and direct sales versus distributor channel configuration. CAGRs derived from historical procurement pattern analysis and forward-looking capacity expansion announcements, with biopharmaceutical process analytical technology adoption curves and academic proteomics infrastructure investment cycles as key inputs.
Material uncertainties — FDA guideline enforcement intensity, ECHA substance restriction finalization, specialized technician training program expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory timeline stability and supply chain geographic reconfiguration pace. Practitioners should keep alternative scenarios live as EU In Vitro Diagnostic Regulation implementation timelines and REACH authorization scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Acrylic Powder Market