
 Southeast Asia Bio-PET Market | 2026-2036
Southeast Asia Bio-PET Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Bio-PET Market Analytics
Conventional fossil-based polyethylene terephthalate is hardening into a cost-disadvantaged position against bio-PET as sugarcane-derived monoethylene glycol achieves parity at scale across Thai and Indonesian conversion facilities. Indorama Ventures Public Company Limited leverages its integrated PTA-Bio-PET chain across Southeast Asian petrochemical zones to secure feedstock certainty. TEIJIN LIMITED anchors its regional position through specialized film-grade bio-PET for electronics and automotive laminates. Toyota Tsusho competes by controlling logistics corridors between Brazilian ethanol suppliers and Southeast Asian polymerization plants.
Bio-PET denotes a partially bio-based polyester where the ethylene glycol component derives from renewable feedstocks—typically sugarcane ethanol—while terephthalic acid remains petroleum-sourced, yielding a material with identical mechanical properties and recyclability to conventional PET but with measurably lower lifecycle carbon intensity. Virgin Bio-PET dominates current production volumes as beverage bottlers prioritize certified renewable content for brand differentiation, while Recycled Bio-PET occupies an emerging niche where post-consumer rPET streams blend with bio-based glycol to achieve dual environmental claims. The Food & Beverage end-user segment concentrates margin pools through long-term offtake agreements with major brand owners, whereas Automotive and Electronics segments remain fragmented with specifications still under negotiation.
Thailand's Board of Investment promotes bio-based chemical investments through tax incentives and feedstock security frameworks, while Indonesia's Ministry of Industry enforces progressive bio-content labeling requirements that channel procurement toward certified renewable resins. REACH-equivalent substance notification protocols under ASEAN harmonized standards shape import access for non-regional resin producers. Stakeholders must monitor whether Vietnamese regulators extend mandatory recycled-content mandates to cover bio-based equivalents, as this would restructure procurement priorities across Mekong Delta packaging clusters.
Market Dynamics
Thailand's concentrated PTA-Bio-PET manufacturing clusters are absorbing disproportionate regional capacity, forcing Indonesian and Vietnamese converters to secure long-term offtake agreements or risk feedstock exclusion.
Growth Catalysts
- Thailand's Board of Investment tax incentives:Feedstock security frameworks accelerate capital deployment into bio-based chemical investments, locking in polymerization capacity ahead of regional competitors.
- Beverage bottler procurement mandates:Brand owners prioritize certified renewable content for packaging differentiation, pulling resin volumes through long-term supply contracts.
- Sugarcane ethanol-to-MEG conversion:Thai and Indonesian facilities achieve cost parity at scale, compressing the premium gap against fossil-based glycol.
Market Restraints
- Petroleum-derived terephthalic acid dependency:Bio-PET remains partially fossil-based, limiting carbon intensity reductions and exposing pricing to crude oil volatility.
- Thai production concentration risk:Overreliance on Chonburi and Map Ta Phut industrial zones creates single-point vulnerability for regional resin supply.
- Indonesian labeling enforcement gaps:Progressive bio-content requirements lack uniform auditing standards, creating compliance friction for cross-border shipments.
Strategic Opportunities
- Vietnamese Mekong Delta packaging clusters:Blow-molding capacity expansion for carbonated soft drinks creates demand nodes underserved by current bio-PET distribution.
- Electronics and automotive laminates:Film-grade specifications remain under negotiation, offering white space for specialized resin producers to establish premium positioning.
- Recycled Bio-PET blending:Dual environmental claims combining post-consumer rPET with bio-based glycol command price premiums in sustainability-focused segments.
Industry Challenges
- Polymerization technician scarcity:Southeast Asian technical institutes lack curricula aligned to bio-based polyester process engineering, constraining plant commissioning timelines.
- REACH-equivalent substance notification:ASEAN harmonized standards create documentation bottlenecks for non-regional resin producers seeking import access.
- Legacy PET recycling infrastructure incompatibility:Existing mechanical recycling lines require retrofitting to handle bio-PET streams without contamination penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Bio-PET Market |
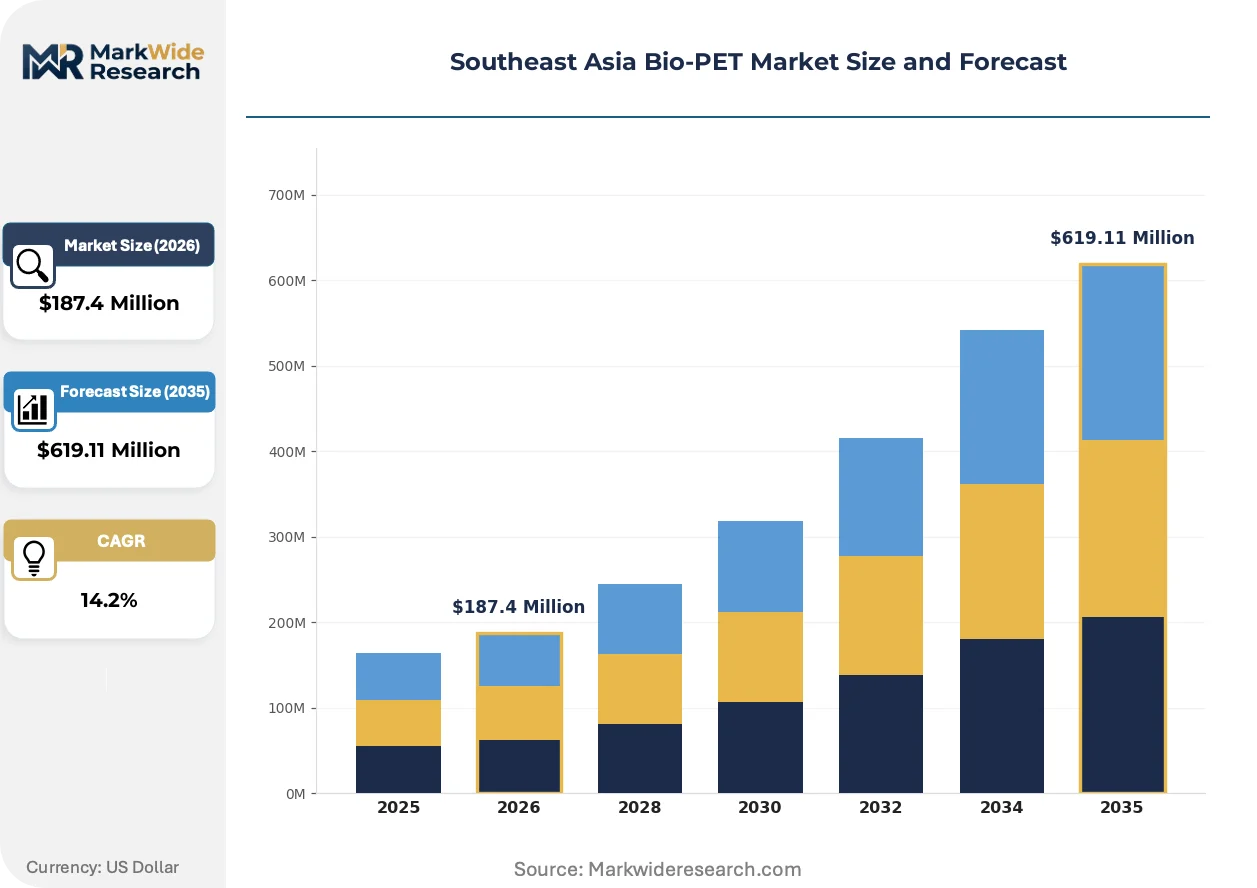
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin Bio-PET, Recycled Bio-PET, Blended Bio-PET, Biodegradable Bio-PET Application: Beverage Bottles, Food Packaging, Textile Industry, Consumer Goods End User: Food & Beverage, Automotive, Electronics, Pharmaceuticals Distribution Channel: Direct Sales, Online Sales, Retail, Distributors |
| Companies Covered | PepsiCo, TEIJIN LIMITED, Indorama Ventures Public Company Limited, Danone, Plastipak Holdings, Inc., The Coca-Cola Company, Toyota Tsusho, Far Eastern New Century Corporation, Toray Industries, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Bio-PET Market Evolving Landscape
Process intensification and feedstock diversification are compressing conversion economics while regulatory pressure on lifecycle carbon accounting is rewriting procurement specifications across end-use verticals.
Second-generation bio-ethylene glycol production from agricultural residues is rewriting the feedstock economics for Thai polymerization plants. Beverage bottlers in Bangkok and Jakarta are trialing certified batches at commercial scale. This technology is compressing the cost premium against fossil-derived MEG to single-digit percentages.
Indonesia's Ministry of Industry enforces progressive bio-content labeling requirements that channel procurement toward certified renewable resins. Converters face mandatory disclosure thresholds that exclude uncertified imports. Food and beverage packaging lines in Java and Sumatra are restructuring supplier qualification protocols to maintain market access.
Brand owners now mandate mass-balance certification as a non-negotiable procurement gate, displacing self-declared sustainability claims. Long-term offtake agreements with fixed renewable content percentages are replacing spot resin purchases. This pattern concentrates most visibly among multinational beverage bottlers operating across Thai and Vietnamese bottling facilities.
Southeast Asia Bio-PET Market Segmentation
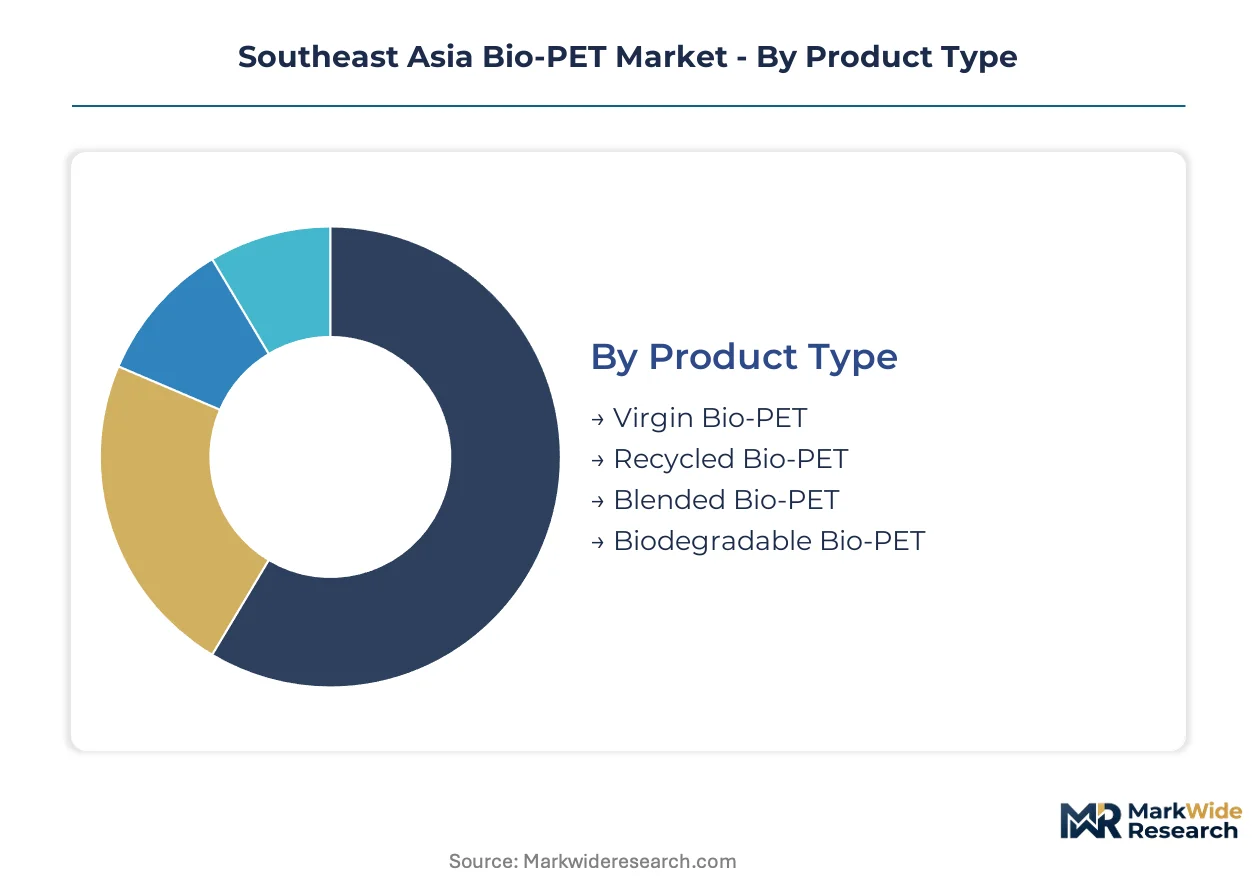
Bio-PET segmentation in Southeast Asia reflects divergent technical maturity across product grades and sharply contrasting procurement patterns between beverage bottlers and industrial laminators. Understanding these divides exposes where margin pools concentrate and where specification gaps create entry opportunities for specialized resin producers.
Product Type:
Integration depth varies sharply: Virgin Bio-PET operates as standalone certified material, while Blended and Recycled variants embed into hybrid sustainability claims requiring mass-balance documentation.
- Virgin Bio-PET:Fully bio-based monoethylene glycol derived from sugarcane ethanol polymerized with petroleum-sourced terephthalic acid delivers identical mechanical properties to conventional PET. Beverage bottlers across Thai and Indonesian facilities concentrate procurement here for brand-certified renewable content claims.
- Recycled Bio-PET:Post-consumer rPET streams combined with bio-based glycol achieve dual environmental credentials—renewable feedstock plus circular material recovery. Electronics and automotive laminators in Vietnam's industrial zones are testing film-grade specifications for premium positioning.
- Blended Bio-PET:Partial bio-content formulations balance cost against certification thresholds for mid-tier packaging applications.
- Biodegradable Bio-PET:Modified polyester variants with enhanced degradation pathways remain technically immature for commercial-scale Southeast Asian deployment.
Volume placements concentrate in Virgin Bio-PET; the faster expansion belongs to Recycled Bio-PET.
Application:
Cost-tier stratification separates commodity beverage packaging from specialized industrial laminates where specification negotiation still determines supplier qualification.
- Beverage Bottles:Carbonated soft drink and bottled water applications dominate resin offtake through long-term supply contracts with multinational bottlers. Thai and Indonesian converters are expanding blow-molding capacity to capture this procurement channel.
- Food Packaging:Trays, clamshells, and flexible films for fresh and processed foods carry stringent migration limits under ASEAN harmonized standards. Indonesian labeling enforcement is channeling procurement toward certified renewable resins with documented bio-content percentages.
- Textile Industry:Fiber-grade bio-PET for apparel and industrial yarns remains underdeveloped in Southeast Asian manufacturing clusters.
- Consumer Goods:Cosmetic and personal care packaging applications command modest volumes with higher sensitivity to aesthetic and haptic properties.
Procurement gravity sits with Beverage Bottles; specification development is advancing fastest in Food Packaging.
End User:
Customer-type concentration creates divergent margin structures: multinational beverage corporations drive volume through centralized procurement, while automotive and electronics buyers fragment across specialized technical requirements.
- Food & Beverage:Brand owners mandate mass-balance certification as non-negotiable procurement gates, displacing spot resin purchases with fixed renewable-content agreements. Bangkok and Jakarta bottling facilities are restructuring supplier qualification protocols to maintain market access.
- Automotive:Interior trim, under-hood components, and structural laminates require film-grade specifications still under negotiation. TEIJIN LIMITED anchors regional positioning through specialized resin development for this segment.
- Electronics:Display films, circuit substrates, and device housings demand optical clarity and dimensional stability that bio-PET formulations are still qualifying against.
- Pharmaceuticals:Primary packaging for drug delivery systems faces extended regulatory validation timelines that delay bio-PET adoption.
Contract concentration favors Food & Beverage; technical qualification is progressing most rapidly in Automotive.
Distribution Channel:
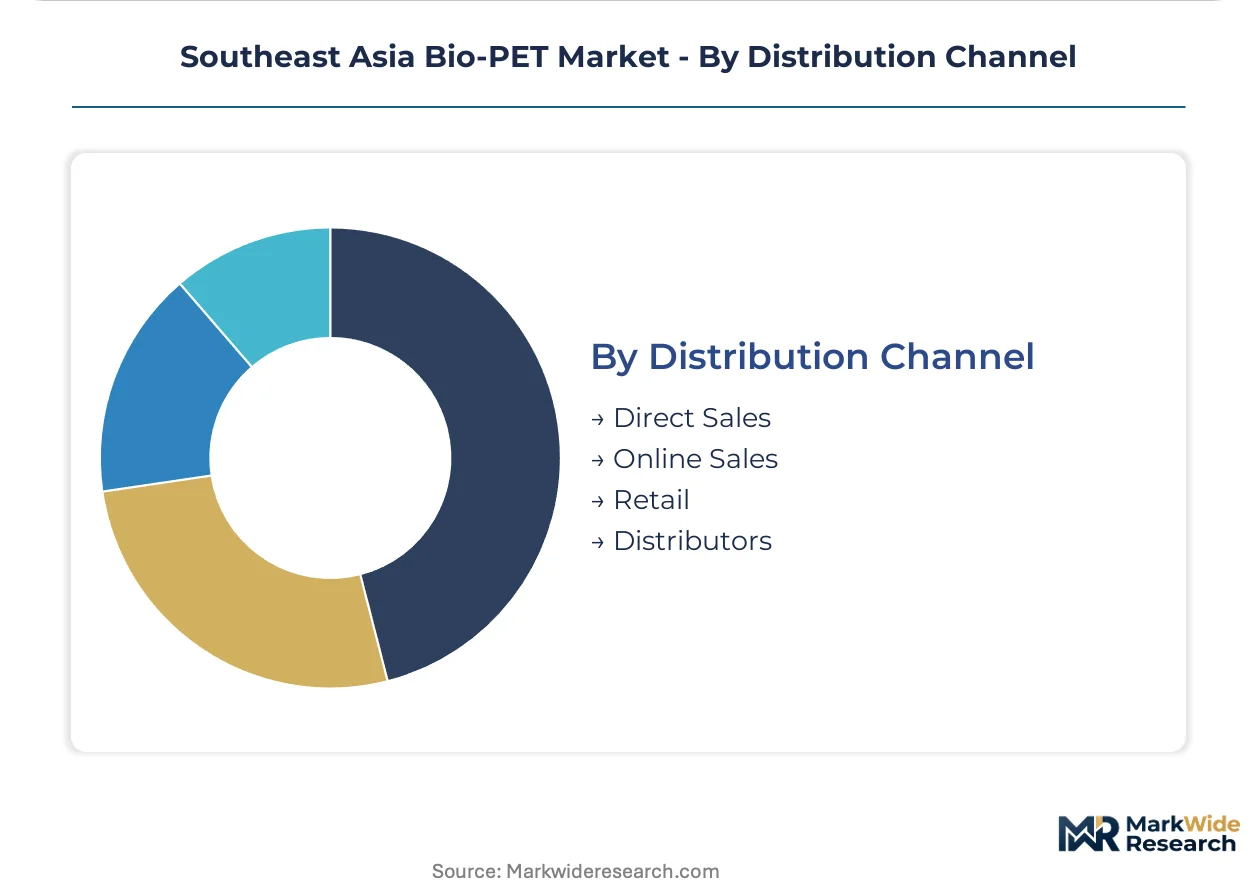
Supply-chain configuration determines access economics: direct relationships with polymerization plants lock in feedstock certainty, while distributor networks serve fragmented converter bases in emerging demand nodes.
- Direct Sales:Long-term offtake agreements between resin producers and major bottlers eliminate intermediary margins and secure volume commitments. Indorama Ventures leverages its integrated PTA-Bio-PET chain across Thai petrochemical zones to dominate this channel.
- Distributors:Regional resin traders serve Vietnamese and smaller Indonesian converters lacking scale for direct plant procurement. Mekong Delta packaging clusters rely on this channel for flexible volume access.
- Online Sales:Digital procurement platforms capture spot-market transactions for specialty grades and trial batches.
- Retail:Limited to small-volume specialty resin sales for research and prototyping applications.
Contract value pools in Direct Sales; network expansion is accelerating fastest through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers across Bangkok and Jakarta are pulling disproportionate resin volumes through long-term offtake agreements, concentrating procurement gravity in Thailand and Indonesia while Vietnamese converters scramble for feedstock access.
Thailand
Indorama Ventures commands integrated PTA-Bio-PET capacity across Chonburi and Map Ta Phut industrial zones, locking in polymerization certainty. The Board of Investment extends tax holidays for bio-based chemical investments. Bangkok bottling facilities are trialing second-generation agricultural residue feedstocks at commercial scale.
Indonesia
Carbonated soft drink converters in Java and Sumatra are expanding blow-molding lines to capture multinational procurement mandates. The Ministry of Industry enforces progressive bio-content labeling thresholds that exclude uncertified resin imports. Surabaya packaging clusters are restructuring supplier qualification protocols to maintain market access.
Vietnam
Mekong Delta packaging converters face feedstock exclusion risks as Thai production concentration hardens. The national regulator has not yet extended mandatory recycled-content mandates to bio-based equivalents. Ho Chi Minh City industrial zones are absorbing distributor-served resin volumes for flexible blow-molding capacity.
Philippines
Beverage bottlers in Luzon are negotiating mass-balance certification requirements with lagging domestic polymerization infrastructure. The national standards body aligns substance notification protocols with ASEAN harmonized frameworks. Manila Bay packaging corridors rely on imported resin streams through regional distributor networks.
Malaysia
Specialized film-grade applications for electronics laminates are testing qualification protocols in Penang industrial zones. The national investment authority promotes bio-based manufacturing through feedstock security frameworks. Johor Bahru chemical clusters are evaluating backward integration into sugarcane ethanol supply chains.
Southeast Asia Bio-PET Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated petrochemical players lock in polymerization scale ahead of regional competitors. The vendor base concentrates around three strategic archetypes: upstream resin producers with captive feedstock control, downstream converters securing long-term offtake certainty, and brand owners mandating certified renewable content through procurement gates. M&A activity and strategic partnerships are compressing intermediary margins between polymerization plants and bottling facilities.
Among Thailand-based integrated producers, Indorama Ventures Public Company Limited exemplifies upstream resin control through PTA-Bio-PET chain ownership. TEIJIN LIMITED anchors specialized film-grade positioning for automotive and electronics laminates. Toyota Tsusho occupies logistics coordination archetypes between Brazilian ethanol suppliers and Southeast Asian polymerization infrastructure.
| Leading Market Players |
|---|
| PepsiCo |
| TEIJIN LIMITED |
| Indorama Ventures Public Company Limited |
| Danone |
| Plastipak Holdings, Inc. |
| The Coca-Cola Company |
| Toyota Tsusho |
| Far Eastern New Century Corporation |
| Toray Industries |
| Others |
Value Network & Pricing Analysis
Captive PTA-Bio-PET integration across Thai petrochemical zones anchors both supply security and pricing leverage for dominant resin producers. This backward integration into purified terephthalic acid production eliminates intermediary markups while locking in feedstock certainty against Brazilian ethanol price volatility.
Pricing Analysis
High-volume beverage bottlers command contract-based long-term offtake structures with fixed renewable content percentages, while smaller Vietnamese converters absorb spot-market premiums through distributor intermediaries. Price differentiation hinges on mass-balance certification grade and volume scale, with certified virgin resin carrying substantial premiums over uncertified blended grades. Cost compression in standard-tier bio-PET is intensifying as Thai and Indonesian facilities achieve sugarcane ethanol-to-MEG parity at scale. Mid-tier packaging converters in Java and Sumatra exhibit highest price sensitivity, whereas multinational brand owners prioritize certification certainty over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chonburi and Map Ta Phut industrial zones, where Indorama Ventures concentrates regional polymerization capacity. Raw material flows draw from Brazilian sugarcane ethanol suppliers, petroleum-derived terephthalic acid feedstocks, and specialized catalyst systems for bio-MEG conversion. Tariff exposure on uncertified resin imports under ASEAN harmonized standards creates compliance friction for non-regional producers. Distribution runs through direct plant relationships for major bottlers and regional distributor networks for Mekong Delta packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: Thai production concentration against expanding Indonesian and Vietnamese converter demand props pricing power for integrated resin producers.
For Market Incumbents: Extend polymerization capacity ahead of competitor commissioning timelines, particularly in Vietnamese industrial zones where feedstock exclusion risks are mounting. Lock in long-term Brazilian ethanol supply contracts before second-generation agricultural residue technologies rewrite feedstock economics. Certification investment in mass-balance chain-of-custody systems defends against emerging resin producers lacking audit infrastructure. For New Entrants and Emerging Players: Begin with film-grade bio-PET specifications for automotive and electronics laminators in Vietnam's industrial zones, where technical qualification protocols remain under negotiation and incumbent presence is thinnest. Target distributor-served Mekong Delta packaging converters with flexible volume commitments that integrated producers disfavor. Position around Recycled Bio-PET blending capabilities to capture dual environmental claim premiums in sustainability-focused segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated petrochemical majors seeking bio-based resin capabilities. Five-to-ten year viability hinges on whether Vietnamese regulators extend mandatory recycled-content mandates to bio-based equivalents, restructuring procurement priorities. Monitor Thai Board of Investment incentive renewals as inflection signal for regional capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Production | Eliminates feedstock dependency for Bio-PET polymerization across Thai industrial zones. |
| Mass-Balance Certification Investment | Locks in multinational beverage bottler procurement gates under Indonesia's labeling enforcement. |
| Second-Generation Feedstock Qualification | Agricultural residue-to-MEG conversion compresses cost premium against fossil-derived glycol. |
| Vietnamese Distribution Network Expansion | Captures Mekong Delta blow-molding capacity underserved by direct plant relationships. |
| Recycled Bio-PET Blending Capability | Dual environmental claims command price premiums in electronics and automotive laminates. |
Research Methodology
Multi-period observation of polymerization capacity commissioning timelines, bio-content labeling enforcement patterns, and long-term offtake agreement structures anchored the trend analysis, supplemented by interviews with plant managers at Thai and Indonesian conversion facilities, procurement leads at multinational beverage bottlers, distribution channel partners in Vietnamese industrial zones, and technical R&D directors specializing in bio-based polyester process engineering. Secondary validation drew from ASEAN harmonized standards documentation, customs and trade flow data, SEC filings of listed petrochemical conglomerates, and Board of Investment incentive disclosure records. Bottom-up resin volume modeling triangulated against top-down end-use demand aggregation.
Input-output matrix framing connected sugarcane ethanol supply elasticity, petroleum feedstock price volatility, and regulatory certification thresholds to Bio-PET volume and value trajectories across the projection horizon. Segmentation dimensions spanned product grade tier, end-use application, customer-type concentration, and regional production hub. CAGRs were derived from regression analysis of historical capacity utilization against procurement mandate diffusion rates, incorporating second-generation bio-ethylene glycol technology adoption curves and Indonesian labeling enforcement phase-in schedules as industry-specific forecast inputs.
Underlying measurement precision varies by segment; Virgin Bio-PET carries tighter precision than emerging Recycled Bio-PET grades where specification protocols remain under negotiation. Forecasts reflect documented assumptions regarding Thai incentive continuity, Brazilian ethanol supply reliability, and ASEAN regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Europe Bioplastics Market
Bioplastics
US Bioplastics Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
North America Bioplastics Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market