
 Refined Naphthalene Market | 2026-2036
Refined Naphthalene Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Naphthalene Market Analytics
Direct procurement channels between naphthalene refiners and phthalic anhydride manufacturers is tilting toward long-term supply contracts with embedded purity guarantees. Rain Carbon leverages its integrated carbon materials platform to sustain captive feedstock security across the Americas. Koppers anchors its position through specialized tar distillation infrastructure that controls upstream access to crude naphthalene streams.
Refined naphthalene denotes a purified aromatic hydrocarbon derived from coal tar or petroleum feedstock, typically achieving purity levels above 99% through fractional distillation and crystallization, serving primarily as a precursor for phthalic anhydride, naphthalene sulfonates, and dye intermediates. The flake and powder product types dominate current volume flows, with powder grades commanding margin premiums in detergent and dispersant applications where solubility performance dictates specification. Plastics and coatings applications are expanding fastest, driven by phthalate plasticizer demand and alkyd resin formulations that require consistent naphthalene feedstock quality.
EPA standards under the Clean Air Act and OSHA workplace exposure limits shape domestic production protocols, while REACH registration requirements in Europe constrain market access for non-compliant imports. The EU F-Gas Regulation indirectly influences naphthalene demand patterns as insulation foam manufacturers seek alternative blowing agent pathways. Stakeholders must monitor evolving purity standards and carbon intensity disclosure rules that will determine which refiners retain preferred supplier status across regulated end-use sectors.
Market Dynamics
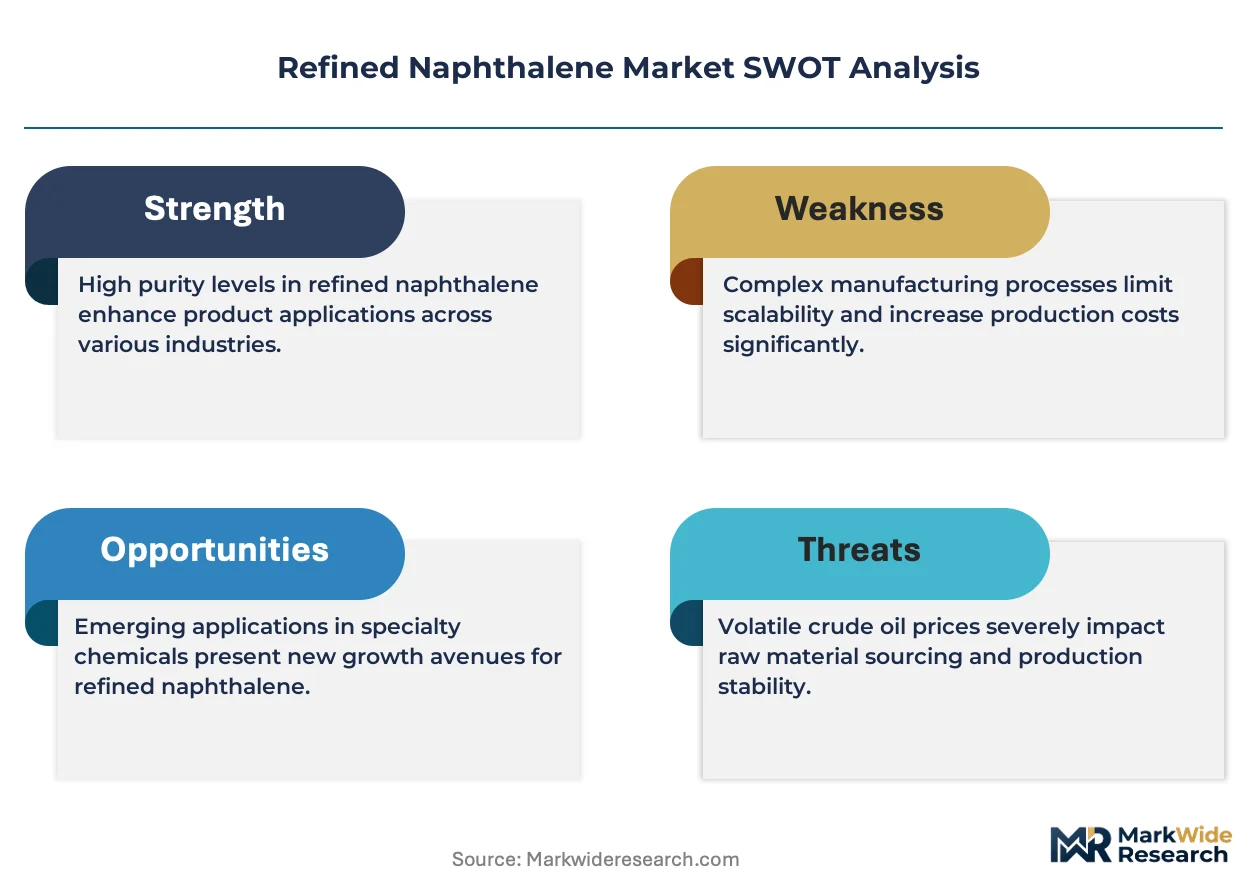
Purity specification tightening across major regulatory jurisdictions is compressing the supplier base capable of serving phthalic anhydride and dye intermediate manufacturers. Refiners lacking fractional distillation upgrades face exclusion from premium offtake channels as downstream producers seek embedded compliance guarantees.
Growth Catalysts
- REACH registration thresholds:ECHA mandates for substance volume tracking are filtering out non-compliant crude naphthalene traders. European phthalic anhydride producers now require documented purity certificates from every supply tier.
- Alkyd resin formulation demand:Coatings manufacturers in India and China are absorbing larger flake naphthalene volumes for high-solids resin systems. These formulations demand consistent aromatic feedstock quality.
- Coal tar distillation infrastructure:Integrated carbon materials platforms in the Americas are securing captive crude naphthalene access. This upstream control insulates refined product output from raw material volatility.
Market Restraints
- Crude naphthalene supply concentration:Tar distillation capacity clusters in specific industrial corridors. Disruptions at major coking facilities transmit directly to refined product availability.
- Petroleum-derived naphthalene cost structure:Alternative feedstock from catalytic reforming operations tracks crude oil price movements. This creates margin compression during energy price spikes.
- Phthalate plasticizer substitution:Non-phthalate alternatives in flexible PVC applications are displacing some traditional naphthalene-derived plasticizer demand. Bio-based and terephthalate esters capture specification-sensitive segments.
Strategic Opportunities
- Carbon intensity disclosure rules:EU CSRD requirements are creating premium tiers for refiners with verified low-carbon production pathways. Early certifiers capture preferred supplier status with multinational chemical buyers.
- Dispersant-grade powder expansion:Naphthalene sulfonate concrete admixtures are penetrating infrastructure markets in Southeast Asia. High-solubility powder grades command margin premiums over standard flake.
- Direct refiner-to-manufacturer channels:Long-term supply contracts with embedded purity guarantees are displacing spot market transactions. This contractual shift locks in volume commitments and reduces price volatility exposure.
Industry Challenges
- Crystallization process optimization:Achieving consistent 99%+ purity requires precise temperature control and solvent selection. Talent scarcity in fractional distillation engineering constrains capacity expansion timelines.
- Multi-jurisdiction compliance synchronization:Simultaneous EPA, REACH, and BIS standard adherence demands dedicated regulatory affairs functions. Smaller refiners struggle to maintain parallel certification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Naphthalene Market |
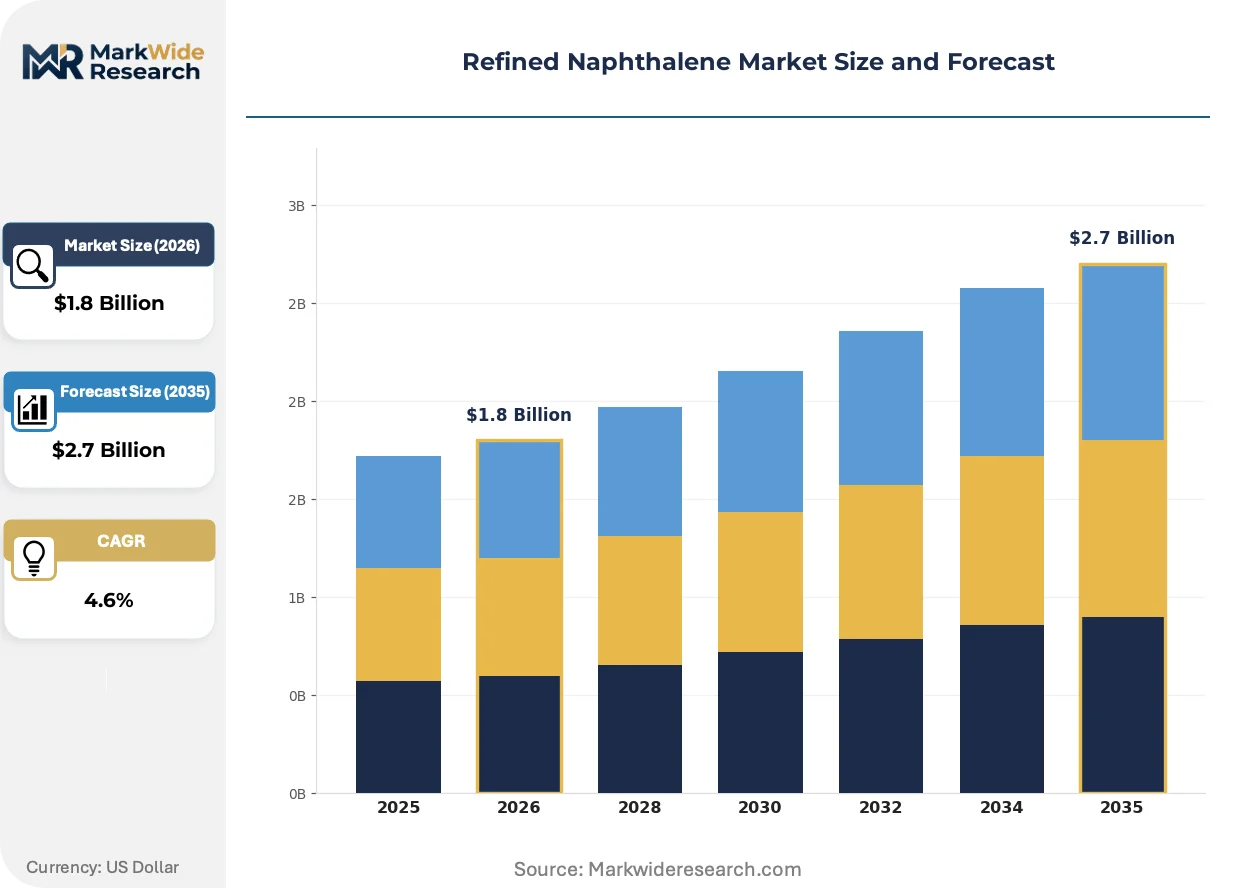
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Powder, Liquid, Granules Application: Dyes, Plastics, Coatings, Detergents End User: Chemicals, Textiles, Automotive, Construction Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Rain Carbon, Koppers, JFE Chemical Corporation, Himadri Specialty Chemical, China Steel Chemical, ExxonMobil Chemical, Deza, Dong-Suh Chemical Ind. Co., Ltd., Kuwait Aromatics Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Naphthalene Market Evolving Landscape
Process intensification technologies are compressing the capital requirements for high-purity naphthalene production. Digital quality control systems and advanced crystallization methods are enabling new entrants to challenge established refinery economics.
Continuous melt crystallization systems are collapsing the energy intensity differential between coal tar and petroleum-derived naphthalene purification. Indian specialty chemical producers are deploying these units at scale to serve domestic textile dye houses. The technology is compressing the traditional advantage held by integrated tar distillation operators with legacy batch equipment.
EPA enforcement of Clean Air Act standards for hazardous air pollutants is mandating emissions controls at tar distillation facilities. US-based refiners are retrofitting thermal oxidizers and vapor recovery systems to maintain operating permits. Phthalic anhydride manufacturers sourcing from these facilities absorb compliance costs through modified contract pricing structures.
Specification-driven purchasing is consolidating buyer relationships around refiners with integrated laboratory certification capabilities. Dye intermediate manufacturers in India are requiring batch-specific purity documentation with every delivery. This behavioral shift favors larger producers with in-house analytical infrastructure over traders relying on third-party testing.
Refined Naphthalene Market Segmentation
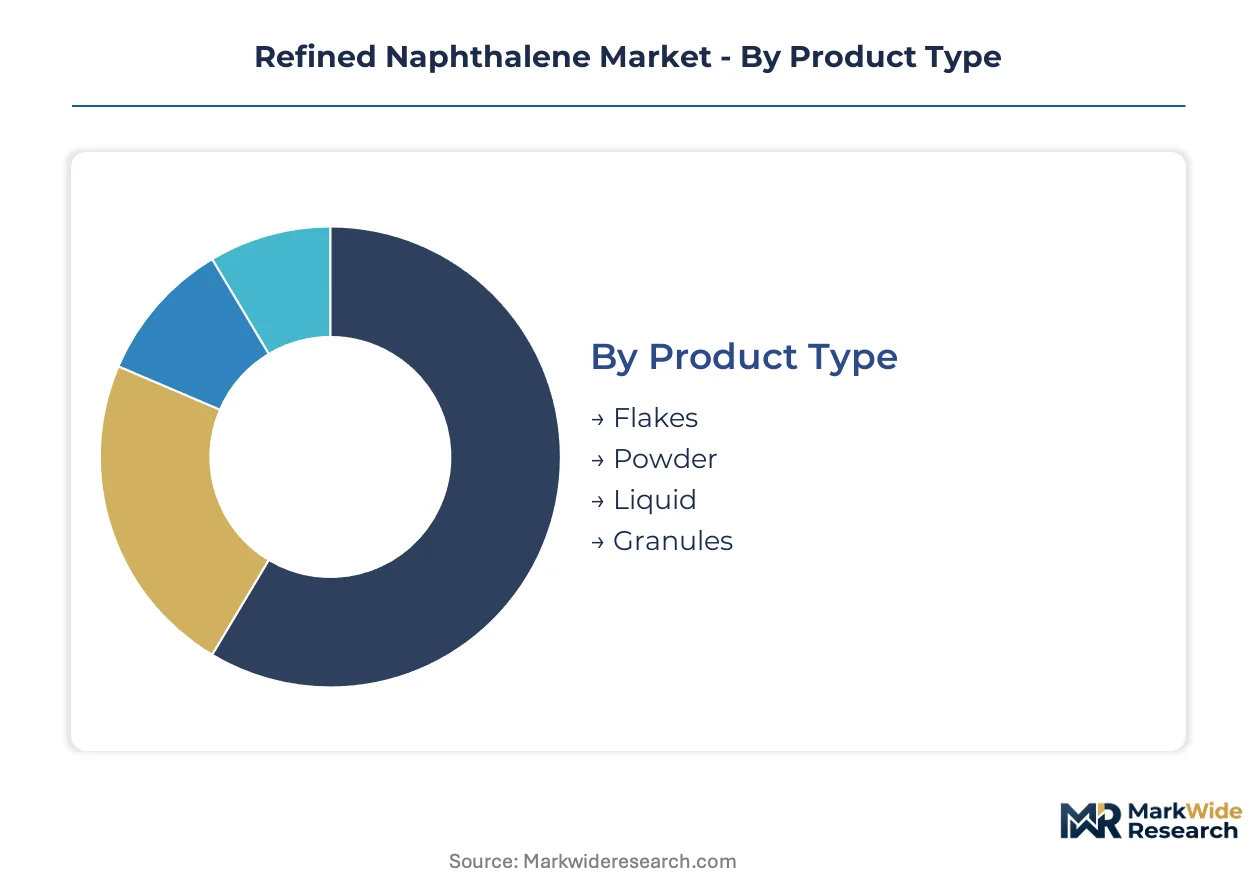
Segmentation in refined naphthalene markets tracks how purity specifications, physical form factors, and procurement channels align with distinct end-use compliance requirements. Each category reveals where margin premiums concentrate and which supply relationships command pricing power.
Product Type:
Use-case spectrum spans bulk industrial feedstock to precision-dispersed formulations, with physical form dictating handling economics and dissolution performance.
- Flakes:Crystalline platelets achieve 99% purity through controlled cooling of molten naphthalene. Construction chemicals manufacturers in India absorb the largest volumes for phthalic anhydride production, drawn by established handling infrastructure at integrated carbon black facilities.
- Powder:Micronized particles with enhanced surface area serve naphthalene sulfonate dispersant applications where rapid solubility is non-negotiable. Detergent formulators and concrete admixture producers pay margin premiums for grades that collapse dissolution time.
- Liquid:Molten or solvent-dissolved forms eliminate solid handling for continuous process manufacturers. Chemical producers with heated storage infrastructure favor this format for operational simplicity.
- Granules:Compacted spherical particles reduce dust generation during pneumatic conveying. Specialty applications with stringent workplace exposure protocols specify this form.
Established volume favors Flakes; emerging adoption favors Powder.
Application:
Cost tier stratification separates commodity phthalic anhydride feedstock from specification-sensitive dye intermediates and dispersant systems.
- Dyes:Aromatic intermediates for azo and anthraquinone pigments demand batch-certified purity above 99.5%. Textile dye houses in India require documented compliance with BIS specifications for every delivery.
- Plastics:Phthalate plasticizer production consumes the largest naphthalene volumes, though non-phthalate substitution pressures are compressing growth in flexible PVC applications.
- Coatings:Alkyd resin formulations for high-solids industrial coatings absorb consistent flake volumes. Automotive refinish and protective coatings manufacturers prioritize aromatic feedstock consistency.
- Detergents:Naphthalene sulfonate condensates serve as dispersants and wetting agents in laundry and industrial cleaning formulations. Powder grades command pricing premiums for rapid dissolution performance.
Volume leadership sits with Plastics; steepest expansion trajectory belongs to Coatings.
End User:
Customer type determines whether procurement flows through long-term supply contracts with embedded purity guarantees or spot market transactions with third-party certification.
- Chemicals:Phthalic anhydride and naphthalene sulfonate manufacturers represent the core demand base, with integrated producers securing captive crude feedstock and merchant refiners serving spot requirements.
- Textiles:Dye intermediate producers in India and China require laboratory-verified purity documentation for every batch. This behavioral shift consolidates purchasing around refiners with in-house analytical infrastructure.
- Automotive:Coatings and underbody sealant manufacturers specify consistent aromatic feedstock quality for alkyd resin systems. OEM tier suppliers absorb compliance costs through modified contract structures.
- Construction:Concrete admixture producers in Southeast Asia are expanding offtake for naphthalene sulfonate superplasticizers. Infrastructure investment cycles directly correlate with regional demand spikes.
Contractual stability concentrates in Chemicals; specification intensity peaks in Textiles.
Distribution Channel:
Supply concentration shapes whether procurement bypasses intermediaries or flows through layered distribution with accumulated margin.
- Direct Sales:Refiner-to-manufacturer relationships with multi-year contracts and embedded purity guarantees. Phthalic anhydride producers with integrated carbon materials platforms favor this channel for feedstock security.
- Distributors:Regional chemical distributors aggregate smaller volume requirements from dye houses and specialty formulators. Inventory carrying costs and certification documentation capabilities determine distributor viability.
- Online Retail:Digital platforms serve research quantities and small-batch specialty applications. Purity verification and chain-of-custody documentation remain friction points.
- Wholesalers:Bulk commodity handlers move standard-grade flake to construction chemicals and coatings manufacturers with less stringent certification requirements.
Volume gravity centers on Direct Sales; channel expansion is climbing fastest in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in refined naphthalene markets tilts toward Indian refiners serving domestic textile dye houses, while European producers absorb REACH compliance costs that compress margins relative to Asian competitors.
United States
Phthalic anhydride manufacturers along the Gulf Coast absorb captive feedstock from integrated carbon materials platforms. EPA enforcement of Clean Air Act standards for hazardous air pollutants mandates thermal oxidizer retrofits at tar distillation facilities. Houston-area refiners pass compliance costs through modified contract pricing structures with downstream chemical producers.
Germany
Coal tar distillation infrastructure in the Ruhr region anchors European supply for high-purity dye intermediates. REACH registration thresholds enforced by ECHA filter out non-compliant crude naphthalene traders, compressing the supplier base. Ludwigshafen chemical producers now require documented purity certificates from every supply tier.
India
Textile dye houses in Maharashtra and Gujarat expand offtake for high-grade flake and powder grades as domestic production scales. BIS specifications govern batch-certified purity above 99.5% for aromatic intermediates. Himadri Specialty Chemical leverages captive coal tar access to serve expanding regional demand.
China
Steel-integrated chemical producers in the Yangtze River Delta region control upstream crude naphthalene streams from coking operations. Dual carbon goals and MEE emissions standards shape refinery upgrade timelines. Shandong Province alkyd resin formulators absorb consistent flake volumes for coatings applications.
Japan
Specialty chemical producers in the Kansai region serve precision dye intermediate applications with laboratory-verified purity documentation. METI industrial standards and JIS specifications constrain import competition. Osaka-based refiners maintain preferred supplier status with multinational chemical buyers through integrated certification capabilities.
Refined Naphthalene Market Competitive Landscape
Integrated tar distillers and merchant specialty chemical producers split the market into distinct capability tiers. Market structure concentrates around upstream feedstock control, with refiners lacking fractional distillation upgrades facing exclusion from premium offtake channels. Three archetypes dominate: steel-integrated chemical divisions with captive coking access, independent coal tar refiners with specialized distillation infrastructure, and petroleum-derived naphthalene producers tracking crude oil cost structures. Competitive moves center on long-term supply contracts with embedded purity guarantees and crystallization process upgrades that achieve consistent 99%+ purity.
Within the integrated carbon materials tier, Rain Carbon and Koppers exemplify upstream control strategies that insulate refined product output from raw material volatility. Among Asia-Pacific specialty chemical producers, Himadri Specialty Chemical occupies a position representing domestic Indian refiners scaling high-grade output for textile dye applications. These named entities anchor archetype-level commentary without constraining the broader competitive dynamics visible across the supplier base.
| Leading Market Players |
|---|
| Rain Carbon |
| Koppers |
| JFE Chemical Corporation |
| Himadri Specialty Chemical |
| China Steel Chemical |
| ExxonMobil Chemical |
| Deza |
| Dong-Suh Chemical Ind. Co., Ltd. |
| Kuwait Aromatics Company |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta steel-chemical corridor anchors global crude naphthalene availability, with coking-integrated producers leveraging captive tar streams to dictate refined product pricing power across Asian markets. Downstream phthalic anhydride manufacturers absorb cost pass-throughs when coking facility disruptions tighten feedstock availability.
Pricing Analysis
Configured-to-order pricing for 99.5%+ purity dye-intermediate grades commands substantial premiums over standard 99% flake destined for phthalic anhydride production. Three-tier pricing structure across premium certified, standard industrial, and economy spot grades reflects certification burden and volume scale differentiation. Pricing pressure stems from petroleum-derived naphthalene cost volatility tracking crude oil movements, compressing margins for non-integrated refiners. Construction chemicals buyers exhibit highest price sensitivity due to commoditized phthalic anhydride output, while textile dye houses accept premium pricing for batch-verified purity documentation.
Supply Chain Analysis
Upstream crude naphthalene draws from coal tar distillation clusters in China, India, and the United States, with petroleum reforming operations in South Korea and Japan providing alternative feedstock pathways. Refined output hinges on crystallization solvent systems, thermal oxidizer compliance equipment, and laboratory certification infrastructure. Single-source vulnerability concentrates in tar distillation capacity tied to steel production cycles, transmitting coking facility shutdowns directly to refined product availability. Distribution runs through direct refiner-to-manufacturer long-term contracts with embedded purity guarantees, displacing spot market transactions for premium grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated phthalic anhydride producers with captive carbon materials platforms, fragmenting negotiating leverage for merchant refiners lacking upstream control. This consolidation forces supply contract restructuring toward multi-year purity-guaranteed arrangements.
For Market Incumbents: Entrench preferred supplier status through fractional distillation upgrades achieving consistent 99%+ purity and integrated laboratory certification capabilities serving BIS and REACH documentation requirements. Defend against continuous melt crystallization technology disruptors by locking in long-term offtake with Indian textile dye houses. Prioritize carbon intensity disclosure investments to capture EU CSRD-compliant premium tiers before competitor certification.
For New Entrants and Emerging Players: Build out naphthalene sulfonate superplasticizer-grade powder capacity targeting Southeast Asian infrastructure markets where high-solubility specifications command margin premiums. Penetrate the dispersant-grade powder segment through partnerships with concrete admixture formulators lacking in-house purification infrastructure. Deploy direct sales channels with batch-specific purity documentation to displace distributor-dependent competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because REACH and EPA purity standard tightening will exclude non-upgraded refiners from premium offtake channels. Target acquisition archetypes include coal tar distillers with crystallization engineering talent and existing thermal oxidizer installations. Watch carbon intensity disclosure rule enforcement velocity as the inflection signal determining which Asian refiners retain European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal Tar Distillation | Captive crude naphthalene access insulates margin from feedstock volatility and coking facility disruptions. |
| Continuous Melt Crystallization Deployment | Indian specialty chemical producers compress energy intensity differential versus legacy batch equipment operators. |
| Carbon Intensity Certification Program | Early EU CSRD compliance captures preferred supplier status with multinational chemical buyers. |
| Long-term Supply Agreement with Purity Guarantees | Phthalic anhydride manufacturers secure embedded compliance documentation across REACH and EPA jurisdictions. |
| Joint Venture with Southeast Asian Admixture Producers | Naphthalene sulfonate superplasticizer demand tracks infrastructure investment cycles in Vietnam and Indonesia. |
Research Methodology
Operator-level perspectives from tar distillation plant managers, phthalic anhydride procurement leads, textile dye house technical directors, and naphthalene sulfonate formulator R&D heads anchored the qualitative base. These primary engagements combined with customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from integrated carbon materials producers, and ECHA REACH registration databases. Bottom-up volume modeling across grade tiers and end-use industries triangulated against top-down macro chemical consumption indicators.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning purity grade tier, physical form factor, application industry, and regional production hub. CAGRs derived from regression analysis of historical consumption patterns against phthalate plasticizer output, alkyd resin formulation trends, and concrete admixture penetration rates. Forecast inputs incorporated steel production cycle correlations, coking facility capacity utilization, and regulatory compliance cost trajectories.
Stress conditions across crude oil price volatility, coking facility disruption frequency, and REACH registration timeline enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding purity standard evolution and carbon disclosure rule adoption velocity. Cross-checking against IHS Markit chemical production benchmarks and national statistics office industrial output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Ammonium Thiosulfate Market