
 Copper Oxychloride Market | 2026-2036
Copper Oxychloride Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Oxychloride Market Analysis
Aftermarket technical advisory services is reconfiguring margin pools away from bulk chemical sales toward application-specific guidance. Syngenta leverages its agronomic expertise to bundle copper oxychloride with precision dosing protocols. Albaugh sustains competitive pressure through backward integration into active ingredient synthesis. Parikh Enterprises Private Limited anchors its position in South Asian contract manufacturing for branded formulators.
Copper oxychloride is a basic copper chloride compound with approximate formula CuCl2·3Cu(OH)2, manufactured through the reaction of copper metal or copper salts with hydrochloric acid and subsequent oxidation, serving primarily as a broad-spectrum fungicide and bactericide in crop protection. The fungicide product type category captures the dominant volume share, reflecting entrenched vineyard and orchard protocols across temperate growing regions. The bio-stimulant segment is expanding fastest as formulators combine copper trace elements with microbial inoculants to meet regenerative agriculture specifications. Application in horticulture commands premium pricing due to smaller batch requirements and higher residue sensitivity compared with broad-acre agriculture.
EPA registration requirements and FIFRA tolerances govern US market access, while REACH authorisation processes in Europe restrict impurity profiles and environmental release thresholds. India's Central Insecticides Board mandates BIS certification for imported technical grade material, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving maximum residue limits in target export markets to preempt formulation obsolescence.
Market Dynamics
REACH authorisation processes and EU Green Deal residue tightening are compressing formulation shelf lives while accelerating bio-stimulant R&D cycles across European vineyards and orchards.
Growth Catalysts
- Regenerative Agriculture Mandates:EU Green Deal specifications for soil health are pulling copper trace element demand into microbial inoculant formulations. Formulators blend oxychloride with bio-stimulants to meet regenerative certification thresholds.
- Maharashtra-Gujarat Cultivation Expansion:Grape and mango acreage concentration in India's western states anchors copper-based fungicide procurement volumes. Maharashtra's vineyard protocols standardize copper oxychloride as a dormant spray staple.
- Precision Dosing Hardware:Variable-rate application technology is virtualizing fungicide deployment in temperate orchards. Vineyard operators pair copper products with sensor-calibrated sprayers to reduce residue variability.
Market Restraints
- Copper Price Volatility:Electrolytic copper cathode fluctuations transmit directly into active ingredient production economics. Smaller formulators lack hedging infrastructure to buffer raw material swings.
- REACH Impurity Thresholds:ECHA authorisation processes restrict heavy metal content in technical grade material. Compliance testing extends lead times for non-European suppliers seeking European market access.
- Biological Fungicide Substitution:Bacillus subtilis and Trichoderma-based alternatives displace copper oxychloride in organic-certified horticulture. Premium pricing for biologicals compresses copper's share in residue-sensitive export crops.
Strategic Opportunities
- Sub-Saharan Orchard Development:South African and Kenyan avocado and citrus expansion creates underpenetrated demand for copper-based bactericides. Local formulators lack technical grade synthesis capacity, opening contract manufacturing entry points.
- Carbon Credit-Linked Application Protocols:EU Carbon Border Adjustment Mechanism incentives reward precision fungicide use with verified emission reductions. Vineyard cooperatives bundle copper dosing with soil carbon monitoring to access green finance.
- Drone-Based Micro-Spraying:UAV application technology converges with GIS-mapped canopy density data. Service providers in Australia's Riverina wine region deploy copper oxychloride via drone fleets for terrain-inaccessible blocks.
Industry Challenges
- BIS Certification Timelines:India's Central Insecticides Board technical grade import approvals stretch 18-24 months. Non-domestic suppliers face working capital strain from inventory holding periods.
- Residue Testing Infrastructure Gaps:Export-oriented growers in developing horticulture clusters lack in-house LC-MS/MS capabilities. Third-party testing backlogs delay harvest timing decisions.
- Legacy Equipment Compatibility:Existing vineyard sprayer fleets require nozzle retrofitting for low-volume copper suspensions. Capital expenditure for precision hardware upgrades strains smaller operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Oxychloride Market |
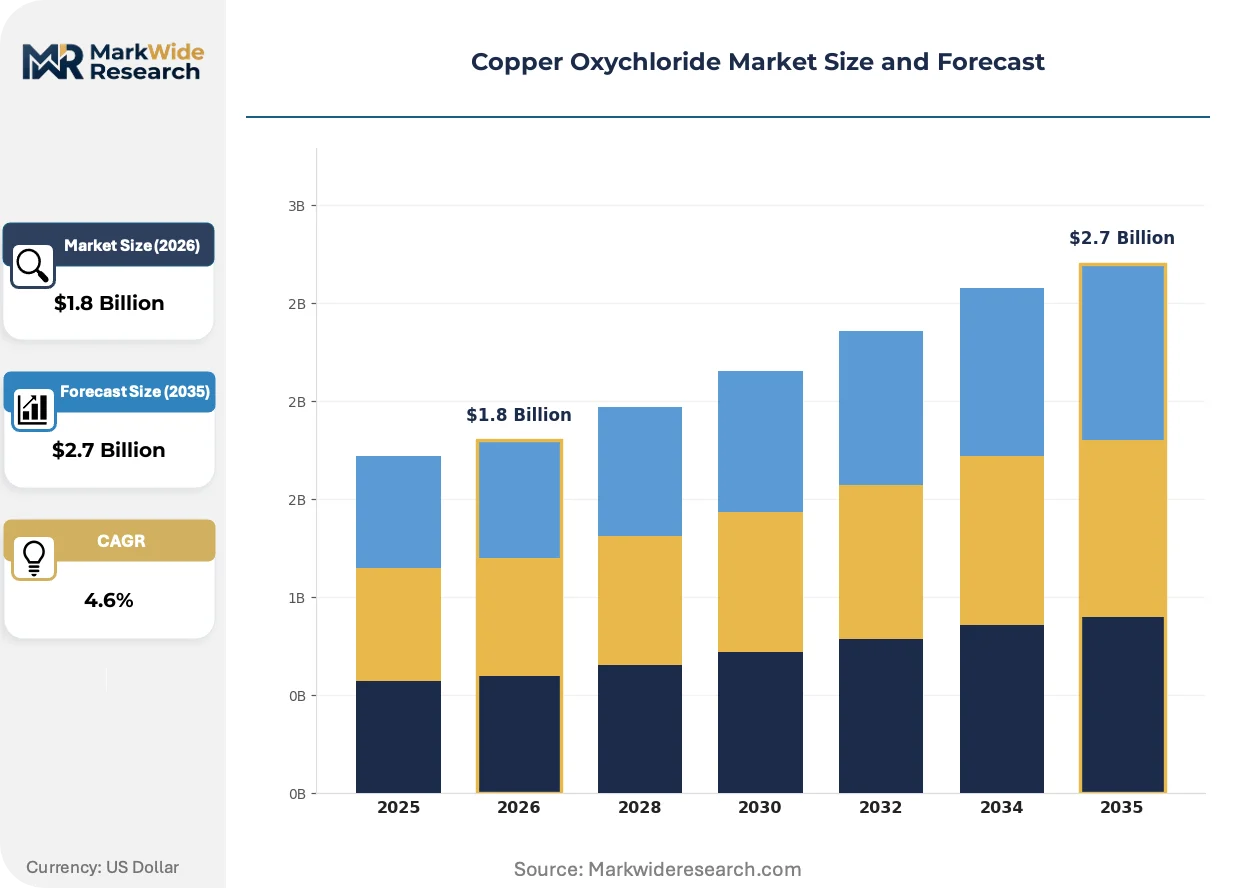
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticide, Fungicide, Herbicide, Bio-stimulant Application: Agriculture, Horticulture, Turf & Ornamental, Soil Treatment End User: Farmers, Agricultural Cooperatives, Retailers, Distributors Distribution Channel: Online Sales, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Prescient Industries Limited, TIB Chemical, Oxiquímica Agroscience, Parikh Enterprises Private Limited, Albaugh, Syngenta, Biota Agro Solutions, Killicks Pharma, IQV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Oxychloride Market Emerging Trajectories
Formulation science is pivoting toward compatibility matrices that bind copper ions with organic chelators, while regulatory chemistry is fragmenting along residue-limit boundaries.
Encapsulated copper delivery systems are virtualizing fungicide persistence in vineyard canopies. These polymer-coated microspheres release copper ions in response to humidity triggers. French and Italian cooperative wineries pilot the technology to reduce application frequency. The approach is virtualizing seasonal labor requirements while compressing total copper loading per hectare.
EPA's revised FIFRA ecological risk assessments for copper compounds are tightening aquatic toxicity benchmarks. The agency's 2024 biological evaluation requirements now mandate sediment organism testing for new registrations. Vineyard operators in California's Central Valley face buffer zone expansion for riparian-adjacent blocks. Formulators are responding with particle size engineering to reduce runoff mobility.
Direct procurement from technical grade manufacturers is displacing distributor intermediaries among large vineyard estates. Australia's Treasury Wine Estates and South Africa's Distell negotiate annual copper oxychloride tonnage contracts directly with Indian and Chinese active ingredient producers. This channel compression concentrates price negotiation leverage with volume buyers. The pattern is most visible in Margaret River and Stellenbosch premium wine regions where estate scale supports dedicated supply agreements.
Copper Oxychloride Market Segmentation
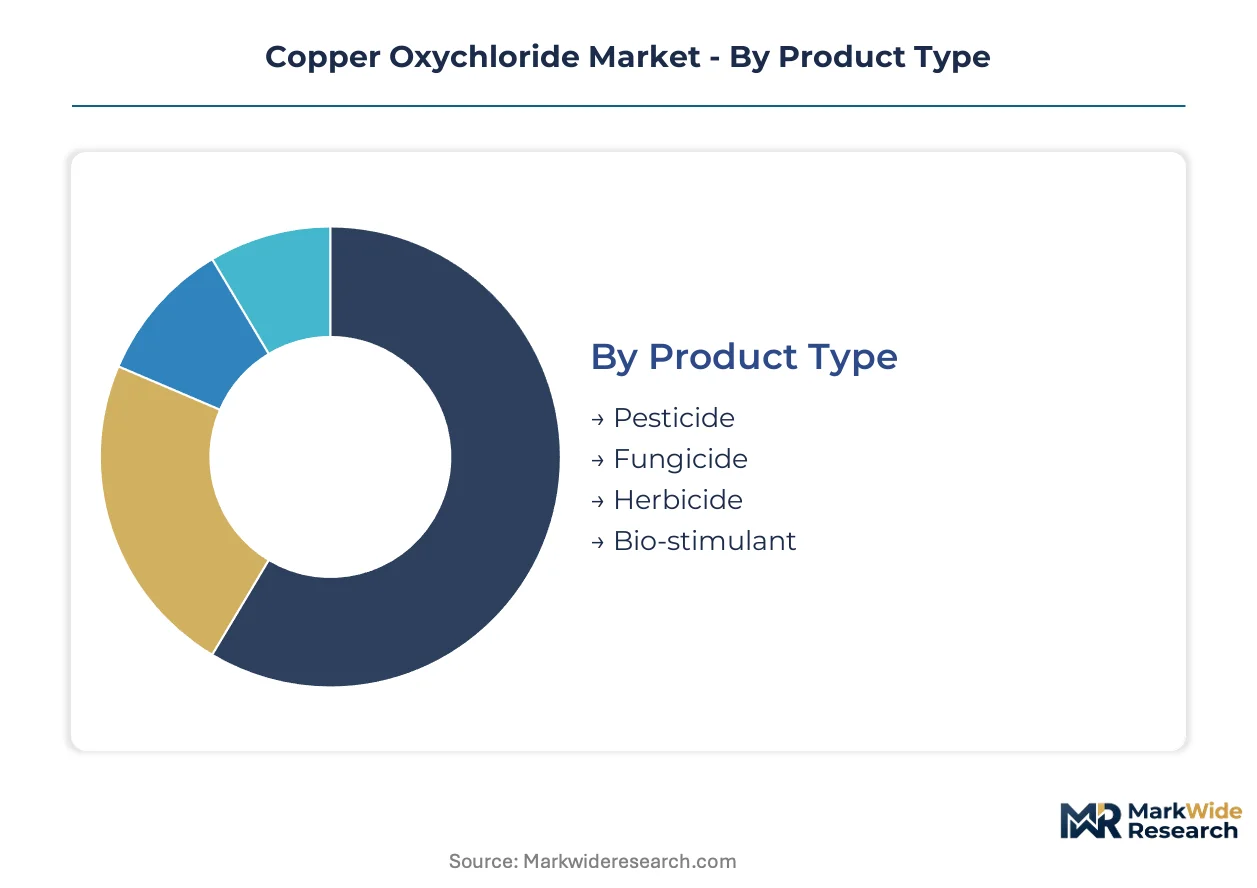
Copper oxychloride procurement patterns diverge sharply across crop protection categories and distribution pathways. Understanding these splits reveals where formulation margins concentrate and which customer relationships command pricing power.
Product Type:
Cost tier differentiation separates commodity-grade bulk sales from precision-formulated premium offerings.
- Fungicide:Broad-spectrum copper chloride formulations dominate vineyard and orchard protocols across temperate growing regions. Maharashtra's grape growers standardize this as dormant spray staple, anchoring volume procurement.
- Bio-stimulant:Microbial inoculant blends incorporating copper trace elements are climbing the fastest as regenerative agriculture certifications tighten. EU Green Deal soil health specifications pull demand toward chelated copper complexes.
- Pesticide:General crop protection applications utilize basic copper oxychloride suspensions for bacterial disease suppression in field vegetables.
- Herbicide:Limited adoption in weed management programs where copper-based algicidal properties target aquatic nuisance species in rice paddies.
Fungicide holds installed capacity. Bio-stimulant is rotating up the share rankings.
Application:
Volume concentration tracks high-value perennial crops versus broad-acre annual rotations.
- Horticulture:Premium wine grapes, citrus, and mango cultivation command batch-specific formulations with tight residue limits. Australia's Margaret River estates negotiate direct technical grade contracts.
- Agriculture:Field crop applications span cereals and oilseeds where copper deficiency correction drives foliar spray adoption. India's Gujarat cotton belt sustains seasonal demand spikes.
- Turf & Ornamental:Golf course superintendents and landscape contractors deploy copper bactericides for anthracnose control in warm-season grasses.
- Soil Treatment:Pre-plant copper amendment for nematode suppression and micronutrient replenishment in intensive vegetable systems.
Horticulture captures margin premiums. Agriculture rotates up the share rankings.
End User:
Customer type determines whether procurement flows through cooperative bargaining or direct manufacturer negotiation.
- Farmers:Individual vineyard operators and orchardists in India's western states anchor spot market purchases. Smaller holdings rely on retailer credit terms and seasonal bundling with equipment services.
- Agricultural Cooperatives:French and Italian winery collectives aggregate copper oxychloride demand into annual tonnage contracts. Cooperative scale enables technical advisory service bundling from Syngenta and Albaugh.
- Retailers:Input supply stores in Kenya's avocado districts and South Africa's citrus belts stock copper formulations for cash crop producers.
- Distributors:Regional chemical wholesalers manage inventory float and BIS certification documentation for Indian import channels.
Agricultural Cooperatives hold installed capacity. Farmers are rotating up the share rankings.
Distribution Channel:
Supply chain configuration determines working capital intensity and regulatory compliance burden.
- Direct Sales:Treasury Wine Estates and Distell negotiate active ingredient procurement straight from Indian and Chinese technical grade manufacturers. Channel compression eliminates distributor margins.
- Wholesale:Bulk tonnage movements through agricultural supply cooperatives in Europe's vineyard regions. REACH documentation and ECHA authorization tracking concentrate at this tier.
- Offline Retail:Physical input stores dominate in developing horticulture clusters where growers require face-to-face application guidance.
- Online Sales:Emerging platform procurement for specialty bio-stimulant formulations in Australia's Riverina and California's Central Valley precision agriculture adopters.
Direct Sales holds installed capacity. Online Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for copper oxychloride diverges sharply between India's fragmented vineyard holdings and Australia's consolidated wine estates. Smallholder procurement in Maharashtra responds acutely to spot copper cathode movements. Large-scale operators in Margaret River and Stellenbosch lock in annual technical grade contracts that buffer raw material volatility.
India
Maharashtra's grape cultivation belt and Gujarat's mango orchards anchor regional demand for copper-based dormant sprays. The Central Insecticides Board mandates BIS certification for imported technical grade material, stretching approval timelines to 18-24 months. Nashik's vineyard clusters standardize copper oxychloride protocols, with cooperative procurement aggregating seasonal volumes.
Australia
Treasury Wine Estates and Riverina precision agriculture adopters drive direct manufacturer negotiation for fungicide tonnage. The APVMA regulates agricultural chemical registration with residue limit benchmarks aligned to EU export requirements. Margaret River estates bypass distributor channels entirely, sourcing active ingredient from Indian and Chinese technical grade producers.
France
Bordeaux and Burgundy winery cooperatives aggregate copper oxychloride demand into annual supply contracts with bundled agronomic advisory services. REACH authorisation through ECHA restricts heavy metal impurity thresholds in technical grade imports. Champagne vineyard blocks pilot encapsulated copper delivery systems to reduce application frequency and total copper loading per hectare.
South Africa
Stellenbosch and Western Cape citrus expansion creates underpenetrated demand for copper-based bactericides in avocado and table grape production. The country's national agricultural chemical regulator enforces residue limits calibrated to EU and UK export market access. Local formulators lack technical grade synthesis capacity, opening contract manufacturing entry points for Indian suppliers.
United States
California Central Valley vineyard operators face EPA FIFRA buffer zone expansion for riparian-adjacent copper applications. The agency's 2024 biological evaluation requirements mandate sediment organism testing for new registrations. Washington State's apple and cherry orchards deploy variable-rate application technology to reduce residue variability and aquatic runoff exposure.
Copper Oxychloride Market Vendor Landscape
Integrated agronomic service providers and technical grade manufacturers split the market between formulation bundling and backward integration strategies. The vendor base concentrates around three archetypes: precision agriculture bundlers, active ingredient synthesizers, and contract manufacturing specialists. Competitive positioning hardens through M&A consolidation of regional distributors and capacity expansion into South Asian technical grade production.
Within the precision agriculture bundling tier, Syngenta and Albaugh exemplify the convergence of copper oxychloride supply with sensor-calibrated dosing protocols and vineyard advisory services. Parikh Enterprises Private Limited anchors the contract manufacturing archetype, occupying a position in South Asian technical grade synthesis for branded formulators serving European and Australian export markets. These three entities represent the dominant strategic configurations without exhaustively mapping competitive positions.
| Leading Market Players |
|---|
| Prescient Industries Limited |
| TIB Chemical |
| Oxiquímica Agroscience |
| Parikh Enterprises Private Limited |
| Albaugh |
| Syngenta |
| Biota Agro Solutions |
| Killicks Pharma |
| IQV |
| Others |
Supply Flow & Price Mechanics
The Mumbai-Jawaharlal Nehru Port freight corridor transmits electrolytic copper cathode price volatility directly into Maharashtra vineyard procurement costs, concentrating margin pressure on smaller formulators while enabling large Australian estates to extract volume-based price differentiation through direct technical grade contracts.
Pricing Analysis
After-sales agronomic advisory services now capture the dominant lifetime value tier, with Syngenta and Albaugh bundling precision dosing protocols into multi-year vineyard support contracts. Three-tier pricing structure across premium encapsulated formulations, standard wettable powders, and economy bulk suspensions separates residue-sensitive export growers from domestic commodity buyers. Cost compression in the economy tier is intensifying because Indian spot buyers lack hedging infrastructure against copper cathode swings. Agricultural cooperatives in France and Italy exhibit lowest price sensitivity due to aggregated bargaining power, while individual farmers in Maharashtra's Nashik cluster face acute spot market exposure.
Supply Chain Analysis
REACH authorization restrictions on heavy metal impurities function as de facto export controls limiting non-European technical grade flows into Bordeaux and Burgundy cooperatives. Active ingredient synthesis concentrates in India and China, with technical grade production anchored in Gujarat and Jiangsu provinces. Raw material supply draws from electrolytic copper cathode, hydrochloric acid, and oxidation catalyst feedstocks. Single-source vulnerability concentrates in Indian BIS certification bottlenecks, where 18-24 month approval timelines strain working capital for importers. Distribution runs through direct manufacturer contracts for large estates, cooperative wholesale channels for European collectives, and distributor intermediaries for developing horticulture clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is rotating toward large vineyard estates and agricultural cooperatives as channel compression eliminates distributor margins, fragmenting procurement leverage across consolidated Australian operators and fragmented Indian smallholders.
For Market Incumbents: Build regulatory compliance moats through preemptive ECHA authorization investments and BIS certification pre-positioning. Syngenta should deepen backward integration into active ingredient synthesis to buffer copper cathode volatility. Albaugh must defend against biological fungicide substitution by accelerating encapsulated copper R&D partnerships with Champagne cooperatives. Channel control through direct estate relationships in Margaret River and Stellenbosch anchors pricing power against commodity erosion. For New Entrants and Emerging Players: Establish a beachhead in South African contract manufacturing for technical grade supply to Kenyan and Western Cape citrus expansion zones. Kenya's avocado districts and South Africa's table grape belts present penetrable white-space demand where local formulators lack synthesis capacity. A go-to-market angle through drone-based micro-spraying service partnerships in Australia's Riverina region bypasses legacy equipment compatibility barriers facing smaller vineyard operators. For Investors and Strategic Acquirers: South Asian technical grade specialists with captive BIS certification capabilities and European REACH documentation expertise represent the priority acquisition archetype. Long-term viability over the next decade hinges on positioning upstream of regenerative agriculture certification requirements and carbon credit-linked application protocols. Watch for inflection signals in EPA FIFRA sediment organism testing mandates that could accelerate particle size engineering investments and consolidate formulation capabilities among compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Albaugh's captive production of copper oxychloride technical grade buffers raw material cost transmission. |
| Encapsulated Copper Delivery System Development | French and Italian cooperatives pilot polymer-coated microspheres to reduce application frequency and labor costs. |
| Direct Manufacturer Contract Negotiation | Treasury Wine Estates eliminates distributor margins through annual tonnage agreements with Indian producers. |
| Drone-Based Micro-Spraying Service Launch | Riverina wine region operators deploy UAV fleets for terrain-inaccessible blocks with GIS-mapped canopy data. |
| REACH Authorization Pre-Positioning | Non-European suppliers compress ECHA approval lead times through preemptive heavy metal impurity testing. |
Methodological Framework
A standing panel of vineyard operations managers, agricultural cooperative procurement heads, technical grade plant managers, and copper fungicide formulators provided ongoing calibration against customs data and SEC filings. Primary interviews with Maharashtra grape growers and Bordeaux winery collectives were cross-referenced with BIS certification records, ECHA authorization databases, and APVMA registration filings. Bottom-up tonnage estimates from India's Central Insecticides Board were triangulated against top-down copper cathode consumption patterns reported in industry association data.
Scenario-bracketing across conservative, baseline, and aggressive adoption paths for bio-stimulant formulations shaped projections across the analysis window. Segmentation dimensions modeled include product type tier, crop application intensity, end-user scale, and regional regulatory cluster. CAGRs were derived from weighted average of historical volume trajectories and forward-looking vineyard acreage expansion plans. Industry-specific inputs incorporated copper cathode price elasticity coefficients and encapsulated formulation adoption curves from Champagne pilot programs.
Stress conditions across electrolytic copper price bands, REACH authorization timeline extensions, and biological fungicide substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding vineyard mechanization rates and regenerative agriculture certification penetration. Material shifts in EPA FIFRA aquatic toxicity benchmarks or EU Carbon Border Adjustment Mechanism fungicide protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethanolamine Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Calcium Borate Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Vinyl Acetate Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Tributyl Phosphate Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Elemental Fluorine Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Penoxsulam Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Hydrazine Market