
 Metal Forging Market | 2026-2036
Metal Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Forging Market Intelligence
The divergence in capital investment for large-scale press forging versus specialized closed-die capabilities is redrawing the competitive landscape. ThyssenKrupp Forged Technologies leverages its heavy press capacity to serve the power generation and shipbuilding sectors. In contrast, ATI Forged Products specializes in complex, high-strength alloy components for demanding aerospace applications. Bharat Forge Ltd. competes by supplying a high volume of parts to global automotive OEMs.
Metal forging is a manufacturing process that shapes metal through localized compressive forces, delivered by hammers or presses. This method produces parts with an oriented grain structure, yielding superior mechanical strength and fatigue resistance compared to casting. High-volume hot forging processes serve the cost-sensitive automotive OEMs sector. Conversely, closed die forging delivers the high-precision and material integrity required for critical aerospace components.
Component traceability and material certification standards, enforced by the FAA in the United States, dictate requirements for aerospace suppliers. In Europe, CE marking and quality management systems like ISO 9001 are prerequisites for market entry in industrial applications. China's GB standards for industrial materials also influence production specifications. Success for forging companies hinges on navigating these disparate regulatory regimes while investing in process automation.
Market Dynamics
The central dynamic in the metal forging market is the tension between massive capital investment in heavy press capacity for commodity applications and the focused development of specialized, high-value-added capabilities for advanced alloys and complex geometries in niche sectors.
Growth Catalysts
- Aerospace Lightweighting:Demand from the aerospace industry for lightweight, high-strength forged components made from titanium and nickel superalloys is a primary growth vector, driven by the need for improved fuel efficiency and performance in next-generation aircraft.
- Automotive Electrification:The transition to electric vehicles creates new requirements for forged components, including durable gears for EV transmissions, strong motor shafts, and robust parts for battery pack structures and suspension systems.
- Emissions Regulations:Stricter emissions standards from bodies like the EPA and their European counterparts compel automakers to reduce vehicle weight, stimulating innovation in forging processes and materials like high-strength steel and aluminum alloys.
Market Restraints
- Input Material Volatility:Price fluctuations and supply availability for key raw materials, including specialty steel, aluminum, and titanium alloys, create significant cost uncertainty and can compress margins for forging companies.
- High Capital Expenditure:The substantial upfront investment required for purchasing, installing, and maintaining large-scale forging presses and associated heat treatment equipment constitutes a major barrier to entry and expansion.
- Threat of Substitution:In non-critical applications, forging faces competition from alternative manufacturing processes, such as advanced casting techniques and the use of high-performance polymer composites, which can offer lower costs or weight.
Strategic Opportunities
- Renewable Energy Sector:The expansion of wind and geothermal power generation presents opportunities for large-scale forgings, such as main shafts, gears, and bearings for wind turbines, and durable components for downhole drilling equipment.
- Near-Net-Shape Forging:Advances in process simulation and die design enable the production of near-net-shape components that require minimal subsequent machining, offering significant cost and material savings to customers.
- Hybrid Manufacturing:Integrating forging with additive manufacturing allows for the creation of complex components where a forged base provides core strength and a 3D-printed section adds intricate features, opening new design possibilities.
Industry Challenges
- Skilled Workforce Scarcity:A persistent shortage of skilled labor, including experienced die designers, metallurgists, and press operators, poses a significant operational challenge and can constrain production capacity and quality control.
- Energy Intensity and Costs:Hot forging is an energy-intensive process, exposing manufacturers to volatile energy prices and increasing pressure to comply with environmental mandates, such as those under the EU Green Deal.
- Complex Certification Pathways:The lengthy and expensive qualification processes for new materials or components, particularly those mandated by regulators like the FAA for aerospace, can delay market entry for innovative products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Forging Market |
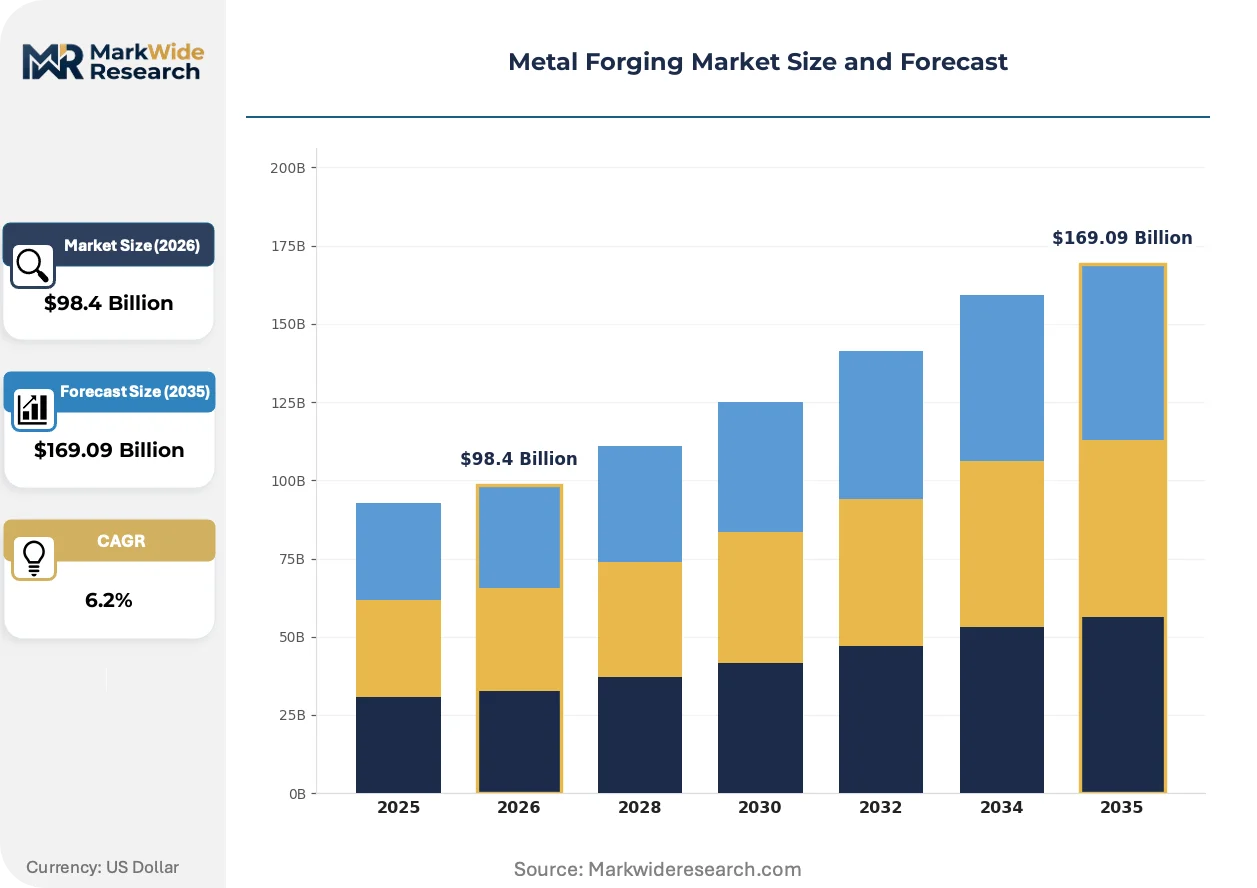
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $169.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Die, Closed Die, Impression Die, Cold Forging, Hot Forging Technology: Press Forging, Drop Hammer, Rotary Forging, Roll Forging, Upset Forging Application: Aerospace Components, Oil & Gas Equipment, Power Generation, Heavy Machinery, Construction Tools End User Industry: Automotive OEMs, Shipbuilding, Mining Operations, Energy Producers, Agricultural Equipment |
| Companies Covered | Scot Forge, Ellwood Group, Bharat Forge Ltd., Japan Casting & Forging Corporation, ATI Forged Products, ThyssenKrupp Forged Technologies, China First Heavy Industries, Larsen & Toubro Limited, Precision Castparts Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Forging Market Strategic Shifts & Innovations
The convergence of digital modeling with advanced material science is redefining the possibilities and economics of metal forging. This shift enables the production of components with unprecedented strength-to-weight ratios and material integrity, pushing the process into new, high-value applications.
Simulation software, particularly finite element analysis (FEA), allows designers to model material flow and thermal effects during the forging process. Aerospace and high-performance automotive sectors are rapidly adopting this technology to shorten development cycles for complex parts. This software-first approach is decomposing the traditional, trial-and-error-based die design process, significantly reducing tooling rework, material waste, and time-to-market for critical components.
European Union directives, specifically the Corporate Sustainability Reporting Directive (CSRD), are mandating greater supply chain transparency. This regulation forces forging suppliers selling into the EU to document and report on energy use, material provenance, and overall carbon footprint. The heavy industrial and automotive sectors are most impacted, compelling investment in digital traceability systems to maintain market access and prove compliance.
A notable shift in purchasing behavior involves moving from transactional, per-part procurement to long-term agreements based on total component lifecycle cost. This change disrupts the commodity spot-market for standard forgings, favoring suppliers who can provide extensive material data and performance guarantees. This trend is most visible in the power generation and commercial aerospace sectors, where equipment uptime is a critical financial and operational metric.
Metal Forging Market Segmentation
The metal forging market categorizes its diverse product offerings and manufacturing methods to address specific industrial requirements. Understanding these segments reveals how different forging processes serve distinct end-use sectors. This segmentation highlights the interplay between material properties, production scale, and precision demands across various applications.
Product Type:
The distribution channels for metal forgings often dictate the optimal product type, balancing cost-effectiveness with performance specifications.
- Hot Forging:This process shapes metal above its recrystallization temperature, enhancing ductility and reducing forming forces. High-volume hot forgings are essential for cost-sensitive automotive OEMs, meeting stringent performance requirements for engine and powertrain components.
- Closed Die:This method uses dies that fully enclose the workpiece, producing complex shapes with high dimensional accuracy and superior grain structure. Critical aerospace components, including turbine blades and structural parts, rely on closed die forging for their integrity and strength.
- Open Die:Open die forging uses flat dies to progressively shape large, custom components, primarily for heavy industrial machinery.
- Impression Die:Impression die forging combines aspects of open and closed die, using dies with cavities that partially enclose the metal.
- Cold Forging:Performed below the recrystallization temperature, cold forging improves surface finish and mechanical properties for smaller, precision parts.
Hot Forging dominates the installed base of large-scale production. Closed Die is where expansion concentrates for high-value applications.
Technology:
The choice of forging technology directly correlates with the desired application, influencing component size, complexity, and material properties.
- Press Forging:Hydraulic or mechanical presses apply continuous, controlled pressure to deform metal, suitable for large, intricate components and high production volumes. Heavy machinery and power generation sectors utilize press forging for their substantial component requirements.
- Drop Hammer:Drop hammers deliver impact energy to shape metal, offering versatility for various part geometries and material types. This technology finds extensive use in general industrial applications where moderate production runs and robust parts are needed.
- Rotary Forging:Rotary forging involves localized deformation through rotating dies, ideal for producing symmetrical components like gears and shafts.
- Roll Forging:Roll forging reduces cross-sectional areas and redistributes material, commonly used to pre-form stock for subsequent operations.
- Upset Forging:Upset forging increases the diameter of a workpiece by compressing its length, often for automotive valve stems and fasteners.
The Press Forging segment is expanding most quickly in capital-intensive industries, while Drop Hammer continues to hold significant market share across diverse manufacturing needs.
Application:
Component volume requirements heavily influence the selection of forging applications, driving economies of scale for specific industries.
- Aerospace Components:Forged aerospace components require exceptional strength-to-weight ratios and fatigue resistance, often using titanium and nickel superalloys. The demand for improved fuel efficiency in next-generation aircraft drives innovation in this high-value segment.
- Heavy Machinery:This application segment includes large, durable forged parts for construction, mining, and agricultural equipment, demanding high wear resistance. Industrial activity in China continues to concentrate a significant share of demand for these robust components.
- Oil & Gas Equipment:Forged parts for oil and gas equipment must withstand extreme pressures and corrosive environments, including wellhead components and drilling tools.
- Power Generation:Power generation applications utilize large forgings for turbine shafts, generator components, and nuclear reactor parts, demanding high integrity.
- Construction Tools:Forged construction tools, such as hammers and wrenches, require high impact strength and durability for demanding work environments.
The largest volume of forged components flows into Heavy Machinery, with Aerospace Components demonstrating significant growth potential.
End User Industry:
Supply concentration within specific end-user industries often dictates the specialized capabilities and material certifications required from forging suppliers.
- Automotive OEMs:This sector demands high-volume, cost-effective forged components for engines, transmissions, and suspension systems. Vehicle lightweighting initiatives to meet stricter emissions standards compel automakers to innovate in forging processes and materials.
- Energy Producers:Energy producers require durable forgings for both traditional and renewable energy infrastructure, including wind turbine shafts and oil rig components. The expansion of wind and geothermal power generation presents opportunities for large-scale forgings in this sector.
- Shipbuilding:Shipbuilding utilizes large, robust forgings for propeller shafts, rudder stocks, and engine components, demanding high reliability.
- Mining Operations:Mining operations rely on heavy-duty forged parts for excavation equipment, crushers, and conveyor systems, requiring extreme wear resistance.
- Agricultural Equipment:Agricultural equipment uses forged components for tractors, harvesters, and implements, requiring strength and durability in harsh conditions.
The Automotive OEMs sector drives consistent demand for high-volume parts, whereas innovation in Energy Producers is creating new market avenues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global metal forging market exhibits a complex trade dynamic, with some nations serving as significant exporters of finished forged components while others concentrate on raw material extraction and domestic consumption. This balance influences regional investment in advanced forging technologies and specialized material processing. Demand for high-strength components is driving localized production capabilities.
China
Demand for heavy machinery and automotive forgings drives significant production capacity in China. The country's GB standards influence material specifications for industrial applications. Manufacturing hubs like the Yangtze River Delta concentrate investment in large-scale hot forging operations.
United States
Aerospace lightweighting and automotive electrification create strong demand for advanced forgings in the United States. The FAA enforces stringent material certification standards for critical aircraft components. Major industrial clusters in states like Ohio and Michigan focus on high-precision closed-die forging.
Germany
Europe's industrial powerhouse, Germany, drives demand for high-precision forgings in its automotive and industrial machinery sectors. CE marking and ISO 9001 are prerequisites for market entry. The Rhine-Ruhr region remains a center for advanced press forging technologies.
India
Infrastructure development and a growing automotive industry fuel demand for metal forgings across India. The PLI scheme encourages domestic manufacturing and technology adoption in key sectors. Industrial corridors, such as those in Maharashtra and Gujarat, are expanding forging capacities.
Japan
Advanced manufacturing in Japan requires high-performance forgings for its automotive and industrial equipment industries. JIS standards ensure material quality and production consistency. The Chubu region, home to major automotive OEMs, leads in specialized forging processes.
Metal Forging Market Key Industry Players
Concentration sits with large, vertically integrated forging houses that serve multiple heavy industries. The metal forging market exhibits a tiered structure, ranging from global giants with extensive heavy press capacity to specialized regional players. Strategic archetypes include high-volume commodity producers and niche providers of complex, high-strength components. Capacity expansion and strategic partnerships remain dominant competitive moves across the sector.
Among the leading market participants, India-based Bharat Forge Ltd. exemplifies a high-volume producer supplying global automotive OEMs. Germany's ThyssenKrupp Forged Technologies represents a major player leveraging extensive heavy press capacity for sectors like power generation. US-based ATI Forged Products occupies a position as a specialist in complex, high-strength alloy components for demanding aerospace applications. These entities collectively underscore the market's differentiation between commodity and high-value-added forging capabilities.
| Leading Market Players |
|---|
| Scot Forge |
| Ellwood Group |
| Bharat Forge Ltd. |
| Japan Casting & Forging Corporation |
| ATI Forged Products |
| ThyssenKrupp Forged Technologies |
| China First Heavy Industries |
| Larsen & Toubro Limited |
| Precision Castparts Corp. |
Cost & Logistics Intelligence
Three-month lead times for high-precision aerospace forgings influence pricing power for specialized manufacturers, reflecting the intricate supply chain and stringent certification processes. This extended delivery window underscores the reliance on advanced capabilities and material traceability across the ecosystem.
Pricing Analysis
Configured-to-order pricing for specialized components like turbine blades commands a premium over standard commodity forgings. The dominant pricing model remains contract-based long-term offtake agreements, particularly with major automotive OEMs and aerospace primes. Price differentiation stems from material integrity and certification level, such as FAA approval for critical aerospace parts. Pricing softness runs through high-volume hot forged parts due to intense competition from Chinese manufacturers. Automotive OEMs are the most price-sensitive segment, prioritizing cost-effectiveness for mass-produced components, while aerospace buyers value performance over immediate cost.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume automotive forgings, while strategic stockpiles support critical aerospace and power generation applications. Geographic supply concentration for raw materials centers on Australia for iron ore, China for specialty steels, and the United States for titanium alloys. Raw material volatility for nickel and titanium creates a significant supply chain risk. Distribution runs through a mix of direct sales to large OEMs and a network of specialized distributors serving smaller industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal forging presents a significant service-attach opportunity, with recurring revenue from inspection, certification, and lifecycle management services expanding faster than initial component sales.
For Market Incumbents: Fortify core heavy press capabilities by investing in advanced process automation and digital simulation tools. This defends against lower-cost alternatives in commodity segments and enhances efficiency for large-scale projects. Deepen vertical integration into specialized heat treatment and finishing operations to control quality and reduce external dependencies. Counter new entrant threats by accelerating material science R&D for next-generation alloys.
For New Entrants and Emerging Players: A service-layer gap exists in rapid prototyping and small-batch production of complex geometries using hybrid manufacturing techniques. Target niche applications in medical implants or high-performance motors where design complexity and material integrity are paramount. A go-to-market angle focused on co-development with design engineers, offering rapid iteration and material optimization, can unlock new market avenues.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core forging assets with specialized closed-die capabilities. Long-term viability hinges on companies with strong intellectual property in advanced material processing and established aerospace or power generation certifications. The signal to watch for inflection is the increasing adoption rate of near-net-shape forging in new automotive EV platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid Manufacturing | Combines forged strength with additive complexity for next-generation aerospace components. |
| Expand Near-Net-Shape Capabilities | Reduces material waste and machining costs for automotive and industrial customers. |
| Secure Long-Term Raw Material Contracts | Mitigates price volatility for specialty steel and titanium alloys. |
| Automate Quality Control Systems | Enhances component traceability and meets stringent FAA and CE marking standards. |
| Develop Advanced Digital Twin Solutions | Shortens development cycles for complex parts and optimizes production efficiency. |
Research Approach
Cross-validation between primary interviews with industry metallurgists and secondary data from regulatory bodies anchors the qualitative findings. This study involved discussions with plant managers, procurement leads at automotive OEMs, aerospace design engineers, and material scientists. Secondary data sources included industrial association reports, government trade statistics, and company financial disclosures, along with technical publications.
Sensitivity analysis framed the quantitative modeling across the analysis window, evaluating demand shifts under various economic and technological scenarios. The analytical framework segmented the market by product type, technology, application, end-user industry, and regional production capacity. Compound annual growth rates were derived from historical trends and projected future demand, considering factors like vehicle lightweighting initiatives and renewable energy infrastructure build-out.
Material uncertainties — such as unforeseen shifts in global trade policies or rapid advancements in substitute manufacturing processes — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Revision becomes warranted when significant regulatory changes, like new EU Green Deal mandates, cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Aluminum Extruded Products Market
Metals
Copper Foil Market
Metals
Global Aluminium Wire Rod Market
Metals
Global Aluminum Market
Metals
Global Tin Market
Metals
Metal Recycling Market
Metals
Aluminium Rolled Products Market
Metals
Titanium Powder Market
Metals
China Copper Market
Metals
Platinum Market
Metals
Lithium Tungstate Market
Metals
Cobalt Market
Metals
Carbon Steel Market
Metals
Ferro Aluminum Market
Metals
Magnesium Metal Market
Metals
Global Brass Rods Market