
 Global Concrete Superplasticizers Market | 2026-2036
Global Concrete Superplasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Superplasticizers Market Foresight
Multi-source procurement among ready-mix concrete producers is hardening as supply chain resilience takes priority over cost minimization. Sika AG leverages its integrated polymer manufacturing network across Europe and Asia to sustain formulation consistency. BASF SE anchors its position through backward integration into ethylene oxide derivatives. MAPEI S.p.A. competes via specialized distribution partnerships with national infrastructure contractors.
Concrete superplasticizers are high-range water-reducing admixtures, typically composed of polycarboxylate ether copolymers or sulfonated naphthalene formaldehyde condensates, that enable flowable concrete at water-cement ratios below 0.30 without segregation. These additives permit placement of self-consolidating concrete in densely reinforced structural elements while maintaining compressive strength targets above 50 MPa. Polycarboxylate ether formulations command premium positioning due to superior slump retention and compatibility with supplementary cementitious materials. Sulfonated melamine formaldehyde retains share in precast applications where rapid demolding cycles prioritize early strength development. Lignosulfonates occupy economy-tier positioning for non-structural mass concrete where performance thresholds remain modest.
The US EPA construction sector guidelines, China's GB 8076 admixture standards, and the EU Green Deal embodied carbon thresholds collectively elevate product performance requirements while restricting legacy chemistries. REACH registration burdens and F-Gas Regulation spillover effects are reshaping polymer feedstock sourcing decisions for European formulators. Stakeholders must monitor divergence between regional low-carbon concrete certifications and admixture compatibility protocols to avoid specification lockout in cross-border infrastructure tenders.
Market Dynamics
Polycarboxylate ether copolymer chemistry is consolidating competitive advantage as infrastructure specifications harden across high-rise construction corridors. Formulation consistency now separates procurement winners from specification lockouts.
Growth Catalysts
- GB 8076 admixture standards:China's tightening concrete durability requirements force specification upgrades from sulfonated naphthalene to polycarboxylate ether systems in megacity construction.
- Self-consolidating concrete placement:Densely reinforced structural elements in high-rise towers demand flowable mixes below 0.30 water-cement ratios without segregation.
- Supplementary cementitious material compatibility:Fly ash and slag blends in low-carbon concrete require polycarboxylate ether retention properties unavailable in legacy chemistries.
Market Restraints
- Ethylene oxide derivative volatility:Backward integration into polymer feedstocks demands capital commitments that mid-scale formulators cannot sustain.
- REACH registration burdens:European polymer feedstock sourcing faces ECHA compliance costs that favor integrated multinationals over regional specialists.
- Sulfonated melamine formaldehyde substitution ceiling:Precast rapid-demolding applications resist polycarboxylate conversion due to early strength development requirements.
Strategic Opportunities
- India's PLI scheme for construction chemicals:Domestic manufacturing incentives attract technology transfer partnerships for polycarboxylate ether production.
- EU Green Deal embodied carbon thresholds:Low-carbon concrete certifications create specification pull for admixtures enabling cement reduction.
- Digital dosing system integration:IoT-enabled ready-mix plant automation creates channel openings for real-time slump control services.
Industry Challenges
- Polymer synthesis technician scarcity:Formulation chemistry expertise concentrates at integrated manufacturers, constraining independent blenders.
- Cross-border certification divergence:GB standards, ASTM C494, and EN 934-2 compatibility testing creates timeline friction for universal product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Superplasticizers Market |
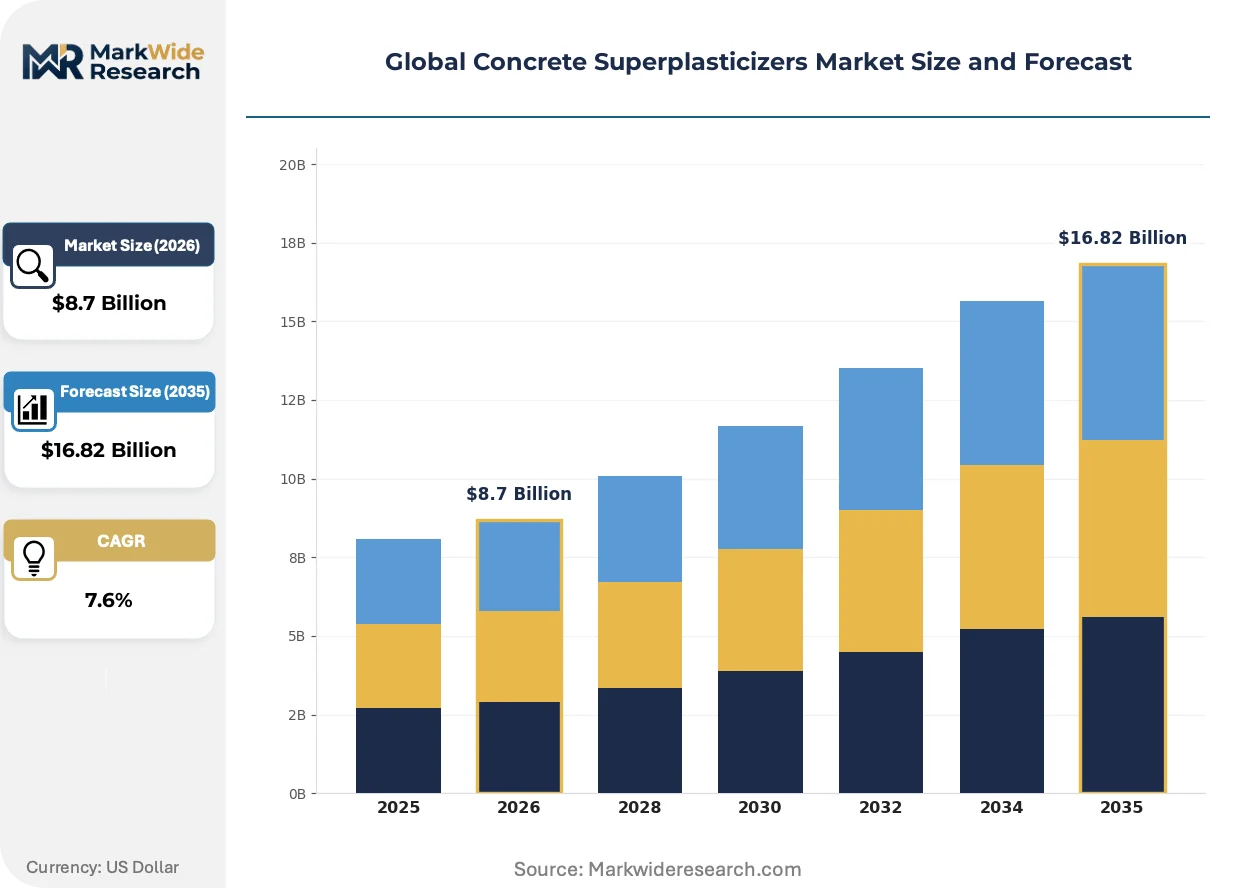
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $16.82 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfonated Melamine Formaldehyde, Polycarboxylate Ether, Sulfonated Naphthalene Formaldehyde, Lignosulfonates Application: High-Rise Buildings, Bridges, Tunnels, Dams, Flyovers, Commercial Complexes End User: General Contractors, Infrastructure Developers, Real Estate Developers, Industrial Construction Firms Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, Retail Suppliers |
| Companies Covered | Sika AG, BASF SE, MAPEI S.p.A., Arkema Group, GCP Applied Technologies Inc., Fosroc Inc., Kao Corporation, Chryso S.A.S., MBCC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Superplasticizers Market Shifts & Advancements
Admixture chemistry is bifurcating between premium polycarboxylate ether systems and legacy sulfonated formulations as performance specifications diverge by end-use. Three forces are compressing competitive timelines.
Polycarboxylate ether molecular architecture with tailored side-chain density enables extended slump retention without retardation. Ready-mix producers in China's Yangtze River Delta are adopting these systems for 90-minute delivery windows. The technology is modularizing formulation platforms, allowing rapid customization for local cement chemistry without full re-registration.
REACH F-Gas Regulation spillover effects are restricting fluorinated polymer feedstock availability for European formulators. ECHA compliance timelines now exceed 18 months for novel polymer introductions. German and French admixture specialists are accelerating bio-based polyether polyol development to circumvent feedstock concentration risk.
Multi-source procurement mandates from national infrastructure contractors are fragmenting long-term supply agreements. Japanese general contractors now require qualified secondary suppliers for megaproject bids. This pattern is most visible in Southeast Asian high-speed rail concrete packages, where consortium risk-sharing protocols demand formulation interchangeability certification.
Global Concrete Superplasticizers Market Segmentation
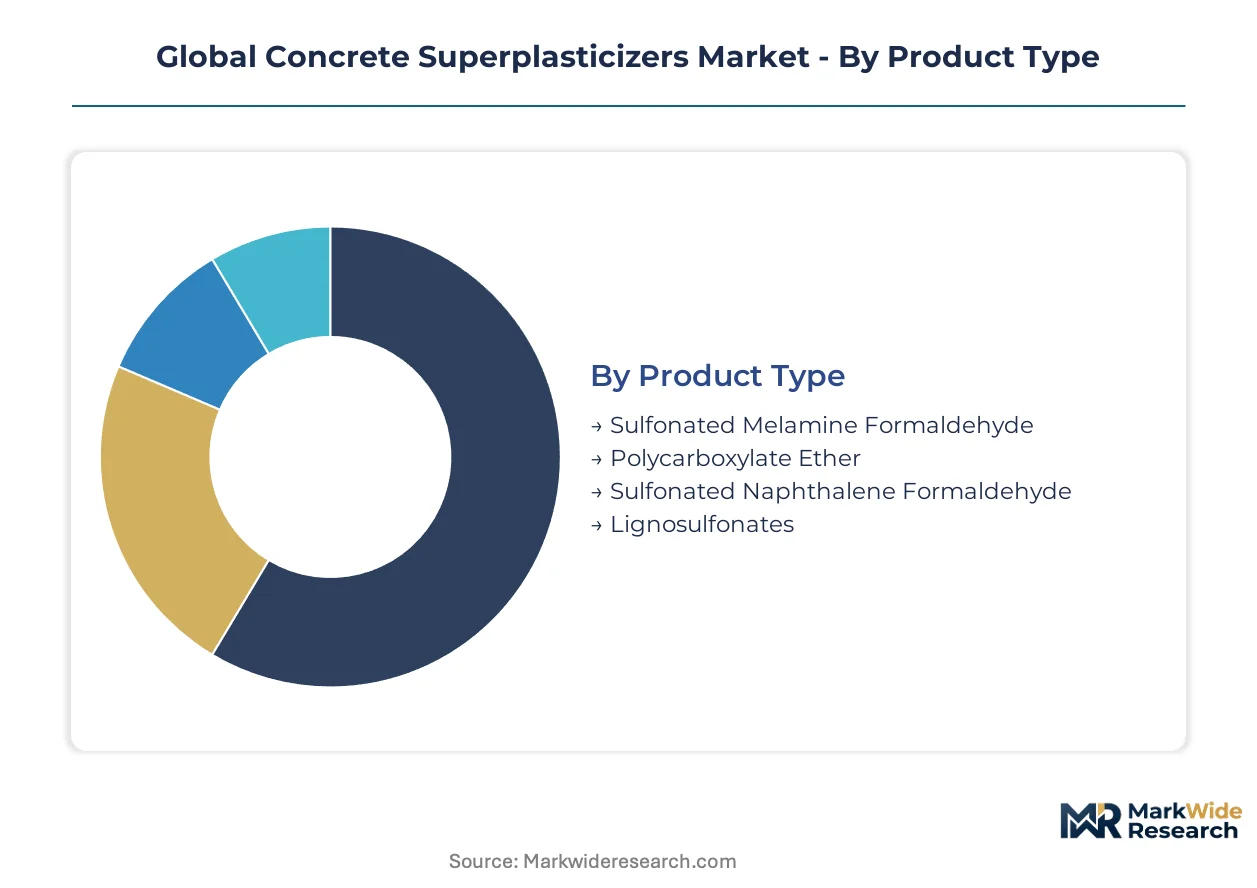
Superplasticizer procurement decisions hinge on performance tier alignment with structural requirements and cement chemistry compatibility. Specification engineers weigh slump retention against early strength development across distinct formulation categories and end-use applications.
Product Type:
Volume concentration favors commodity chemistries, while premium positioning clusters around advanced polymer architectures with tailored side-chain engineering.
- Polycarboxylate Ether:Copolymer systems with adjustable polyethylene oxide side chains deliver extended slump retention above 90 minutes. China's Yangtze River Delta megaprojects specify these formulations for self-consolidating concrete in densely reinforced high-rise cores. GB 8076 durability upgrades are displacing legacy chemistries in municipal procurement.
- Sulfonated Naphthalene Formaldehyde:Condensate polymers retain economy-tier positioning for standard-performance ready-mix applications. Indian infrastructure corridors and Southeast Asian road projects continue specifying these systems where water reduction targets remain moderate. Cost pressures from ethylene oxide derivative volatility constrain formulator margins.
- Sulfonated Melamine Formaldehyde:Rapid demolding cycles in precast concrete manufacturing favor these systems for early strength development.
- Lignosulfonates:Wood pulp byproduct derivatives occupy mass concrete applications with modest performance thresholds.
Mature deployment sits with Sulfonated Naphthalene Formaldehyde. Newer deployment is concentrated in Polycarboxylate Ether.
Application:
Structural complexity and reinforcement density determine admixture performance tier selection across vertical and horizontal construction.
- High-Rise Buildings:Densely reinforced structural elements demand flowable concrete below 0.30 water-cement ratios without segregation. Shanghai, Beijing, and Shenzhen tower projects specify polycarboxylate ether systems for 50+ MPa compressive strength targets. Pumping heights exceeding 300 meters require extended slump retention incompatible with legacy chemistries.
- Bridges:Segmental construction and cable-stayed designs prioritize self-consolidating concrete placement in complex formwork geometries. China's high-speed rail bridge corridors and India's Dedicated Freight Corridor specify high-range water reducers for durability in aggressive exposure conditions.
- Tunnels:Shotcrete applications and lining segments require rapid setting control with sustained workability.
- Dams:Mass concrete placements with low heat-of-hydration requirements favor economy-tier admixtures.
- Flyovers:Urban elevated highway projects balance placement speed with traffic load specifications.
- Commercial Complexes:Mixed-use developments integrate varying performance requirements across structural and architectural concrete elements.
Specification intensity peaks in High-Rise Buildings. Standardized procurement dominates Dams.
End User:
Contractor scale and project portfolio composition shape formulation loyalty versus multi-source procurement strategies.
- Infrastructure Developers:National contractors with megaproject mandates drive specification upgrades through qualified supplier programs. China's state-owned construction enterprises and India's NHAI contractors enforce polycarboxylate ether compatibility testing across cement sources. Risk-sharing protocols in Southeast Asian high-speed rail consortia demand formulation interchangeability certification.
- General Contractors:Diverse project portfolios require flexible admixture sourcing across performance tiers. US commercial construction firms balance ASTM C494 compliance with regional ready-mix supplier capabilities.
- Real Estate Developers:Vertical integration into construction management creates captive specification control.
- Industrial Construction Firms:Process facility and power plant projects prioritize durability specifications for aggressive chemical exposure.
Backward integration pressure concentrates with Infrastructure Developers. Fragmented procurement persists among General Contractors.
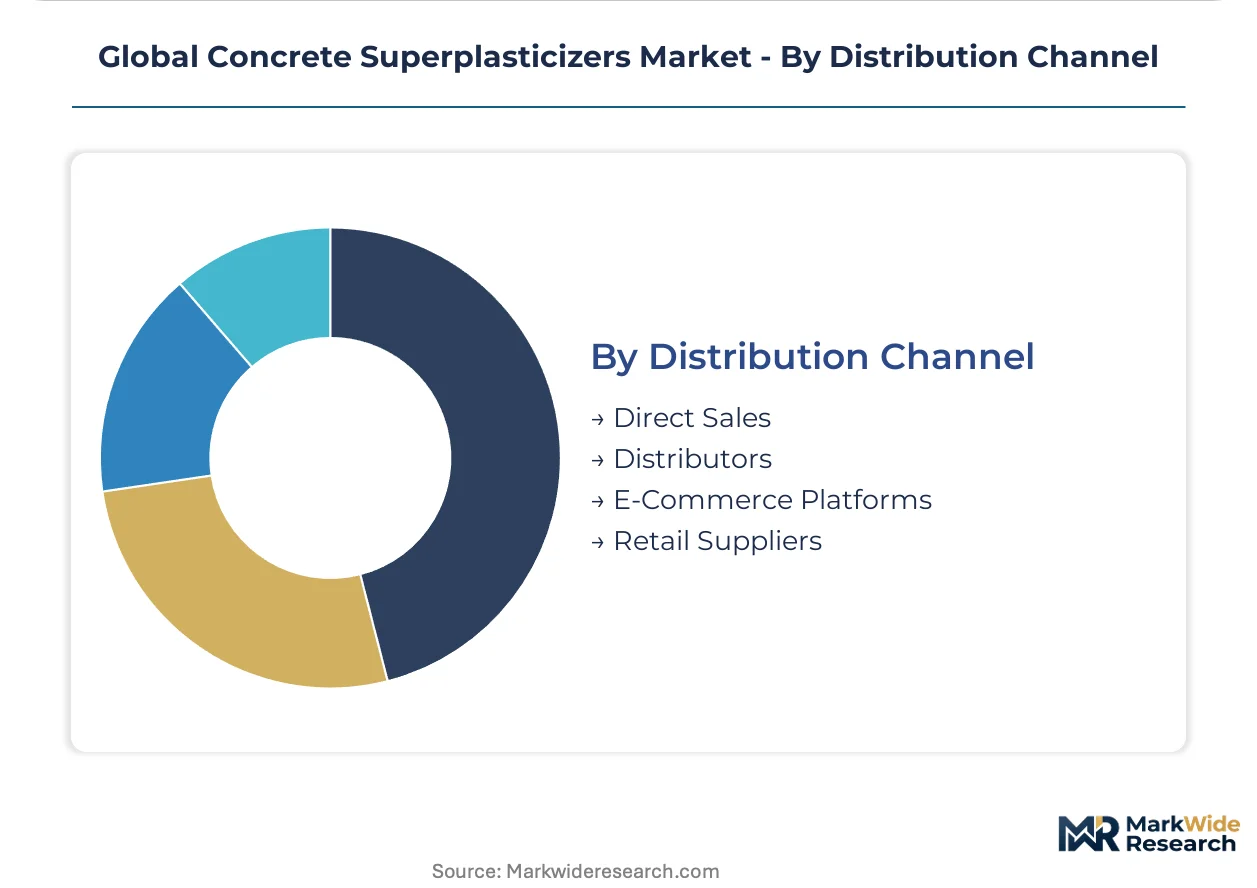
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to manufacturing assets.
- Direct Sales:Integrated multinational suppliers deploy technical field teams for megaproject formulation customization. Sika AG and BASF SE anchor direct relationships with national infrastructure contractors across Europe and Asia-Pacific. Real-time slump control services and IoT-enabled dosing system integration strengthen channel stickiness.
- Distributors:Regional specialists provide logistics coverage for mid-scale ready-mix producers beyond manufacturing plant radii.
- E-Commerce Platforms:Standard-grade commodity admixtures migrate to digital procurement for small-batch and maintenance applications.
- Retail Suppliers:Contractor yard sales serve repair and renovation segments with immediate availability requirements.
Technical service intensity anchors Direct Sales. Transactional efficiency drives E-Commerce Platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide derivative production clusters in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta anchor superplasticizer formulation supply. These feedstock localities determine competitive positioning across construction corridors.
China
GB 8076 admixture standards and dual carbon goals force polycarboxylate ether upgrades in Shanghai, Beijing, and Shenzhen high-rise construction. MEE enforcement tightens legacy chemistry phaseouts. The Yangtze River Delta megacity corridor concentrates procurement for 50+ MPa compressive strength specifications.
Germany
REACH registration burdens and F-Gas Regulation spillover effects reshape polymer feedstock sourcing for European formulators. ECHA compliance timelines exceed 18 months for novel polymer introductions. The Rhine-Ruhr industrial cluster anchors backward integration into ethylene oxide derivatives.
United States
ASTM C494 compliance requirements and EPA construction sector guidelines elevate product performance thresholds. Commercial construction firms balance specification standards with regional ready-mix supplier capabilities. Texas and California infrastructure corridors drive specification intensity for high-range water reducers.
India
PLI scheme incentives for construction chemicals attract technology transfer partnerships for polycarboxylate ether production. NHAI contractors enforce compatibility testing across cement sources. The Dedicated Freight Corridor and urban metro projects concentrate demand in Maharashtra and Gujarat.
Japan
METI procurement guidelines and JIS standards enforce formulation interchangeability certification for megaproject bids. General contractors require qualified secondary suppliers for consortium risk-sharing protocols. Kanto and Kansai construction corridors specify extended slump retention for seismic-resistant designs.
Global Concrete Superplasticizers Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution reach. The vendor base separates into integrated polymer manufacturers, specialized admixture blenders, and construction chemical distributors. Three archetypes dominate: backward-integrated multinationals with captive feedstock supply, technology-licensing regional specialists, and distribution-anchored national contractors. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement shifts toward multi-source qualification.
Within the integrated multinational tier, Sika AG and BASF SE exemplify archetypes combining polymer synthesis with technical field service deployment. MAPEI S.p.A. occupies a position emphasizing specialized distribution partnerships with national infrastructure contractors. These three entities represent distinct strategic postures: Swiss-anchored global manufacturing networks, German-based backward integration into ethylene oxide derivatives, and Italian-focused contractor relationship depth.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| MAPEI S.p.A. |
| Arkema Group |
| GCP Applied Technologies Inc. |
| Fosroc Inc. |
| Kao Corporation |
| Chryso S.A.S. |
| MBCC Group |
| Others |
Supply & Pricing Matrix
National infrastructure contractors in China and Japan concentrate procurement volume through qualified supplier programs, anchoring contract-based long-term offtake agreements that lock in polycarboxylate ether premiums while squeezing sulfonated naphthalene margins. This buyer concentration forces formulators to bundle technical field services with product supply, unbundling pure chemical pricing from slump control guarantees.
Pricing Analysis
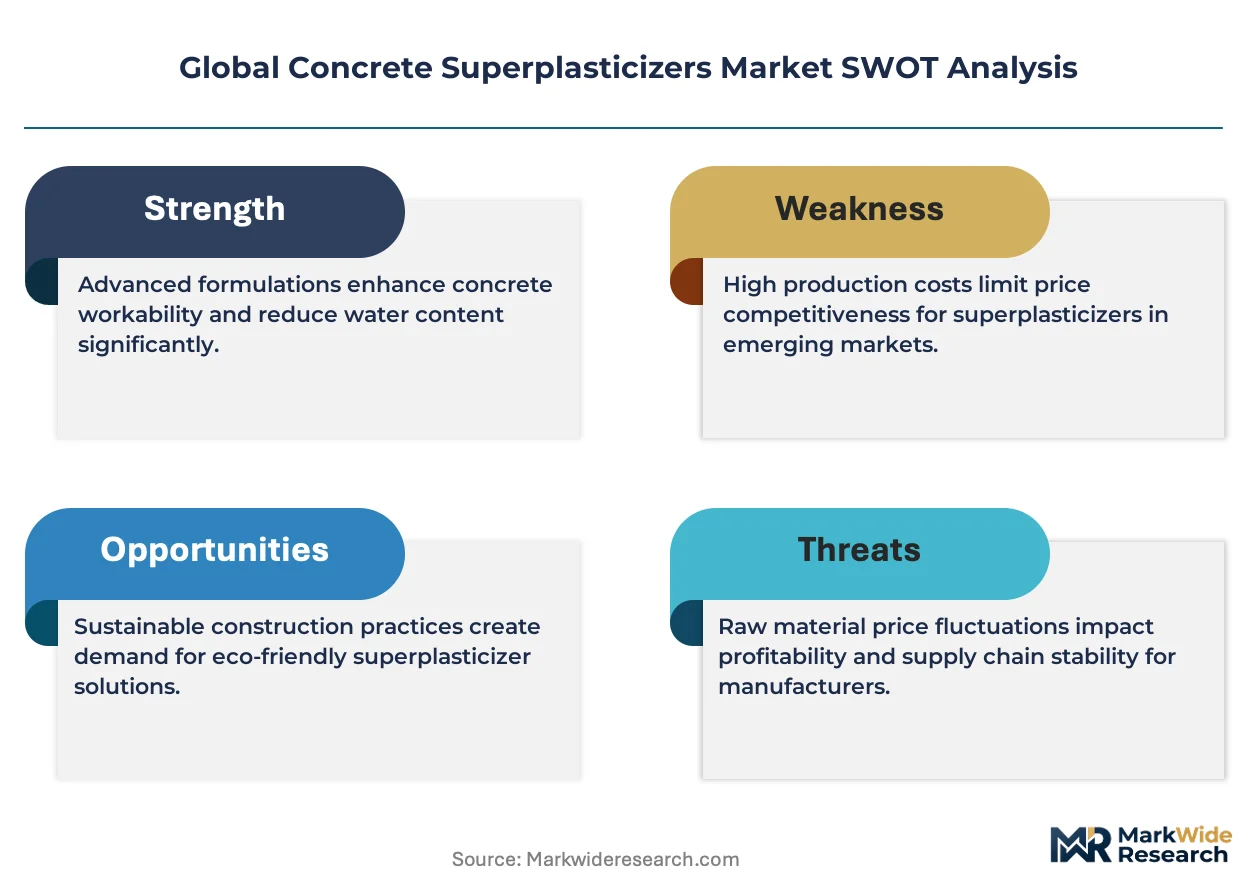
Technical service bundling separates procurement winners from commodity suppliers, with Sika AG and BASF SE embedding real-time dosing optimization into premium contracts while economy-tier lignosulfonates trade unassisted. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—GB 8076 compliance in China commands 15-20% premiums over legacy formulations. Cost compression in sulfonated naphthalene runs through ethylene oxide derivative volatility, squeezing independent blenders without backward integration. Ready-mix concrete producers with multi-source mandates prove most price-sensitive; infrastructure developers with single-source technical partnerships accept premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from Japanese general contractors and Southeast Asian high-speed rail consortia fragment long-term supply agreements, forcing formulation interchangeability certification as a baseline qualification. Manufacturing gravity centers on Germany's Rhine-Ruhr corridor and China's Yangtze River Delta, with ethylene oxide derivative production feeding polymer synthesis. Feedstock supply draws from petroleum naphtha crackers and bio-based polyether polyol development. Single-source vulnerability concentrates in European fluorinated polymer feedstocks restricted by F-Gas Regulation spillover effects. Distribution runs through direct sales for megaprojects and regional distributors for mid-scale ready-mix coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as polycarboxylate ether copolymers displace sulfonated naphthalene formaldehyde across high-rise and infrastructure specifications. Formulation chemistry expertise now separates viable competitors from specification lockouts.
For Market Incumbents: Anchor backward integration into ethylene oxide derivatives to defend margin position against feedstock volatility that crushes independent blenders. Prioritize GB 8076 pre-certification and ASTM C494 dual registration to capture cross-border infrastructure tenders. Expand technical field service deployment in China's Yangtze River Delta megacity corridor where 90-minute slump retention requirements lock out legacy suppliers. For New Entrants and Emerging Players: The gap between premium polycarboxylate ether and economy lignosulfonate pricing creates white-space opportunity for mid-tier sulfonated melamine formaldehyde specialization in precast rapid-demolding applications. Target India's PLI scheme incentives for domestic polycarboxylate ether manufacturing partnerships. Pursue digital dosing system integration as a service-led entry angle, offering IoT-enabled slump control to ready-mix producers without captive technical teams. For Investors and Strategic Acquirers: The window for entry favors regional specialists with certified formulation platforms and established infrastructure contractor relationships over greenfield polymer synthesis investments. Acquisition targets should demonstrate backward integration into ethylene oxide derivatives or locked long-term feedstock offtake. Watch ECHA compliance timeline divergence as the inflection signal—novel polymer introductions exceeding 18-month registration windows will consolidate advantage at integrated multinationals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Captive feedstock supply insulates margins from petrochemical volatility affecting European and Asian formulators. |
| GB 8076 and ASTM C494 Dual Certification | Cross-border infrastructure tenders in China and the US demand compatibility testing across both regulatory frameworks. |
| IoT-Enabled Dosing System Integration | Real-time slump control services create channel stickiness with ready-mix producers in Japan's Kanto construction corridor. |
| PLI Scheme Manufacturing Partnerships | India's domestic production incentives attract technology transfer for polycarboxylate ether supply to NHAI contractors. |
| Bio-Based Polyether Polyol Development | German and French specialists circumvent F-Gas Regulation feedstock restrictions through renewable chemistry pathways. |
Research Methodology
Document review covered customs and trade flow databases, SEC and ECHA regulatory filings, and construction chemical industry association reports, complemented by interviews with technical directors at multinational admixture suppliers, procurement leads at Chinese state-owned construction enterprises, and plant managers at European ethylene oxide derivative manufacturers. Bottom-up volume estimates triangulated against top-down construction spending allocations across high-rise, bridge, and tunnel applications.
Cross-referencing historical price series against expert panel input on specification upgrade timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, structural application intensity, contractor scale archetype, and regional regulatory cluster. CAGRs derived from elasticity-adjusted construction output forecasts and admixture penetration rate assumptions. Industry-specific inputs incorporated cement chemistry variability indices and supplementary cementitious material blend ratios.
Underlying measurement precision varies by segment; polycarboxylate ether volume estimates carry tighter precision than lignosulfonate mass concrete applications due to procurement concentration in qualified supplier programs. Forecasts reflect assumptions on GB 8076 enforcement intensity, REACH registration timeline stability, and ethylene oxide derivative capacity expansion. Deviation in China's dual carbon policy implementation pace or ECHA F-Gas Regulation scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Calcium Hydroxylapatite Fillers Market
Chemicals & Materials
Soy Polysaccharides Market
Chemicals & Materials
Global High Purity Oxygen Market
Chemicals & Materials
Galvanized Steel Market
Chemicals & Materials
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Chemicals & Materials
Fragrance Concentrates Market
Chemicals & Materials
BPA Free Thermal Paper Market
Chemicals & Materials
Aluminum Welding Wires Market
Chemicals & Materials
Hydrogen Gas Analyzers Market
Chemicals & Materials
North America Quicklime Market
Chemicals & Materials
Global Mineral Cosmetics Market
Chemicals & Materials
Montelukast Intermediate Market
Chemicals & Materials
Dielectric Fluid Market
Chemicals & Materials
Coating Thickness Gauge Market
Chemicals & Materials
Water and Wastewater Treatment Technologies Market
Chemicals & Materials
Tempered Glass Market