
 Sugar Dissolvers Market | 2026-2036
Sugar Dissolvers Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Dissolvers Market Insights
Multi-source equipment procurement is recalibrating how North American and European processors secure sugar dissolvers. IKA-Werke GmbH & Co. KG leverages its German engineering heritage to dominate high-shear laboratory and pilot-scale installations. Silverson Machines anchors its position through rotor-stator technology leadership in inline industrial applications. INOXPA competes aggressively on sanitary stainless-steel construction for dairy and beverage clients requiring EHEDG-compliant designs.
A sugar dissolver is a mechanical or electromechanical device engineered to reduce crystalline sucrose into homogeneous aqueous solution, typically achieving dissolution rates above 95% within specified temperature and shear parameters. The equipment serves critical functions across food processing, pharmaceutical syrup preparation, and large-scale beverage formulation where particle uniformity directly impacts product stability and shelf life. Industrial-grade units command the dominant share of value given their integration with automated CIP systems and SCADA-controlled throughput. Magnetic and ultrasonic technologies represent the fastest-expanding categories as manufacturers seek reduced thermal degradation of sensitive formulations. Manual and countertop segments remain mature with thinner margin pools, though home-user demand has shifted toward compact electric models with programmable viscosity targets.
The FDA enforces 21 CFR Part 117 sanitary standards that dictate stainless-steel surface finishes and cleanability validation for food-contact dissolvers, while the EU's Machinery Directive 2006/42/CE mandates CE-marked safety interlocks and noise emission controls on electric units sold in member states. REACH compliance further constrains seal and gasket material selection, pushing manufacturers toward fluoropolymer alternatives. Stakeholders must monitor evolving MDR spillover effects as pharmaceutical-grade dissolution equipment faces heightened traceability and qualification documentation requirements.
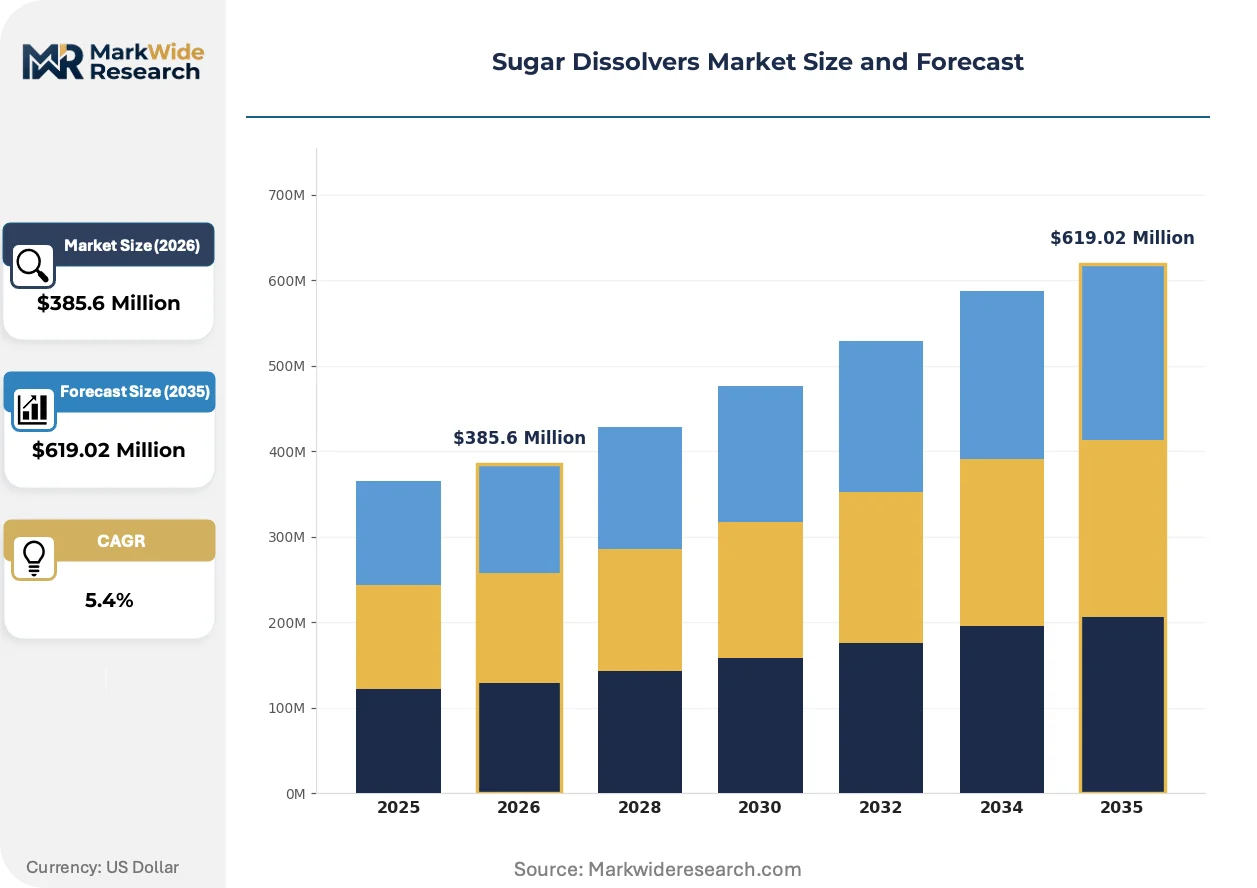
Market Dynamics
The sugar dissolvers market is restructuring around magnetic and ultrasonic dissolution technologies that reduce thermal degradation while meeting FDA's 21 CFR Part 117 sanitary standards. Equipment manufacturers face mounting pressure to integrate automated CIP systems with SCADA-controlled throughput as beverage and pharmaceutical processors consolidate supplier relationships.
Growth Catalysts
- 21 CFR Part 117 Compliance Mandate:FDA sanitary design requirements for stainless-steel surface finishes and cleanability validation force processor upgrades across carbonated beverage and ready-to-drink manufacturing lines.
- Carbonated Beverage Production Expansion:North American and European bottlers are retrofitting dissolution systems to handle higher throughput with reduced energy intensity per liter processed.
- Ultrasonic Dissolution Technology:Non-thermal dissolution methods preserve heat-sensitive pharmaceutical syrups and functional beverage formulations, opening premium equipment segments.
Market Restraints
- Stainless-Steel Input Volatility:EHEDG-compliant 316L stainless-steel pricing fluctuations compress margin pools for sanitary equipment fabricators serving dairy and beverage clients.
- German Engineering Concentration:Precision equipment procurement gravitates toward Baden-Württemberg and Bavaria machine-building clusters, creating supply bottleneck risks for non-European buyers.
- Magnetic Stirrer Substitution:Lower-cost magnetic technologies displace high-shear rotor-stator units in laboratory and pilot-scale applications below 500-liter batch sizes.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's tightened GMP enforcement and export-oriented formulation growth create demand for qualification-documented dissolution equipment in Hyderabad and Ahmedabad clusters.
- REACH-Driven Fluoropolymer Adoption:ECHA restrictions on seal and gasket materials push manufacturers toward captive fluoropolymer production, enabling premium pricing for compliant designs.
- Ultrasonic-Magnetic Convergence:Hybrid systems combining cavitation with variable frequency magnetic fields address viscosity-sensitive applications in probiotic and enzyme-based beverages.
Industry Challenges
- EHEDG Certification Timelines:European Hygienic Engineering and Design Group validation for dairy-grade dissolvers extends 14-18 months, delaying market entry for new equipment platforms.
- SCADA-Legacy Integration Complexity:Brownfield beverage plants struggle to interface modern dissolution controllers with 1990s-era distributed control systems without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Dissolvers Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Countertop, Industrial Application: Food Processing, Beverage Production, Pharmaceutical, Household End User: Manufacturers, Restaurants, Home Users, Laboratories Technology: Ultrasonic, Magnetic, Heating, Mechanical |
| Companies Covered | IKA-Werke GmbH & Co. KG, INOXPA, FrymaKoruma, Silverson Machines, Cargill, Archer Daniels Midland Company, Roquette Group, Tereos Group, Südzucker AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Dissolvers Market Trends and Innovations
Equipment architecture is fragmenting into configurable subsystems as processors demand line-flexibility without full replacement cycles. Three distinct vectors are compressing traditional equipment procurement patterns.
Magnetic dissolution platforms are modularizing around plug-and-play heating jackets and variable-frequency drive controllers. Mid-scale confectionery processors in Belgium and the Netherlands adopt these units to switch between hard candy and fondant production within single shifts. The technology is modularizing what were previously fixed-capital investments into redeployable assets.
REACH Annex XVII restrictions on perfluorinated compounds are forcing seal material transitions before 2026 compliance deadlines. Equipment manufacturers face reformulation costs for O-ring and gasket specifications across dairy and pharmaceutical product lines. German and Swiss fabricators are accelerating fluoropolymer alternative testing to maintain CE-marked product continuity.
Service unbundling is separating dissolution equipment from bundled maintenance contracts. North American beverage processors now procure dissolvers through capital expenditure while sourcing CIP validation and calibration through third-party metrology providers. This bifurcation is most visible in California and Texas carbonated soft drink operations seeking operational expenditure flexibility.
Sugar Dissolvers Market Segmentation
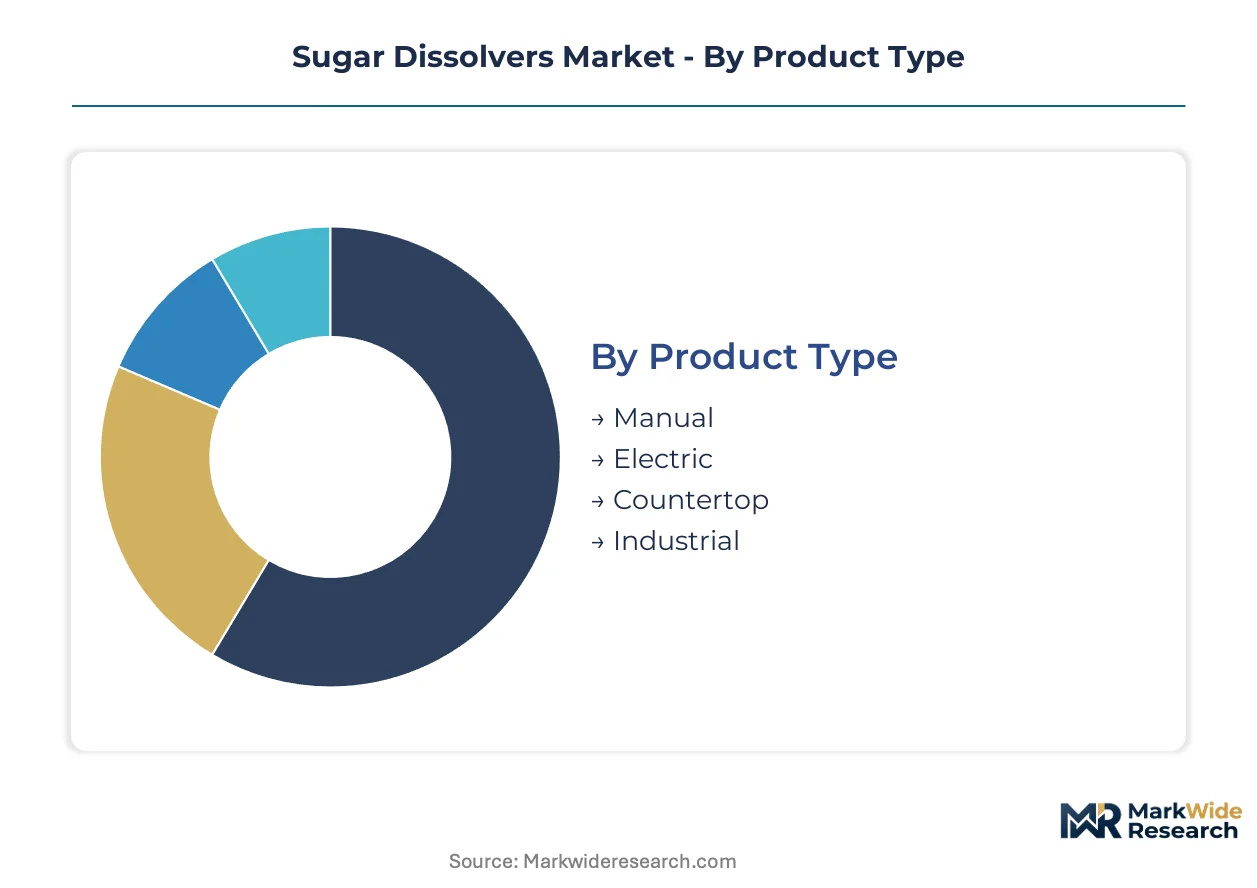
Sugar dissolver procurement splits sharply between capital-intensive industrial installations and low-friction consumer purchases. Equipment specification cascades through four interlocking dimensions that determine sanitary certification requirements, automation integration depth, and lifecycle service economics.
Product Type:
Capital intensity peaks with automated dissolution lines requiring CIP validation and SCADA integration, while manual and countertop units demand minimal upfront commitment.
- Industrial:These systems integrate with automated CIP systems and SCADA-controlled throughput, serving carbonated beverage manufacturers and pharmaceutical syrup operations in Germany and Belgium. Precision engineering standards from Baden-Württemberg fabricators drive premium procurement for units exceeding 10,000-liter batch capacity.
- Electric:Mid-scale units with programmable viscosity targets and variable-frequency drive controllers attract confectionery processors in the Netherlands seeking shift-flexibility between hard candy and fondant production. Modular heating jackets convert fixed-capital investments into redeployable assets.
- Countertop:Compact units serve small-batch food service operations with basic dissolution needs and limited floor space constraints.
- Manual:Hand-cranked or simple mechanical agitation devices persist in artisanal confectionery and developing-market microprocessors with minimal automation requirements.
Most installed capacity flows through Industrial systems. Expansion is steepest in Electric configurations bridging pilot-scale flexibility with production throughput.
Application:
Regulatory stringency varies dramatically across use cases, with pharmaceutical and beverage segments facing the most intensive qualification documentation.
- Beverage Production:Carbonated soft drink and ready-to-drink manufacturers retrofit dissolution systems to handle higher throughput with reduced energy intensity per liter processed. North American bottlers in California and Texas consolidate supplier relationships around automated platforms.
- Pharmaceutical:Heat-sensitive syrup formulations and probiotic applications drive ultrasonic and magnetic technology adoption to preserve active ingredient stability. CDSCO's tightened GMP enforcement in India creates demand for qualification-documented equipment in Hyderabad and Ahmedabad clusters.
- Food Processing:Dairy and confectionery operations require EHEDG-compliant stainless-steel construction with validated cleanability protocols.
- Household:Home-user demand concentrates on compact electric models with simplified viscosity programming for beverage and baking applications.
Beverage Production commands the dominant equipment value flow. Pharmaceutical represents the fastest-climbing specification tier as MDR spillover intensifies traceability mandates.
End User:
Procurement authority separates between centralized manufacturing engineering teams and distributed operational buyers with divergent capital approval thresholds.
- Manufacturers:Beverage, pharmaceutical, and food processing corporations deploy enterprise-wide equipment standardization programs with multi-year service agreements and centralized spare parts logistics.
- Laboratories:Pilot-scale facilities in research-intensive clusters prioritize high-shear rotor-stator technology for formulation development and process scale-up validation.
- Restaurants:Food service chains and independent operators source countertop electric units through foodservice equipment distributors with bundled maintenance options.
- Home Users:Individual consumers purchase through retail channels with emphasis on compact footprint and intuitive viscosity controls.
Manufacturers absorb the majority of industrial-grade unit shipments. Laboratories are gaining share fastest as R&D outsourcing accelerates formulation service demand.
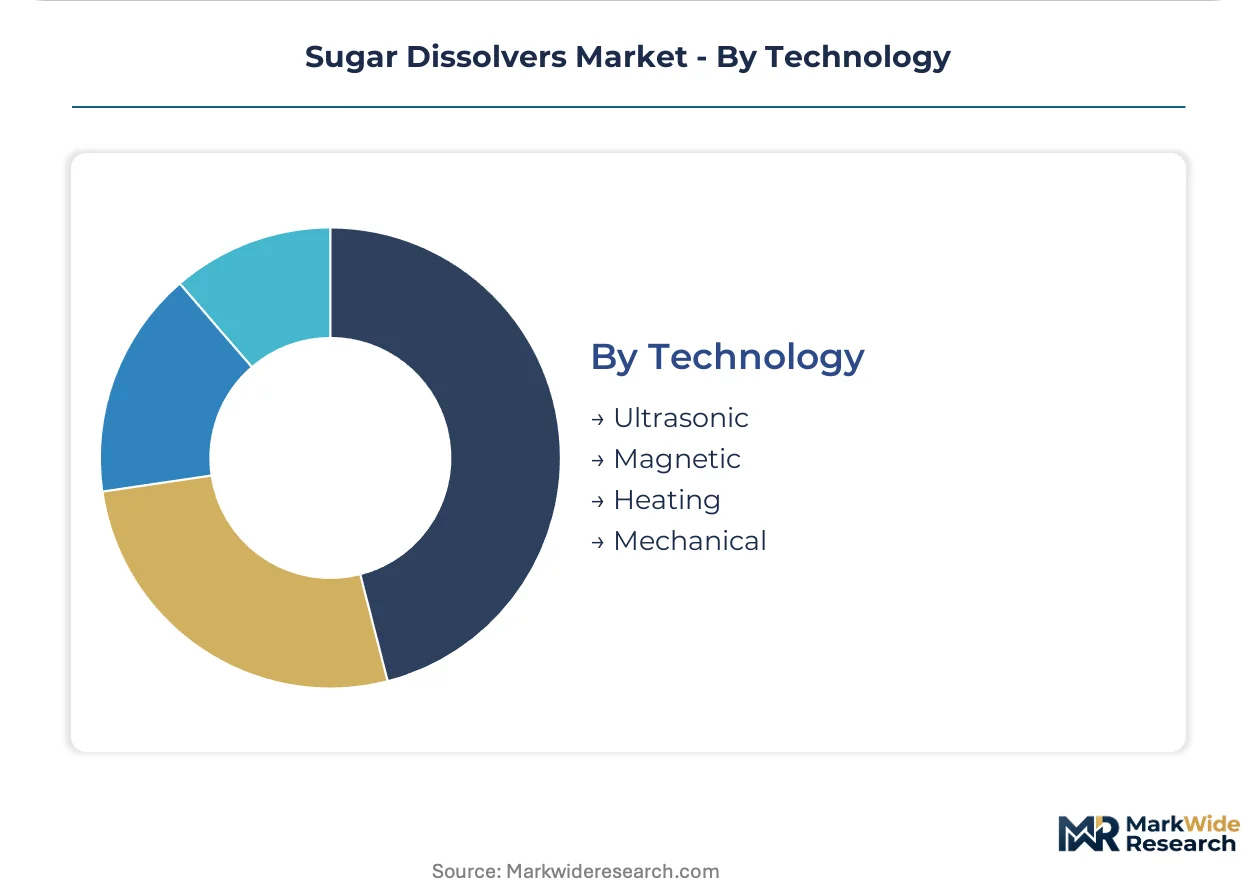
Technology:
Energy transfer mechanisms determine thermal degradation profiles, dissolution kinetics, and compatibility with shear-sensitive active ingredients.
- Ultrasonic:Cavitation-based non-thermal dissolution preserves enzyme and probiotic viability in functional beverages. Hybrid systems combining ultrasonic with variable frequency magnetic fields address viscosity-sensitive applications.
- Magnetic:Variable-frequency drive controllers enable modular platform configurations with plug-and-play heating jacket integration. Mid-scale confectionery processors adopt these for production flexibility.
- Mechanical:Rotor-stator high-shear technology dominates inline industrial applications where particle uniformity directly impacts product stability and shelf life.
- Heating:Direct thermal dissolution remains prevalent in conventional syrup preparation where heat tolerance permits accelerated dissolution rates.
Mechanical systems retain the largest installed base. Ultrasonic platforms are expanding most quickly as manufacturers seek reduced thermal degradation pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg machine-building clusters anchor equipment procurement for precision dissolution systems serving pharmaceutical and confectionery processors. Regional demand patterns diverge sharply between mature European markets prioritizing EHEDG-compliant upgrades and emerging Asian pharmaceutical hubs seeking qualification-documented platforms.
Germany
Bavarian and Baden-Württemberg fabricators supply high-shear industrial units exceeding 10,000-liter capacity to carbonated beverage bottlers. The EU Machinery Directive 2006/42/CE mandates CE-marked safety interlocks on electric dissolvers sold across member states. Stuttgart-based engineering houses dominate premium procurement for confectionery applications requiring validated cleanability protocols.
United States
California and Texas carbonated soft drink operations consolidate supplier relationships around automated platforms with SCADA integration. FDA's 21 CFR Part 117 sanitary standards dictate stainless-steel surface finishes and cleanability validation for food-contact equipment. Midwest beverage processors retrofit dissolution lines to reduce energy intensity per liter processed.
India
Hyderabad and Ahmedabad pharmaceutical clusters drive demand for qualification-documented dissolution equipment as CDSCO tightens GMP enforcement. Export-oriented formulation growth creates procurement urgency for ultrasonic and magnetic technologies preserving heat-sensitive active ingredients. Domestic fabricators compete on cost while European suppliers capture premium qualification-intensive segments.
Belgium
Flemish confectionery processors adopt modular electric units with plug-and-play heating jackets for shift-flexibility between hard candy and fondant production. REACH Annex XVII restrictions on perfluorinated compounds force seal material transitions before 2026 deadlines. Antwerp-area dairy operations require EHEDG-compliant 316L stainless-steel construction for CIP-validated systems.
Netherlands
Mid-scale food processors prioritize redeployable assets converting fixed-capital investments into modular configurations. ECHA restrictions on seal and gasket materials push manufacturers toward fluoropolymer alternatives. Rotterdam-port beverage bottlers seek reduced thermal degradation pathways for functional drink formulations.
Sugar Dissolvers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue magnetic and ultrasonic technology niches with reduced thermal degradation profiles. The vendor base stratifies across German precision engineering houses, Spanish sanitary equipment specialists, and British rotor-stator technology providers. Three archetypes dominate: heritage engineering firms leveraging century-old process knowledge, stainless-steel fabricators competing on EHEDG certification speed, and laboratory-scale specialists defending against magnetic stirrer substitution. Consolidation pressures intensify as beverage processors reduce approved supplier lists from twelve to four vendors per region.
Within the heritage engineering tier, IKA-Werke GmbH & Co. KG exemplifies German precision fabrication for high-shear laboratory and pilot-scale installations. Silverson Machines anchors British rotor-stator expertise for inline industrial applications where particle uniformity governs product stability. INOXPA represents Spanish sanitary stainless-steel construction competing aggressively for dairy and beverage clients requiring rapid EHEDG compliance documentation. These three occupy positions reflecting distinct competitive vectors: engineering heritage, inline industrial specialization, and sanitary certification agility.
| Leading Market Players |
|---|
| IKA-Werke GmbH & Co. KG |
| INOXPA |
| FrymaKoruma |
| Silverson Machines |
| Cargill |
| Archer Daniels Midland Company |
| Roquette Group |
| Tereos Group |
| Südzucker AG |
| Others |
Pricing and Supply Chain Analysis
Precision welding specialists concentrated in Baden-Württemberg command wage premiums that widen pricing spreads between German-engineered premium dissolvers and standardized Asian-fabricated units. Labor-cost differentials between Stuttgart-area machine shops and East Asian metalworking clusters translate into three-tier equipment procurement economics.
Pricing Analysis
EHEDG-compliant 316L stainless-steel input costs pass through directly to equipment price points, with sanitary-grade surface finish requirements adding substantial fabrication premiums. Three-tier pricing structure across premium, standard, and economy levels separates qualification-documented pharmaceutical units from beverage-grade systems and basic food-service models. Cost compression in economy tiers is intensifying because magnetic stirrer technologies displace high-shear units in sub-500-liter applications. Laboratory procurement teams exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize qualification documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore coordinate hub-and-spoke logistics for spare parts and retrofit kits serving beverage bottlers. Component sourcing draws from Germany for precision-engineered rotor-stator assemblies, Spain for sanitary stainless-steel vessels, and Switzerland for fluoropolymer seal materials. Single-source vulnerability concentrates in Baden-Württemberg for high-capacity industrial units exceeding 10,000-liter batch capacity. Distribution runs through OEM-direct channels for large installations and foodservice equipment distributors for countertop electric models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
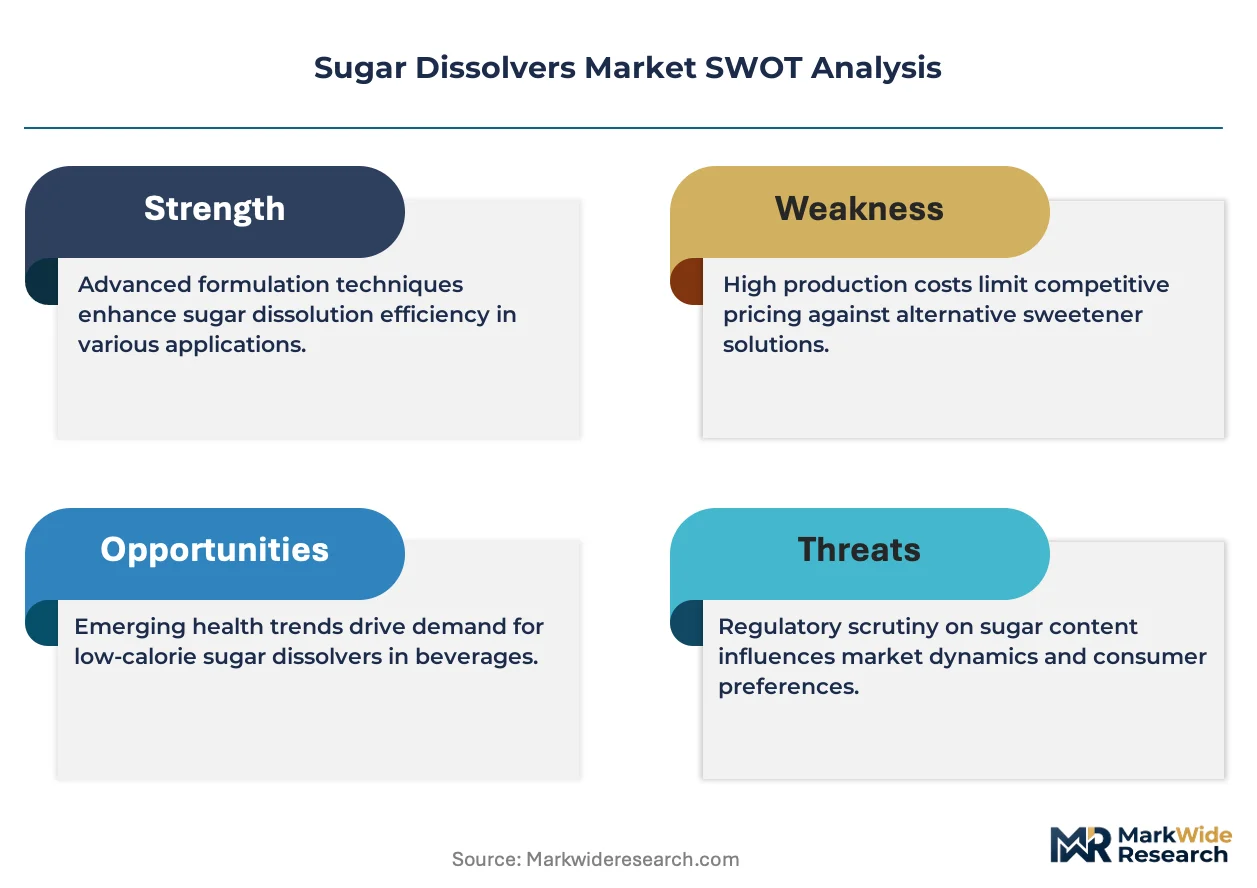
The sugar dissolvers market functions as a regulatory compounder where FDA's 21 CFR Part 117 sanitary standards and REACH Annex XVII material restrictions continuously force processor equipment upgrades.
For Market Incumbents: Cement EHEDG certification agility as the primary defensive moat against Spanish and Italian sanitary fabricators competing on documentation speed. Accelerate captive fluoropolymer seal production to offset REACH-driven material substitution costs. Deepen backward integration into precision machining capacity at Stuttgart-area facilities to defend margin position against Asian cost competition.
For New Entrants and Emerging Players: Direct-to-laboratory digital sales channels bypass incumbent distributor relationships for pilot-scale magnetic and ultrasonic units. Target Indian pharmaceutical clusters in Hyderabad and Ahmedabad where CDSCO's tightened GMP enforcement creates qualification-documented equipment demand without entrenched supplier relationships. Lead with ultrasonic-magnetic hybrid systems addressing probiotic beverage viscosity sensitivity as the differentiated entry wedge.
For Investors and Strategic Acquirers: Beverage conglomerates with consolidated supplier reduction programs are the most active acquirers in this space, seeking captive dissolution equipment capability. Five-to-ten-year viability hinges on ultrasonic technology platform ownership as thermal degradation concerns reshape pharmaceutical procurement. Monitor EHEDG certification backlog durations as the inflection signal—shortening queues indicate competitive pressure intensification.
| Strategic Initiative | Industry Significance |
|---|---|
| EHEDG Certification Acceleration | Reduces 14-18 month validation timelines that delay platform launches for dairy-grade dissolvers. |
| Fluoropolymer Seal Captive Production | Secures REACH-compliant material supply for O-ring and gasket specifications before 2026 deadlines. |
| Ultrasonic-Magnetic Hybrid Development | Addresses enzyme and probiotic viability requirements in functional beverage formulations. |
| Indian Pharmaceutical Cluster Expansion | Captures CDSCO-driven GMP upgrade demand in Hyderabad and Ahmedabad formulation hubs. |
| SCADA-Legacy Integration Partnerships | Enables brownfield beverage plant retrofits without full production line shutdowns. |
Research Methodology
Coverage spans Germany, United States, India, Belgium, and Netherlands, with primary inputs from each territory combined with secondary validation. Interviews with plant engineers at beverage bottlers, pharmaceutical manufacturing directors, EHEDG certification auditors, foodservice equipment distributors, and stainless-steel procurement leads informed demand-side dynamics. Secondary sources included FDA 21 CFR guidance documents, ECHA REACH restriction timelines, CDSCO GMP circulars, EU Machinery Directive compliance databases, and trade customs data for dissolution equipment imports. Bottom-up unit economics triangulated against top-down market sizing across technology and application segments.
Granularity-level modeling disaggregated revenue and volume across product type, application, end user, and technology dimensions with regional production cluster specificity. CAGRs derived from segment-level growth rate reconciliation against macro drivers including regulatory compliance mandates and beverage production capacity expansion. Forecast inputs incorporated EHEDG certification throughput assumptions, stainless-steel price volatility scenarios, and magnetic stirrer substitution elasticity in laboratory segments.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic dissolution would alter the outlook if heat-sensitive formulation demand accelerates faster than projected. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and material substitution timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Oxygenated Solvents Market
Solvents
Methyl Formate Market
Solvents
N-Hexane Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Global Droppers Market
Solvents
Europe Acetonitrile Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Hydrophobic Solvents Market
Solvents
Fluid Neutralizing Market
Solvents
Global Ink Solvents Market
Solvents
Dimethyl Formamide Market
Solvents
Nitromethane Market
Solvents
Citrus Solvents Market
Solvents
Global Glycidol Market
Solvents
Global Tert-Butanol Market
Solvents
Hexylene Glycol Market