
 Industrial Films Market | 2026-2036
Industrial Films Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Films Market Intelligence
The gap between premium performance grades and commodity resin-based films is repositioning procurement patterns across downstream industries. Saint-Gobain Performance Plastics leverages specialized fluoropolymer and silicone film technologies to command pricing power in aerospace and medical barrier applications. Berry Global Inc. anchors its position through massive blown film extrusion scale across North American distribution networks.
Industrial films are polymer-based sheet materials typically manufactured through cast extrusion, blown film, or calendering processes, with thicknesses ranging from micrometers to several millimeters depending on mechanical load and barrier requirements; they serve protective, separation, containment, and functional surface modification roles across manufacturing and logistics chains. Polyethylene formulations dominate volume flows in flexible packaging and agricultural ground cover due to cost efficiency and processability, while PET films capture margin concentration in electronics and optical display substrates where dimensional stability and clarity are critical. Barrier-featured films are outpacing standard grades in food packaging and pharmaceutical blister applications as shelf-life extension becomes a non-negotiable specification.
REACH in Europe, EPA guidelines in the United States, and evolving GB standards in China are collectively restricting phthalate plasticizers and setting recycled content minimums that force reformulation investments across resin suppliers and converters. The EU Green Deal and associated packaging regulations are accelerating demand for biodegradable-featured film alternatives, though performance parity remains unresolved in high-moisture applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven margin erosion and stranded inventory positions.
Market Dynamics
Recycled content mandates across major economies are forcing simultaneous reformulation of resin systems and reconfiguration of extrusion assets, compressing margin structures for converters unable to secure certified feedstock streams.
Growth Catalysts
- REACH compliance deadlines:European converters are accelerating adoption of bio-based polyesters to meet recycled content floors in packaging applications, pulling investment into compatibilizer chemistry.
- Precision agriculture expansion:Controlled-release mulch films are displacing conventional polyethylene ground cover in California's Central Valley and Spain's Almería greenhouse cluster.
- China's manufacturing belt:Massive consumption of protective films for electronics and construction membranes sustains volume demand despite export softness.
Market Restraints
- Crude-linked resin volatility:Naphtha and ethylene price swings transmit directly to blown film converters within 30-60 day lags, eroding contract profitability.
- Fluoropolymer supply concentration:PTFE and PVDF film production clusters in Japan and Germany create chokepoint risk for aerospace and medical barrier specifications.
- Performance gaps in biodegradables:PLA and PHA formulations fail moisture barrier tests required for fresh produce packaging, limiting addressable market expansion.
Strategic Opportunities
- India's packaging modernization:FSSAI enforcement of food-contact material standards is creating certified-film demand as organized retail expands in Maharashtra and Karnataka.
- Photovoltaic backsheet films:Fluorinated copolymer laminates are capturing share from glass-glass modules in utility-scale installations requiring weight reduction.
- EU Green Deal packaging rules:Extended producer responsibility schemes will mandate minimum recycled content thresholds by 2030, advantaging early movers with secured rPET supply.
Industry Challenges
- Extrusion technician scarcity:Blown film die adjustment and gauge control expertise is retiring faster than vocational programs in the US Midwest and Germany's Ruhr region can replenish.
- Multi-layer coextrusion capex:Seven-layer barrier lines require $15-25 million per installation, freezing out mid-scale converters from pharmaceutical and retort pouch qualifications.
- REACH-SVHC testing timelines:Substance of very high concern notifications delay new product introductions by 12-18 months, stranding development investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Films Market |
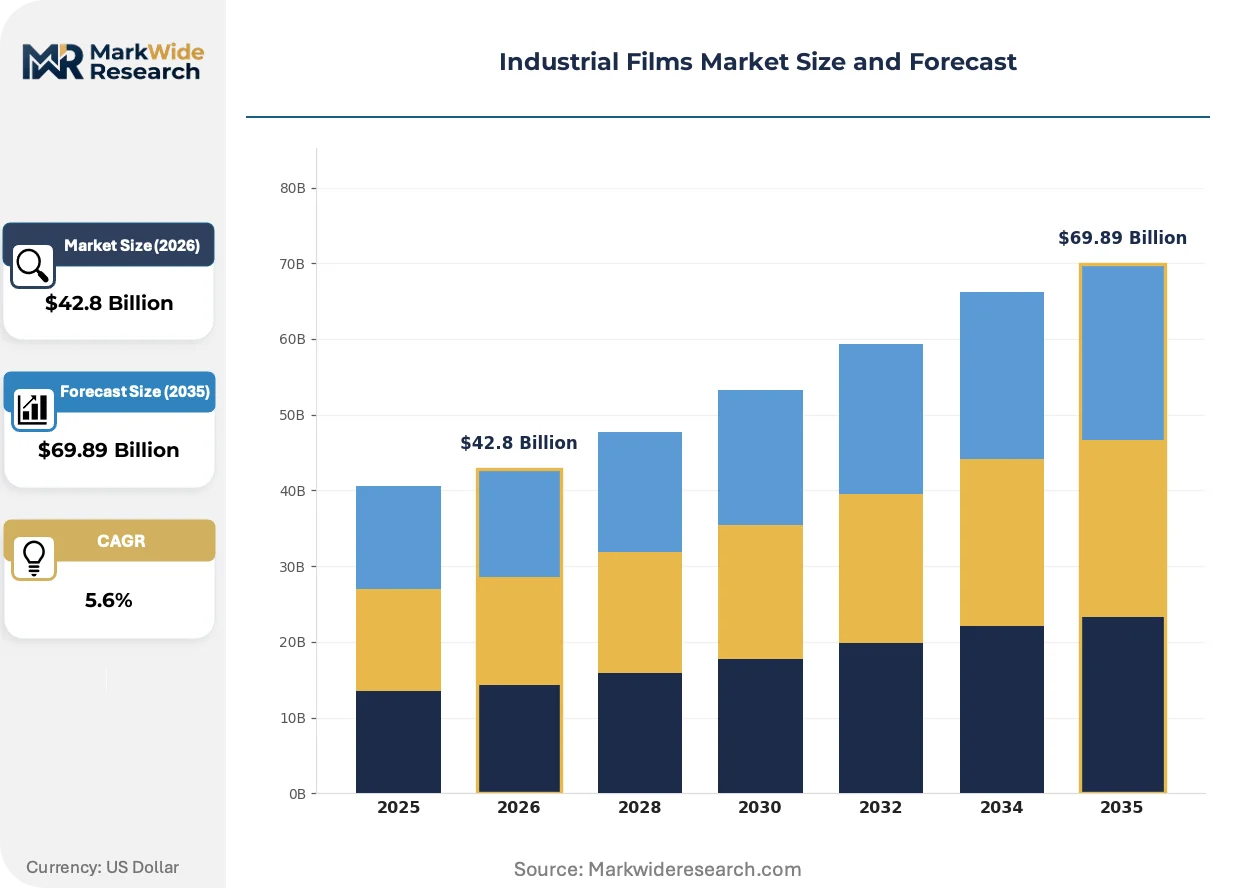
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $69.89 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Agriculture, Construction, Automotive Thickness: Thin, Medium, Heavy, Extra Heavy Feature: Barrier, Biodegradable, UV-Resistant, Antistatic |
| Companies Covered | Saint-Gobain Performance Plastics, Berry Global Inc., Toray Industries, Inc., Eastman Chemical Company, 3M Company, Mitsubishi Chemical Corporation, DuPont de Nemours, Inc., Cosmo Films Ltd, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Films Market Strategic Shifts & Innovations
Digital process control and closed-loop recycling systems are converging to redefine manufacturing economics, while regulatory pressure on chemical content accelerates material substitution cycles.
Machine vision-guided extrusion is automating gauge uniformity in cast film lines serving optical display substrates. Samsung Display and LG Chem are deploying these systems across South Korean fabrication facilities. Real-time thickness feedback is automating raw material yield optimization and reducing startup scrap rates below 3%.
The EU Green Deal's packaging and packaging waste regulation is mandating design-for-recycling criteria that prohibit multi-material laminates in single-use applications. This industrial consequence is forcing converters toward mono-material polyethylene structures. Food packaging and pharmaceutical blister formats in Germany and France are responding with investment in high-barrier EVOH coextrusion compatible with existing mechanical recycling streams.
Buyers in the industrial films sector are consolidating supplier relationships around certified circularity credentials rather than spot price optimization. Large format printing and construction membrane distributors are displacing fragmented broker networks with direct mill relationships. This pattern is most visible in the Netherlands and Denmark where procurement teams now require third-party mass balance certification for all polymer inputs.
Industrial Films Market Segmentation
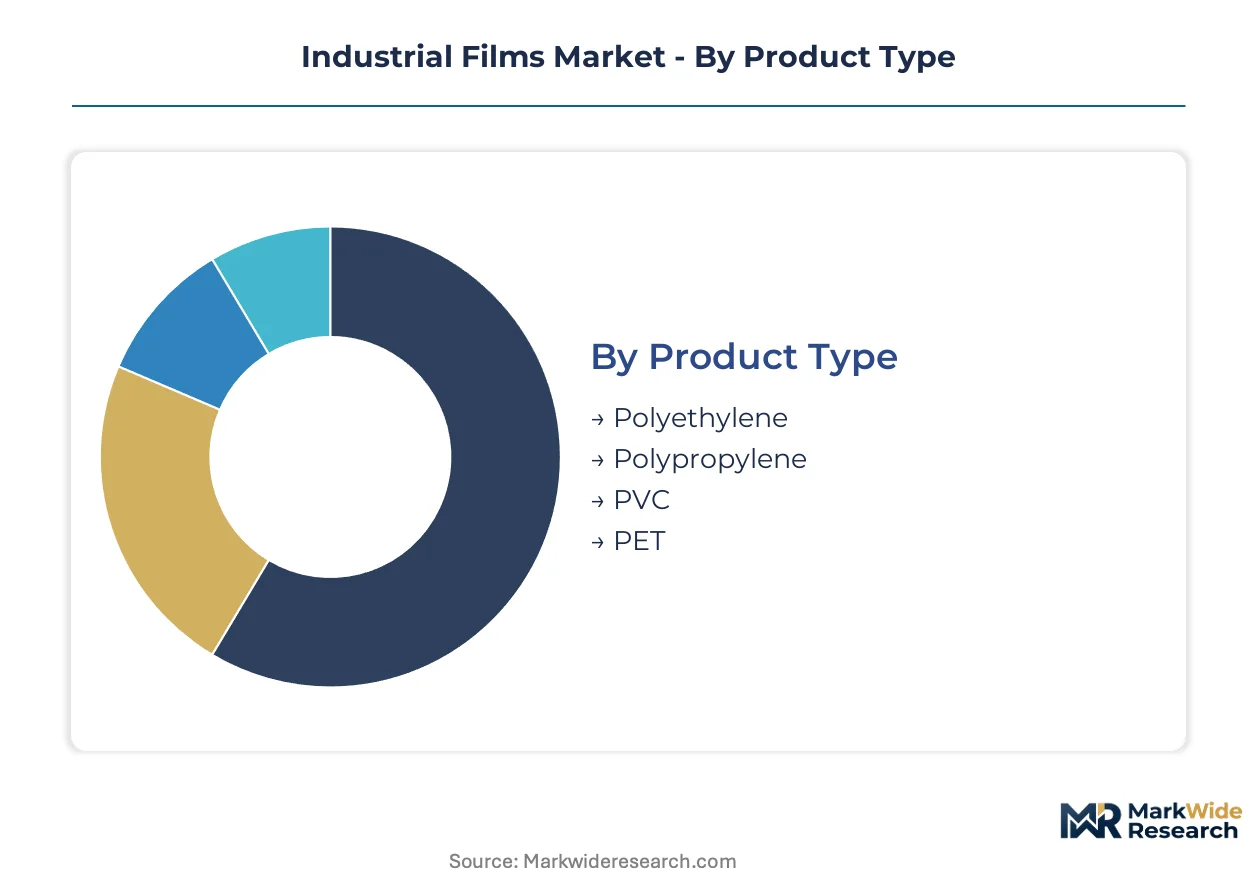
Industrial films serve divergent performance requirements across protective packaging, agricultural ground cover, and engineered barrier applications. Segmentation reveals how resin chemistry, thickness engineering, and functional additives create distinct procurement tiers with varying margin structures and technical qualification barriers.
Product Type:
Buyers differentiate primarily by cost-performance tradeoffs and regulatory compliance requirements rather than brand preference.
- Polyethylene:Linear low-density and high-density formulations dominate flexible packaging and agricultural mulch through superior processability and moisture resistance. Blown film converters in China's manufacturing belt consume massive volumes for electronics protective films despite export softness in adjacent sectors.
- PET:Biaxially oriented polyester films capture premium positioning in electronics substrates and optical display applications where dimensional stability and clarity specifications are non-negotiable. Samsung Display and LG Chem fabrication facilities in South Korea anchor demand for gauge-controlled optical grades.
- Polypropylene:Cast and oriented PP films serve high-clarity food packaging and label stock with lower density advantages versus PET.
- PVC:Calendered and extruded vinyl films retain niche positions in construction membranes and medical blister packs despite REACH-driven plasticizer scrutiny.
Polyethylene leads volumes today; PET is gaining share fastest.
Application:
End-use concentration determines technical qualification depth and contract duration, with food-contact and medical applications imposing the steepest certification barriers.
- Packaging:Multi-layer coextrusion dominates food and pharmaceutical formats where EVOH barrier layers extend shelf life. Germany and France are responding to EU Green Deal mandates with investment in mono-material polyethylene structures compatible with mechanical recycling streams.
- Agriculture:Controlled-release mulch films and greenhouse sheeting are expanding in California's Central Valley and Spain's Almería cluster as precision farming operations displace conventional polyethylene ground cover.
- Construction:Vapor barriers, geomembranes, and protective sheeting demand heavy-gauge calendered or blown films with puncture resistance specifications.
- Automotive:Surface protection films during assembly and interior trim laminates require low-gloss aesthetics and residue-free removal properties.
Packaging commands the largest revenue pool; agriculture is climbing the fastest.
Thickness:
Gauge selection directly correlates with mechanical load requirements and processing equipment constraints across extrusion and converting assets.
- Thin:Sub-25 micrometer films serve high-volume flexible packaging and lamination where yield optimization drives procurement. Machine vision-guided extrusion systems in South Korean optical substrate lines are automating gauge uniformity to reduce startup scrap below 3%.
- Medium:25-100 micrometer specifications balance handling durability with material efficiency in standard industrial wrapping and agricultural mulch.
- Heavy:100-250 micrometer films address construction membranes and dunnage sheeting requiring puncture resistance and load-bearing performance.
- Extra Heavy:Above-250 micrometer calendered or blown structures serve geomembrane containment and heavy-duty protective applications with multi-year service life requirements.
Medium gauge leads volumes today; thin films are expanding most quickly.
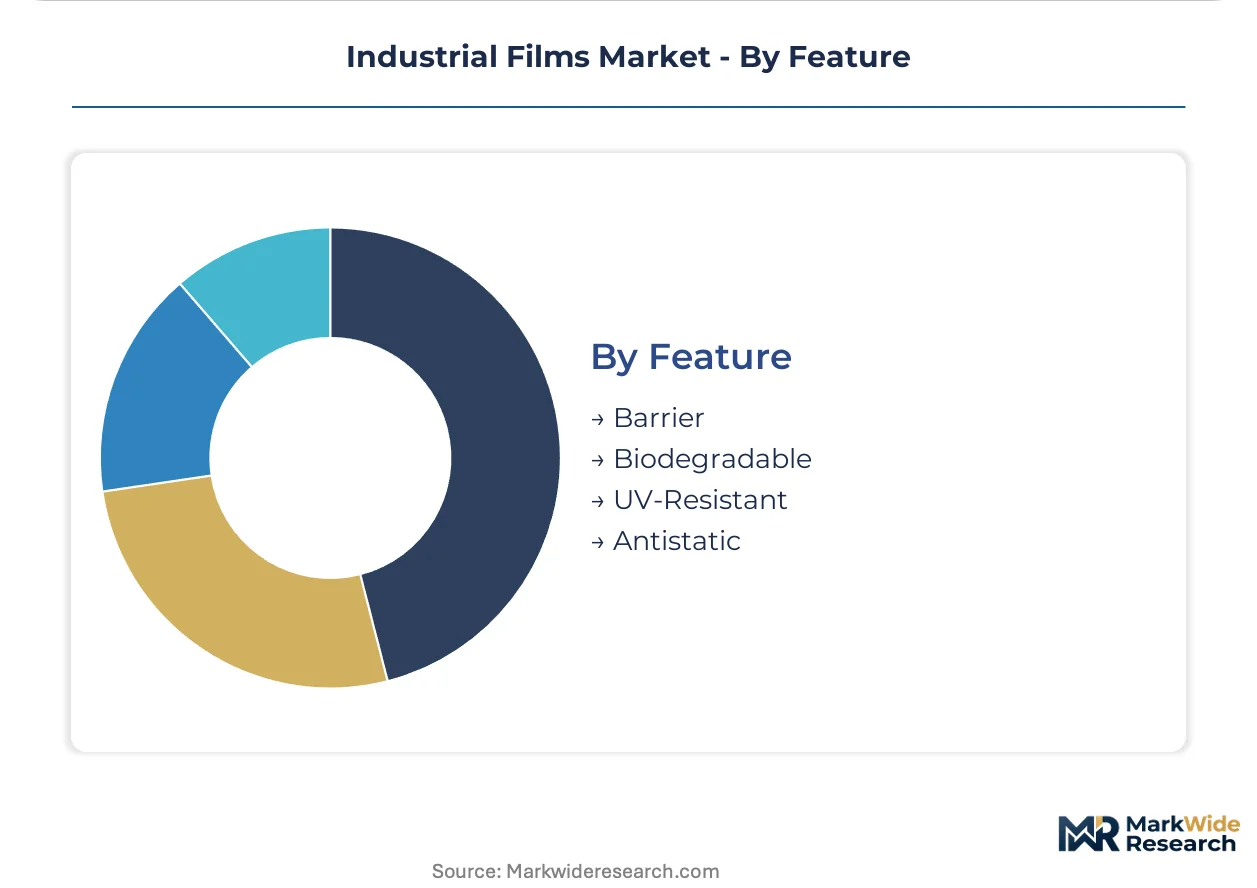
Feature:
Functional additive packages create pricing stratification that separates commodity resin converters from qualified barrier and specialty film suppliers.
- Barrier:EVOH coextrusion and metallized or coated structures are outpacing standard grades in food packaging and pharmaceutical blister applications. The EU Green Deal's design-for-recycling criteria are forcing converters toward mono-material barrier solutions compatible with existing mechanical recycling streams.
- Biodegradable:PLA and PHA formulations face moisture barrier limitations in fresh produce packaging that constrain addressable market expansion despite regulatory tailwinds.
- UV-Resistant:HALS-stabilized formulations extend agricultural film service life in high-insolation regions such as California and Spain's southeastern greenhouse clusters.
- Antistatic:Conductive additive packages protect sensitive electronics during manufacture and shipping, with demand concentrated in China's electronics manufacturing belt.
Barrier films lead volumes today; biodegradable grades are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion technician talent pools in Germany's Ruhr region and the US Midwest anchor operational continuity for precision film manufacturing, while China's manufacturing belt concentrates converter capacity at unmatched scale.
United States
Blown film converters in the Midwest rely on agricultural mulch demand from California's Central Valley and construction membrane orders from Texas. EPA guidelines on chemical content and recyclability force reformulation investments. Chicago-area extrusion facilities face technician retirement waves faster than vocational programs replenish skilled labor.
Germany
REACH compliance deadlines accelerate bio-based polyester adoption among packaging converters serving pharmaceutical and food-contact applications. ECHA substance notifications delay new product introductions by 12-18 months. The Ruhr region's blown film expertise supports barrier film qualification for retort pouch and blister pack formats.
China
Massive consumption of protective films for electronics manufacturing and construction membranes sustains volume demand across the Yangtze River Delta. GB standards on recycled content minimums tighten material specifications. Shenzhen and Suzhou fabrication clusters drive antistatic and optical-grade film procurement.
India
FSSAI enforcement of food-contact material standards creates certified-film demand as organized retail expands in Maharashtra and Karnataka. The central food regulator's testing protocols impose qualification barriers on imported resin formulations. Mumbai-Pune industrial corridor converters invest in mono-material polyethylene structures for snack and dairy packaging.
Japan
Fluoropolymer film production for aerospace and medical barrier specifications concentrates PTFE and PVDF supply chains. METI industrial policy supports advanced materials R&D in barrier coatings. Osaka-area chemical complexes maintain chokepoint positions for high-performance film exports.
Industrial Films Market Key Industry Players
Top-tier vendors anchor premium barrier and specialty segments, while mid-scale converters compete on blown film scale and distribution reach. The vendor base stratifies across three archetypes: diversified chemical conglomerates with captive resin supply, specialized film converters with deep qualification relationships, and regional extrusion houses serving commodity packaging. M&A activity concentrates among North American distributors consolidating fragmented broker networks. Capacity expansion focuses on seven-layer coextrusion lines for pharmaceutical and food barrier applications.
Within the diversified chemical conglomerate tier, DuPont de Nemours, Inc. and Mitsubishi Chemical Corporation occupy positions defined by fluoropolymer and polyester film technology depth. Berry Global Inc. exemplifies scale-driven consolidation across North American distribution networks. Saint-Gobain Performance Plastics represents specialized positioning in aerospace and medical barrier specifications where technical qualification creates pricing power.
| Leading Market Players |
|---|
| Saint-Gobain Performance Plastics |
| Berry Global Inc. |
| Toray Industries, Inc. |
| Eastman Chemical Company |
| 3M Company |
| Mitsubishi Chemical Corporation |
| DuPont de Nemours, Inc. |
| Cosmo Films Ltd |
| Amcor plc |
| Others |
Cost & Logistics Intelligence
Naphtha price index movements transmit directly through ethylene and polyethylene resin contracts, cascading into three distinct pricing tiers across blown film converters. Premium barrier film suppliers command pricing power through REACH-certified formulations and pharmaceutical qualification relationships, while commodity resin converters absorb margin compression from crude-linked volatility.
Pricing Analysis
Bundled technical service and certification support separates premium-tier suppliers from unbundled commodity resin traders. Three-tier pricing structure across premium, standard, and economy levels reflects EVOH barrier content, gauge precision, and pharmaceutical-grade qualification status. Pricing pressure stems from recycled content mandates forcing simultaneous reformulation and extrusion asset reconfiguration. Food-contact and medical blister buyers exhibit lowest price sensitivity due to regulatory qualification switching costs, while construction membrane distributors negotiate aggressively on volume.
Supply Chain Analysis
REACH-SVHC and FDA food-contact certifications gate upstream resin supply, filtering qualified converters from commodity extrusion houses. Raw material flows concentrate in China, Germany, and the United States, with ethylene and naphtha feedstocks drawing from integrated petrochemical complexes. Fluoropolymer film production rests on concentrated PTFE and PVDF supply chains in Japan and Germany. Single-source vulnerability in aerospace-grade fluoropolymer supply creates chokepoint exposure. Distribution runs through direct mill relationships displacing fragmented broker networks in the Netherlands and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial films represent a margin-expansion trajectory as barrier-featured grades displace commodity polyethylene in food packaging and pharmaceutical applications. Cost-down pressure from recycled content mandates simultaneously creates premium-tier pricing power for early movers with secured rPET supply.
For Market Incumbents: Extend qualification relationships into emerging biodegradable-compatible barrier technologies before performance parity resolves. Defend pharmaceutical and retort pouch positions through backward integration into compatibilizer chemistry. Capacity expansion in India's Maharashtra-Karnataka corridor captures FSSAI-driven certified-film demand before import qualification barriers harden.
For New Entrants and Emerging Players: Capture photovoltaic backsheet film demand as fluorinated copolymer laminates displace glass-glass modules in utility-scale installations. India's organized retail expansion offers the most penetrable geography for certified food-contact film qualification. Pursue direct mill relationships with large-format printing distributors in the Netherlands and Denmark requiring mass balance certification.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized converters holding pharmaceutical barrier qualifications and seven-layer coextrusion assets. Long-term viability favors suppliers with secured recycled feedstock streams and REACH-compliant formulation libraries. Watch for EU Green Deal recycled content threshold announcements as inflection indicators for rPET supply scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Secures rPET supply chains ahead of EU Green Deal minimum content mandates. |
| Seven-Layer Coextrusion Capacity Expansion | Qualifies converters for pharmaceutical blister and retort pouch barrier specifications. |
| REACH-SVHC Compliance Investment | Accelerates product introduction timelines currently delayed by substance notification requirements. |
| Joint Venture in India's Industrial Corridor | Positions partners for FSSAI-certified film demand from Maharashtra and Karnataka retail expansion. |
| Machine Vision Extrusion Automation | Reduces optical-grade film startup scrap below 3% at Samsung Display and LG Chem supplier facilities. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's extrusion and converting clusters. The approach combines primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC filings. Bottom-up resin consumption modeling and top-down end-use demand triangulation anchor volume estimates.
Granularity extends to grade tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories reconciled against macroeconomic drivers and regulatory compliance timelines. Forecast inputs incorporate extrusion technician labor availability, seven-layer coextrusion capex cycles, and REACH notification delay distributions.
Crude-linked resin volatility, fluoropolymer supply concentration, and regulatory divergence between REACH, EPA, and GB standards are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in recycled content mandate enforcement timelines or major resin supplier qualification status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Extruders Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Couplings Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Injection Mold Hot Runners Market