
 Polyisocyanurate Insulation Market | 2026-2036
Polyisocyanurate Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisocyanurate Insulation Market Outlook
A shortage of certified spray foam applicators is redrawing competitive boundaries in the Polyisocyanurate Insulation Market. Owens Corning leverages its national contractor certification network to sustain installation quality control across commercial projects. Kingspan Group anchors its position through backward integration into facings and metal skins that pair with rigid board systems. Huntsman Corporation specializes in MDI supply chemistry that underpins polyiso core formulation consistency.
Polyisocyanurate insulation is a thermoset cellular plastic formed by reacting polymeric methylene diphenyl diisocyanate with polyols, yielding closed-cell structures with thermal resistance values typically exceeding R-6 per inch, primarily deployed to reduce heat transfer in building envelopes and industrial equipment. Rigid board dominates value capture due to its established specification in commercial roofing assemblies and proven compatibility with mechanically attached and adhesive applied installation methods. Spray foam represents the fastest-growing product type as contractors seek seamless monolithic barriers for complex geometries in industrial and HVAC end uses where thermal bridging demands meticulous detailing.
The US Department of Energy's building energy codes, the EPA's SNAP program governing blowing agent transitions, and state-level stretch codes in California and Massachusetts are collectively elevating minimum thermal performance thresholds and restricting hydrofluorocarbon-based formulations. These frameworks compel manufacturers to reformulate core chemistry while expanding qualification documentation for code officials. Stakeholders must monitor blowing agent phase-down schedules and pre-position next-generation low-global-warming-potential formulations ahead of enforcement milestones.
Market Dynamics
The US Department of Energy's escalating R-value mandates for roof assemblies are compressing specification windows for lower-performance materials. Cold storage construction across the US Southeast is accelerating demand for high-R-value thermal barriers that meet stringent envelope performance criteria.
Growth Catalysts
- Cold Storage Conversion Wave:Warehouse-to-refrigerated-facility transformations in Georgia and Florida are pulling premium rigid board volumes into distribution center retrofits.
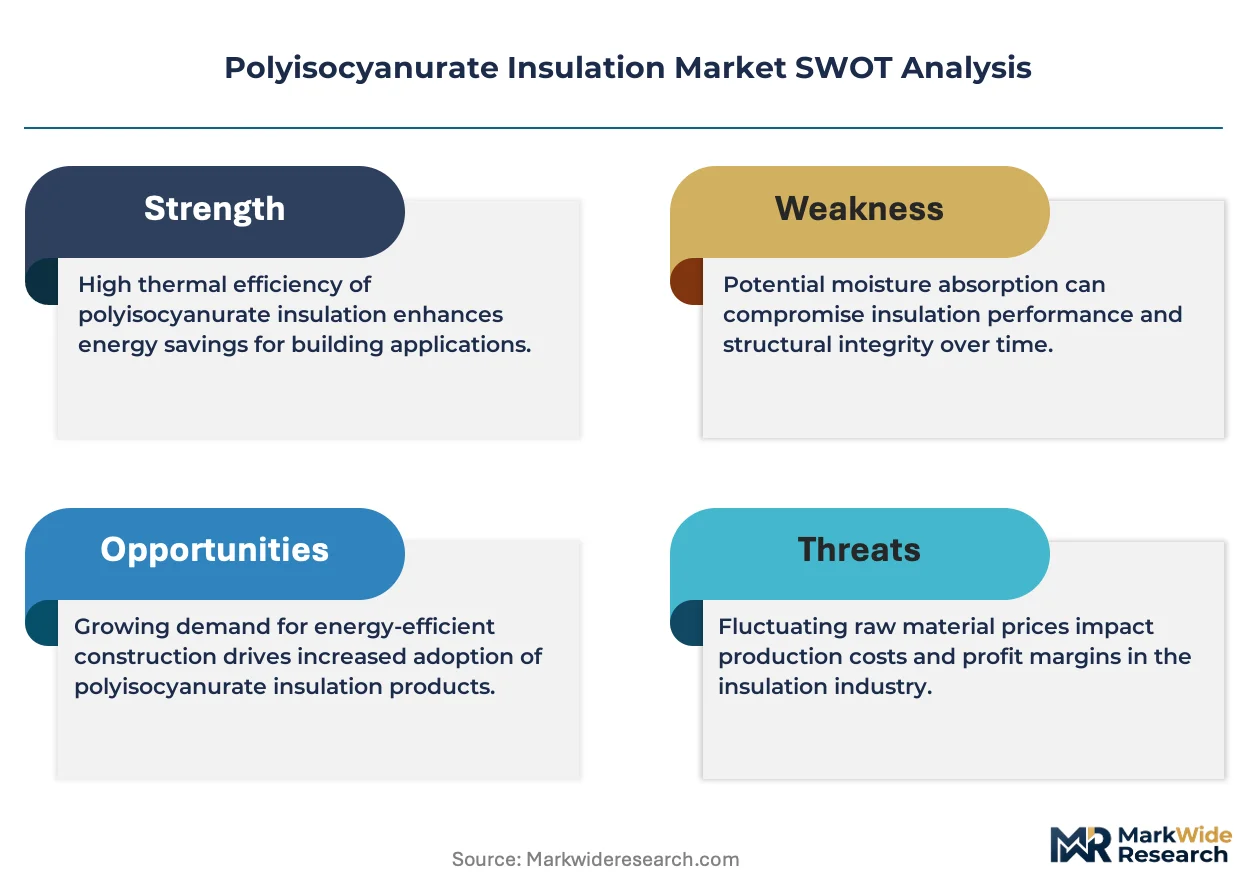
- EPA SNAP Phase-Down:The program's hydrofluorocarbon restrictions are forcing core chemistry reformulations that favor manufacturers with advanced low-GWP blowing agent capabilities.
- Mechanical Attachment Compatibility:Polyiso rigid board's proven integration with adhered and mechanically fastened roofing systems sustains specification dominance in commercial re-roofing cycles.
Market Restraints
- MDI Supply Concentration:Polymeric methylene diphenyl diisocyanate feedstock availability hinges on a concentrated base of chemical producers, exposing formulators to input volatility.
- Certified Applicator Scarcity:The shortage of trained spray foam technicians limits installation capacity for monolithic barrier projects in complex industrial geometries.
- Mineral Wool Substitution:Fire-resistant stone wool insulation is capturing specification share in high-rise envelope assemblies where combustibility restrictions tighten.
Strategic Opportunities
- Massachusetts Stretch Code Alignment:Municipalities adopting above-code energy standards create premium demand pockets for R-30+ roof assemblies in commercial construction.
- HVAC Equipment Integration:Pre-insulated ductwork and chiller enclosures represent an underdeveloped application channel for closed-cell spray foam formulations.
- Digital Specification Platforms:Building information modeling workflows are opening direct-to-designer channels that bypass traditional distributor intermediaries.
Industry Challenges
- Blowing Agent Transition Timelines:Manufacturers face compressed windows to qualify next-generation formulations under evolving EPA enforcement schedules.
- Code Documentation Burden:Expanding qualification requirements for state and local officials strain technical service resources across product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisocyanurate Insulation Market |
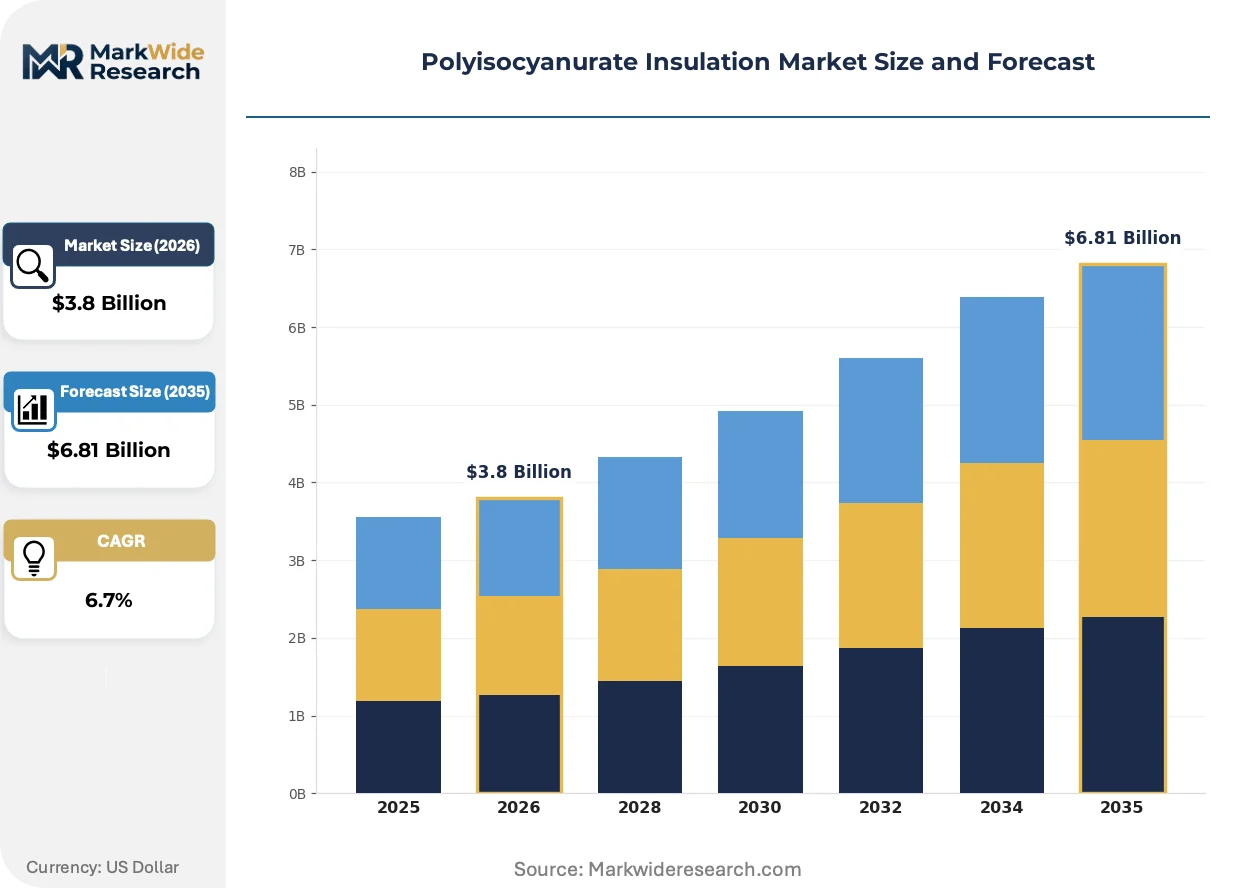
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Board, Spray Foam, Flexible Foam, Laminated Board End Use: Commercial, Residential, Industrial, HVAC Installation Method: Mechanically Attached, Adhesive Applied, Integrated Systems, Inverted Roofs Thickness: Low, Medium, High, Ultra-High |
| Companies Covered | Kingspan Group, Owens Corning, GAF Materials Corporation, BASF SE, Johns Manville, Huntsman Corporation, Carlisle Construction Materials, IKO Industries, Covestro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisocyanurate Insulation Market Strategic Shifts
Reformulation chemistry and installation methodology are converging to reshape competitive boundaries in thermal barrier specification. Three developments are actively restructuring how value flows through the supply chain.
Next-generation hydrofluoroolefin blowing agents are displacing legacy HFC formulations in core production. Large-scale roofing contractors in Texas and California are specifying low-GWP alternatives on new construction portfolios. This chemistry transition is compressing margins for formulators caught between R&D investment cycles and enforcement deadlines.
California's Title 24 Building Energy Efficiency Standards are mandating thermal performance thresholds that exceed federal baselines. The regulation forces manufacturers to maintain dual product lines and documentation systems. Commercial roofing segments in the state's coastal urban corridors are experiencing the most acute specification pressure.
Building owners are consolidating insulation procurement into envelope-performance contracts that bundle material, installation, and long-term thermal monitoring. General contractors in the US Southeast are ceding specification authority to specialized roofing integrators. This bundling pattern is most pronounced in cold storage and pharmaceutical distribution verticals where thermal failure carries operational penalties.
Polyisocyanurate Insulation Market Segmentation
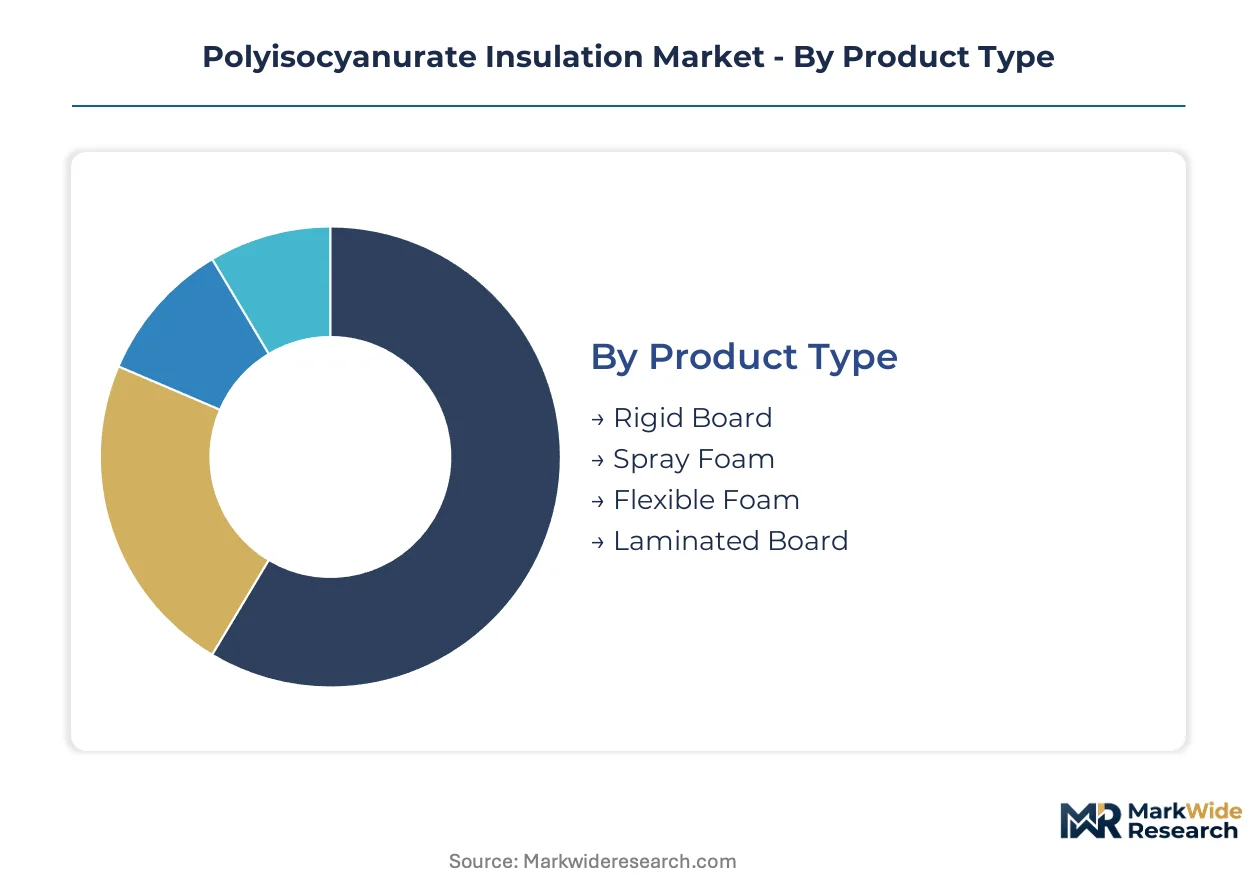
Polyisocyanurate insulation specification hinges on thermal performance mandates, installation constraints, and end-use operating conditions. Regulatory frameworks governing blowing agents and R-value minimums fragment demand across product categories and thickness tiers. Understanding these segmentation boundaries reveals where formulation investments concentrate and which installation channels capture premium pricing.
Product Type:
EPA SNAP phase-down schedules and state-level low-GWP mandates differentiate product viability across commercial roofing and industrial envelope applications.
- Rigid Board:Closed-cell thermoset panels manufactured with facings bonded to polyiso cores deliver R-values exceeding R-6 per inch. Commercial re-roofing cycles across the US Southeast specify mechanically attached rigid board for warehouse-to-cold-storage conversions where thermal bridging penalties are severe. The US Department of Energy's escalating roof assembly mandates cement rigid board's specification dominance.
- Spray Foam:Field-applied monolithic barriers formed by reacting MDI with polyols create seamless thermal envelopes. Industrial HVAC equipment and complex geometries in pharmaceutical distribution centers drive uptake where detailing precision prevents thermal failure. Certified applicator scarcity constrains installation capacity expansion.
- Flexible Foam:Lower-density formulations accommodate curved surfaces and irregular substrates in equipment insulation. Industrial OEMs specify flexible foam for pre-insulated ductwork and chiller enclosures.
- Laminated Board:Composite assemblies combining polyiso cores with metal or gypsum facings target fire-rated envelope assemblies. High-rise commercial construction in Massachusetts stretch code jurisdictions favors laminated configurations.
Rigid board handles the majority of throughput; spray foam is the fastest mover on share.
End Use:
Cost tier stratification separates specification authority between owner-operated facilities and developer-driven construction.
- Commercial:Roofing integrators bundle material procurement with installation and thermal monitoring for distribution centers and retail envelopes. Cold storage verticals command premium R-30+ assemblies with operational failure penalties.
- Industrial:Process equipment, tanks, and piping systems require closed-cell barriers with chemical resistance. Petrochemical facilities on the US Gulf Coast specify high-density formulations.
- Residential:Steep-slope roofing and attic applications compete with mineral wool and fiberglass on installed cost. California Title 24 compliance elevates polyiso specification in new construction.
- HVAC:Pre-insulated ductwork and chiller enclosures represent an emerging specification channel. Mechanical contractors seek factory-applied foam to reduce field labor.
Commercial commands the dominant revenue share; HVAC is expanding most quickly as equipment OEMs internalize insulation procurement.
Installation Method:
Volume concentration tracks roofing contractor capability and substrate condition across re-roofing versus new construction cycles.
- Mechanically Attached:Fastener-based systems dominate commercial re-roofing where existing decks permit penetration. Texas and Florida roofing contractors specify mechanical attachment for wind uplift resistance.
- Adhesive Applied:Full-adhered membranes paired with rigid board target high-performance envelopes in coastal urban corridors. Adhesive chemistry compatibility with facings determines system warranty terms.
- Integrated Systems:Factory-assembled insulation-membrane composites reduce field labor and quality variance. Large-scale new construction portfolios specify integrated systems for schedule compression.
- Inverted Roofs:Ballasted configurations with insulation above the waterproofing membrane suit plaza decks and vegetated roofs. Urban commercial developments specify inverted assemblies for membrane protection.
Mechanically attached retains the largest installed base; integrated systems are climbing the fastest as general contractors consolidate envelope procurement.
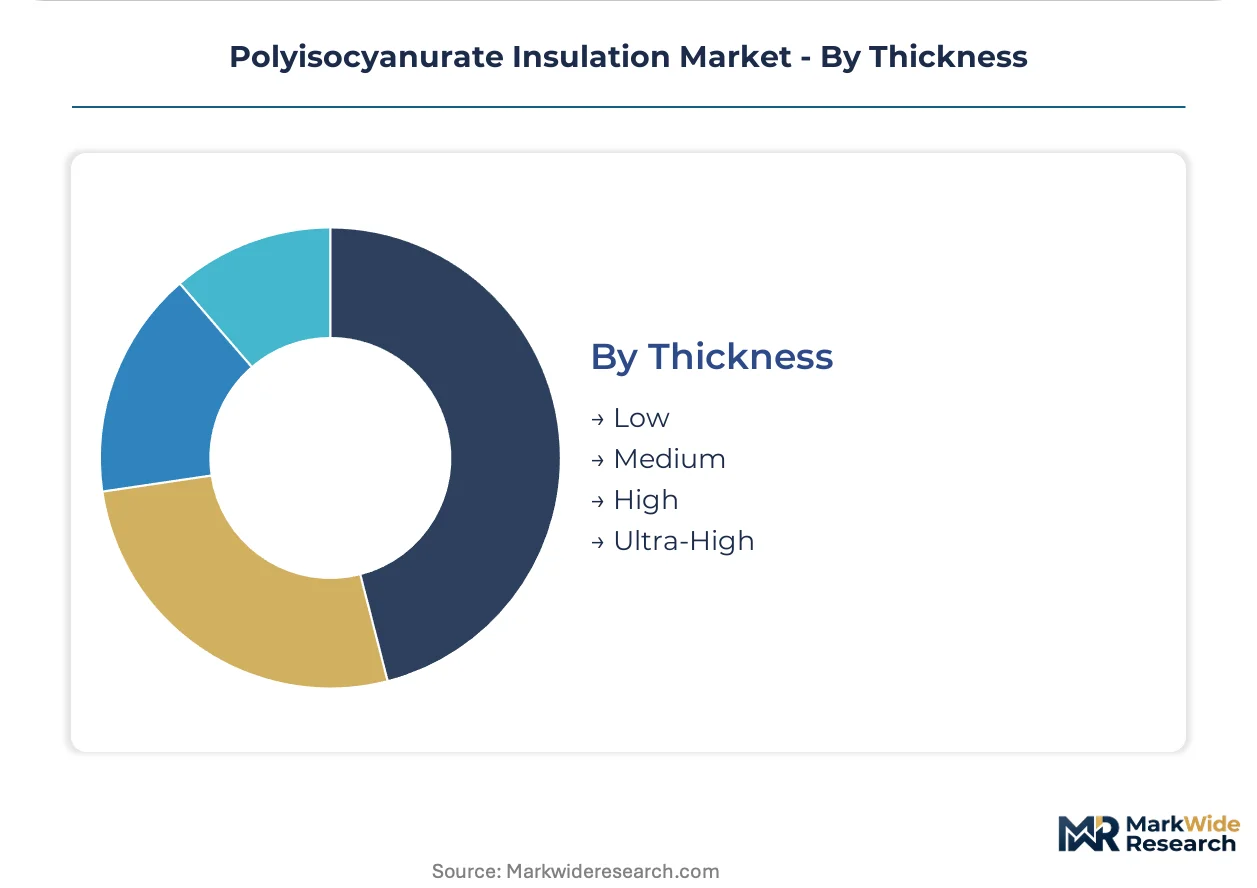
Thickness:
Margin structure stratifies across code minimum compliance, stretch code alignment, and specialized high-R applications.
- Low:Thin profiles target retrofit applications with space constraints and cost-sensitive residential roofing. Stock-keeping unit efficiency favors low-thickness commoditization.
- Medium:Standard commercial roofing assemblies balance R-value achievement with material cost. Medium thickness captures the bulk of re-roofing specification.
- High:Multi-layer assemblies meet Massachusetts stretch code and California Title 24 thresholds. Cold storage envelope design specifies high-thickness roof assemblies.
- Ultra-High:Specialized applications including cryogenic equipment and pharmaceutical distribution centers demand maximum thermal resistance. Ultra-high thickness commands formulation premiums and extended lead times.
Medium thickness dominates current specification volume; high thickness is gaining share fastest as above-code energy standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in Massachusetts cold storage projects exceed those in Florida warehouse conversions by double-digit margins, reflecting divergent code stringency. The United States dominates absolute volume, though regional pricing-power asymmetries concentrate in code-advanced jurisdictions.
United States
Georgia and Florida warehouse-to-refrigerated-facility conversions pull premium rigid board volumes into distribution center retrofits. The EPA SNAP program's hydrofluorocarbon restrictions force core chemistry reformulations that favor manufacturers with advanced low-GWP capabilities. Texas roofing contractors specify mechanically attached systems for wind uplift resistance across commercial re-roofing portfolios.
Canada
Ontario's commercial construction sector specifies high-R-value assemblies for cold climate envelope performance. The country's national building code advances energy efficiency requirements that elevate thermal barrier specifications. Greater Toronto Area distribution centers integrate polyiso rigid board with adhered membrane systems for freeze-thaw durability.
Germany
Industrial envelope retrofits in the Rhine-Ruhr region demand closed-cell spray foam for complex geometries in manufacturing facilities. The EU F-Gas Regulation restricts high-GWP blowing agents, compelling reformulation investments. Bavaria's pharmaceutical distribution clusters specify laminated board assemblies for fire-rated cold storage applications.
China
Yangtze River Delta cold chain logistics construction accelerates specification of high-performance thermal barriers. The Ministry of Ecology and Environment's dual carbon goals pressure manufacturers toward low-emission formulations. Shanghai's pharmaceutical distribution hubs adopt spray foam for monolithic envelope integrity in temperature-controlled facilities.
Japan
Kanto region commercial building retrofits specify rigid board for space-constrained roof assemblies. METI's energy efficiency standards tighten thermal performance thresholds for building envelopes. Tokyo's data center construction integrates pre-insulated ductwork for HVAC thermal management.
Polyisocyanurate Insulation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base concentrates around integrated material suppliers, specialty chemical producers, and installation-focused fabricators. Three archetypes dominate: backward-integrated board manufacturers, MDI chemistry specialists, and contractor-certification platforms. Competitive moves center on captive supply of facing materials and pre-positioning of low-GWP formulation capabilities ahead of enforcement milestones.
Within the integrated-material tier, Kingspan Group and Owens Corning occupy positions that exemplify divergent strategic anchors. Kingspan's backward integration into facings and metal skins pairs with rigid board systems to capture envelope-performance contracting value. Owens Corning leverages its national contractor certification network to sustain installation quality control across commercial roofing projects. Huntsman Corporation represents the chemistry-specialist archetype, anchoring its position through MDI supply consistency that underpins core formulation reliability for downstream formulators.
| Leading Market Players |
|---|
| Kingspan Group |
| Owens Corning |
| GAF Materials Corporation |
| BASF SE |
| Johns Manville |
| Huntsman Corporation |
| Carlisle Construction Materials |
| IKO Industries |
| Covestro |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between rigid board manufacturers and Gulf Coast petrochemical complexes lock in MDI supply access while stabilizing input cost visibility across multi-year roofing project cycles. These contractual structures insulate formulators from spot market volatility in methylene diphenyl diisocyanate feedstock, the dominant cost component in polyiso core production.
Pricing Analysis
Price spreads between Massachusetts stretch code jurisdictions and Florida warehouse conversion markets exceed fifteen percent, reflecting divergent thermal performance mandates. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and blowing agent chemistry, with low-GWP formulations commanding formulation premiums. Cost compression in standard-grade rigid board intensifies as mineral wool substitution accelerates in high-rise fire-rated assemblies. Cold storage developers exhibit lowest price sensitivity due to operational failure penalties, while residential roofing contractors face acute installed-cost pressure from fiberglass competition.
Supply Chain Analysis
Port congestion across Houston and Charleston trade lanes elevates inbound logistics costs for facing materials sourced from Asian metal-coating facilities. MDI supply concentrates in the United States, Germany, and China, with polyiso core production drawing from concentrated petrochemical corridors along the US Gulf Coast. Feedstock dependencies rest on methylene diphenyl diisocyanate, polyether polyols, and aluminum foil facings. Single-source vulnerability in blowing agent chemistry exposes formulators to EPA SNAP enforcement timelines. Distribution runs through roofing distributor networks and direct-to-contractor channels serving commercial re-roofing integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral wool substitution in high-rise envelope assemblies represents an immediate displacement threat that incumbent polyiso manufacturers must navigate through chemistry differentiation and fire-performance certification investments.
For Market Incumbents: Shield specification share in commercial roofing by accelerating low-GWP blowing agent qualification ahead of EPA enforcement milestones. Deepen backward integration into facings production to capture envelope-performance contracting value. Counter mineral wool substitution through laminated board fire-rating investments targeting Massachusetts and California high-rise verticals. For New Entrants and Emerging Players: Anchor in HVAC equipment integration as the most penetrable white-space channel, where pre-insulated ductwork and chiller enclosure demand outpaces incumbent supply capacity. Target pharmaceutical distribution center construction in the US Southeast, where thermal failure penalties sustain premium pricing. Pursue certified applicator network partnerships as the primary go-to-market angle for spray foam market entry. For Investors and Strategic Acquirers: Capital is best deployed toward MDI chemistry specialists with captive low-GWP formulation capabilities and established contractor certification platforms. Long-term viability hinges on pre-positioning for building energy code escalation across the analysis window. Monitor Massachusetts stretch code adoption velocity as the critical inflection signal for premium R-30+ assembly demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Low-GWP Blowing Agent Transition | EPA SNAP compliance secures formulation access ahead of hydrofluorocarbon phase-down deadlines. |
| Backward Integration into Facings | In-house metal skin production captures margin from envelope-performance contracting consolidation. |
| Certified Applicator Network Expansion | Installation quality control differentiates spray foam offerings in complex industrial geometries. |
| HVAC Equipment Partnership | Pre-insulated ductwork integration opens underdeveloped specification channel beyond roofing. |
| Massachusetts Stretch Code Alignment | R-30+ roof assembly qualification captures premium demand pockets in above-code jurisdictions. |
Study Parameters
A spread of perspectives from commercial roofing contractors, cold storage facility engineers, MDI procurement managers, and building code officials converged on the working assumptions underlying this analysis. Primary fieldwork with spray foam applicators and rigid board distributors combined with secondary validation through US Department of Energy code documentation, EPA SNAP regulatory filings, and American Chemistry Council trade data. Bottom-up project pipeline analysis and top-down construction spending triangulation anchored volume estimates across the forecast period.
Segmentation dimensions modeled include product type, end-use vertical, installation method, and thickness tier across the projection horizon. CAGRs derived from regression analysis against construction spending indices and energy code adoption curves. Forecast inputs incorporated cold storage construction permits, warehouse conversion activity, and state-level stretch code proliferation rates without year-specific anchoring.
Decision-makers should treat outputs as directional under stable regulatory enforcement schedules and continued MDI supply availability; material deviation would warrant model refresh. Forecasts reflect assumptions of blowing agent transition timelines and code adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Beryllium Oxide Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Insulation Products Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market