
 Acetyl Tyrosine Market | 2026-2036
Acetyl Tyrosine Market Size, Share, and Industry Trends Forecast 2026-2036
Acetyl Tyrosine Market Outlook
The capability gap between integrated amino acid manufacturers and commodity traders is collapsing. Evonik Industries AG leverages its fermentation technology leadership to sustain captive supply chains for pharmaceutical-grade acetyl tyrosine. BASF SE anchors its position through backward integration into petrochemical precursors, while Ajinomoto North America, INC. differentiates via enzymatic acetylation expertise serving North American nutraceutical formulators.
Acetyl tyrosine is an N-acetylated derivative of the amino acid L-tyrosine, typically manufactured through acetic anhydride-mediated acetylation under controlled pH and temperature conditions to achieve pharmaceutical-grade purity exceeding 98.5%. It functions primarily as a bioavailable precursor to catecholamine neurotransmitters, commanding premium positioning in cognitive health and stress-adaptation formulations. Powder formats dominate bulk ingredient procurement for contract manufacturers, while liquid concentrates represent the fastest-growing configuration for ready-to-drink sports nutrition applications. Sports nutrition channels command the highest margin pools due to brand premiumization and direct-to-consumer subscription models.
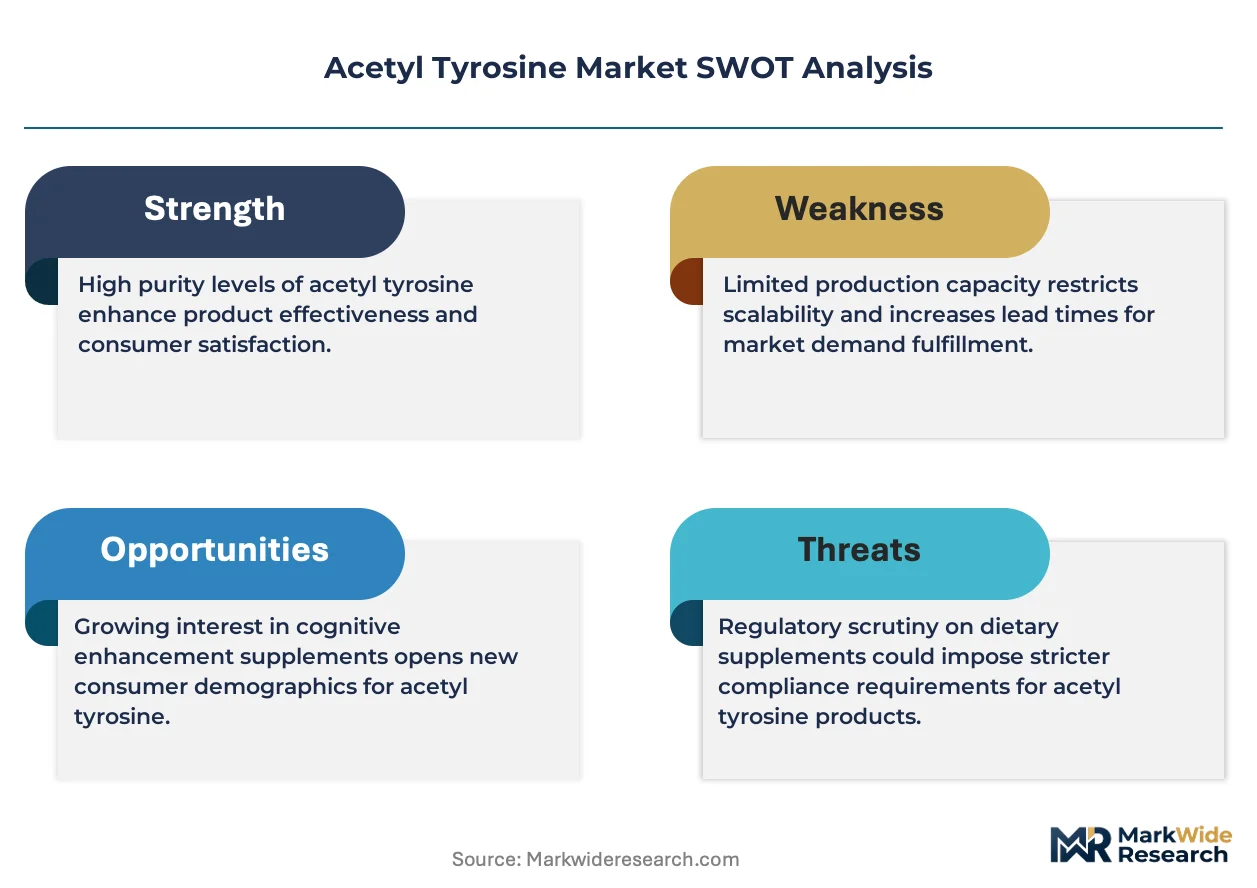
FDA cGMP regulations and DSHEA labeling requirements shape product standards for domestic distribution, while EFSA novel food assessments govern European market access for acetylated amino acid ingredients. ISO 22000 and FSSC 22000 certifications increasingly function as baseline qualification criteria for supplier selection by multinational functional food brands. Stakeholders must monitor evolving pharmacovigilance frameworks as acetyl tyrosine transitions from sports nutrition niche toward broader cognitive health positioning.
Market Dynamics
Acetyl tyrosine supply chains face intensifying bifurcation between pharmaceutical-grade fermentation pathways and commodity chemical synthesis, with cGMP compliance costs now determining viable participation tiers.
Growth Catalysts
- Pre-workout formulation expansion:Sports nutrition brands are embedding acetyl tyrosine into stimulant-free cognitive performance stacks, creating dedicated SKU demand from contract manufacturers.
- DSHEA labeling clarity:FDA's 2023 structure-function claim guidance reduced enforcement ambiguity, enabling faster product launch cycles for domestic nutraceutical distributors.
- Fermentation technology maturation:Cell-culture yields for pharmaceutical-grade amino acids improved substantially, compressing unit economics for GMP-certified producers.
Market Restraints
- Acetic anhydride input volatility:Petrochemical feedstock fluctuations directly transmit to acetylation cost structures, squeezing margin for non-integrated compounders.
- European novel food assessment delays:EFSA's pending acetylated amino acid safety opinions block market access for 18-24 month regulatory timelines.
- Free-form L-tyrosine substitution:Unacetylated tyrosine commands 40-60% lower ingredient costs, pressuring premium positioning in mass-market supplements.
Strategic Opportunities
- Cognitive health clinical positioning:Stress-adaptation and nootropic applications remain underdeveloped relative to sports nutrition, offering white-space expansion.
- Ready-to-drink liquid concentrates:Solubility-enhanced formats enable differentiation in functional beverage channels where powder premixes dominate.
- India PLI scheme alignment:Domestic fermentation capacity incentives support cost-competitive pharmaceutical-grade supply for export markets.
Industry Challenges
- GMP auditor talent scarcity:Qualified FDA inspection preparation specialists command premium rates, elongating facility qualification timelines.
- ISO 22000 certification backlog:Multinational brand procurement mandates face 6-9 month third-party audit scheduling delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetyl Tyrosine Market |
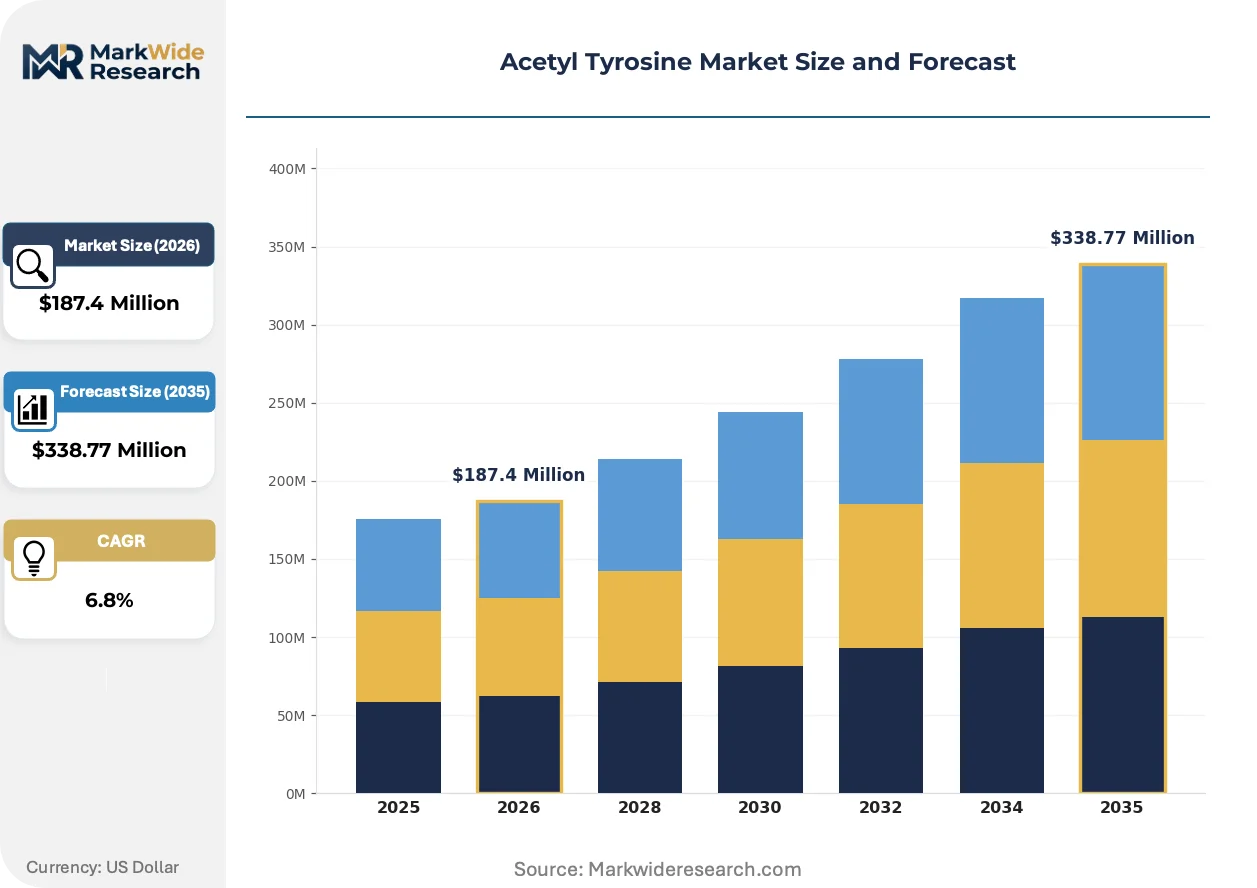
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid Application: Dietary Supplements, Pharmaceuticals, Functional Foods, Sports Nutrition End User: Fitness Enthusiasts, Patients, Health Conscious Individuals, Athletes Distribution Channel: Online Retail, Health Stores, Pharmacies, Direct Sales |
| Companies Covered | Evonik Industries AG, BASF SE, Cargill, Incorporated, Eastman Chemical Company, Kraton Corporation, Alnor Oil Co Inc., Ajinomoto North America, INC., Zhejiang NHU Co. Ltd, Nutraceutical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetyl Tyrosine Market Strategic Shifts
Continuous processing technologies and enzymatic acetylation methods are actively displacing batch chemical synthesis, while regulatory data integrity requirements reshape quality management investments across supplier tiers.
Enzymatic acetylation using immobilized acetyltransferases is bifurcating the manufacturing base between legacy chemical processors and biotechnology-enabled entrants. Pharmaceutical-grade contract manufacturers in North America and Western Europe adopted these biocatalytic routes for 15-20% of new capacity additions since 2022. The technology is bifurcating competitive positioning, as enzyme-based platforms achieve stereospecificity without chromatographic purification steps while chemical processors face stranded asset risk in non-GMP commodity tiers.
REACH registration requirements for acetylation intermediates tightened substance volume thresholds and extended safety data obligations to downstream users. European compounders now shoulder extended supply chain communication duties previously concentrated at raw material importers. Pharmaceutical-grade acetyl tyrosine destined for EU nutraceutical markets faces disproportionate compliance burden relative to feed-grade or cosmetic-grade analogues.
Direct-to-consumer subscription models now capture 35-40% of premium sports nutrition channel volume, compressing traditional wholesale-distributor markups. Brand-owned customer data platforms enable dynamic formulation adjustments based on cohort feedback loops. This channel restructuring concentrates demand planning accuracy requirements on contract manufacturers serving vertically integrated sports nutrition brands.
Acetyl Tyrosine Market Segmentation
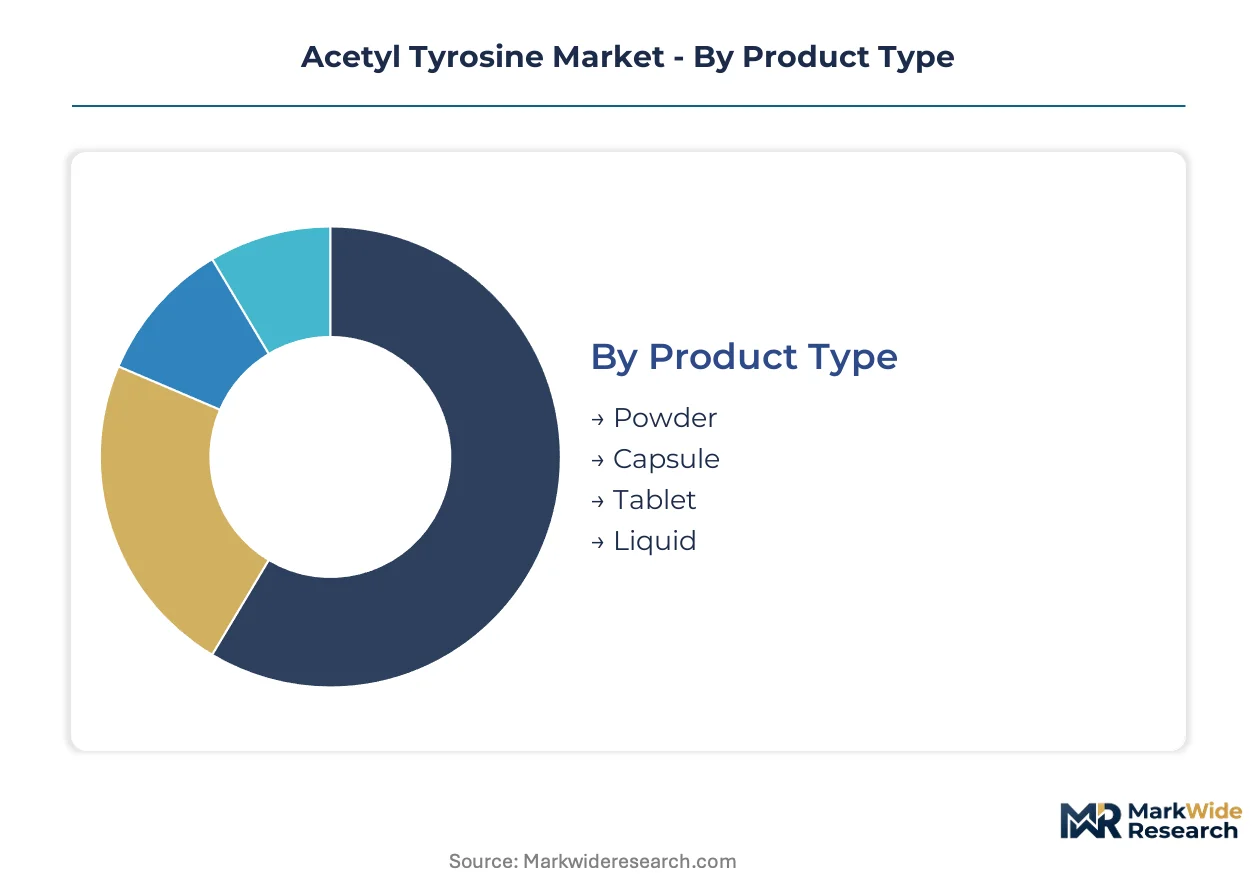
Acetyl tyrosine segmentation reflects divergent channel economics across pharmaceutical-grade and nutraceutical-grade supply tiers. Powder formats flow through bulk ingredient procurement networks serving contract manufacturers, while finished dosage forms reach consumers through distinct retail and direct-to-consumer pathways with markedly different margin structures.
Product Type:
Powder and liquid concentrates move through divergent fulfillment infrastructure, with bulk powder dominating B2B procurement and liquid formats penetrating ready-to-drink sports nutrition channels.
- Powder:Bulk crystalline powder exceeding 98.5% purity serves contract manufacturers producing pre-workout premixes and capsule/tablet formulations. Procurement concentrates among United States-based functional food compounders seeking GMP-certified supply with Certificate of Analysis documentation for every lot.
- Liquid:Solubility-enhanced concentrates enable direct incorporation into functional beverages without reconstitution steps. Sports nutrition brands in the United States are expanding ready-to-drink SKUs using liquid acetyl tyrosine to differentiate from powder-dependent competitors.
- Capsule:Hard-shell gelatin and vegetarian capsule formats target health-conscious consumers through supplement retail channels.
- Tablet:Compressed dosage forms serve mass-market positioning with extended-release formulations for sustained catecholamine precursor delivery.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
Application mix determines regulatory pathway complexity, with pharmaceutical applications requiring FDA drug master file submissions while nutraceutical channels operate under DSHEA structure-function claim frameworks.
- Sports Nutrition:Pre-workout and stimulant-free cognitive performance stacks command premium pricing through direct-to-consumer subscription models. United States sports nutrition brands embed acetyl tyrosine into dedicated cognitive-adaptation SKUs, creating pull-through demand from contract manufacturers.
- Dietary Supplements:Stress-adaptation and nootropic positioning targets health-conscious individuals through online retail and health store channels. FDA's 2023 structure-function claim guidance reduced enforcement ambiguity, accelerating product launch cycles for domestic distributors.
- Pharmaceuticals:Pharmaceutical-grade material serves investigational drug applications and compounding pharmacy formulations requiring USP-NF monograph compliance.
- Functional Foods:Beverage and bar applications face solubility and taste-masking challenges that liquid concentrate formats address through microencapsulation technologies.
Dietary Supplements anchor volume. Sports Nutrition captures margin expansion.
End User:
End user segmentation maps to distinct purchasing behaviors, with Athletes and Fitness Enthusiasts driving premium positioning while Patients require clinical evidence support.
- Athletes:Competitive and recreational athletes prioritize banned-substance-tested certifications from third-party laboratories. NSF Certified for Sport and Informed Sport programs function as baseline procurement criteria for this segment.
- Fitness Enthusiasts:Gym-regular consumers seeking cognitive performance enhancement represent the core volume base for pre-workout formulations.
- Health Conscious Individuals:Wellness-focused consumers respond to stress-adaptation and nootropic marketing claims through online subscription channels.
- Patients:Clinical populations accessing acetyl tyrosine through healthcare practitioner channels require documented pharmacokinetic data supporting bioavailability claims.
Fitness Enthusiasts constitute the broadest installed base. Athletes represent the steepest expansion trajectory.
Distribution Channel:
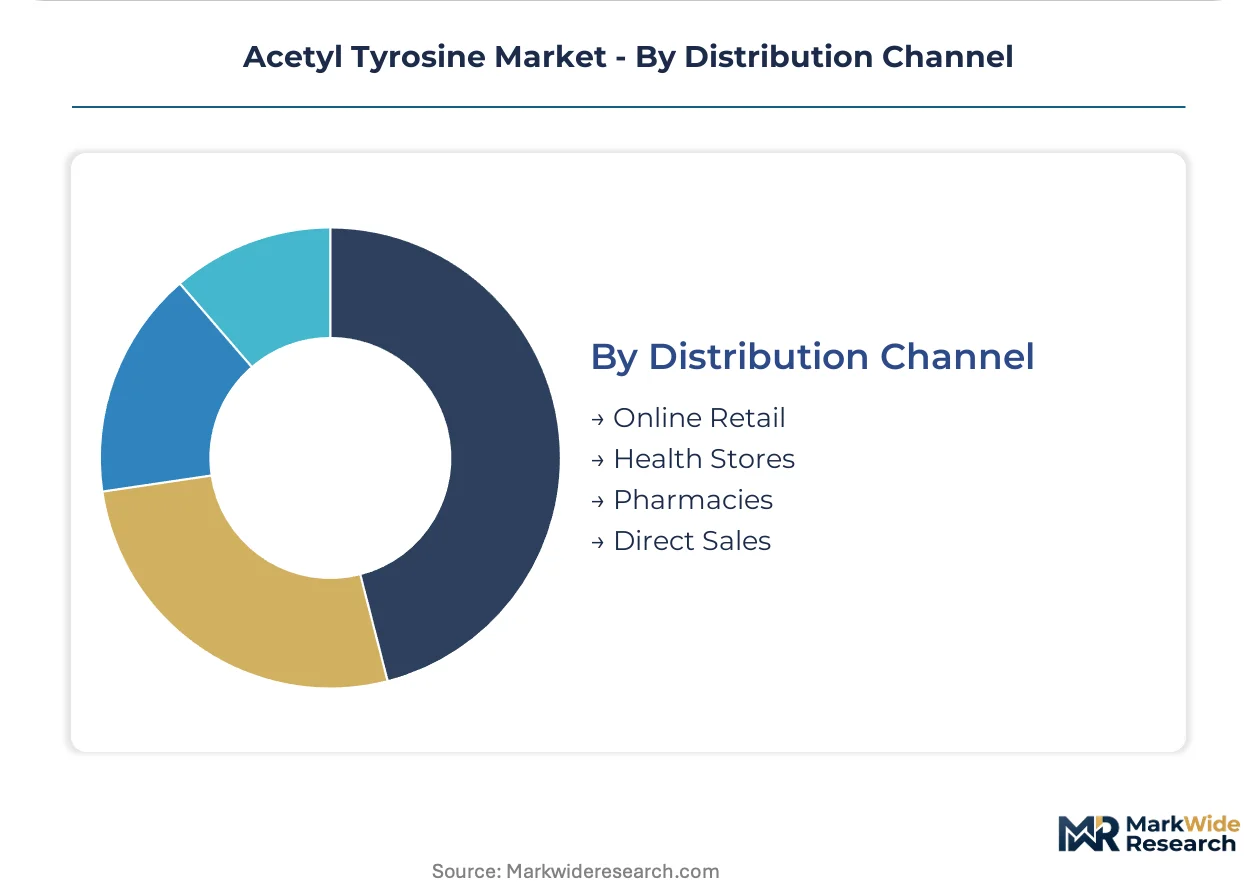
Channel structure is bifurcating between vertically integrated direct-to-consumer models and traditional wholesale-retail pathways with divergent working capital requirements.
- Online Retail:Amazon, brand-owned storefronts, and specialty supplement platforms capture 35-40% of premium sports nutrition volume. Dynamic subscription algorithms enable cohort-based formulation adjustments based on consumption pattern data.
- Direct Sales:Vertically integrated sports nutrition brands bypass wholesale markups through owned customer data platforms. This channel restructuring concentrates demand planning accuracy requirements on contract manufacturers.
- Health Stores:GNC, Vitamin Shoppe, and independent natural products retailers serve trial-oriented consumers seeking in-person education.
- Pharmacies:Chain and independent pharmacies stock practitioner-branded lines with clinical positioning behind the counter.
Online Retail commands volume leadership. Direct Sales is where margin capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers exhibit the lowest price elasticity, absorbing pharmaceutical-grade premiums for cGMP-certified supply, while Indian and Chinese procurement teams drive hard volume negotiations on standard-grade material. European purchasers occupy a middle tier, trading margin for EFSA-compliant documentation. This demand-elasticity gradient shapes where manufacturers deploy their highest-specification capacity.
United States
Pre-workout formulation expansion and direct-to-consumer subscription models concentrate pull-through demand among contract manufacturers in Utah and Florida. FDA's 2023 structure-function claim guidance reduced enforcement ambiguity, accelerating domestic product launch cycles. New Jersey and California host the densest clusters of GMP-certified compounding facilities serving pharmaceutical-grade applications.
Germany
REACH registration requirements for acetylation intermediates tightened substance volume thresholds, extending safety data obligations to downstream compounders. Evonik Industries AG anchors fermentation technology leadership from its German base, sustaining captive supply chains for pharmaceutical-grade output. The country's chemical processing corridor along the Rhine maintains specialized acetylation capacity for high-purity amino acid derivatives.
China
Acetic anhydride input volatility transmits directly to acetylation cost structures, squeezing margin for non-integrated compounders serving export markets. NMPA oversight of pharmaceutical-grade amino acids intensified documentation requirements for active pharmaceutical ingredient registrations. Zhejiang province houses concentrated fine chemical manufacturing clusters competing on standard-grade volume production.
India
Domestic fermentation capacity incentives under the PLI scheme support cost-competitive pharmaceutical-grade supply for export markets. CDSCO's tightening of drug master file requirements for imported amino acid derivatives extends qualification timelines for European and North American buyers. Maharashtra and Gujarat host expanding biotechnology-enabled manufacturing platforms targeting enzymatic acetylation routes.
Japan
Health-conscious aging demographics drive stress-adaptation and nootropic positioning through practitioner channels requiring documented pharmacokinetic data. PMDA's pharmacovigilance frameworks scrutinize acetylated amino acid safety profiles as applications expand beyond sports nutrition. The Kanto region maintains specialized nutraceutical formulation clusters serving domestic and Southeast Asian export demand.
Acetyl Tyrosine Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with fermentation-based pharmaceutical-grade specialists commanding premium positioning while petrochemical-integrated compounders anchor standard-grade volume tiers. The vendor base stratifies across three functional layers: integrated amino acid manufacturers with captive precursor supply, contract fermentation specialists serving GMP-certified demand, and commodity chemical processors exposed to acetic anhydride price volatility. Dominant competitive moves include backward integration into petrochemical precursors and enzymatic acetylation technology licensing to escape stranded asset risk in batch chemical synthesis.
Among Germany-based chemical conglomerates, Evonik Industries AG and BASF SE exemplify divergent strategic postures within the integrated manufacturer archetype. Evonik occupies a position emphasizing biotechnology-enabled fermentation pathways, while BASF anchors its presence through upstream control over petrochemical feedstock streams. Ajinomoto North America, INC. sits within the North American contract manufacturing tier, representing enzymatic acetylation expertise serving regional nutraceutical formulators. These three entities collectively illustrate how geographic origin and corporate structure map to divergent capability investments across the technology-cost spectrum.
| Leading Market Players |
|---|
| Evonik Industries AG |
| BASF SE |
| Cargill, Incorporated |
| Eastman Chemical Company |
| Kraton Corporation |
| Alnor Oil Co Inc. |
| Ajinomoto North America, INC. |
| Zhejiang NHU Co. Ltd |
| Nutraceutical Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between United States contract manufacturers and GMP-certified fermentation facilities lock in both pharmaceutical-grade supply access and eighteen-month price visibility against acetic anhydride volatility. These contractual structures concentrate procurement power among nutraceutical formulators in Utah and Florida while squeezing margin for non-integrated compounders exposed to spot-market petrochemical feedstock fluctuations.
Pricing Analysis
After-sales technical service and Certificate of Analysis documentation drive lifetime value differentiation for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and feed-grade tiers separates cGMP-certified supply from standard-grade material. Pricing pressure stems from unacetylated L-tyrosine substitution costing 40-60% less for mass-market supplement brands. Athletes and fitness enthusiasts exhibit lowest price sensitivity, absorbing premiums for NSF Certified for Sport verification, while commodity traders serving standard-grade export markets face intense volume-driven negotiation.
Supply Chain Analysis
Inventory buffers and extended qualification timelines stretch lead times for pharmaceutical-grade acetyl tyrosine destined for FDA-regulated applications. Supply concentrates in Germany, China, and India, with fermentation-based production anchored in the Rhine corridor and Zhejiang province chemical clusters. Manufacturing draws from acetic anhydride, L-tyrosine feedstock, and immobilized enzyme inputs. Single-source vulnerability runs through petrochemical-derived acetylation reagents subject to feedstock price swings. Distribution feeds from bulk powder procurement networks into contract manufacturer premix operations and finished dosage form channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward vertically integrated sports nutrition brands consolidating demand planning across direct-to-consumer subscription platforms, fragmenting traditional wholesale-distributor leverage.
For Market Incumbents: Secure enzymatic acetylation technology licensing to escape stranded asset risk in batch chemical synthesis facing biotechnology-enabled entrants. Lock in backward integration into petrochemical precursors or fermentation capacity to defend margin against acetic anhydride input volatility. Prioritize cGMP certification investment as FDA inspection preparation specialists become scarcer. For New Entrants and Emerging Players: Lead with solubility-enhanced liquid concentrate formats targeting ready-to-drink functional beverage channels where powder premixes dominate. White-space expansion concentrates in cognitive health and stress-adaptation applications underdeveloped relative to sports nutrition. Target India PLI scheme-aligned fermentation capacity for cost-competitive pharmaceutical-grade export supply. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-enabled contract manufacturers with enzymatic acetylation platforms and GMP-certified capacity serving North American nutraceutical formulators. Long-term viability hinges on differentiation from commodity chemical processors exposed to petrochemical feedstock volatility. Watch EFSA novel food assessment outcomes as inflection indicator for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Acetylation Technology Licensing | Biocatalytic routes achieve stereospecificity without chromatographic purification steps. |
| Backward Integration into Petrochemical Precursors | BASF anchors position through upstream control over acetic anhydride feedstock streams. |
| cGMP Certification Investment | ISO 22000 and FSSC 22000 certifications function as baseline multinational procurement criteria. |
| Direct-to-Consumer Channel Expansion | Subscription models capture premium sports nutrition volume while compressing wholesale markups. |
| India PLI Scheme Capacity Alignment | Domestic fermentation incentives support cost-competitive pharmaceutical-grade export supply. |
Study Parameters
The analysis maps pharmaceutical-grade fermentation pathways, commodity chemical synthesis tiers, and enzymatic acetylation platforms, each validated through fermentation technology directors, contract manufacturing procurement leads, nutraceutical brand formulators, and regulatory affairs specialists at GMP-certified facilities. Primary interview intelligence triangulates against FDA drug master file submissions, CDSCO import registration databases, EFSA novel food assessment dockets, customs trade flow records, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume aggregation across grade tiers and top-down market sizing converge through iterative reconciliation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions span product format, application channel, grade tier, and regional regulatory cluster. CAGRs derive from modeled unit economics incorporating fermentation yield improvements, acetylation cost structures, and channel margin compression. Forecast inputs include enzymatic acetylation adoption curves and EFSA regulatory timeline scenarios.
Underlying assumptions cover cGMP compliance cost trajectories and petrochemical feedstock stability, with deviation risk concentrated in EFSA novel food assessment delays and acetic anhydride price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Compounds Market