
 Styrene Market | 2026-2036
Styrene Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Market Intelligence
Demand from consumer goods fabricators for traditional polystyrene packaging is decoupling from the growth in specialty applications like acrylonitrile butadiene styrene (ABS) for automotive components. LyondellBasell leverages its extensive production scale to serve high-volume commodity segments. In contrast, BASF specializes in higher-margin polymer grades for specialized industrial applications. INEOS competes through its strategic control of key European production assets and integrated logistics networks.
Styrene is an aromatic hydrocarbon, derived primarily from the dehydrogenation of ethylbenzene, that serves as a fundamental liquid monomer. Its primary industrial purpose is as a precursor chemical for polymerization into a wide range of plastics and synthetic rubbers. Polystyrene production remains the dominant application by volume, but synthetic rubber and ABS plastics represent faster-growing segments. Within product types, high-impact polystyrene commands a premium over general-purpose grades due to its enhanced durability for electronics and automotive parts.
Regulations from the US EPA concerning volatile organic compound emissions and Europe's REACH framework on chemical safety govern manufacturing processes. In parallel, China's MEE enforces stringent environmental standards on petrochemical facilities, impacting production costs and plant operations. Navigating these divergent regional environmental policies while investing in circular-economy-compatible polymer grades will be critical for future profitability.
Market Dynamics
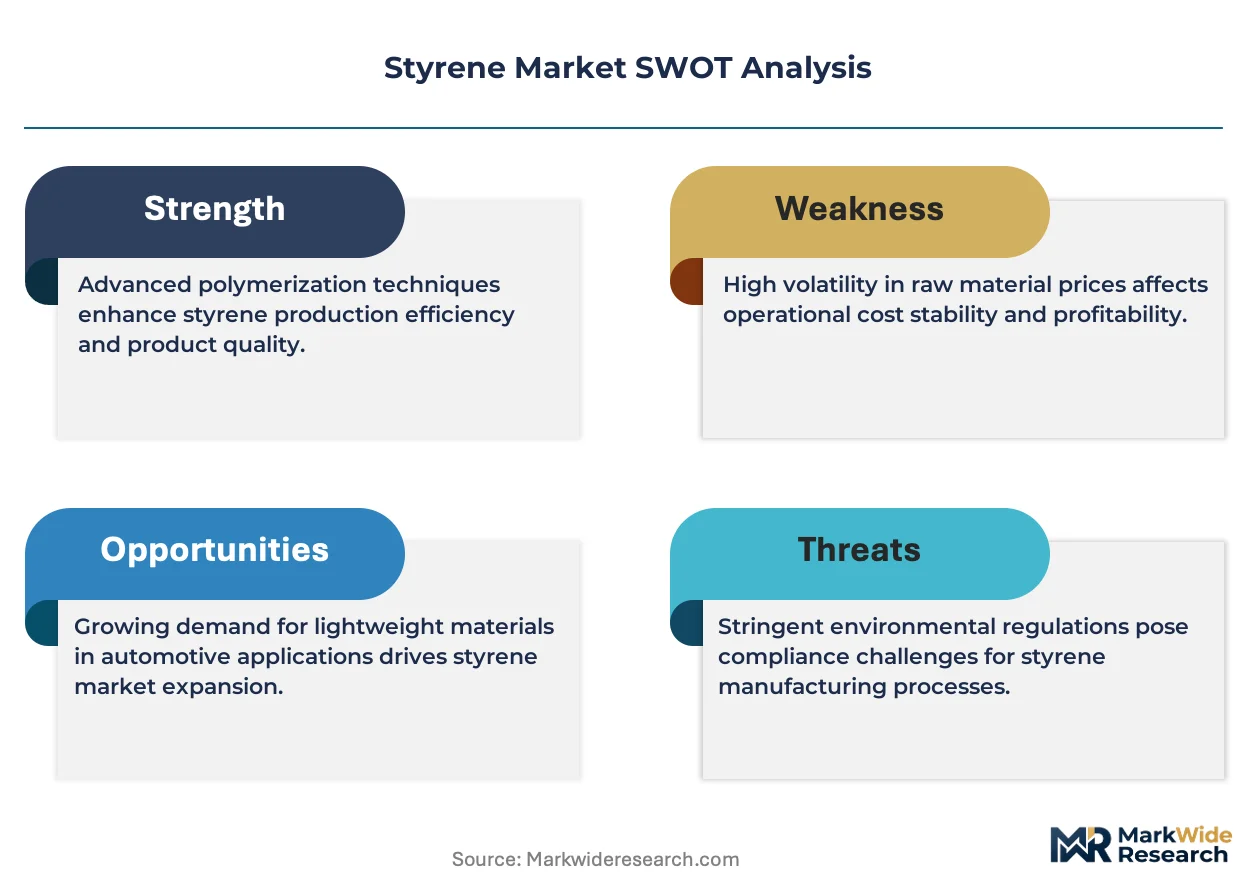
The central tension within the styrene market is the divergence between high-volume, commodity-grade production centered in China and the growing regulatory and commercial pull toward specialized, recyclable polymers driven by circular economy principles like the EU Green Deal.
Growth Catalysts
- Automotive Lightweighting:Demand from automotive manufacturers for lightweight and durable materials to improve fuel efficiency is a significant catalyst, specifically for acrylonitrile butadiene styrene (ABS) and styrene-based composites used in interior and exterior components.
- Circular Economy Policies:Frameworks like the EU Green Deal are compelling producers to innovate, creating a market for advanced, recyclable styrene grades and boosting investment in chemical recycling infrastructure to meet recycled content mandates. *Infrastructure Expansion: Industrialization and urban development in Southeast Asian economies create sustained demand for polystyrene in building insulation, pipes, and electronics housing, along with packaging for a growing consumer class.
Market Restraints
- Feedstock Volatility:The profitability of styrene production is highly sensitive to price fluctuations in its primary feedstocks, crude oil, benzene, and ethylene, creating significant cost pressure and margin uncertainty for producers.
- Material Substitution:In single-use applications like food service and packaging, polystyrene faces intense competition from alternatives like PET, polypropylene, and paper-based materials, driven by negative public perception and bans on expanded polystyrene (EPS).
- Regulatory Compliance Costs:Adherence to stringent environmental standards, including the US EPA's regulations on volatile organic compound (VOC) emissions and Europe's REACH framework, imposes substantial operational and capital costs on manufacturing facilities.
Strategic Opportunities
- Advanced Recycling Technologies:Investing in and scaling chemical recycling processes like pyrolysis allows for the conversion of post-consumer polystyrene waste back into virgin-quality monomer, creating a circular value chain and addressing plastic waste concerns.
- Green Building Materials:There is a growing opportunity for polystyrene-based insulation products in the construction sector, as stricter building codes in regions like North America and Europe mandate higher energy efficiency.
- Medical and Life Sciences Applications:Developing high-purity, medical-grade styrenic polymers opens access to the high-margin diagnostics and labware market, where material consistency and biocompatibility are critical requirements.
Industry Challenges
- Hazardous Material Logistics:The transportation of liquid styrene monomer is complex and capital-intensive, requiring specialized fleets of tankers and strict adherence to international safety protocols for hazardous chemicals, which constrains supply chain flexibility.
- High Capital Investment:Constructing new world-scale styrene plants or retrofitting existing ones to meet the latest environmental standards from regulators like China's MEE requires immense capital expenditure and long project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Market |
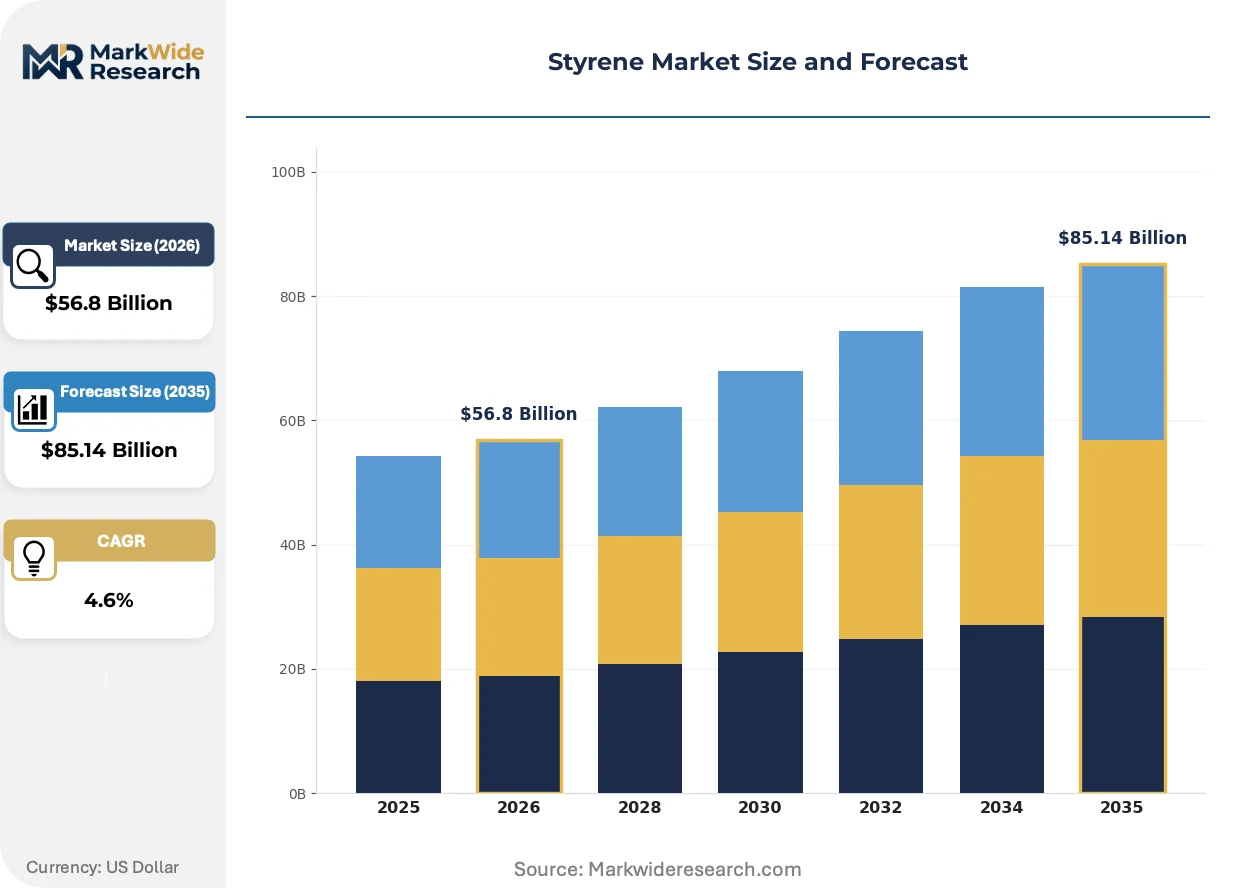
| Market Size in 2026 | $56.8 Billion |
| Market Size in 2035 | $85.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, High Impact, Syrup, Polymer Grade, Hydrocarbon Resins Application: Polystyrene Production, Synthetic Rubber, ABS Plastics, Latex, Resins End User Industry: Packaging Manufacturers, Construction Materials, Electronics Assemblers, Consumer Goods Fabricators, Automotive Component Makers Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesalers, Specialized Dealers |
| Companies Covered | Dow, LG Chem, BASF, SABIC, LyondellBasell, Chevron Phillips Chemical Company, INEOS, Shell, Covestro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Market Strategic Shifts & Innovations
A profound focus on sustainability is reshaping the entire styrene value chain, from feedstock diversification to advanced end-of-life processing. This shift influences product development, investment priorities, and the competitive landscape as producers adapt to circular economy demands.
Chemical recycling, particularly through pyrolysis, converts post-consumer polystyrene waste back into its original monomer form. Major chemical and packaging companies are adopting this technology to meet corporate sustainability goals and regulatory mandates for recycled content. This circular capability is rewriting the material's value proposition, positioning polystyrene as a potentially infinitely recyclable resource rather than a single-use plastic.
Europe's REACH regulation imposes rigorous data and safety assessment requirements on all chemical substances manufactured or imported into the EU. This framework compels styrene producers to invest heavily in toxicological studies and ensure complete supply chain transparency. Companies targeting the European market, especially for sensitive applications like food-contact materials or medical devices, face heightened compliance burdens.
A distinct behavioral shift is evident as consumer goods companies increasingly prioritize packaging materials with certified recycled content. This disrupts traditional procurement models that were based primarily on cost and technical performance, adding sustainability as a key purchasing factor. This trend is most advanced in the food, beverage, and electronics packaging sectors across North America and Europe.
Styrene Market Segmentation
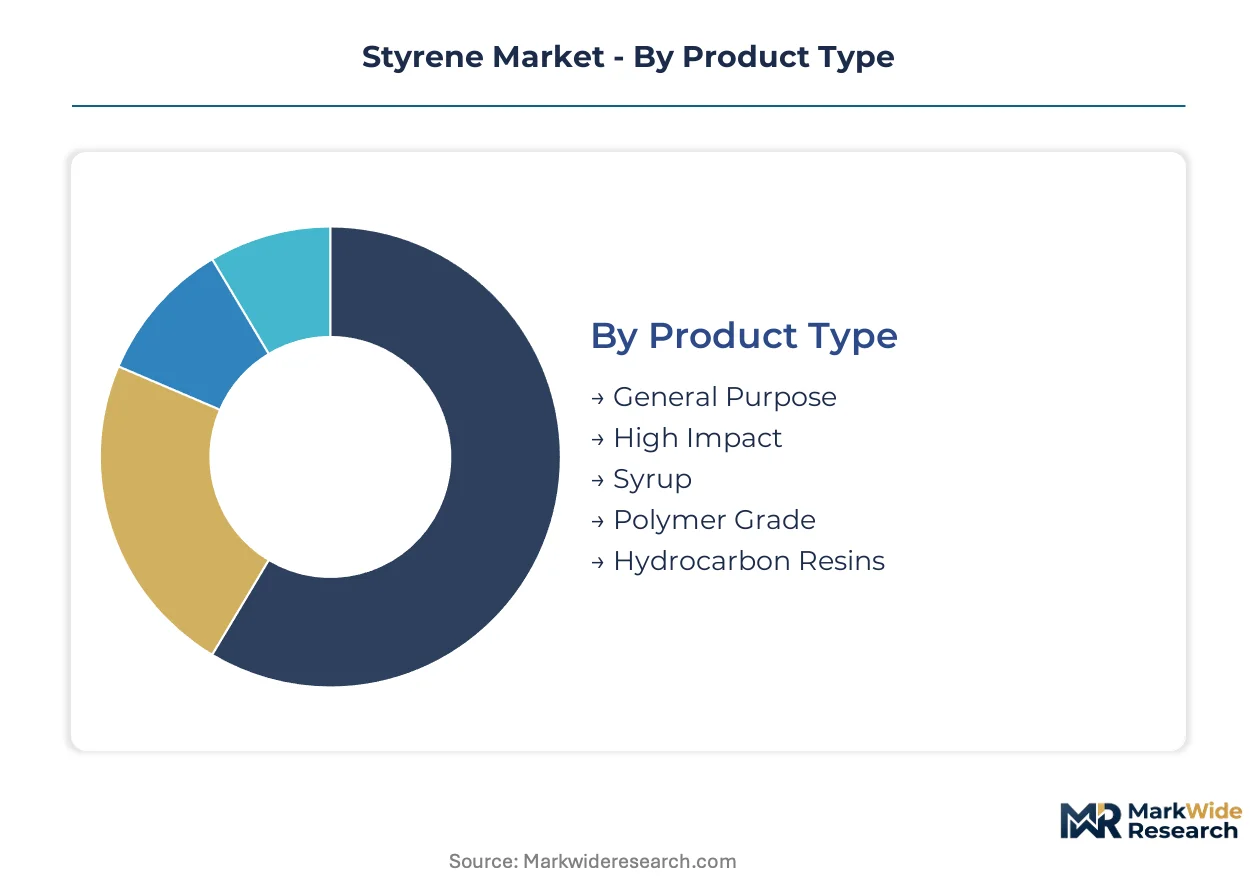
Styrene market segmentation provides a critical framework for understanding the diverse demands and supply dynamics across various product forms, end-use applications, and customer channels. This detailed breakdown helps producers and suppliers align their strategies with specific market needs and regulatory requirements. Analyzing these segments reveals distinct growth drivers and competitive landscapes within the broader styrene industry.
Product Type:
Product type differentiation significantly influences buyer choice, driven by specific performance requirements and cost considerations across various manufacturing processes.
- High Impact:This grade of polystyrene incorporates rubber particles to enhance toughness and durability, making it suitable for applications requiring impact resistance. Demand concentrates in the electronics and automotive sectors, driven by the need for robust yet lightweight components.
- General Purpose:This is the most common and cost-effective form of polystyrene, known for its clarity, rigidity, and ease of processing. Its demand remains high in the packaging industry, particularly for disposable containers and protective inserts.
- Syrup:Styrene syrup is a pre-polymerized form of styrene monomer, often used in polyester resin formulations for composites. It provides a convenient, partially reacted feedstock for specialized resin production.
- Polymer Grade:This refers to high-purity styrene monomer specifically tailored for polymerization into various plastics. It serves as a foundational chemical for a wide array of synthetic polymers.
- Hydrocarbon Resins:These are low molecular weight, thermoplastic resins derived from styrene, used as tackifiers and binders in adhesives, coatings, and rubber formulations. They enhance adhesion and improve processability in industrial applications.
Volume sits with General Purpose; growth tilts toward High Impact.
Application:
The diverse applications of styrene monomer reflect its versatility across various industrial processes and material formulations.
- Polystyrene Production:This application consumes the largest volume of styrene, converting it into solid polystyrene plastics for packaging, insulation, and consumer goods. Polystyrene production remains a foundational segment for styrene demand globally.
- ABS Plastics:Acrylonitrile Butadiene Styrene (ABS) is an engineering thermoplastic known for its strength, rigidity, and impact resistance. Demand for ABS plastics is growing in the automotive and electronics sectors, driven by lightweighting initiatives and enhanced durability requirements.
- Synthetic Rubber:Styrene butadiene rubber (SBR) and other synthetic rubbers utilize styrene as a key monomer for tire manufacturing and various industrial rubber products. This application supports the transportation and industrial sectors.
- Latex:Styrene-butadiene latex is widely used as a binder in paper and carpet coatings, as well as in paints and adhesives. It provides excellent binding properties and film-forming capabilities for diverse industrial uses.
- Resins:Styrene is a critical component in unsaturated polyester resins (UPR), which are used in fiberglass composites for construction, marine, and automotive parts. These resins offer high strength-to-weight ratios.
Polystyrene Production maintains its market dominance, while ABS Plastics exhibits the steepest expansion trajectory.
End User Industry:
End-user industries dictate styrene demand based on their manufacturing scale and specific material properties required for finished goods.
- Automotive Component Makers:These manufacturers use styrene-based polymers like ABS and styrene-butadiene rubber for interior trims, dashboards, and lightweight structural components. Demand is driven by fuel efficiency standards and vehicle weight reduction.
- Packaging Manufacturers:This industry utilizes polystyrene for protective packaging, food containers, and disposable items due to its low cost and good insulation properties. Material substitution pressures influence this segment.
- Construction Materials:Polystyrene foam is a primary material for building insulation, providing thermal efficiency in walls, roofs, and foundations. Stricter building codes, particularly in Europe, drive demand for these materials.
- Electronics Assemblers:Styrenic polymers are essential for casings, internal components, and insulation in consumer electronics and appliances. High-impact polystyrene is particularly valued for its durability.
- Consumer Goods Fabricators:This sector uses styrene derivatives in a wide array of household items, toys, and other consumer products. Material consistency and aesthetic properties are important for these applications.
Packaging Manufacturers constitute a core demand base, with Automotive Component Makers representing an emerging high-value segment.
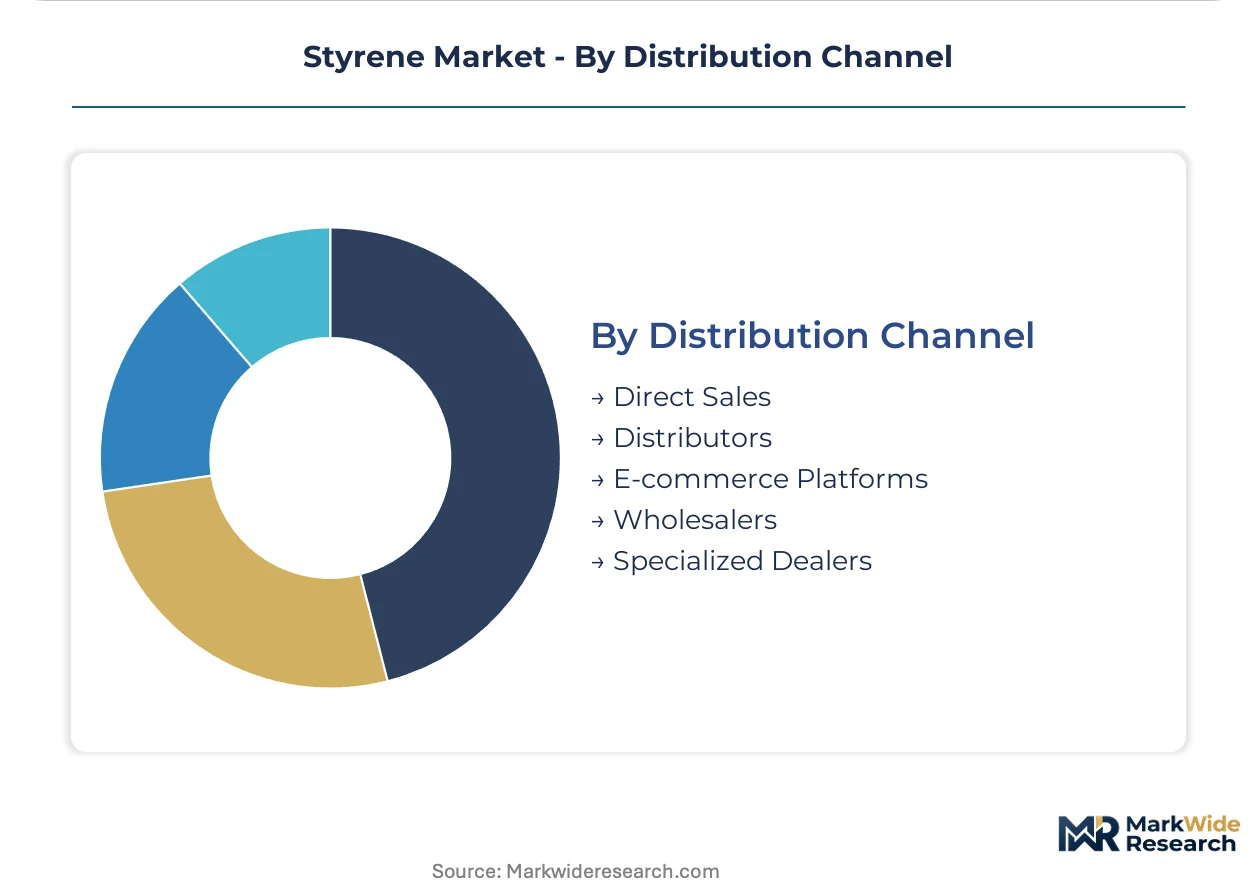
Distribution Channel:
Distribution channels reflect the logistical complexities and scale requirements for delivering styrene monomer and its derivatives to diverse customers.
- Direct Sales:Large-volume buyers, such as major polymer producers and integrated chemical companies, often procure styrene directly from manufacturers. This channel facilitates long-term contracts and strategic partnerships.
- Distributors:Regional and specialized distributors serve smaller to medium-sized enterprises, offering localized inventory, technical support, and tailored delivery solutions. They provide market reach for producers.
- E-commerce Platforms:Emerging e-commerce channels facilitate procurement for niche applications or smaller orders, offering convenience and broader access to specialized styrene grades. This channel is gaining traction for specific product types.
- Wholesalers:Wholesalers manage bulk quantities of styrene and its derivatives, supplying to a network of smaller distributors or directly to industrial users. They play a role in inventory management and supply chain efficiency.
- Specialized Dealers:These dealers focus on specific industries or advanced material grades, providing expert knowledge and customized solutions to clients with unique technical requirements. They cater to high-value applications.
Direct Sales offer efficiency for high-volume transactions, while Distributors provide broad market reach and localized service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones, particularly those in coastal China, drive significant styrene production and consumption, concentrating petrochemical infrastructure. These zones benefit from integrated logistics and policy support for manufacturing exports. Such focused industrial development underpins the region's dominance in the global styrene market.
China
China's industrial expansion and consumer goods fabrication sustain immense styrene demand for packaging and construction materials. The Ministry of Ecology and Environment (MEE) enforces stringent environmental standards on petrochemical facilities, influencing production costs. Major integrated petrochemical complexes, such as those in Jiangsu province, are expanding capacity to meet domestic and export needs.
United States
Automotive component makers in the United States demand styrene derivatives for lightweighting initiatives in vehicle production. The US Environmental Protection Agency (EPA) regulates volatile organic compound emissions from styrene manufacturing plants, driving investment in advanced control technologies. The Gulf Coast region, particularly around Houston, Texas, remains a primary hub for styrene production and downstream processing.
Germany
Germany's advanced manufacturing sector utilizes high-purity styrene grades for specialized industrial applications and durable goods. The European Union's REACH framework imposes rigorous chemical safety assessments on styrene producers and importers. Chemical parks in regions like North Rhine-Westphalia serve as critical centers for polymer research and high-value styrene derivative production.
India
Infrastructure development and a growing consumer class in India fuel demand for polystyrene in building insulation and electronics housing. The Bureau of Indian Standards (BIS) sets quality benchmarks for plastics, influencing material specifications for local manufacturers. Petrochemical clusters along the western coast, including Dahej, are expanding to support the country's increasing polymer consumption.
Netherlands
Netherlands facilities leverage strategic port access and integrated logistics networks to serve the broader European styrene market. The EU Green Deal compels local producers to innovate in recyclable polymer grades and invest in chemical recycling infrastructure. Major production sites, such as those near Rotterdam, are critical for regional supply and distribution of styrene monomer.
Styrene Market Key Industry Players
Top-tier vendors anchor the global styrene market, while a diverse array of regional specialists and commodity producers also compete. The competitive landscape stratifies across integrated petrochemical giants and more focused polymer manufacturers. Key strategic archetypes include large-scale commodity producers, specialty polymer innovators, and regionally dominant players with strong logistical control. Companies primarily focus on capacity expansion, backward integration into feedstocks, and strategic partnerships to secure market share.
On the premium-tier vector, BASF exemplifies a focus on higher-margin polymer grades, serving specialized industrial applications with advanced material solutions. LyondellBasell occupies a position as a large-scale commodity producer, leveraging its extensive global production assets for high-volume segments like traditional polystyrene packaging and general-purpose applications. INEOS, through its strategic control of key European production assets and integrated logistics networks, represents a regionally dominant player, optimizing supply chain efficiency and market access across the continent for various styrene derivatives. These players collectively anchor different facets of the styrene value chain, from specialty to bulk production.
| Leading Market Players |
|---|
| Dow |
| LG Chem |
| BASF |
| SABIC |
| LyondellBasell |
| Chevron Phillips Chemical Company |
| INEOS |
| Shell |
| Covestro |
| Others |
Cost & Logistics Intelligence
Integrated petrochemical giants manage vast production capacities, influencing both market supply and pricing discipline for styrene and its derivatives. This structure often leads to long-term contract pricing.
Pricing Analysis
Premiums for short lead times drive pricing in the styrene market, reflecting immediate demand spikes or supply disruptions. The dominant pricing model involves a hybrid of contract-based long-term offtake agreements for commodity grades and spot market transactions for immediate needs. Price differentiation stems from quality grade, with high-impact polystyrene commanding a premium over general-purpose grades, and from volume scale for large industrial buyers. Pricing softness reflects intense competition from material substitution in packaging applications, particularly from alternatives like PET. Automotive component makers exhibit lower price sensitivity due to stringent performance requirements, unlike packaging manufacturers who seek cost-effective solutions.
Supply Chain Analysis
Logistics and freight costs significantly influence styrene pricing, particularly for hazardous liquid monomer transportation across regions. Geographic supply concentration centers heavily in China, with additional key production hubs along the US Gulf Coast and in the Netherlands. The supply chain draws from primary raw material dependencies on crude oil, benzene, and ethylene. Hazardous material logistics represents a structural risk, requiring specialized fleets and strict safety protocols. Downstream distribution primarily runs through direct sales for large-volume customers and specialized distributors serving smaller to medium-sized enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market currently operates under supply constraints, with high capital investment and long project timelines for new plants creating a capacity bottleneck that props pricing across key segments.
For Market Incumbents: Anticipate continued regulatory pressure for sustainable grades by investing heavily in chemical recycling technologies. Secure long-term feedstock contracts to mitigate volatility from crude oil and benzene price fluctuations. Combat material substitution threats by developing advanced, recyclable styrene grades for packaging. Strengthen regional supply chains to reduce hazardous material logistics risks and enhance market responsiveness.
For New Entrants and Emerging Players: Advanced recycling infrastructure represents a technology-first wedge for specialized players to enter the styrene value chain. Target high-purity, medical-grade styrenic polymers for niche applications in diagnostics and labware, which offer higher margins. Partner with waste management companies to establish reliable feedstock streams for chemical recycling operations. Focus on specialized industrial applications requiring consistent material properties and technical support.
For Investors and Strategic Acquirers: Successful commercial scaling of pyrolysis plants is the leading indicator that validates the long-term viability of circular economy models for styrene. Investors should seek acquisition targets with proprietary chemical recycling technologies or established expertise in high-performance styrene derivatives. The market offers sustained demand for both commodity and specialty grades over the next decade. Monitor regional regulatory shifts, particularly in Europe and China, for investment signals in green polymer capacities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Meets growing demand from industrialization and urban development in Southeast Asian economies. |
| Green Manufacturing Transition | Addresses stringent environmental regulations from China's MEE and Europe's REACH framework. |
| Long-term Supply Agreement | Mitigates feedstock volatility risks from crude oil, benzene, and ethylene price fluctuations. |
| Joint Venture for Chemical Recycling | Accelerates the development and commercialization of circular economy-compatible polymer grades. |
| Product Portfolio Diversification | Expands market reach into high-margin segments like medical devices and advanced composites. |
Research Approach
Document review covered industry reports, trade data from ACC/Cefic, and governmental environmental agency reports from the US EPA and China's MEE, complemented by interviews. Primary research engaged plant managers, procurement leads at automotive OEMs, R&D directors for polymer grades, and distribution channel partners. This approach ensures bottom-up and top-down triangulation of market insights.
The model produced volume and value projections across the analysis window, segmented by product type, application, end-user industry, and regional consumption patterns. CAGRs were derived through regression analysis of historical trends and projected growth rates based on future demand drivers. Industry-specific forecast inputs included feedstock price trends and regulatory mandates for recycled content in consumer goods.
Several conditions sit outside the modeled scope, including geopolitical instability affecting oil supply and rapid technological breakthroughs in alternative materials. Forecasts reflect assumptions regarding economic growth and regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Sodium Tetraborate Market