
 United States Calcium Chloride Market | 2026-2036
United States Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
United States Calcium Chloride Market Intelligence
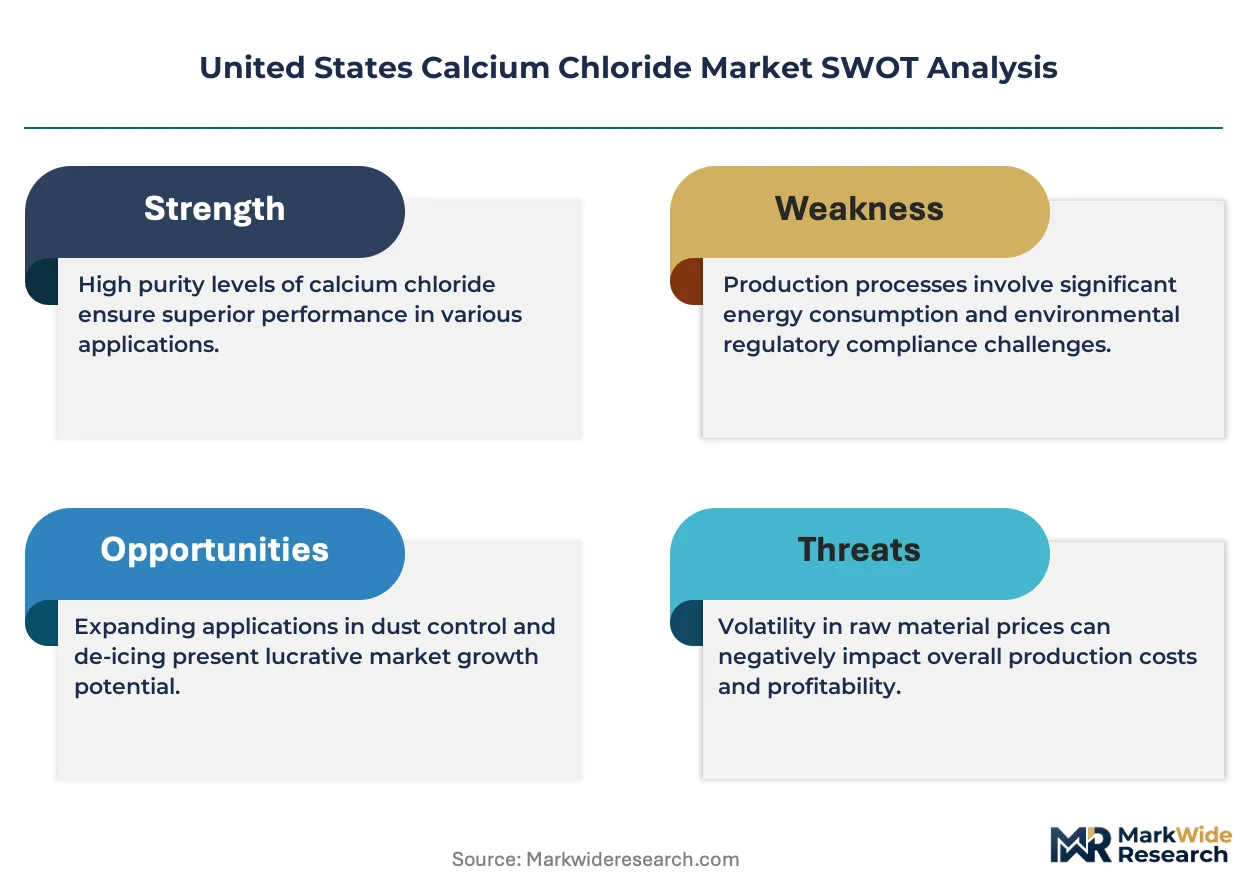
The Great Lakes industrial corridor is fragmenting as new calcium chloride capacity enters the US market from domestic brine extraction expansions and upgraded solar evaporation facilities. Occidental Chemical Corporation leverages its integrated brine-to-product pipeline across Michigan and Ohio to sustain cost leadership in bulk flake supply. TETRA Technologies, Inc. competes through specialized liquid calcium chloride formulations for oilfield and de-icing end uses. Baker Hughes Company anchors its position in industrial refrigeration and dust control applications with captive distribution networks.
Calcium chloride is an inorganic salt with the chemical formula CaCl₂, typically produced at 77-94% assay for industrial grades through the Solvay process or natural brine extraction and evaporation; its hygroscopic nature and exothermic dissolution make it effective for moisture control, freeze-point depression, and soil compaction. Liquid calcium chloride dominates volume flows into de-icing and dust control contracts where municipalities and mining operators prioritize pump-and-spray logistics over solid handling. Flake and pellet grades capture premium positioning in packaged consumer and commercial ice-melt channels where storage stability and controlled dissolution rates command higher unit margins. Granular calcium chloride occupies a narrower niche in oilfield drilling and completion fluids where particle size distribution affects brine density management.
EPA oversight of road treatment runoff and OSHA workplace exposure limits for calcium chloride dust shape product purity specifications and packaging requirements across US manufacturing and distribution. State-level departments of transportation in Minnesota, Wisconsin, and New York enforce seasonal procurement standards that favor certified low-corrosion formulations for bridge deck and highway applications. Stakeholders must monitor evolving EPA stormwater discharge rules and state budget cycles for winter maintenance appropriations to anticipate volume shifts between liquid and solid product formats.
Market Dynamics
State DOT procurement consolidation across the Great Lakes and Northeast corridors is compressing supplier margins while favoring liquid calcium chloride formats that integrate with automated brine-making systems for highway de-icing operations.
Growth Catalysts
- EPA Stormwater Discharge Rules:Stricter runoff controls for road treatment chemicals are mandating certified low-corrosion formulations, expanding replacement demand for legacy chloride blends in bridge deck applications.
- Oilfield Brine Density Management:Unconventional drilling in the Permian and Bakken formations sustains granular calcium chloride consumption for completion fluids where precise particle sizing controls wellbore stability.
- Michigan-Ohio Brine Extraction Expansions:Upgraded solar evaporation capacity is lowering feedstock costs for domestic flake production, tightening cost positioning against imported material.
Market Restraints
- Natural Gas Price Volatility:Thermal energy inputs for brine evaporation and drying operations expose producers to Henry Hub price swings that compress margins during winter demand spikes.
- Single-Source Brine Dependency:Concentrated subsurface reserves in specific Michigan and Ohio counties create geographic supply risk if extraction permits face environmental challenge.
- Magnesium Chloride Substitution:Lower-cost MgCl₂ formulations from Great Salt Lake operations are displacing calcium chloride in non-critical dust control contracts where corrosion tolerance permits.
Strategic Opportunities
- Texas and New Mexico Dust Control:Underpenetrated mining and unpaved road maintenance markets in the Southwest offer volume expansion as drought conditions intensify surface stabilization requirements.
- Industrial Refrigeration Phase-Down:Ammonia system retrofits in food processing and cold storage facilities are creating calcium chloride brine demand as a secondary coolant replacement.
- OSHA Respirable Dust Limits:Tighter workplace exposure standards for bulk handling operations are accelerating demand for pre-wetted flake and pellet formats that reduce airborne particulate generation.
Industry Challenges
- Brine Chemistry Expertise Shortage:Specialized knowledge of subsurface reservoir management and evaporation optimization is concentrating among retiring engineers at legacy extraction operations.
- DOT Certification Timelines:State-level approval processes for new low-corrosion formulations extend 18-24 months, delaying product rollout across fragmented procurement jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Calcium Chloride Market |
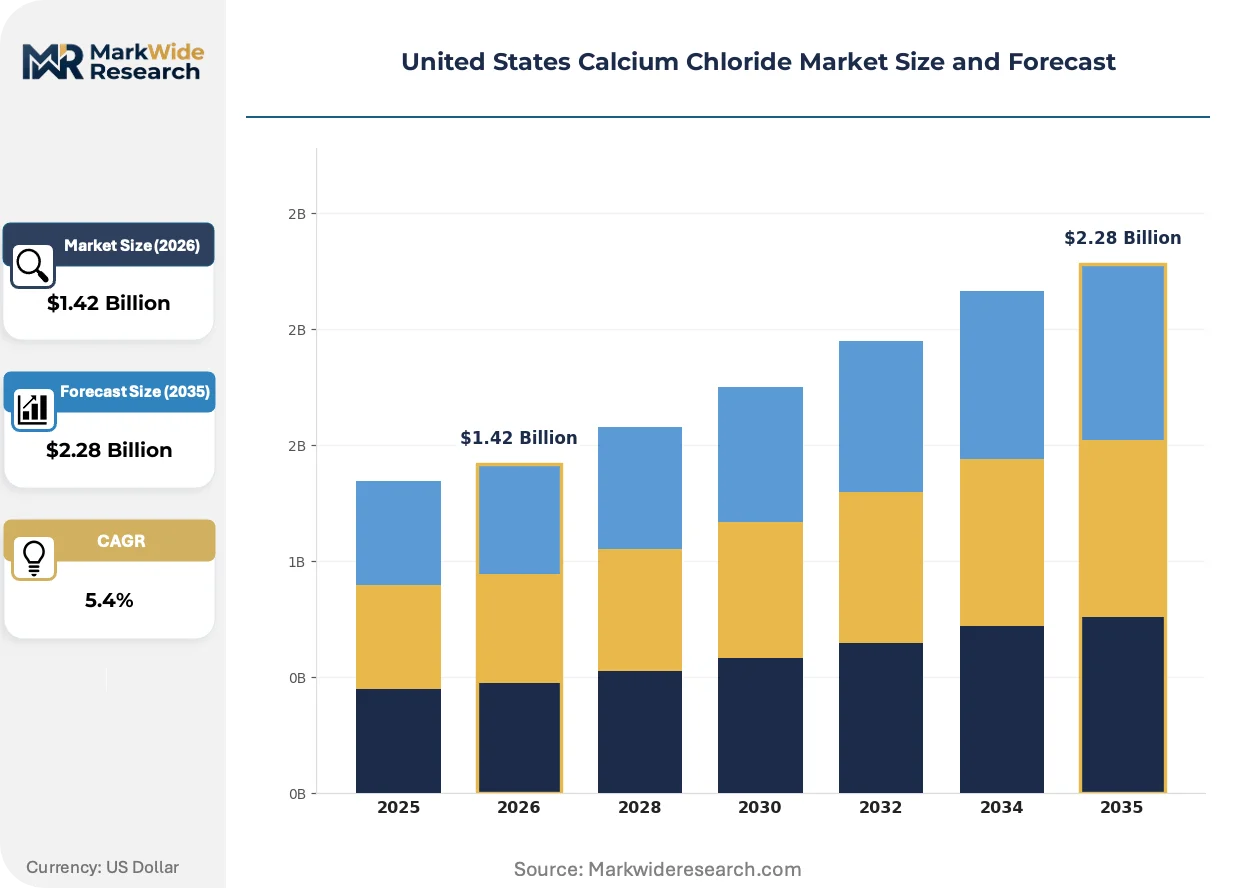
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Liquid, Pellets, Granular End Use Industry: Construction, De-icing, Agriculture, Water Treatment Application: Dust Control, Road Stabilization, Refrigeration, Soil Stabilization Packaging Type: Bulk Bags, Drums, Bags, Totes |
| Companies Covered | Occidental Chemical Corporation, Solvay, TETRA Technologies, Inc., Tiger Calcium Services Inc., Ward Chemical Ltd., Baker Hughes Company, Hill Brothers Chemical Co., Cargill, OxyChem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Calcium Chloride Market Strategic Shifts & Innovations
Continuous liquid calcium chloride delivery systems are displacing bulk solid handling across municipal and industrial accounts, compressing logistics costs while demanding new infrastructure investment from suppliers.
Pre-wetted de-icing technologies that blend calcium chloride brine with rock salt at the spinner are rendering obsolete dry salt-only spreading equipment in Minnesota, Wisconsin, and New York DOT fleets. County maintenance departments are retrofitting existing spreaders with tank-and-pump systems at accelerating pace. Equipment manufacturers are consolidating supply chains around integrated brine-making and application platforms.
EPA effluent limitation guidelines for road treatment runoff are forcing reformulation of calcium chloride products to reduce heavy metal and suspended solid content in stormwater discharge. Chemical producers are investing in additional purification stages and third-party certification. Liquid product lines face tighter analytical documentation requirements than bulk flake alternatives.
Municipal procurement offices are consolidating de-icing chemical purchases into multi-year framework agreements that bundle liquid calcium chloride with application services and weather-linked delivery guarantees. Traditional spot-market buying for packaged ice-melt products persists in retail channels. The shift is most advanced in Michigan, Ohio, and Pennsylvania where county cooperative purchasing agreements dominate.
United States Calcium Chloride Market Segmentation
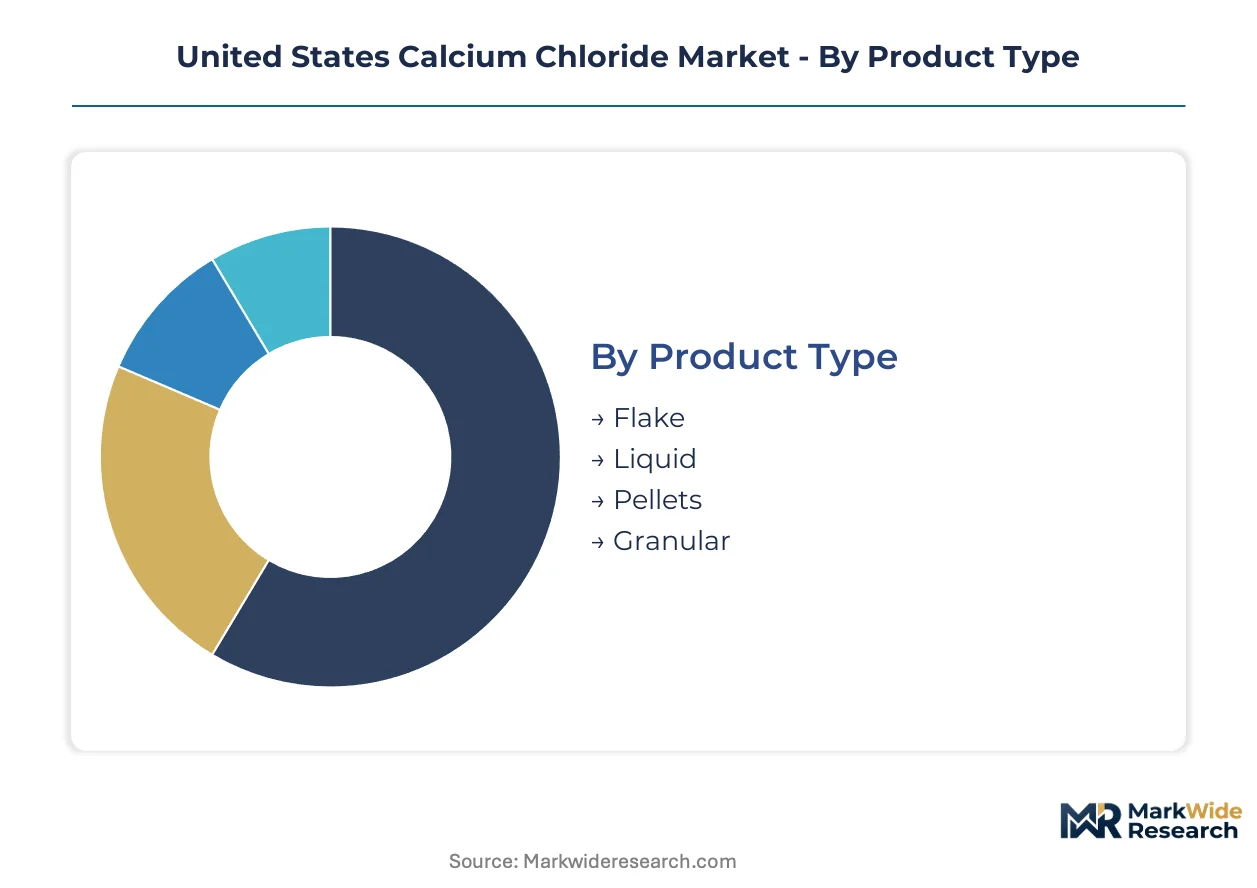
Calcium chloride demand fragments across product formats, end-use sectors, and logistical configurations that each impose distinct purity specifications and distribution economics. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume throughput dominates.
Product Type:
Mature solid formats coexist with emerging liquid delivery systems that reshape procurement patterns across municipal and industrial accounts.
- Liquid:Brine solutions at 28-42% concentration integrate with automated spray systems for highway de-icing and dust suppression. Minnesota, Wisconsin, and New York DOT fleets are retrofitting spreaders with tank-and-pump infrastructure, compressing solid handling costs while demanding new supplier investment in continuous delivery logistics.
- Flake:Dihydrate crystals at 77-80% assay serve packaged ice-melt retail channels and industrial moisture control where storage stability commands premium positioning. Michigan and Ohio brine extraction expansions are tightening domestic feedstock costs against imported material.
- Pellets:Spherical particles at 94% assay minimize dust generation during bulk handling, aligning with OSHA respirable dust limits in warehouse and transportation settings. Pre-wetted formats are gaining preference over dry pellets in sensitive workplace environments.
- Granular:Sized particles for oilfield completion fluids where precise distribution controls brine density in Permian and Bakken drilling operations. Particle specification tolerances are tighter than industrial grades, narrowing qualified supplier pools.
Liquid handles the majority of throughput; pellet formats are expanding most quickly as workplace safety standards tighten.
End Use Industry:
Volume concentrates in winter maintenance applications while emerging industrial cooling systems create new demand nodes.
- De-icing:State DOT procurement across the Great Lakes and Northeast corridors sustains seasonal bulk demand. EPA stormwater discharge rules are mandating certified low-corrosion formulations for bridge deck applications, extending certification timelines and favoring established suppliers with analytical documentation capabilities.
- Construction:Soil compaction and concrete acceleration in roadbuilding and foundation work where calcium chloride accelerates set times and reduces curing periods. Residential and commercial construction cycles in the Midwest and Northeast drive regional demand concentration.
- Water Treatment:Municipal and industrial softening applications where calcium chloride adjusts hardness and alkalinity. Smaller volume segment with stable replacement demand tied to plant upgrade cycles.
- Agriculture:Nutrient supplementation and soil amendment in specialty crop production. Niche positioning relative to dominant nitrogen and potassium fertilizers limits scale.
De-icing commands the dominant revenue share; industrial refrigeration retrofits are climbing the fastest as ammonia phase-downs accelerate.
Application:
Surface stabilization applications dominate volume while specialized thermal management creates differentiated margin pools.
- Dust Control:Unpaved road maintenance and mining haul road stabilization across drought-affected Southwestern counties. Magnesium chloride from Great Salt Lake operations competes on cost where corrosion tolerance permits.
- Road Stabilization:Base course treatment and full-depth reclamation in highway rehabilitation projects. County cooperative purchasing agreements in Michigan, Ohio, and Pennsylvania bundle chemical supply with application services.
- Refrigeration:Secondary coolant brines in food processing and cold storage facilities replacing ammonia systems. FDA food contact compliance requirements shape product purity specifications.
- Soil Stabilization:Subgrade modification for expansive clay mitigation in residential and commercial development. Regional concentration in Texas and Oklahoma where clay soils predominate.
Dust control generates the highest volume throughput; refrigeration applications are gaining share fastest amid cold storage capacity expansion.
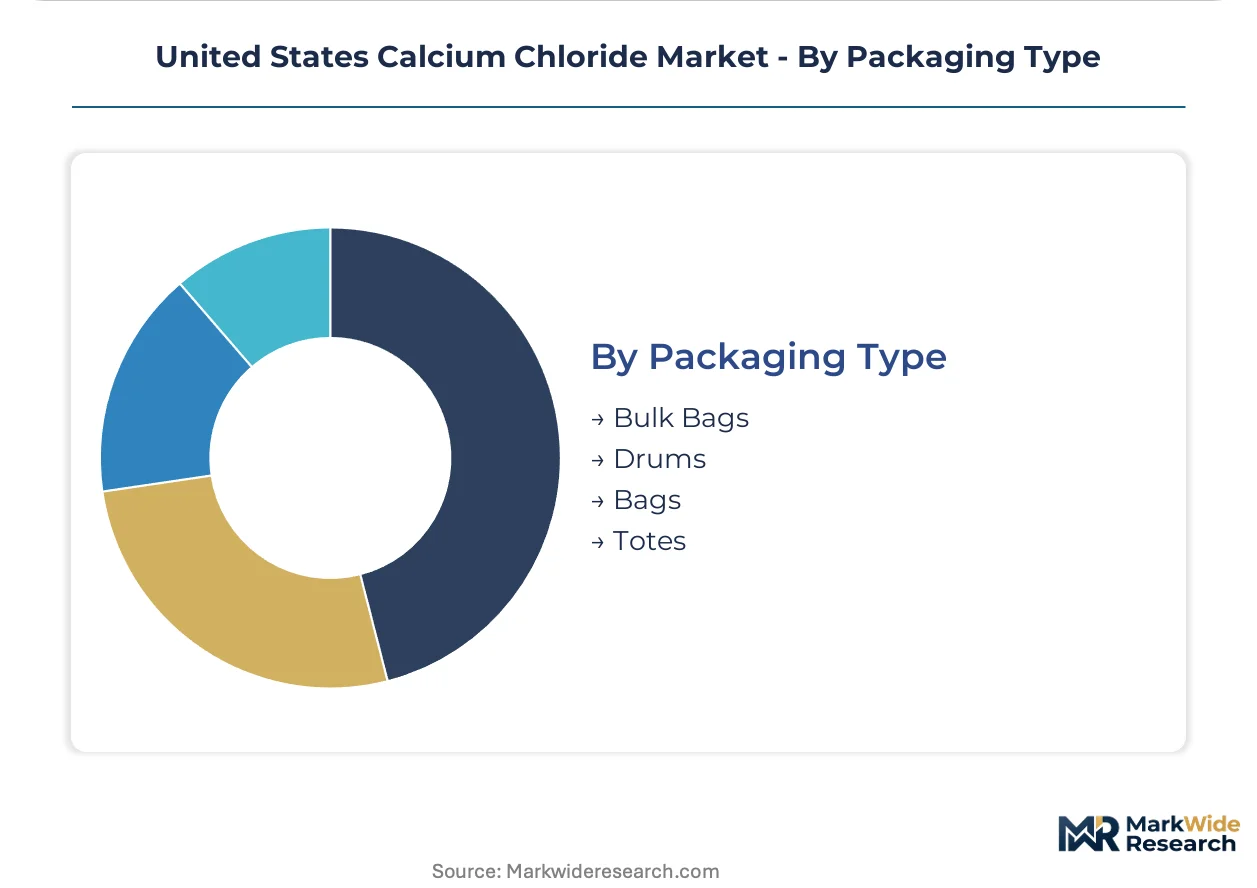
Packaging Type:
Cost tier differentiation separates bulk industrial procurement from packaged retail and specialty channels.
- Bulk Bags:One-ton flexible intermediate bulk containers for industrial accounts with material handling infrastructure. Lowest unit cost format with highest minimum order quantities.
- Totes:Intermediate bulk containers for liquid calcium chloride in 250-330 gallon capacities. Bridge format between drum convenience and bulk economy for mid-scale industrial users.
- Drums:55-gallon steel or polyethylene containers for oilfield and specialized industrial applications requiring contamination control. Premium positioning reflects handling and disposal logistics.
- Bags:50-pound multiwall paper or woven polypropylene for retail ice-melt and consumer moisture control. Highest per-pound packaging cost with established distribution through hardware and mass retail channels.
Bulk bags move the greatest tonnage; tote formats are expanding most quickly as mid-scale liquid adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater discharge rules and state DOT procurement standards anchor calcium chloride demand across the Great Lakes and Northeast corridors where winter severity sustains bulk chemical adoption.
Great Lakes Corridor
Michigan and Ohio host expanding brine extraction operations that feed upgraded solar evaporation facilities lowering domestic feedstock costs. State DOT certification requirements in these states mandate low-corrosion formulations for bridge deck applications, extending supplier qualification timelines. The Detroit-Toledo industrial zone concentrates flake production capacity as Occidental Chemical Corporation leverages integrated brine-to-product pipelines.
Northeast Corridor
New York, Pennsylvania, and New England states drive seasonal procurement through consolidated county cooperative purchasing agreements bundling liquid calcium chloride with application services. Pre-wetted de-icing technologies are displacing dry salt-only spreading equipment across Minnesota, Wisconsin, and New York DOT fleets. Buffalo and Rochester maintenance depots are retrofitting spreaders with tank-and-pump systems at accelerating pace.
Southwest Region
Texas and New Mexico present underpenetrated expansion opportunities for dust control applications as drought conditions intensify surface stabilization requirements across mining and unpaved road maintenance markets. Magnesium chloride from Great Salt Lake operations competes aggressively on cost where corrosion tolerance permits substitution. Midland and Odessa oilfield clusters sustain granular calcium chloride consumption for completion fluids in Permian drilling operations.
Mountain West
Colorado and Utah mining operators prioritize pump-and-spray logistics for dust suppression on haul roads, creating volume demand for liquid calcium chloride formats. OSHA workplace exposure limits for bulk handling operations are accelerating adoption of pre-wetted flake and pellet formats that reduce airborne particulate generation. Denver-based distributors are expanding tote-format liquid delivery to mid-scale industrial accounts.
Southeast Region
Florida and Georgia food processing facilities are retrofitting ammonia refrigeration systems with calcium chloride brine secondary coolants as FDA food contact compliance requirements shape product purity specifications. Industrial cold storage capacity expansion in Atlanta and Jacksonville is climbing fastest amid ammonia phase-downs. Regional humidity control applications in warehousing sustain packaged flake demand through hardware retail channels.
United States Calcium Chloride Market Key Industry Players
Capability concentration sits with integrated brine extraction specialists; scale advantage sits with diversified chemical conglomerates. The market structure reflects a two-tier configuration where upstream feedstock control separates cost leaders from formulation-dependent competitors. Strategic archetypes include brine-integrated producers, oilfield service specialists, and diversified industrial chemical suppliers. Dominant competitive moves center on backward integration into subsurface reserves and continuous liquid delivery infrastructure deployment.
Within the integrated producer tier, Occidental Chemical Corporation and OxyChem exemplify upstream control over Michigan and Ohio brine extraction operations. TETRA Technologies, Inc. occupies a position among oilfield service specialists leveraging liquid formulation expertise for completion fluid applications. Baker Hughes Company anchors the diversified industrial segment through captive distribution networks serving refrigeration and dust control end uses.
| Leading Market Players |
|---|
| Occidental Chemical Corporation |
| Solvay |
| TETRA Technologies, Inc. |
| Tiger Calcium Services Inc. |
| Ward Chemical Ltd. |
| Baker Hughes Company |
| Hill Brothers Chemical Co. |
| Cargill |
| OxyChem |
| Others |
Cost & Logistics Intelligence
The Detroit-Toledo industrial zone concentrates domestic flake production capacity, and its expanding solar evaporation infrastructure is compressing feedstock costs for Michigan and Ohio producers. This upstream cost advantage translates into pricing power against imported material across bulk procurement contracts.
Pricing Analysis
Geographic price spreads between Great Lakes production hubs and Southwestern dust control markets reflect transportation cost differentials of 15-20% for liquid brine deliveries. Contract-based long-term offtake dominates municipal DOT procurement, with price differentiation driven by EPA low-corrosion certification tier and volume scale commitments. Pricing pressure stems from magnesium chloride substitution in non-critical applications where corrosion tolerance permits. County cooperative purchasers exhibit highest price sensitivity; oilfield completion fluid buyers prioritize particle specification compliance over unit cost.
Supply Chain Analysis
Underground brine reservoirs in Michigan and Ohio counties feed the upstream extraction layer, drawing from concentrated subsurface geology that creates single-source vulnerability if environmental permits face challenge. Natural gas inputs for thermal evaporation, polyethylene packaging resins, and specialized corrosion inhibitors constitute critical component dependencies. Henry Hub price volatility exposes margin compression risk during winter demand spikes. Distribution runs through integrated producer networks for bulk liquid, regional distributors for packaged flake, and oilfield service specialists for granular completion grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around EPA-mandated formulation upgrades that disqualify legacy suppliers from bridge deck certification, creating niche openings for analytical documentation specialists.
For Market Incumbents: Harden EPA certification portfolios by accelerating third-party analytical documentation capabilities for low-corrosion formulations. Secure backward integration into additional brine extraction permits beyond current Michigan-Ohio concentration to mitigate single-source geographic risk. Defend against magnesium chloride substitution by bundling application services with chemical supply in multi-year framework agreements. For New Entrants and Emerging Players: Pursue underpenetrated Southwestern dust control markets in Texas and New Mexico where drought intensification outpaces established distribution coverage. Target mid-scale industrial refrigeration retrofits in food processing facilities requiring FDA food contact compliance as the most penetrable segment. Lead with tote-format liquid delivery systems that bridge bulk economy and drum convenience for accounts lacking material handling infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EPA certification timelines and analytical documentation requirements are concentrating share among integrated producers with existing DOT relationships. Acquisition targets should emphasize brine-integrated specialists with captive Michigan or Ohio reserves and established low-corrosion formulation certifications. Monitor state budget appropriations for winter maintenance as the critical inflection signal for volume shifts between liquid and solid product formats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Reserves | Captive feedstock supply from Michigan and Ohio subsurface formations insulates margin from import competition. |
| EPA Low-Corrosion Certification Investment | Third-party analytical documentation unlocks bridge deck procurement in Minnesota, Wisconsin, and New York DOT fleets. |
| Continuous Liquid Delivery Infrastructure | Tank-and-pump systems align with automated brine-making retrofits across county maintenance departments. |
| Pre-Wetted Formulation Development | OSHA-compliant dust reduction formats capture premium positioning in workplace safety-sensitive environments. |
| Multi-Year Framework Agreement Structuring | Weather-linked delivery guarantees bundle chemical supply with application services in consolidated county purchasing. |
Research Approach
Operator-level perspectives from plant managers at brine extraction facilities, procurement leads at state DOTs, distribution channel partners, and technical R&D directors anchored the qualitative base. These primary inputs combined with secondary validation from EPA stormwater discharge filings, state DOT procurement databases, ACC industry reports, and SEC 10-K disclosures. Bottom-up volume modeling across product formats triangulated against top-down value estimates derived from trade flow analysis.
Scenario-bracketing around natural gas price volatility and EPA regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product format tier, end-use industry concentration, packaging configuration, and regional production hub economics. CAGRs were derived from regression-based trending of historical procurement volumes against winter severity indices and state budget appropriation cycles. Oilfield drilling activity in the Permian and Bakken formations, plus cold storage capacity expansion rates, served as industry-specific demand drivers.
Sensitivities concentrate around Henry Hub price spikes, environmental challenge to extraction permits, and magnesium chloride substitution elasticity in dust control applications. Cross-checking against EIA natural gas forward curves and state DOT published appropriation schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Global Ammonium Chloride Market