
 Calcium Chloride Market | 2026-2036
Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Chloride Market Intelligence
The EU Green Deal's carbon-border adjustment mechanism is realigning calcium chloride sourcing patterns across European chemical supply chains. Solvay S.A. leverages its integrated soda ash production to secure captive calcium chloride feedstock with lower logistics intensity. TETRA Technologies, Inc. anchors its position through deep well brine extraction operations across the Gulf Coast basin. Weifang Haibin Chemical Co., Ltd. dominates bulk flake exports from Shandong Province with dedicated port loading infrastructure.
Calcium chloride is a hygroscopic inorganic salt with the chemical formula CaCl₂, typically produced at 77-94% assay through Solvay process co-generation or natural brine evaporation, functioning primarily as a desiccant, freeze-point depressant, and concrete curing accelerator. Liquid formulations lead volume throughput in oilfield completion fluids where density and compatibility specifications command premium positioning, while pellet grades capture margin pools in food preservation applications requiring USP or FCC certification against flake alternatives serving commodity de-icing tenders. The construction end user channel shows structural expansion tied to accelerated concrete curing in cold-weather pours, contrasting with mature dust control demand in mining haul roads where pricing follows diesel-linked contract indices.
EPA stormwater discharge permits under the NPDES framework constrain bulk salt storage practices, indirectly elevating treated product specifications that incorporate calcium chloride for leaching reduction. OSHA workplace exposure limits for calcium chloride dust shape packaging and handling protocols in US manufacturing and distribution facilities. Stakeholders must monitor how state-level procurement consolidation among department of transportation buyers reshapes contract structures and qualification requirements for suppliers seeking multi-year supply agreements.
Market Dynamics
State DOT procurement consolidation across the United States is compressing supplier qualification timelines and reshaping contract structures toward multi-year volume commitments with performance penalties for delivery shortfalls.
Growth Catalysts
- EPA NPDES stormwater permits:Municipalities face stricter bulk salt storage rules, pushing adoption of calcium chloride-treated blends that reduce chloride leaching into watersheds.
- Oilfield completion fluid density specifications:Deepwater drilling operations in the Gulf of Mexico require liquid calcium chloride formulations that maintain wellbore stability under high-pressure conditions.
- Accelerated concrete curing:Cold-weather construction protocols in northern climates mandate calcium chloride additives to achieve specified compressive strength within shortened pour windows.
Market Restraints
- Limestone feedstock cost volatility:Solvay process economics tie directly to soda ash co-generation margins, exposing calcium chloride producers to energy price swings in natural gas-intensive operations.
- Shandong Province supply concentration:Bulk flake exports depend heavily on dedicated port infrastructure at Qingdao and Weifang, creating single-point vulnerability for international shipment capacity.
- Magnesium chloride substitution:Dust control applications in mining haul roads face price competition from magnesium chloride brines sourced from Great Salt Lake evaporation operations.
Strategic Opportunities
- EU Green Deal carbon-border adjustments:European chemical buyers seek lower-logistics-intensity sourcing from integrated soda ash producers with captive calcium chloride streams.
- Food-grade pellet certification:USP and FCC compliance requirements create margin expansion potential in food preservation applications beyond commodity de-icing tenders.
- Direct-to-municipality digital procurement platforms:State DOTs pilot e-procurement systems that bypass traditional distributor networks for bulk de-icing chemical purchases.
Industry Challenges
- OSHA permissible exposure limit compliance:Calcium chloride dust mitigation requires capital investment in enclosed conveying systems and automated packaging lines at distribution facilities.
- Multi-species brine separation expertise:Deep well extraction operations demand specialized geochemical knowledge to manage calcium-magnesium-sodium ratios in Gulf Coast basin feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Chloride Market |
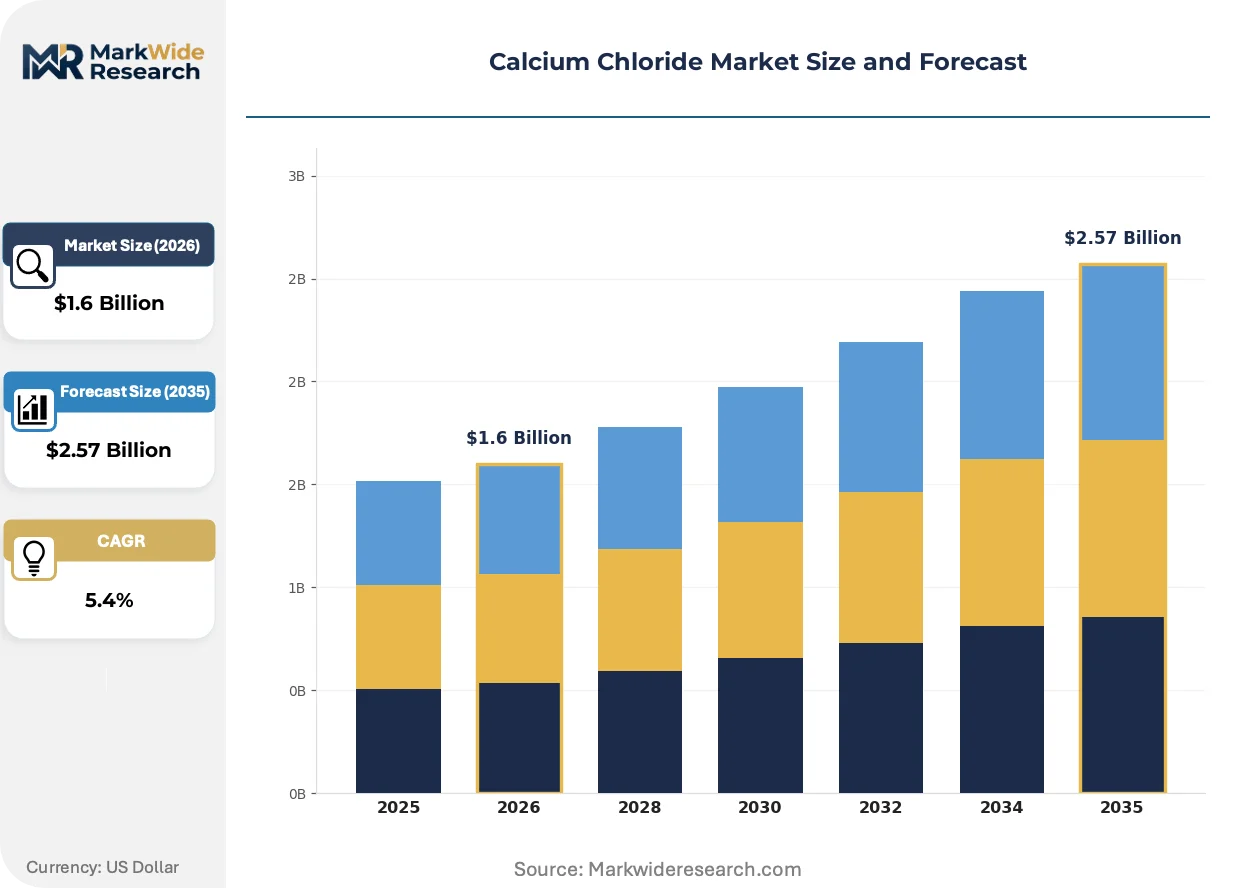
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Pellets, Liquid, Granules Application: De-icing, Dust Control, Food Preservation, Chemical Intermediate End User: Construction, Automotive, Agriculture, Food Industry Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Solvay S.A., Ward Chemical Inc., TETRA Technologies, Inc., Tiger Calcium Services Inc., Weifang Haibin Chemical Co., Ltd., Occidental Petroleum Corporation, Tangshan Sanyou Chemical Industries Co., Ltd., Zirax Ltd., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Chloride Market Strategic Shifts & Innovations
Product formulation flexibility and regulatory compliance automation are redefining competitive advantage across calcium chloride supply chains. Manufacturers invest in assay standardization and application-specific packaging to capture premium positioning.
Blended de-icing formulations is modularizing product offerings for municipal buyers. State DOTs specify treated salt ratios that combine sodium chloride base stock with calcium chloride additive percentages tailored to temperature forecasts. This shift enables suppliers to configure output lines rapidly across pellet, flake, and liquid grades without dedicated plant reconfiguration.
REACH authorization requirements for chloride-based substances in European industrial applications are tightening substance volume tracking obligations. Chemical distributors must demonstrate supply chain transparency from brine extraction through final formulation. The construction end-use channel faces elevated documentation burdens for concrete curing accelerator imports into EU member states.
Specification-driven tendering now dominates highway maintenance chemical procurement in the United States. State DOTs publish detailed performance criteria for freeze-point depression and corrosion inhibition rather than generic product categories. This shift favors suppliers with in-house laboratory certification capabilities and documented field performance histories across multiple winter severity zones.
Calcium Chloride Market Segmentation
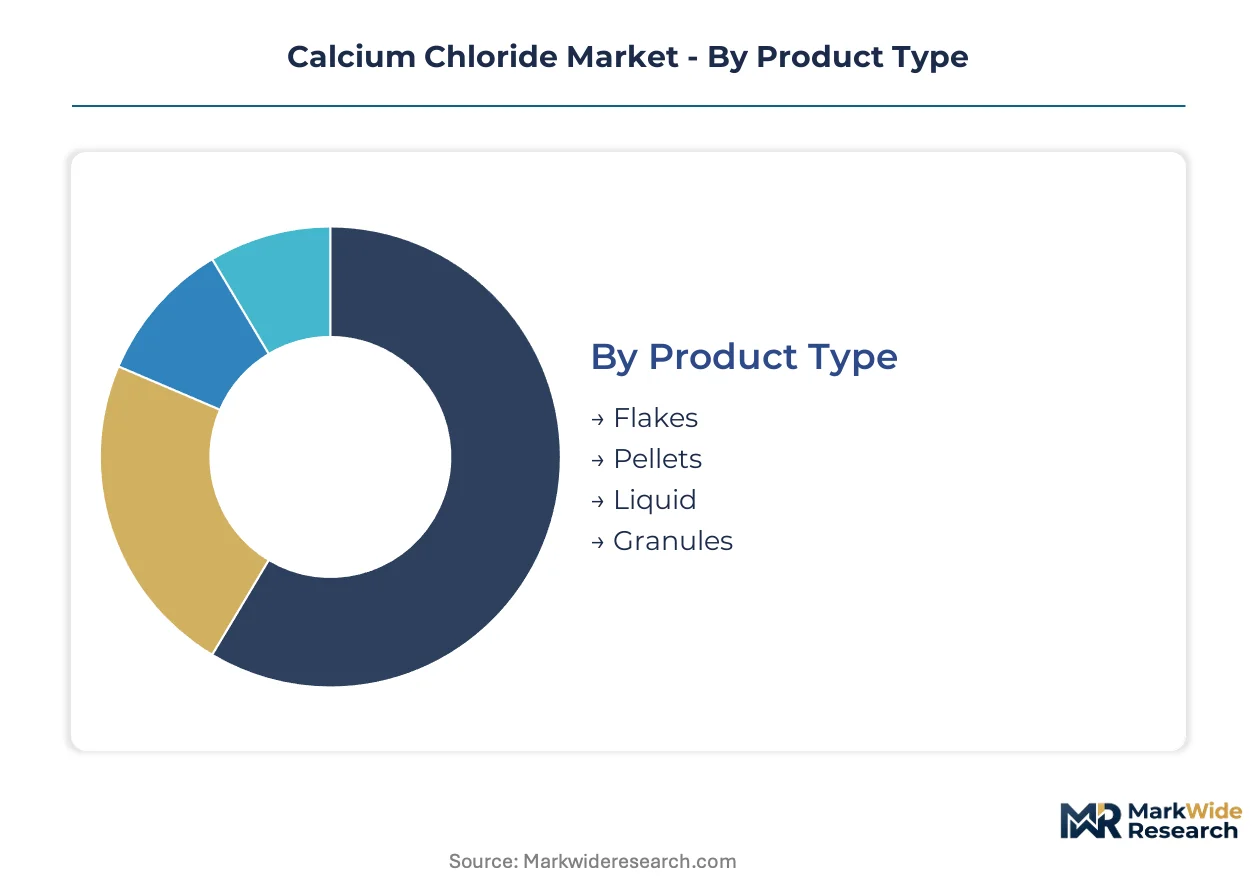
Calcium chloride's physical form and purity grade determine logistics intensity, handling protocols, and margin capture across end-use channels. Segmentation reveals how commodity de-icing volumes fund specialty-grade capacity expansion into food and pharmaceutical applications.
Product Type:
Volume concentrates in bulk flake and liquid formats, while pellet grades command certification premiums in regulated applications.
- Liquid:Aqueous solutions at 28-42% concentration dominate oilfield completion fluid specifications for density control in Gulf of Mexico deepwater drilling. State DOTs specify liquid calcium chloride for pre-wetting salt stockpiles, with procurement volumes tied to winter severity forecasts across the northern United States.
- Flakes:Hygroscopic 77-94% assay material serves as the workhorse format for bulk de-icing tenders and industrial desiccant applications. Shandong Province producers export flake grades through dedicated Qingdao port infrastructure, creating supply concentration risk for international buyers.
- Pellets:Spherical morphology reduces dust generation during pneumatic conveying; USP and FCC certification enables food preservation and pharmaceutical drying applications with margin premiums over commodity grades.
- Granules:Intermediate particle size distribution finds niche positioning in controlled-release dust control formulations for mining haul road maintenance.
Today's leader: Flakes. Tomorrow's challenger: Pellets.
Application:
De-icing anchors volume throughput, while chemical intermediate applications concentrate value capture in integrated manufacturing chains.
- De-icing:Freeze-point depression to minus 25°F drives municipal procurement across the United States, with EPA NPDES stormwater permits pushing adoption of treated salt blends that reduce chloride leaching into watersheds.
- Dust Control:Hygroscopic moisture retention stabilizes unpaved mining haul roads and aggregate stockpiles; pricing follows diesel-linked contract indices in mature western US mining corridors.
- Food Preservation:USP-grade calcium chloride functions as a firming agent in pickled vegetables and cheese production, with FCC compliance requirements creating supplier qualification barriers.
- Chemical Intermediate:Feedstock for calcium hypochlorite and other chlor-alkali derivatives; demand ties to integrated soda ash producer economics through Solvay process co-generation.
De-icing holds volume dominance. Food preservation climbs fastest on certification premiums.
End User:
Construction procurement fluctuates with cold-weather pour schedules, while automotive demand concentrates in aftermarket tire ballast applications.
- Construction:Cold-weather concrete curing accelerators mandate calcium chloride additives to achieve specified compressive strength within shortened pour windows across northern US climates.
- Automotive:Liquid calcium chloride solutions provide tire ballast for agricultural and off-highway equipment; seasonal demand patterns follow planting and harvest cycles.
- Agriculture:Soil amendment applications address calcium deficiency in orchard operations; dust suppression on unpaved farm roads represents secondary consumption.
- Food Industry:Processed food manufacturers specify pellet grades with documented USP or FCC certification for direct food contact applications.
Construction drives seasonal volatility. Food industry delivers margin stability.
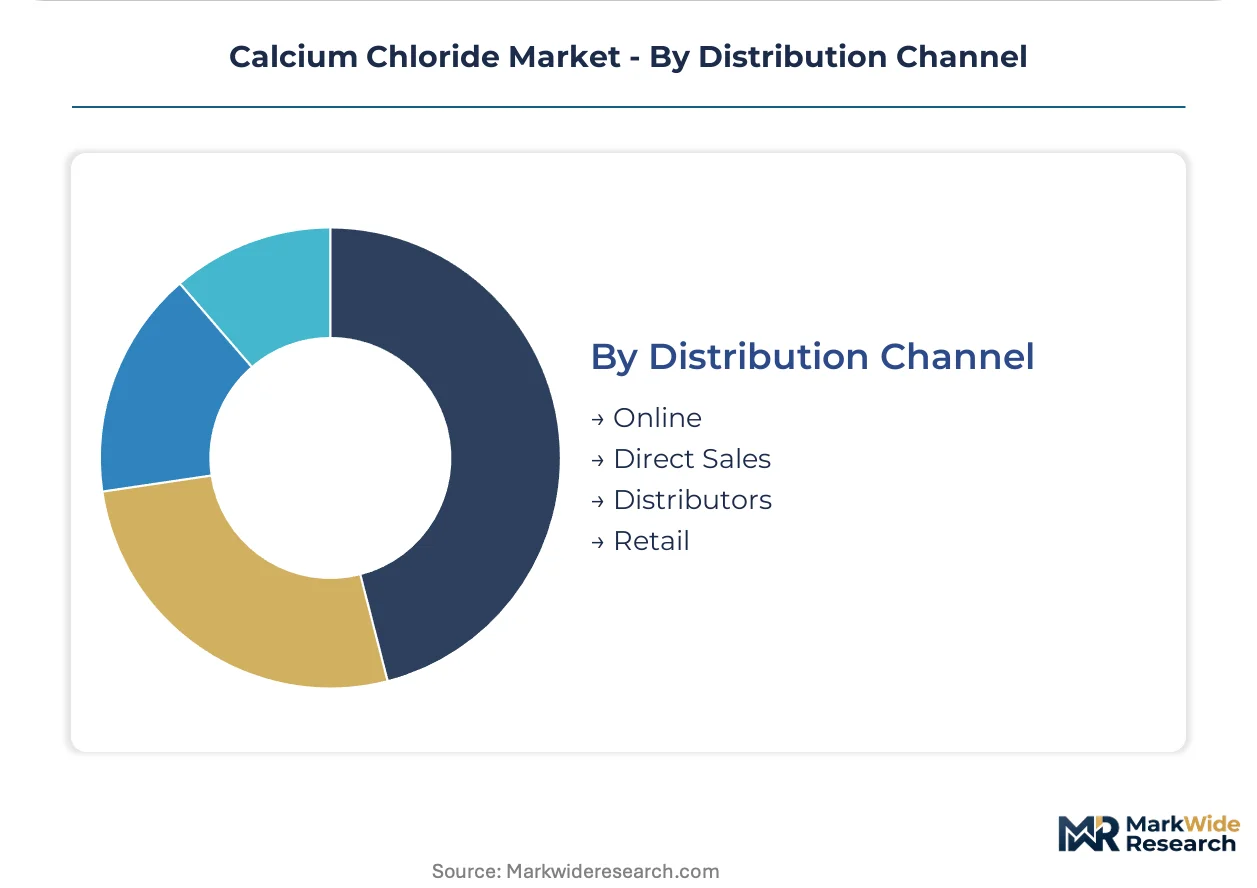
Distribution Channel:
Direct sales capture bulk municipal tenders, while distributor networks handle fragmented industrial accounts.
- Direct Sales:State DOT procurement consolidation favors multi-year supply agreements with integrated producers capable of dedicated railcar delivery to highway maintenance yards.
- Distributors:Regional chemical distributors manage inventory for construction contractors and food processors requiring smaller lot sizes and just-in-time delivery.
- Online:E-procurement platforms piloted by municipal buyers enable price discovery for spot de-icing chemical purchases outside established contract frameworks.
- Retail:Consumer packaged formats for home de-icing and moisture absorption occupy limited shelf space at hardware and home improvement chains.
Direct sales command contract security. Online channels disrupt price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized brine extraction technicians and chemical process engineers concentrate in Gulf Coast petrochemical corridors and Shandong Province manufacturing clusters, anchoring production capacity for hygroscopic salt derivatives.
United States
State DOT procurement teams across Michigan, Minnesota, and New York drive bulk de-icing tenders tied to winter severity indices. EPA NPDES stormwater permits constrain municipal salt storage practices, elevating treated blend specifications that incorporate calcium chloride for leaching reduction. Gulf Coast basin operations near Houston and Lake Charles supply deep well brine feedstocks for oilfield completion fluid formulations.
China
Shandong Province chemical engineers operate dedicated port loading infrastructure at Qingdao and Weifang for bulk flake export capacity. The country's dual carbon goals pressure energy-intensive Solvay process operations, favoring natural brine evaporation methods with lower carbon intensity. Tangshan Sanyou Chemical Industries exemplifies integrated soda ash co-generation models that capture captive calcium chloride streams.
Canada
Transportation ministry procurement officials in Ontario and Quebec specify calcium chloride-treated salt blends for highway maintenance across severe winter corridors. Environment and Climate Change Canada guidelines on road salt environmental impacts parallel EPA frameworks, pushing municipalities toward controlled-release formulations. Alberta oil sands operations consume liquid grades for dust suppression on unpaved haul roads.
Germany
REACH authorization requirements for chloride-based substances tighten substance volume tracking obligations for chemical distributors serving industrial desiccant applications. The EU Green Deal's carbon-border adjustment mechanism realigns sourcing patterns toward lower-logistics-intensity European producers. BASF and Evonik industrial chemical clusters along the Rhine corridor maintain captive calcium chloride feedstock integration.
Saudi Arabia
SABIC process engineers leverage abundant limestone resources and low-cost natural gas for Solvay process economics in Jubail Industrial City. The country's national industrial development program prioritizes downstream chemical derivative capacity expansion. Red Sea coastal evaporation ponds supply raw brine feedstocks for regional desiccant and drilling fluid manufacturers.
Calcium Chloride Market Key Industry Players
Capital-heavy producers compete with asset-light distributors across distinct value chain positions. Integrated chemical conglomerates with captive feedstock streams anchor supply security for municipal tenders, while regional distributors manage fragmented industrial accounts. Three archetypes dominate: brine extraction specialists with deep well operations, Solvay process operators with soda ash co-generation, and bulk commodity traders with dedicated port infrastructure. Competitive moves concentrate on multi-year DOT contract qualification and e-procurement platform integration.
Among European integrated chemical producers, Solvay S.A. occupies a position exemplifying captive feedstock security through soda ash co-generation economics. TETRA Technologies, Inc. and Weifang Haibin Chemical Co., Ltd. represent contrasting geographic anchors for brine extraction versus bulk export manufacturing archetypes. These three companies illustrate how feedstock access and logistics infrastructure determine competitive positioning across municipal, industrial, and oilfield end-use channels.
| Leading Market Players |
|---|
| Solvay S.A. |
| Ward Chemical Inc. |
| TETRA Technologies, Inc. |
| Tiger Calcium Services Inc. |
| Weifang Haibin Chemical Co., Ltd. |
| Occidental Petroleum Corporation |
| Tangshan Sanyou Chemical Industries Co., Ltd. |
| Zirax Ltd. |
| Baker Hughes Company |
| Others |
Cost & Logistics Intelligence
Natural gas feedstock costs cascade through Solvay process economics to stratify calcium chloride pricing across certification tiers, with energy-intensive operations in the United States and Saudi Arabia commanding premium positioning against brine-evaporation competitors in Shandong Province.
Pricing Analysis
Contracted railcar deliveries versus spot bulk tenders split the municipal procurement landscape. Three-tier pricing structure separates USP-certified pellet grades for food preservation from standard flake de-icing commodities and economy liquid formulations for dust control. Cost compression in commodity flake grades is intensifying because Shandong Province exporters leverage dedicated Qingdao port infrastructure for volume throughput. State DOT buyers exhibit highest price sensitivity in multi-year tender competitions, while oilfield completion fluid purchasers prioritize density specification compliance over unit cost.
Supply Chain Analysis
Limestone and deep well brine feedstocks rest on extraction operations concentrated in the United States Gulf Coast basin, Shandong Province manufacturing clusters, and Saudi Arabia's Jubail Industrial City. Soda ash co-generation byproduct streams, natural brine evaporation ponds, and Solvay process chemical synthesis constitute the primary input pathways. Single-source vulnerability concentrates in Qingdao port loading capacity for international flake shipments. Distribution runs through direct railcar delivery to state DOT highway maintenance yards for bulk de-icing volumes, with regional chemical distributors managing fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium chloride market functions as a stable compounder anchored by non-discretionary municipal de-icing procurement that resists economic cyclicality. State DOT budget allocations for highway maintenance chemicals demonstrate inelastic demand patterns across winter severity fluctuations.
For Market Incumbents: Deepen captive brine feedstock security through long-term mineral rights agreements across the Gulf Coast basin to offset magnesium chloride substitution threats in mining dust control applications. Expand in-house laboratory certification capabilities to meet specification-driven tender requirements from consolidated state DOT procurement teams. Prioritize automated packaging line investments that achieve OSHA permissible exposure limit compliance without labor-intensive dust mitigation protocols.
For New Entrants and Emerging Players: Capture direct-to-municipality e-procurement platform integration opportunities as state DOTs pilot digital tendering systems that bypass traditional distributor networks. Target food-grade pellet certification white space where USP and FCC compliance requirements create supplier qualification barriers against commodity flake competitors. Pursue private-label arrangements with regional chemical distributors serving construction contractors requiring just-in-time delivery of accelerated concrete curing additives.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional distributors lack capital for enclosed conveying systems and multi-species brine separation expertise. The five-to-ten-year viability window favors integrated producers with captive feedstock streams and documented field performance histories across multiple winter severity zones. Acquisition target archetypes include deep well brine extraction specialists with proven geochemical management capabilities and established railcar delivery contracts. Watch EPA NPDES permit enforcement intensity as the inflection indicator for treated blend specification adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Feedstock | Secures mineral rights across Gulf Coast basin operations against magnesium chloride substitution. |
| USP-Grade Pellet Certification Investment | Captures margin premiums in food preservation applications beyond commodity de-icing tenders. |
| State DOT E-Procurement Platform Integration | Bypasses traditional distributor networks for multi-year highway maintenance chemical contracts. |
| Automated Packaging Line Capital Deployment | Achieves OSHA dust exposure compliance with enclosed conveying systems at distribution facilities. |
| Long-Term Railcar Delivery Agreement | Locks in dedicated transportation capacity for consolidated municipal procurement volumes. |
Research Approach
Coverage spans the United States, China, Canada, Germany, and Saudi Arabia, with primary inputs from each region's production and consumption centers. Plant managers at Solvay process operations, procurement leads at state DOT highway maintenance divisions, distribution channel partners in regional chemical supply networks, and technical R&D directors at oilfield service companies contributed structured interviews. Secondary validation drew from EPA NPDES permit filings, SEC 10-K disclosures by integrated chemical producers, customs and trade data for bulk flake export volumes, and ACC industry reports. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and end-use segmentations.
Granularity-level modeling tracked liquid, flake, pellet, and granule physical forms at assay concentration tiers from 28% aqueous solutions through 94% anhydrous grades. De-icing, dust control, food preservation, and chemical intermediate applications were projected across construction, automotive, agriculture, and food industry end users. CAGRs were derived from regression analysis of historical procurement volumes against winter severity indices and infrastructure spending patterns. Oilfield completion fluid density specifications and EPA stormwater discharge permit enforcement timelines served as industry-specific forecast calibration inputs across the projection horizon.
Natural gas price volatility, Shandong Province port capacity constraints, and magnesium chloride substitution rates in mining applications are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding state DOT procurement consolidation trajectories and REACH authorization timelines for European industrial applications. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Sulfur Market