
 Glucaric Acid Market | 2026-2036
Glucaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Glucaric Acid Market Analysis
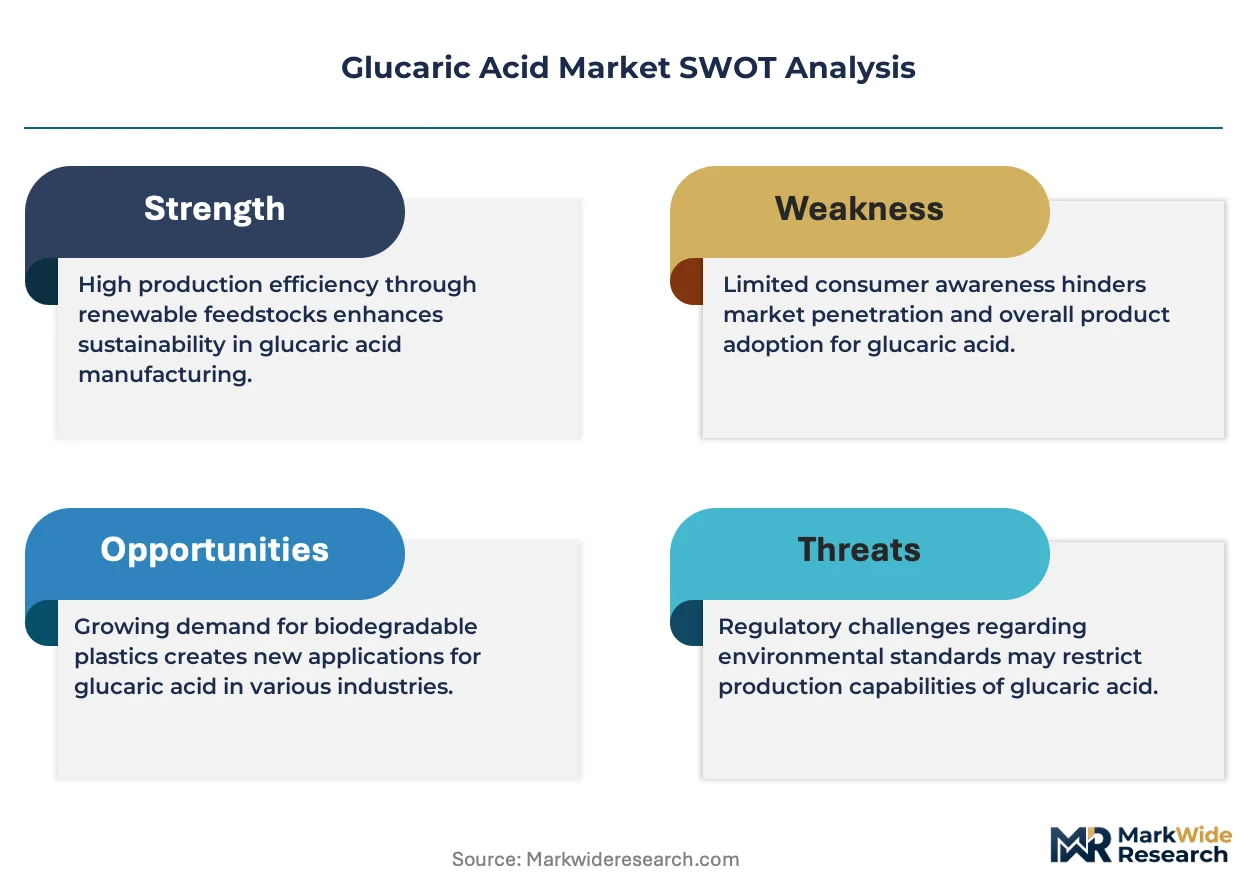
ISO 17025 accreditation is unwinding competitive access for glucaric acid suppliers targeting pharmaceutical and food-grade buyers. Kalion Inc. leverages continuous fermentation technology to sustain cost leadership in bio-based production. BASF SE anchors its position through backward integration into glucose feedstock and captive oxidation capacity. Merck KGaA differentiates via analytical-grade purity standards and controlled-channel distribution to European laboratories.
Glucaric acid is a dicarboxylic acid derived from glucose oxidation, existing as a six-carbon chain with carboxylic acid groups at C1 and C6 positions, typically synthesized through nitric acid oxidation or microbial fermentation with glucose dehydrogenase enzymes. The compound functions primarily as a chelating agent, building block for biodegradable polymers, and platform chemical for adipic acid replacement in nylon production. Powder and crystalline grades command premium positioning due to pharmaceutical and nutraceutical formulation requirements, while liquid concentrates serve volume detergent applications where solubility and handling efficiency matter. Food additive and preservative applications show the fastest trajectory as clean-label demand intensifies across North American and European processed food sectors.
EPA Safer Choice program standards and REACH Annex XVII restrictions on phosphates in consumer detergents directly expand addressable demand for glucaric acid as a sequestrant alternative. FDA GRAS self-affirmation pathways and EFSA novel food consultations govern food and nutraceutical entry, creating multi-year qualification timelines that favor established suppliers with regulatory dossier depth. Stakeholders must monitor fermentation yield breakthroughs and biorefinery co-location economics, as these variables determine which production configurations achieve viable unit economics at commercial scale.
Market Dynamics
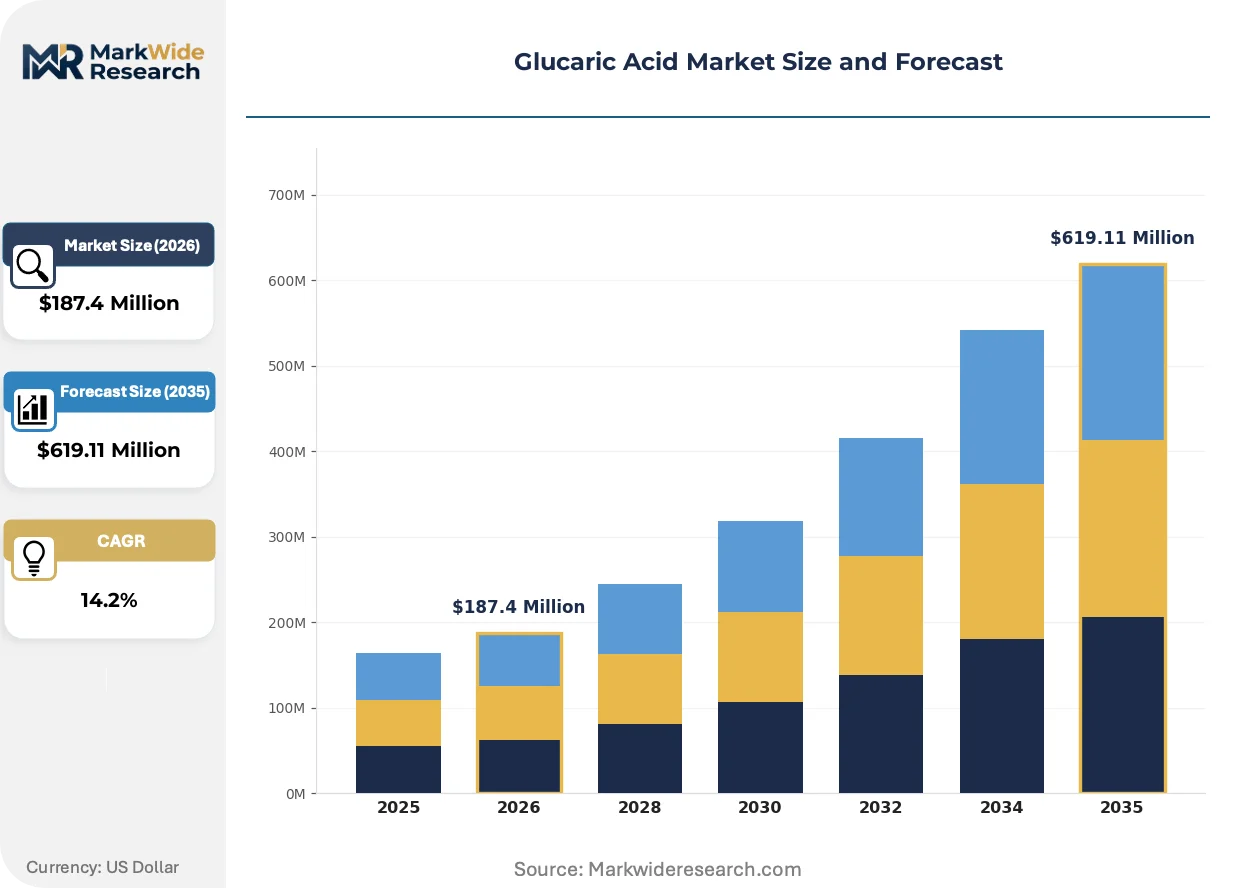
Continuous fermentation technology is compressing production costs for bio-based glucaric acid, while REACH and EPA phosphate restrictions redirect detergent formulation demand toward sequestrant alternatives.
Growth Catalysts
- EPA Safer Choice program:Federal procurement preferences for phosphate-free detergents expand glucaric acid uptake in institutional cleaning contracts across United States school districts and healthcare facilities.
- Glucose dehydrogenase enzyme engineering:Strain optimization breakthroughs at German biotech clusters cut fermentation cycle times, improving unit economics for food-grade certification batches.
- Adipic acid replacement demand:Nylon 6,6 producers in United States and Germany pilot glucaric acid as a bio-based precursor to reduce Scope 3 emissions under Science Based Targets initiatives.
Market Restraints
- Nitric acid oxidation dependency:Conventional chemical synthesis routes expose producers to volatile glucose feedstock pricing and hazardous waste disposal costs concentrated in China and India.
- ISO 17025 accreditation scarcity:Analytical-grade certification bottlenecks limit supplier entry into European pharmaceutical and laboratory chemical channels.
- Citric acid substitution threat:Established chelating agents with deeper supply chains and lower spot pricing capture volume detergent contracts from cost-sensitive buyers.
Strategic Opportunities
- EFSA novel food pathway acceleration:Accelerated consultation timelines for GRAS-equivalent status in European nutraceutical applications open formulation partnerships with clean-label supplement brands.
- Biorefinery co-location models:Integration with corn wet milling complexes in Iowa and Illinois yields captive glucose supply and shared utility infrastructure.
- Biodegradable polymer feedstock demand:Polyglucaric acid esters gain traction as compostable packaging films displace petroleum-derived polyesters in German and French retail chains.
Industry Challenges
- Fermentation scale-up talent gap:Industrial microbiology and bioprocess engineering expertise concentrates at academic institutions, creating hiring competition among commercial producers.
- Multi-jurisdiction dossier compilation:FDA GRAS self-affirmation, EFSA novel food consultations, and state-level chemical inventories impose parallel compliance timelines stretching 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucaric Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Crystalline End User: Food & Beverage, Pharmaceuticals, Agriculture, Personal Care Application: Food Additive, Preservative, Nutraceutical, Detergent Distribution Channel: Online, Distributors, Direct Sales, Retail |
| Companies Covered | Merck KGaA, Kalion Inc., Cayman Chemical Company, Haihang Group, NutriScience Innovations, BASF SE, Rivertop Renewables, Alfa Chemistry, AK Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucaric Acid Market Emerging Trajectories
Bioprocess intensification and regulatory chemistry mandates are restructuring how glucaric acid reaches end-use markets, with implications for production geography and supplier qualification requirements.
Continuous fermentation systems with cell retention technology are displacing batch oxidation processes in commercial-scale glucaric acid manufacturing. Specialty chemical distributors in Germany and the Netherlands now specify bio-based origin certificates for detergent-grade material. This displacement compresses capital intensity per kilogram of output while raising barriers for nitric acid oxidation incumbents.
REACH Annex XVII restrictions on phosphates in consumer laundry detergents entered full enforcement across EU member states in 2017, with downstream effects persisting in formulation R&D budgets. Detergent manufacturers reformulated powder and liquid products to meet Ecolabel criteria, redirecting sequestrant procurement toward glucaric acid and polyaspartic acid alternatives. German formulators lead this transition, with ECHA substance volume tracking showing steady registration increases for glucaric acid salts.
Clean-label preservative preferences among North American processed food brands now prioritize recognizable ingredient names over functional performance metrics alone. Procurement teams at mid-size contract manufacturers request glucaric acid documentation for pH buffering and chelation in sauce and dressing applications. This shift concentrates demand qualification activity with suppliers holding FDA GRAS letters and third-party organic handling certifications.
Glucaric Acid Market Segmentation
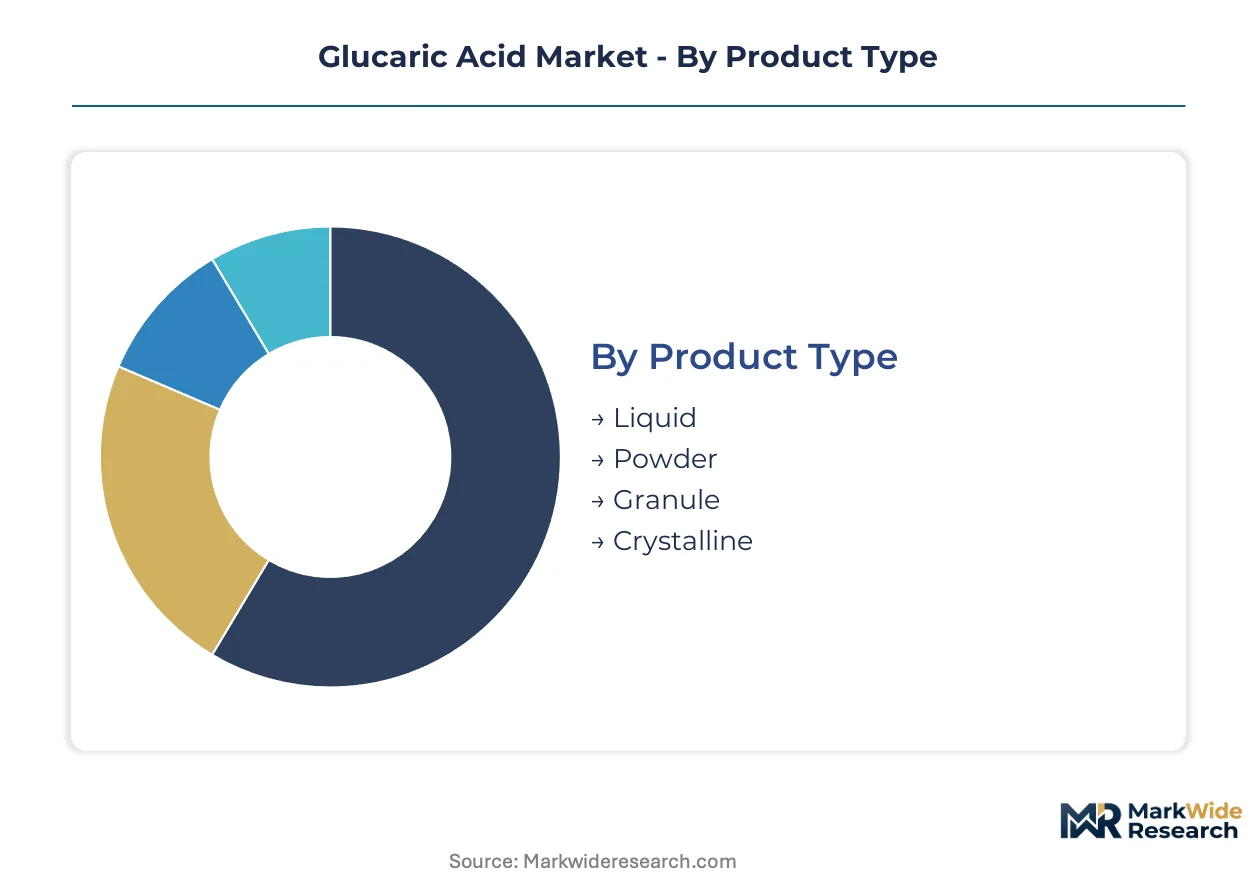
Glucaric acid procurement patterns diverge sharply across physical forms and end-use specifications, with pharmaceutical and food-grade buyers imposing certification requirements that commodity detergent purchasers rarely demand. Suppliers configure production assets and inventory positions around these tiered qualification barriers.
Product Type:
Powder and crystalline grades serve export-intensive pharmaceutical channels, while liquid concentrates dominate domestic detergent formulation volumes in Germany and the United States.
- Liquid:Aqueous solutions at 40-60% concentration optimize handling efficiency for high-volume detergent manufacturers. Demand concentrates with institutional cleaning contractors in United States school districts seeking phosphate-free sequestrants under EPA Safer Choice procurement rules.
- Powder:Spray-dried material with controlled particle size distribution suits food additive applications requiring precise dosing in dry seasoning blends. North American processed food brands specify powder grades for clean-label sauce and dressing formulations.
- Granule:Agglomerated form factors improve flowability for agricultural chelation applications.
- Crystalline:High-purity solid meeting USP and EP monographs for analytical reagent and pharmaceutical intermediate use.
Liquid holds the largest share; momentum sits with crystalline grades as laboratory chemical distributors expand bio-based origin certificate requirements.
End User:
Margin structures vary threefold across end-use tiers, with pharmaceutical and food-grade certification batches commanding premium positioning over agricultural commodity volumes.
- Food & Beverage:Clean-label preservative and pH buffering applications in sauces, dressings, and processed meat products. FDA GRAS self-affirmation pathways and third-party organic handling certifications govern supplier qualification.
- Pharmaceuticals:Analytical-grade purity standards for laboratory reagents and drug synthesis intermediates. ISO 17025 accreditation bottlenecks limit viable supplier pools for European pharmaceutical distributors.
- Agriculture:Chelating agent for micronutrient fertilizers, competing with EDTA and citric acid on cost per metal ion sequestered.
- Personal Care:Emerging use in biodegradable cosmetic formulations, particularly in German and French natural product lines.
Food & Beverage captures the steepest expansion trajectory; Pharmaceuticals retains the highest margin per kilogram.
Application:
Application selection determines regulatory pathway complexity, with food additive and nutraceutical entries requiring multi-year dossier compilation versus detergent sequestrant approvals.
- Food Additive:pH control and chelation in processed foods, replacing synthetic preservatives with recognizable ingredient names. EFSA novel food consultation timelines create 24-36 month entry barriers favoring established suppliers.
- Preservative:Microbial growth inhibition through metal ion sequestration in acidic food systems. Clean-label positioning drives procurement at mid-size North American contract manufacturers.
- Nutraceutical:Dietary supplement ingredient for detoxification and hormone metabolism support claims.
- Detergent:Phosphate replacement sequestrant in institutional and consumer laundry products. REACH Annex XVII restrictions and EPA Safer Choice program standards redirect formulation R&D budgets toward glucaric acid and polyaspartic acid alternatives.
Detergent commands the greatest volume; nutraceutical applications are climbing the fastest as European clean-label supplement brands accelerate EFSA-equivalent status petitions.
Distribution Channel:
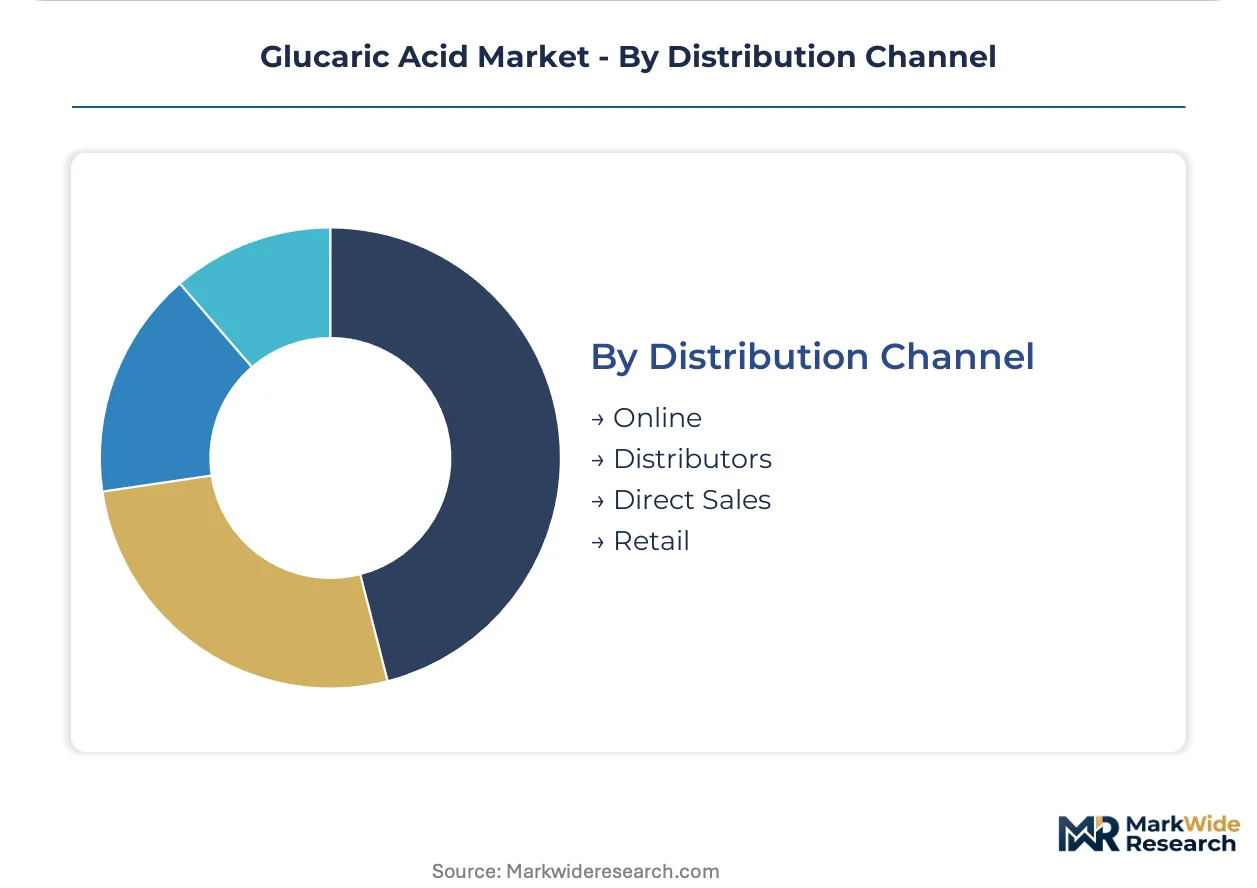
Channel selection reflects buyer scale and technical service requirements, with direct sales dominating pharmaceutical qualification batches and distributors handling detergent commodity volumes.
- Online:E-procurement platforms serving small-scale research laboratories and specialty food startups with certificate-of-analysis documentation.
- Distributors:Regional chemical distributors inventory detergent-grade liquid concentrates for just-in-time delivery to formulators in Germany, the Netherlands, and United States Midwest manufacturing corridors.
- Direct Sales:Dedicated account management for pharmaceutical and food-grade buyers requiring regulatory dossier support and custom specification development.
- Retail:Limited presence through specialty chemical and laboratory supply storefronts.
Distributors move the highest tonnage; direct sales is gaining share fastest as pharmaceutical buyers consolidate supplier relationships around regulatory compliance capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Northwestern Europe's dominance in glucaric acid trade flows, connecting glucose feedstock corridors from the Rhine-Ruhr industrial belt to Atlantic-facing formulation centers.
Germany
Detergent manufacturers in the Rhine-Ruhr region drive sequestrant demand as REACH Annex XVII phosphate restrictions tighten formulation requirements. ECHA substance volume tracking shows steady registration increases for glucaric acid salts among domestic formulators. The Leverkusen-Düsseldorf chemical corridor hosts backward-integrated producers with captive oxidation capacity serving both domestic and Benelux markets.
United States
Corn wet milling complexes in Iowa and Illinois yield captive glucose supply for fermentation-based production, while institutional cleaning contractors in Midwest school districts seek phosphate-free alternatives under EPA Safer Choice procurement rules. The Chicago-Gary manufacturing corridor concentrates detergent formulation activity with direct rail links to glucose feedstock sources. FDA GRAS self-affirmation pathways govern food-grade entry for suppliers targeting North American processed food brands.
China
Nitric acid oxidation capacity concentrates in Shandong and Jiangsu provinces, exposing producers to volatile glucose pricing and hazardous waste disposal compliance under MEE environmental enforcement. The Yangtze River Delta chemical clusters serve export-oriented detergent ingredient demand despite REACH-equivalent registration bottlenecks for European pharmaceutical channels. Qingdao and Ningbo ports handle bulk liquid concentrate shipments to Southeast Asian formulation markets.
India
Specialty chemical distributors in Maharashtra and Gujarat inventory technical-grade material for agricultural chelation applications competing with EDTA on cost per metal ion sequestered. CDSCO import licensing requirements and state-level chemical inventories create parallel compliance timelines for pharmaceutical-grade entry. The Mumbai-Pune industrial belt hosts contract manufacturers exploring clean-label preservative applications for domestic processed food brands.
Netherlands
Rotterdam's liquid bulk terminals enable just-in-time delivery of aqueous concentrates to German and Belgian detergent formulators seeking Ecolabel-compliant sequestrants. EFSA novel food consultation pathways attract nutraceutical ingredient traders establishing European distribution headquarters. The Port of Rotterdam's chemical handling infrastructure connects glucose feedstock flows from the ARA refining hub to biorefinery co-location opportunities.
Glucaric Acid Market Vendor Landscape
Listed leaders compete with private specialists across regulatory dossier depth and fermentation technology access. The vendor base fragments between multinational chemical conglomerates with backward integration into glucose feedstock and venture-backed biotech specialists commercializing continuous fermentation platforms. Three archetypes dominate: integrated chemical majors with captive oxidation assets, bioprocess technology licensors, and analytical-grade specialists serving laboratory distribution channels. Capacity expansion and strategic partnerships around biorefinery co-location represent the dominant competitive moves.
Within the integrated chemical tier, BASF SE anchors European supply through Rhine-Ruhr manufacturing assets. Among fermentation technology specialists, Kalion Inc. exemplifies venture-backed platforms targeting cost compression via continuous cell retention systems. On the analytical-grade vector, Merck KGaA occupies a position serving European pharmaceutical distributors with ISO 17025-accredited material. These three anchors illustrate how competitive positioning diverges across feedstock control, bioprocess innovation, and regulatory certification depth.
| Leading Market Players |
|---|
| Merck KGaA |
| Kalion Inc. |
| Cayman Chemical Company |
| Haihang Group |
| NutriScience Innovations |
| BASF SE |
| Rivertop Renewables |
| Alfa Chemistry |
| AK Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for crystalline pharmaceutical grades concentrate pricing power with ISO 17025-accredited suppliers in Germany and the United States, while liquid detergent concentrates trade on tighter inventory cycles that expose producers to glucose feedstock volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade crystalline, food-grade powder, and technical-grade liquid separates buyers by certification burden and volume scale. Pharmaceutical batches command substantial premiums due to ISO 17025 scarcity and multi-year dossier investments, while detergent volumes compete on delivered cost against citric acid substitutes. Cost compression in technical grades is intensifying because Chinese nitric acid oxidation incumbents face hazardous waste disposal escalation under MEE enforcement. Agricultural chelation buyers exhibit highest price sensitivity; pharmaceutical distributors show least.
Supply Chain Analysis
Just-in-time delivery preferences dominate detergent formulation channels in Germany and the Netherlands, whereas pharmaceutical buyers maintain strategic stockpiles to buffer against ISO 17025 accreditation bottlenecks. Production concentrates in Germany, the United States, and China, with glucose feedstock sourcing anchored in Iowa-Illinois corn wet milling and Rhine-Ruhr industrial complexes. The network rests on nitric acid oxidation capacity in Shandong and Jiangsu provinces, creating single-source vulnerability for non-fermentation supply. Distribution runs through Rotterdam liquid bulk terminals for European detergent formulators and direct rail links to Midwest manufacturing corridors for United States institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against citric acid and EDTA incumbents with deeper supply chains; incumbents must navigate price-sensitive detergent procurement while extracting premium positioning from regulatory-grade certification scarcity.
For Market Incumbents: Fortify backward integration into glucose feedstock through biorefinery co-location in Iowa and Illinois to compress unit economics against Chinese oxidation competitors. Deepen ISO 17025 accreditation moats to limit analytical-grade channel entry, as EFSA novel food consultation timelines already favor established dossier holders against insurgent fermentation specialists. For New Entrants and Emerging Players: Differentiate on continuous fermentation technology platforms that collapse production cycle times below batch oxidation benchmarks. Target North American food additive white space where FDA GRAS self-affirmation pathways remain more navigable than EFSA equivalents, and pursue direct sales models with mid-size contract manufacturers seeking clean-label preservative documentation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because multi-jurisdiction compliance timelines create durable competitive moats around incumbent certification assets. Acquisition targets with captive glucose supply and EFSA consultation progress offer superior risk-adjusted positioning. Watch fermentation yield breakthroughs at German biotech clusters as the inflection signal for bio-based cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Biorefinery Co-location | Captive glucose supply from Iowa-Illinois wet milling complexes compresses feedstock logistics costs. |
| ISO 17025 Accreditation Investment | Analytical-grade certification unlocks European pharmaceutical distributor channels with limited viable supplier pools. |
| Continuous Fermentation Scale-Up | Cell retention technology displaces batch oxidation capital intensity per kilogram of food-grade output. |
| EFSA Novel Food Pathway Navigation | Accelerated consultation timelines open formulation partnerships with clean-label European nutraceutical brands. |
| Backward Integration into Glucose Feedstock | Rhine-Ruhr and Midwest corn belt proximity secures supply against volatile Chinese glucose pricing. |
Methodological Framework
A spread of perspectives from plant managers at fermentation facilities, procurement leads at detergent OEMs, distribution channel partners in Rotterdam and Chicago, and regulatory affairs directors converged on the working assumptions. Primary interviews triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical majors, and ECHA substance volume tracking databases. Bottom-up capacity and utilization estimates reconciled with top-down end-use demand modeling across the analysis window.
Segmentation dimensions modeled include physical form tier, end-use industry certification level, regional production hub, and distribution channel structure. CAGRs derived from slope-intercept fitting of historical volume trajectories against projected regulatory mandate enforcement schedules and fermentation technology adoption curves. Industry-specific inputs incorporated EPA Safer Choice procurement penetration assumptions and REACH Annex XVII compliance timelines.
Forecasts assume regulatory continuity in EPA Safer Choice standards and REACH Annex XVII phosphate restrictions; material policy shifts would require re-modeling. Revision becomes warranted when fermentation yield breakthroughs at commercial scale cross thresholds that invert bio-based versus nitric acid oxidation unit economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
2-Ethyl Hexanol Market