
 Sulfamic Acid Market | 2026-2036
Sulfamic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfamic Acid Market Outlook
Water treatment facilities are rotating toward higher-purity sulfamic acid formulations as municipal infrastructure upgrades accelerate. BASF SE leverages its integrated European production network to sustain supply security for industrial-grade buyers. Nissan Chemical Corporation anchors its position through specialized laboratory-grade manufacturing in Japan. Shandong Mingda Chemical Technology Co., Ltd dominates regional cost structures with scaled output serving Asian cleaning-agent producers.
Sulfamic acid is a strong, non-volatile, non-hygroscopic solid acid with the formula H3NSO3, manufactured primarily through urea-sulfur trioxide reaction followed by hydrolysis, and it functions as a selective sulfonating agent, descaling compound, and chlorine stabilizer across industrial processes. Industrial-grade product lines occupy the largest volume share, though laboratory-grade and pharmaceutical-grade segments command superior margin pools due to stringent certification requirements. Chemical intermediates and cleaning agents represent the fastest-growing application clusters, while textile processing remains mature with stable offtake.
EPA regulations in the United States and REACH frameworks in Europe constrain residual heavy-metal thresholds, compelling producers to upgrade purification systems and documentation protocols. China's SAMR enforces GB standards for industrial chemical purity that directly shape export eligibility for domestic manufacturers. Stakeholders must monitor regulatory divergence across these jurisdictions to calibrate product portfolios and certification investments without overcommitting to single-market specifications.
Market Dynamics
Municipal water treatment infrastructure upgrades across China, India, and Germany are tightening purity specifications for sulfamic acid suppliers, forcing purification system investments and documentation protocol overhauls.
Growth Catalysts
- EPA Standards Evolution:United States municipalities are accelerating descaling agent procurement to meet revised residual heavy-metal thresholds, pulling higher-purity formulations into water treatment facilities.
- Cleaning Agent Manufacturing:Asian producers of industrial degreasers and metal cleaners are expanding sulfamic acid offtake for selective sulfonation processes in surface preparation.
- Chlorine Stabilization Demand:Swimming pool and aquatics facilities in Germany are adopting sulfamic acid-based stabilizers to extend chlorine efficacy under REACH-compliant formulations.
Market Restraints
- Urea Feedstock Volatility:The urea-sulfur trioxide reaction pathway exposes producers to nitrogen fertilizer price swings, compressing margin predictability for integrated manufacturers.
- Shandong Supply Concentration:Regional production gravity in China's Shandong province creates single-point vulnerability for Asian cleaning-agent supply chains.
- Hydrochloric Acid Substitution:Some descaling applications are reverting to liquid acid alternatives where handling infrastructure already exists, capping sulfamic acid penetration in legacy industrial sites.
Strategic Opportunities
- Pharmaceutical-Grade Certification:Laboratory-grade producers can capture margin expansion by securing pharmacopeia compliance for excipient applications in oral dosage manufacturing.
- India Municipal Expansion:Smart Cities Mission infrastructure investments are opening bulk tender opportunities for water treatment chemical suppliers in secondary urban centers.
- EU Green Deal Alignment:REACH-registered producers with verified carbon footprint documentation can access preferential procurement channels under the EU Green Deal sustainable chemistry incentives.
Industry Challenges
- Analytical Chemist Shortage:GB standards compliance and REACH documentation require specialized chromatography expertise that remains scarce in China's inland manufacturing zones.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA, REACH, and SAMR registration processes extend product launch cycles by 18-24 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfamic Acid Market |
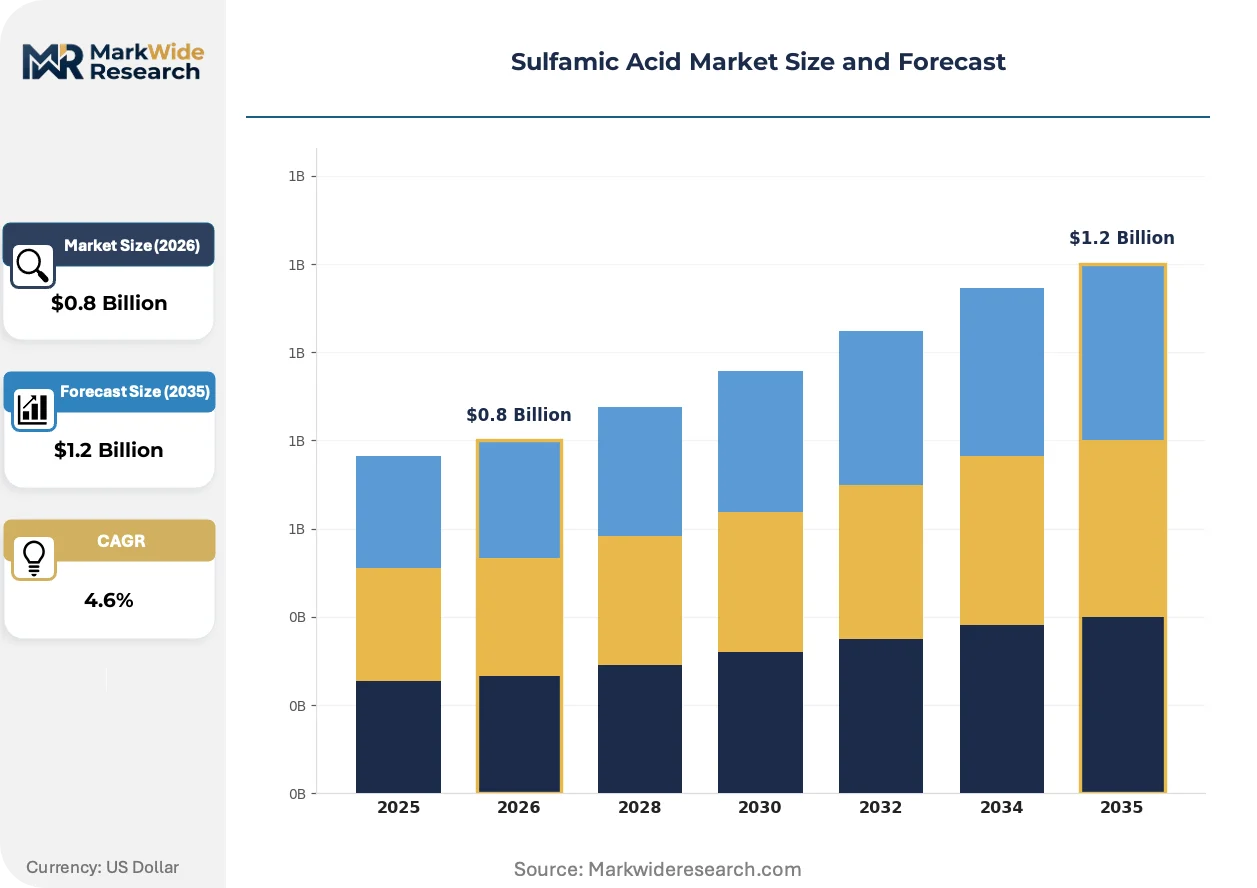
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Pharmaceutical Grade, Cosmetic Grade Application: Cleaning Agents, Water Treatment, Chemical Intermediates, Textile Processing End User: Chemical Manufacturers, Pharmaceuticals, Cosmetics, Water Treatment Facilities Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BASF SE, Nissan Chemical Corporation, DuPont, AkzoNobel N.V., Shandong Mingda Chemical Technology Co., Ltd, Laizhou Jinxing Chemical Co., Ltd., Yantai Sanding Chemical Co., Ltd., Palm Commodities International, LLC, Raviraj Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfamic Acid Market Strategic Shifts
Membrane-based purification systems are displacing traditional crystallization methods, enabling producers to meet tightening heavy-metal specifications while reducing solvent waste streams.
Continuous-flow reactor technology is decomposing batch manufacturing economics in sulfamic acid production. Specialty chemical producers in Japan and Germany are adopting these systems to reduce cycle times and improve lot-to-lot consistency. The shift is compressing capital recovery periods for mid-scale producers while raising barriers for legacy batch operators.
REACH authorization requirements for substances of very high concern are tightening supply chain due diligence obligations across European industrial chemical distribution. Importers must now document full substance identity down to 0.1% concentration thresholds. Laboratory-grade and pharmaceutical-grade segments are responding fastest, locking in audited supplier relationships before 2025 authorization deadlines.
Specification-driven procurement is consolidating buyer power among municipal water authorities and large-scale cleaning-agent manufacturers. Long-term framework agreements with fixed purity tiers are displacing spot-market purchasing in Germany and the United States. This concentration is most visible in North Rhine-Westphalia's regional water utility purchasing cooperatives.
Sulfamic Acid Market Segmentation
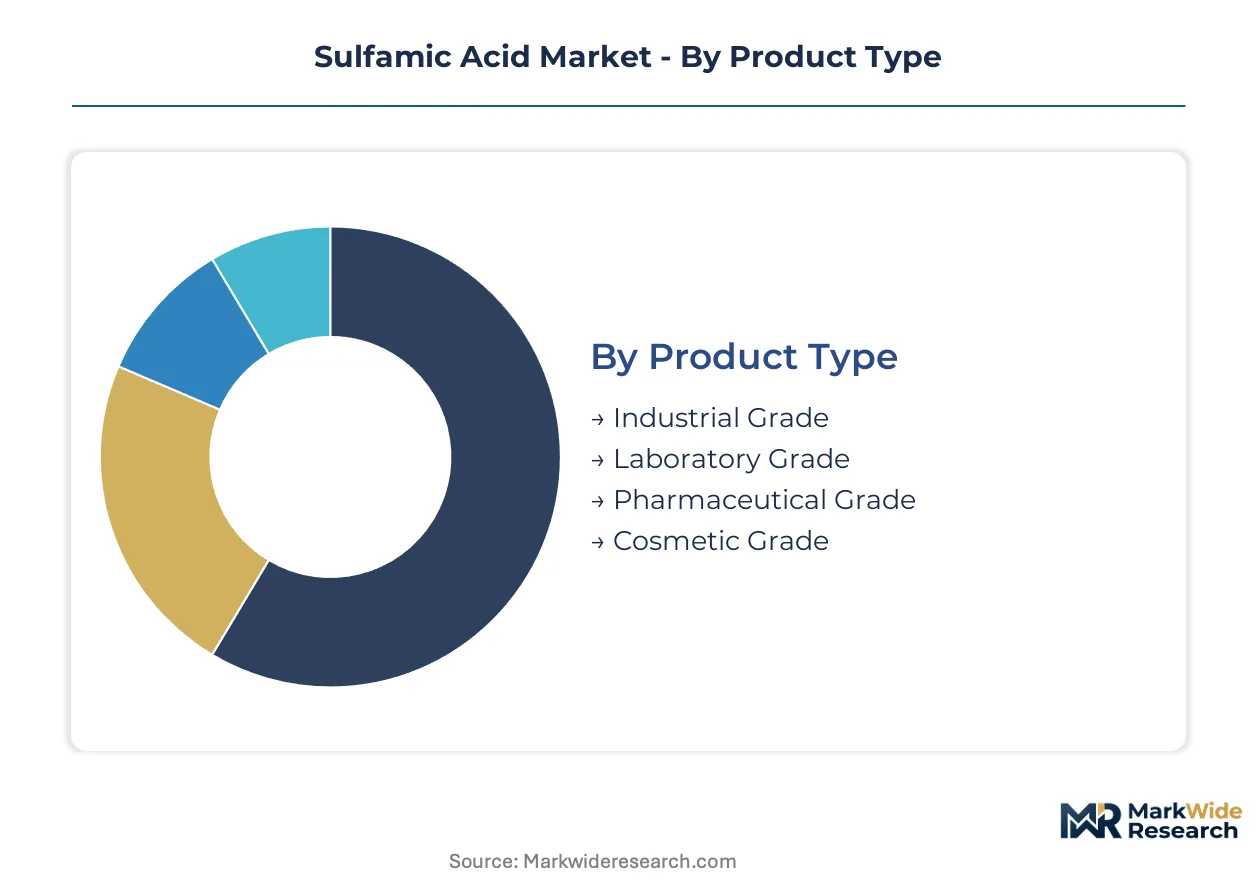
Sulfamic acid producers calibrate purification investments and certification protocols against discrete margin tiers that separate commodity industrial volumes from premium laboratory and pharmaceutical grades. Specification divergence across product categories directly shapes capital allocation decisions for membrane-based purification upgrades and multi-jurisdiction compliance documentation.
Product Type:
Margin pools concentrate sharply in certified grades where pharmacopeia compliance and analytical documentation command substantial premia over commodity industrial volumes.
- Industrial Grade:This segment comprises standard-purity formulations with residual heavy-metal thresholds adequate for descaling and metal cleaning applications. Municipal water authorities in Germany and industrial degreaser manufacturers across China absorb the bulk of volume, though EPA and REACH purity evolution is compressing the specification gap with higher grades.
- Laboratory Grade:Chromatography-verified purity with full substance identity documentation down to 0.1% concentration thresholds distinguishes this tier. REACH-registered producers in Japan and Germany are locking in audited supplier relationships ahead of authorization deadlines, capturing margin expansion through certification scarcity.
- Pharmaceutical Grade:Pharmacopeia-compliant excipient specifications for oral dosage manufacturing. CDSCO and FDA validation requirements extend registration timelines but open preferential procurement channels with innovator drug manufacturers.
- Cosmetic Grade:Refined purity standards aligned with EU cosmetic regulation heavy-metal limits and preservative system compatibility. Formulators in France and Germany specify this grade for acidic pH adjustment in rinse-off products.
The dominant share belongs to Industrial Grade, while Laboratory Grade is closing the gap fastest.
Application:
Volume concentration patterns diverge between mature textile offtake and rapidly expanding chemical intermediate demand driven by selective sulfonation chemistry.
- Cleaning Agents:Metal degreasers, concrete removers, and industrial surface preparation formulations rely on sulfamic acid's non-volatile solid form for safer handling than liquid mineral acids. Asian manufacturing clusters in Shandong province feed scaled output into this segment, though hydrochloric acid substitution caps penetration at legacy industrial sites with existing liquid acid infrastructure.
- Water Treatment:Descaling compounds for cooling towers, boilers, and municipal distribution systems dominate this application. Infrastructure upgrades across India's Smart Cities Mission secondary urban centers and Germany's municipal utility cooperatives are pulling higher-purity formulations into bulk tender specifications.
- Chemical Intermediates:Selective sulfonating agent demand from dyestuff, sweetener, and pharmaceutical precursor synthesis. Continuous-flow reactor adoption in Japan and Germany is compressing cycle times for mid-scale producers serving this segment.
- Textile Processing:Mature application for pH control and desizing operations with stable offtake patterns. Mills in China and India maintain consistent procurement volumes without significant specification escalation.
Cleaning Agents retains the largest volume position, though Chemical Intermediates is expanding most quickly.
End User:
Procurement power concentrates among large-scale chemical manufacturers and municipal water authorities with specification-driven framework agreements displacing spot-market purchasing.
- Chemical Manufacturers:Integrated sulfonation operations and cleaning-agent formulators with captive acid consumption or toll manufacturing arrangements. Shandong Mingda Chemical Technology Co. and comparable scaled producers serve this tier through direct supply contracts with volume-tiered pricing.
- Pharmaceuticals:Innovator and generic drug manufacturers requiring excipient-grade acid with full ICH Q3D elemental impurity documentation. Multi-jurisdiction certification timelines of 18-24 months favor incumbent suppliers with established pharmacopeia filings.
- Cosmetics:Formulation houses and contract manufacturers serving EU and North American markets with cosmetic-grade specifications. REACH and EU cosmetic regulation compliance documentation requirements shape supplier qualification protocols.
- Water Treatment Facilities:Municipal utilities and industrial cooling system operators with tightening heavy-metal thresholds under evolving EPA and GB standards. North Rhine-Westphalia's regional purchasing cooperatives exemplify consolidated buyer power in this segment.
Chemical Manufacturers command the dominant procurement volume, while Pharmaceuticals is gaining share fastest.
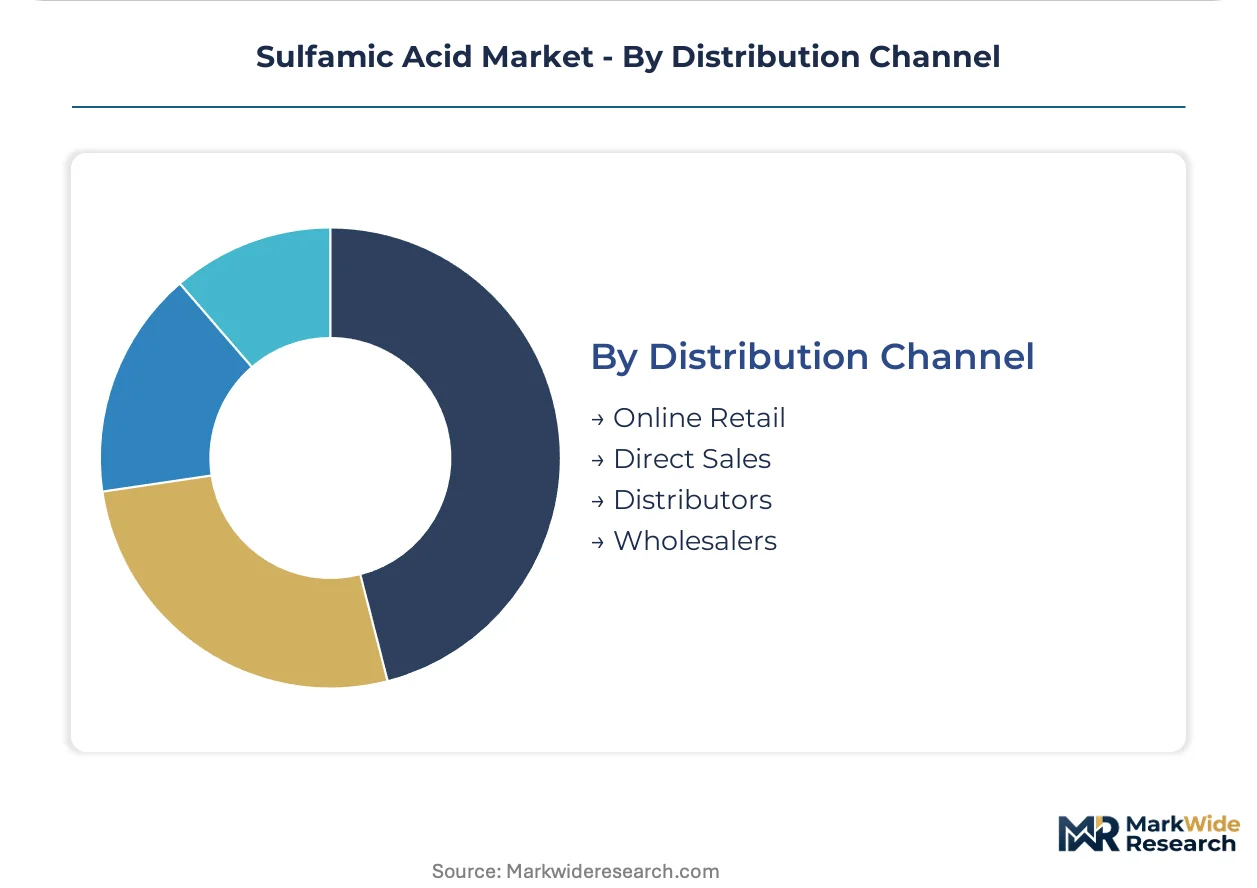
Distribution Channel:
Channel economics reflect the tension between specification-intensive direct relationships for certified grades and cost-efficient indirect coverage for commodity industrial volumes.
- Direct Sales:Long-term framework agreements with fixed purity tiers dominate municipal water authority and large chemical manufacturer procurement. BASF SE leverages its integrated European production network to sustain supply security through direct channels for industrial-grade buyers.
- Distributors:Specialty chemical distributors with REACH registration support and analytical documentation capabilities serve mid-scale laboratory and pharmaceutical-grade buyers. Inventory positioning in Rotterdam and Singapore hubs reduces lead times for Asian and European customers.
- Online Retail:E-commerce platforms with certified hazardous materials logistics capabilities capture small-volume laboratory and research-grade demand. Limited to sub-tonnage quantities with full SDS and substance identity documentation.
- Wholesalers:Regional bulk chemical wholesalers with blending and repackaging infrastructure serve cleaning-agent manufacturers and smaller water treatment operators. Price competition intensifies in this channel as Shandong supply concentration creates margin pressure.
Direct Sales holds the dominant channel position, while Distributors is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water authorities and industrial cleaning-agent manufacturers concentrate procurement power across Germany, China, India, and the United States. Specification-driven framework agreements now displace spot-market purchasing in these buyer archetypes. Each geography imposes distinct purity thresholds that reshape supplier qualification protocols.
Germany
North Rhine-Westphalia's regional water utility purchasing cooperatives consolidate bulk tender specifications for descaling compounds. REACH authorization deadlines for substances of very high concern tighten supply chain due diligence obligations to 0.1% concentration thresholds. BASF SE leverages its integrated European production network from Ludwigshafen to sustain supply security for industrial-grade buyers under evolving ECHA frameworks.
China
Shandong province's scaled chemical manufacturers feed Asian cleaning-agent producers with cost-optimized industrial-grade output. SAMR enforces GB standards for industrial chemical purity that directly shape export eligibility for domestic manufacturers. Qingdao and Weifang production clusters face analytical chemist shortages for chromatography-verified documentation required by inland manufacturing zones.
India
Smart Cities Mission infrastructure investments open bulk tender opportunities for water treatment chemical suppliers in secondary urban centers like Indore and Coimbatore. CDSCO validation requirements for pharmaceutical-grade applications extend registration timelines but open preferential procurement channels with generic drug manufacturers. Gujarat's chemical manufacturing belt anchors domestic supply for both industrial and excipient-grade demand.
United States
EPA's revised residual heavy-metal thresholds accelerate descaling agent procurement from municipal water authorities in California and Texas. Municipal infrastructure upgrades across the Southwest pull higher-purity formulations into cooling tower and boiler treatment specifications. DuPont's historical presence in industrial chemical distribution shapes procurement patterns for mid-Atlantic water treatment operators.
Japan
Specialized laboratory-grade manufacturing from Kanto-region producers serves chromatography-verified purity demand across Asia-Pacific research institutions. METI standards for chemical substance management complement REACH-aligned documentation protocols for export-oriented suppliers. Nissan Chemical Corporation anchors high-specification output from Tokyo-area facilities for selective sulfonation chemistry applications.
Sulfamic Acid Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive urea feedstock positions and regional specialists with scaled batch operations. Three archetypes dominate: European REACH-registered producers with full analytical documentation capabilities, Chinese cost-optimized manufacturers with Shandong production gravity, and Japanese laboratory-grade specialists with continuous-flow reactor technology. Competitive moves center on membrane-based purification system upgrades and multi-jurisdiction certification investments that extend product launch cycles.
Among European-registered conglomerates, BASF SE exemplifies the integrated archetype with supply security positioning across industrial-grade segments. Shandong Mingda Chemical Technology Co., Ltd and Laizhou Jinxing Chemical Co., Ltd occupy the scale-driven tier with regional cost structures serving Asian cleaning-agent producers. Nissan Chemical Corporation represents the specialization archetype with laboratory-grade manufacturing capabilities from Japanese facilities. These three company types collectively illustrate the market's structural segmentation between certification-intensive premium tiers and volume-optimized commodity supply.
| Leading Market Players |
|---|
| BASF SE |
| Nissan Chemical Corporation |
| DuPont |
| AkzoNobel N.V. |
| Shandong Mingda Chemical Technology Co., Ltd |
| Laizhou Jinxing Chemical Co., Ltd. |
| Yantai Sanding Chemical Co., Ltd. |
| Palm Commodities International, LLC |
| Raviraj Group |
| Others |
Value Chain & Pricing Dynamics
Long-term framework agreements with fixed purity tiers lock in supply access for municipal water authorities and industrial cleaning-agent manufacturers while anchoring price visibility across volatile urea feedstock cycles. Shandong province's production gravity concentrates bargaining power among scaled Chinese manufacturers serving Asian commodity demand, whereas REACH-registered European producers extract certification premia from laboratory-grade buyers.
Pricing Analysis
Cost-plus contracts indexed to urea futures dominate industrial-grade transactions, with nitrogen fertilizer price swings passing through to downstream descaling compound manufacturers. Three-tier pricing structure across pharmaceutical, laboratory, and industrial grades separates margin pools by certification intensity and analytical documentation burden. Pricing pressure stems from hydrochloric acid substitution in legacy industrial sites with existing liquid acid handling infrastructure. Chemical manufacturers exhibit highest price sensitivity due to volume-tiered procurement and toll manufacturing arrangements, while pharmaceutical innovators accept substantial premia for pharmacopeia-compliant excipient documentation.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for laboratory-grade producers sourcing chromatography-verified materials from Japanese Kanto-region facilities. Manufacturing concentrates in China, Germany, and India, with Shandong province anchoring scaled industrial-grade output and Gujarat's chemical belt serving domestic Indian pharmaceutical demand. Feedstock dependencies on urea, sulfur trioxide, and membrane purification chemicals expose producers to fertilizer market volatility and specialty equipment lead times. Single-source vulnerability concentrates in Shandong's regional production clusters, where inland analytical chemist shortages constrain GB standards compliance documentation. Distribution runs through direct sales channels for municipal framework agreements and specialty chemical distributors for mid-scale certified-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification divergence across purity grades fragments procurement power and creates service-layer niches where incumbents under-invest in analytical documentation support.
For Market Incumbents: Consolidate supply security through backward integration into captive urea feedstock positions or membrane purification system upgrades that lock in heavy-metal specification compliance ahead of evolving EPA thresholds. BASF SE's integrated European network exemplifies defensive positioning against Shandong supply concentration risks. Certification investment in pharmacopeia documentation extends product launch cycles but deepens switching costs for pharmaceutical-grade buyers. For New Entrants and Emerging Players: Analytical documentation service gaps in China's inland manufacturing zones present white-space opportunities for chromatography-verified laboratory-grade supply with full substance identity protocols. India's Smart Cities Mission secondary urban centers offer the most penetrable geography for bulk water treatment tenders. Go-to-market execution should anchor on CDSCO validation partnerships that compress registration timelines for generic drug manufacturers seeking excipient-grade acid. For Investors and Strategic Acquirers: Capital is best deployed toward laboratory-grade specialists with established REACH registration and continuous-flow reactor technology that compresses cycle times for selective sulfonation chemistry applications. Long-term viability hinges on multi-jurisdiction certification capabilities spanning EPA, REACH, and SAMR frameworks. The inflection signal to monitor is authorization deadline compliance for substances of very high concern, which will consolidate audited supplier relationships ahead of regulatory cutoffs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Urea Feedstock | Captive nitrogen supply insulates margin predictability against fertilizer price volatility from Yara and CF Industries pricing. |
| Membrane Purification System Upgrade | Heavy-metal specification compliance meets tightening EPA residual thresholds for California municipal water authorities. |
| Pharmacopeia Certification Investment | CDSCO and FDA validation opens preferential procurement channels with Indian generic drug manufacturers. |
| Continuous-Flow Reactor Adoption | Cycle time compression improves lot-to-lot consistency for Japanese selective sulfonation chemistry applications. |
| REACH-Registered Distribution Partnership | Rotterdam and Singapore hub positioning reduces lead times for European and Asian laboratory-grade buyers. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at Shandong and Gujarat production facilities, procurement leads at German municipal water cooperatives, distribution channel partners in Rotterdam and Singapore, and technical R&D directors at Japanese laboratory-grade manufacturers, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and SAMR GB standards documentation. Bottom-up volume estimates from individual production facilities were triangulated with top-down demand aggregation across application segments.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling rather than single-point extrapolation. Forecast inputs incorporated urea feedstock price correlation coefficients and membrane purification technology adoption curves.
Material uncertainties — urea futures volatility, REACH authorization timeline slippage, and analytical chemist availability in China's inland zones — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory evolution and infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Sodium Bicarbonate Market