
 Global Ammonium Chloride Market | 2026-2036
Global Ammonium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ammonium Chloride Market Foresight
Consolidation among Chinese fertilizer distributors is repositioning procurement leverage toward integrated suppliers. Jiangsu Debang Chemical Industry Group Co. Ltd. leverages its chlor-alkaki integration to control feedstock costs across agricultural and industrial grades. BASF SE anchors European supply through REACH-certified pharmaceutical-grade production. Dallas Group of America Inc. competes on metalwork applications with specialized particle-size distribution capabilities.
Ammonium chloride is an inorganic salt with the formula NH₄Cl, typically produced via the Solvay process or as a byproduct of sodium carbonate manufacturing, with purity grades ranging from agricultural-grade to pharmaceutical-grade exceeding 99.5% assay. Its primary industrial purpose spans nitrogen fertilization, fluxing in galvanizing baths, electrolyte formulation for dry-cell batteries, and expectorant synthesis in drug manufacturing. Agricultural Grade dominates volume flows due to sustained fertilizer consumption across rice-cultivating regions, while Pharmaceutical Grade captures disproportionate margin pools given stringent USP and EP certification requirements. Metalwork applications within the Application dimension are gaining traction as galvanizing output rises in automotive and construction supply chains.
EPA standards for fertilizer runoff shape agricultural-grade product specifications in the United States, while ECHA's REACH framework governs impurity thresholds for industrial and pharmaceutical grades across Europe. China's MEE enforces wastewater discharge limits on chlor-alkali co-producers, directly affecting ammonium chloride yield economics. India's FSSAI and CDSCO maintain separate purity protocols for food-grade and pharmaceutical-grade imports. Stakeholders must monitor evolving battery-electrolyte purity standards as dry-cell manufacturers assess alternative chemistries.
Market Dynamics
Chlor-alkali co-production economics in China's Shandong province are compressing agricultural-grade margins while REACH-certified pharmaceutical material commands price premiums in European battery and drug formulations.
Growth Catalysts
- India's PLI scheme for agrochemicals:Domestic fertilizer producers are expanding offtake commitments under production-linked incentive frameworks, redirecting procurement toward integrated chlor-alkali suppliers.
- Battery-grade purity specifications:Dry-cell manufacturers are tightening electrolyte impurity thresholds, pulling pharmaceutical-grade ammonium chloride into industrial applications previously served by technical grades.
- Galvanizing bath expansion:Automotive and construction metalwork output is rising across East Asian supply chains, amplifying flux consumption in continuous hot-dip coating lines.
Market Restraints
- Feedstock cost volatility:Natural gas and salt brine input swings destabilize Solvay process economics for non-integrated producers lacking captive alkali supply.
- Shandong supply concentration:Chlor-alkali cluster dominance creates single-geography disruption risk for global agricultural-grade volume flows.
- REACH compliance friction:ECHA's tightening impurity documentation requirements extend certification timelines for European pharmaceutical-grade exports.
Strategic Opportunities
- Brazilian fertilizer deficit:Underpenetrated direct-application markets in Mato Grosso soybean belts offer volume expansion for agricultural-grade exporters with port logistics control.
- Food-grade certification convergence:India's FSSAI protocols for edible salt substitutes are creating dual-use pathways for purified ammonium chloride in processed food formulations.
- Carbon capture integration:Solvay process CO₂ utilization is converging with cement plant flue-gas streams, enabling carbon-negative production claims in EU Green Deal alignment.
Industry Challenges
- Pharmaceutical-grade assay validation:USP and EP certification timelines stretch 18-24 months, freezing capacity allocation decisions for multi-grade producers.
- Legacy wastewater infrastructure:China's MEE discharge limits require chlor-alkali co-producers to retrofit treatment systems, compressing yield economics for mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ammonium Chloride Market |
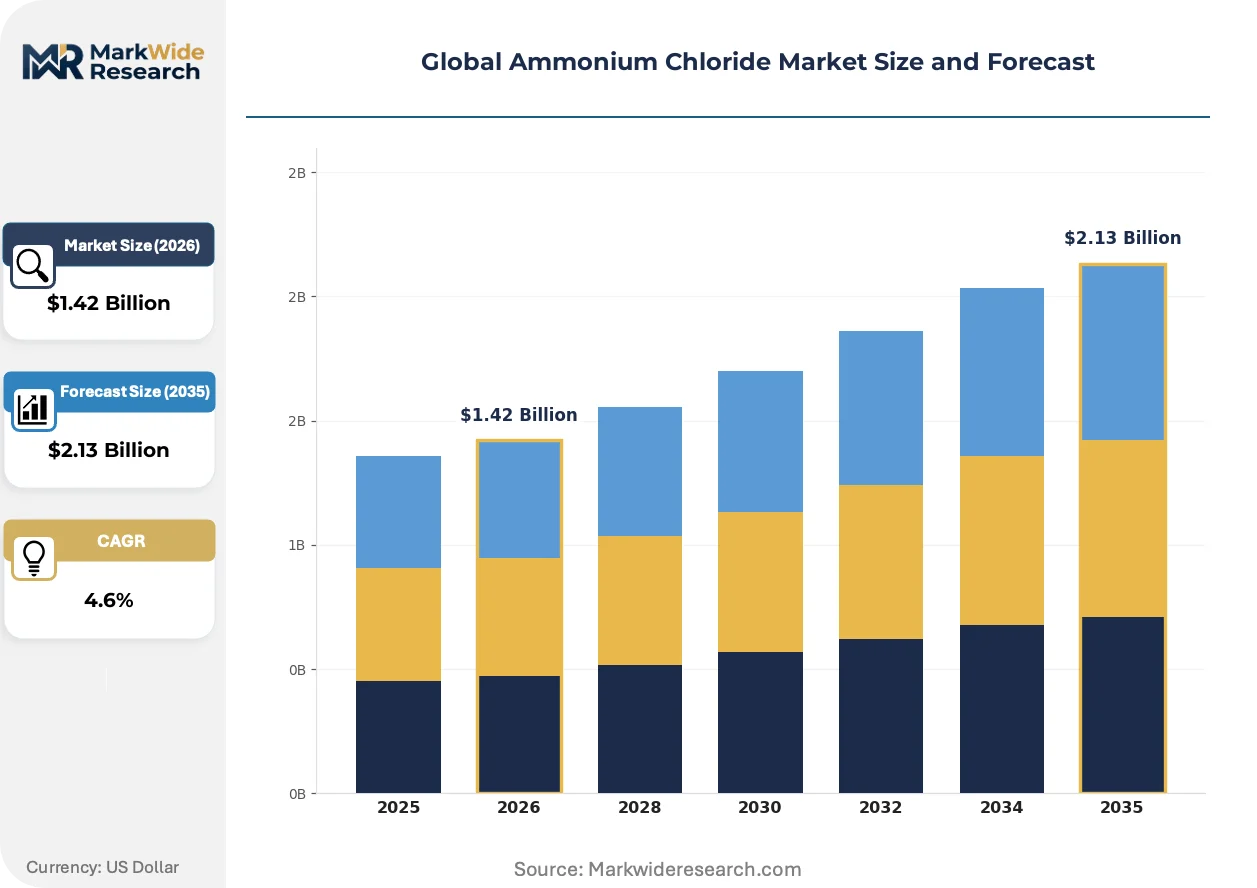
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Agricultural Grade Application: Metalwork, Batteries, Textiles, Leather Processing, Pharmaceuticals End User Industry: Metal Fabricators, Battery Manufacturers, Textile Producers, Tannery Units, Drug Manufacturers Packaging Type: Bag, Drum, Jumbo Bag, Bulk Container |
| Companies Covered | Jiangsu Debang Chemical Industry Group Co. Ltd., Tuticorin Alkali Chemicals and Fertilizers Ltd, BASF SE, Apollo Fertilizer, Zaclon LLC, Central Glass Co. Ltd., Dallas Group of America Inc., Mosaic Company, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ammonium Chloride Market Shifts & Advancements
Purification technology advances are bifurcating the competitive landscape between commodity agricultural supply and certified industrial grades, while regulatory chemistry mandates reshape end-use specifications.
Crystallization control systems are converging with in-line spectroscopic monitoring to enable real-time purity adjustment during Solvay process output. Pharmaceutical and battery-grade buyers in Germany and Japan are adopting these systems fastest, compressing batch-to-batch variation below 0.1% assay deviation. This precision is converging with automated packaging lines to eliminate manual handling contamination risks in high-value segments.
REACH Annex XVII restrictions on heavy metal impurities are tightening maximum allowable lead and cadmium thresholds in battery-grade material. European dry-cell manufacturers are reformulating electrolyte blends to accommodate these limits, forcing upstream ammonium chloride refiners to install ion-exchange polishing stages. The compliance burden falls heaviest on technical-grade producers lacking existing pharmaceutical infrastructure.
Consolidation among Indian fertilizer distributors is compressing procurement decision cycles from annual to quarterly contracting. Integrated chlor-alkali suppliers with captive ammonium chloride output are displacing merchant traders in Punjab and Haryana rice-belt supply chains. This concentration is most visible in states where state agricultural departments have centralized input subsidy distribution through fewer licensed offtakers.
Global Ammonium Chloride Market Segmentation
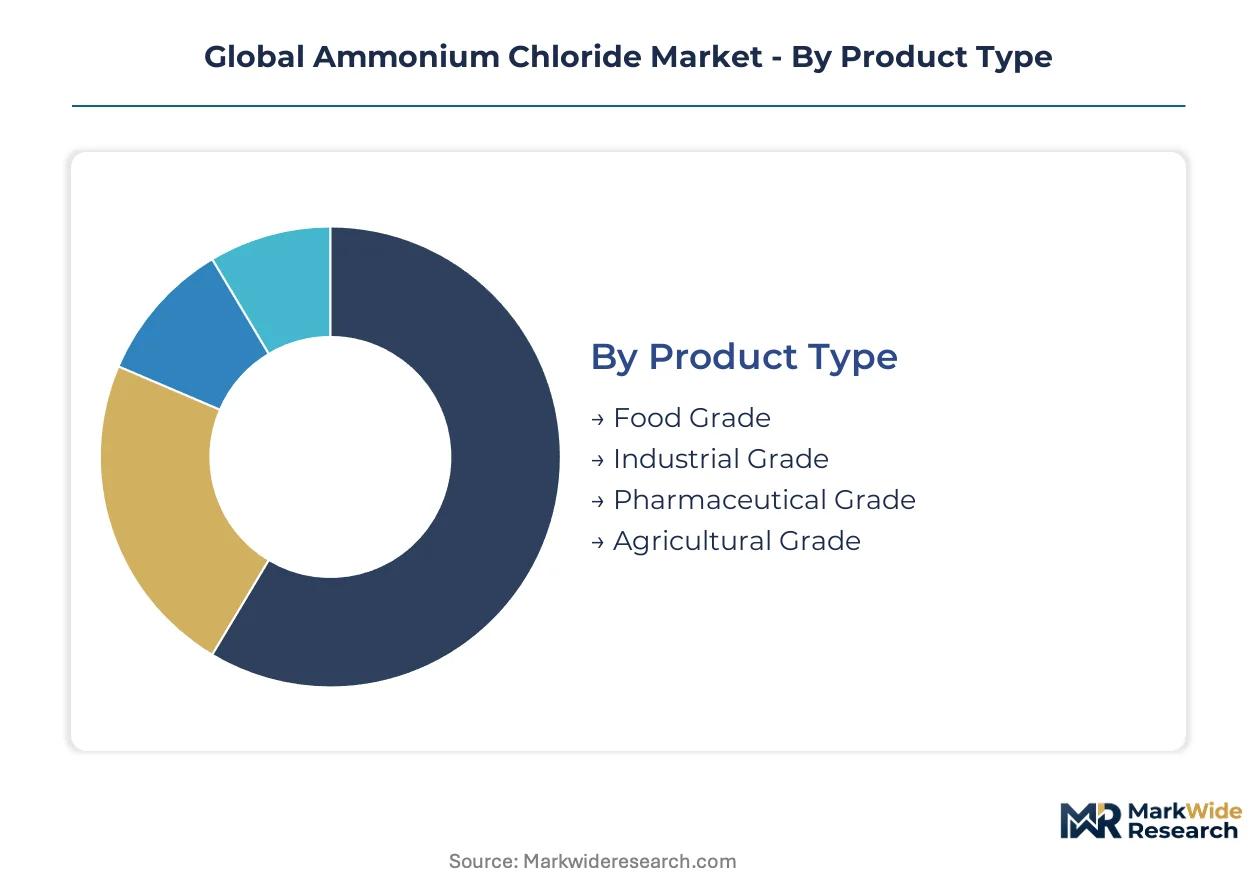
Grade certification tiers determine procurement economics across ammonium chloride applications, with purity thresholds separating commodity fertilizer flows from premium pharmaceutical and battery-electrolyte markets. Segmentation discipline reveals how chlor-alkali producers allocate capacity between margin-dilute agricultural volumes and REACH-certified industrial grades.
Product Type:
Buyer procurement decisions pivot on purity specifications and certification burden, with agricultural buyers prioritizing cost-per-nitrogen-unit while industrial purchasers demand assay documentation.
- Agricultural Grade:Contains 24-25% nitrogen content with tolerance for trace contaminants acceptable in fertilizer blending. Demand concentrates in India's Punjab and Haryana rice belts where state subsidy programs channel procurement through consolidated distributor networks.
- Pharmaceutical Grade:Exceeds 99.5% assay with USP and EP certification requirements governing heavy metal limits below 10 ppm. Battery manufacturers in Germany and Japan are pulling this grade into electrolyte formulations as REACH Annex XVII tightens impurity thresholds for cadmium and lead.
- Industrial Grade:Technical specifications serve metalwork fluxing and textile dyeing applications with moderate purity requirements. Chinese chlor-alkali clusters in Shandong province dominate merchant supply to East Asian galvanizing operations.
- Food Grade:FSSAI-compliant material for edible salt substitutes and processed food formulations. India's regulatory convergence between food and pharmaceutical standards is creating dual-use certification pathways for purified material.
Volume sits with Agricultural Grade; growth tilts toward Pharmaceutical Grade.
Application:
End-use performance requirements reshape supply chain configuration, with continuous-process manufacturers demanding batch-to-batch consistency unavailable from commodity merchants.
- Metalwork:Fluxing applications in continuous hot-dip galvanizing lines require controlled particle-size distribution to prevent bath contamination. Automotive and construction metalwork expansion across East Asia is amplifying consumption in coating line electrolyte maintenance.
- Batteries:Dry-cell electrolyte formulation demands sub-0.1% assay deviation achievable through crystallization control systems with in-line spectroscopic monitoring. Japanese and German manufacturers are adopting these precision systems fastest.
- Pharmaceuticals:Expectorant synthesis and diagnostic reagent production require pharmaceutical-grade material with 18-24 month certification timelines freezing capacity allocation decisions.
- Textiles:Dye-fixing and flame-retardant applications utilize industrial-grade material with less stringent purity protocols than battery or drug formulations.
- Leather Processing:Tanning bath pH adjustment consumes technical-grade volumes with procurement decisions driven by delivered cost rather than certification documentation.
Metalwork commands current volume leadership; battery applications are climbing the fastest.
End User Industry:
Customer concentration patterns determine pricing leverage, with fragmented tannery and textile sectors facing margin compression against integrated chlor-alkali suppliers.
- Battery Manufacturers:Dry-cell producers in Japan and Germany are consolidating supplier bases around REACH-certified refiners capable of ion-exchange polishing for heavy metal removal.
- Drug Manufacturers:Formulation specialists require locked supply agreements with 24-month forward visibility given USP validation timelines.
- Metal Fabricators:Continuous galvanizing lines in automotive supply chains specify particle-size distribution tolerances that disqualify agricultural-grade merchants.
- Textile Producers:Dye-house operators in Bangladesh and Vietnam purchase industrial-grade material through regional traders with limited backward integration.
- Tannery Units:Leather processors in Pakistan and Ethiopia represent price-sensitive demand with minimal specification enforcement.
Procurement consolidation favors Battery Manufacturers and Drug Manufacturers; Tannery Units face steepest supplier attrition.
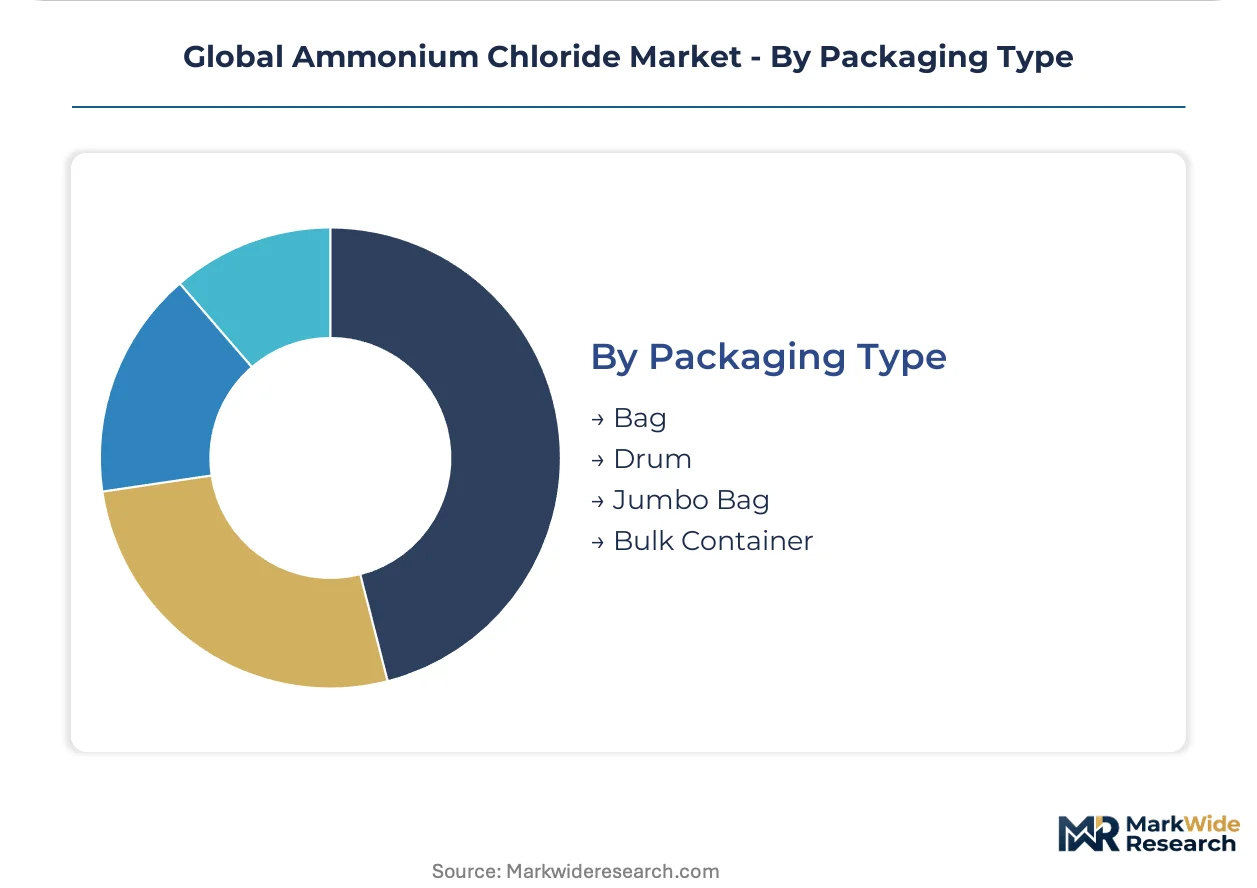
Packaging Type:
Logistics economics and contamination risk shape format selection, with high-value segments demanding sealed systems incompatible with bulk agricultural handling.
- Bag:25-50 kg woven polypropylene serves agricultural distribution through Indian state fertilizer depots and Southeast Asian rice-belt cooperatives.
- Jumbo Bag:One-tonne flexible intermediate bulk containers reduce handling costs for textile and leather processors with intermediate volume requirements.
- Drum:Sealed steel or fiber containers with nitrogen blanket protect pharmaceutical-grade material from moisture absorption during 18-24 month certification storage.
- Bulk Container:ISO tank and flexitank formats serve chlor-alkali integrated producers with captive downstream consumption, eliminating packaging cost for internal transfers.
Agricultural channels favor Bag and Jumbo Bag formats; Pharmaceutical and Battery segments are displacing toward Drum and specialized sealed systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salt brine deposits in China's Shandong province anchor global ammonium chloride production economics, with chlor-alkali clusters supplying downstream processors across agricultural and industrial grades. Regional demand patterns diverge between fertilizer-intensive rice belts and REACH-certified pharmaceutical markets.
China
Shandong province chlor-alkali co-producers dominate agricultural-grade volume through Solvay process integration with captive soda ash output. MEE wastewater discharge limits are compressing yield economics for mid-scale facilities lacking retrofit capital. Qingdao and Weifang chemical parks concentrate capacity serving both domestic fertilizer blenders and export-oriented battery-grade refiners.
India
Punjab and Haryana rice belts drive agricultural-grade consumption through state subsidy programs channeling procurement via consolidated distributor networks. PLI scheme incentives for agrochemicals are redirecting offtake toward integrated chlor-alkali suppliers with captive ammonium chloride output. Gujarat chlor-alkali corridors supply pharmaceutical-grade material meeting CDSCO and FSSAI dual-certification requirements.
Germany
REACH Annex XVII compliance is tightening heavy metal thresholds for battery-grade imports, pulling pharmaceutical-grade material into dry-cell electrolyte formulations. Ludwigshafen chemical complexes anchor European supply through ECHA-certified production infrastructure. Bavarian and North Rhine-Westphalia industrial zones concentrate demand from automotive galvanizing lines specifying controlled particle-size distribution.
United States
EPA fertilizer runoff standards shape agricultural-grade specifications for rice cultivation in Arkansas and Louisiana delta regions. Dallas Group of America Inc. occupies metalwork fluxing segments with specialized distribution capabilities. Midwest chlor-alkali producers face feedstock cost volatility from natural gas price swings destabilizing non-integrated Solvay economics.
Brazil
Mato Grosso soybean belts present underpenetrated direct-application opportunities for agricultural-grade exporters controlling port logistics through Santos and Paranaguá terminals. ANVISA pharmaceutical regulations create certification barriers for battery-grade imports, preserving market segmentation. São Paulo state fertilizer distributors are consolidating procurement leverage toward integrated suppliers with backward alkali control.
Global Ammonium Chloride Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-negative production claims and food-grade certification convergence. The vendor base stratifies across three archetypes: integrated chlor-alkali conglomerates with captive feedstock, pharmaceutical-grade specialists with locked USP validation timelines, and regional fertilizer merchants facing distributor consolidation pressure. Competitive moves center on M&A for port logistics control and capacity expansion into REACH-certified battery-grade refining.
Within the integrated conglomerate tier, Jiangsu Debang Chemical Industry Group Co. Ltd. exemplifies chlor-alkaki integration anchoring feedstock cost control across multiple purity grades. BASF SE occupies the pharmaceutical-grade specialist position through REACH-certified European production infrastructure. Dallas Group of America Inc. represents the regional metalwork-focused archetype with specialized particle-size distribution capabilities for galvanizing applications.
| Leading Market Players |
|---|
| Jiangsu Debang Chemical Industry Group Co. Ltd. |
| Tuticorin Alkali Chemicals and Fertilizers Ltd |
| BASF SE |
| Apollo Fertilizer |
| Zaclon LLC |
| Central Glass Co. Ltd. |
| Dallas Group of America Inc. |
| Mosaic Company |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
State fertilizer subsidy programs in India and consolidated distributor networks in China's Shandong province anchor procurement leverage, compressing agricultural-grade ammonium chloride toward spot-indexed contracts while pharmaceutical-grade material commands fixed-price premiums tied to USP certification timelines.
Pricing Analysis
Volume-mass agricultural flows trade near production cost while margin-rich pharmaceutical grades capture certification scarcity premiums. Three-tier pricing structure across pharmaceutical, industrial, and agricultural levels reflects purity thresholds and documentation burden. Cost compression in agricultural grades intensifies as Shandong chlor-alkali clusters flood spot markets with Solvay process co-product. State procurement officers in Punjab and Haryana exhibit highest price sensitivity; Japanese battery manufacturers show lowest sensitivity given electrolyte purity requirements.
Supply Chain Analysis
Single-source vulnerability sits with China's Shandong province, where chlor-alkali cluster dominance concentrates 60-70% of global agricultural-grade merchant supply. Production draws from salt brine deposits, natural gas feedstock, and captive soda ash integration. Tariff exposure looms for European battery-grade importers as REACH Annex XVII documentation requirements extend customs clearance timelines. Distribution runs through state fertilizer depots in India, integrated chlor-alkali direct sales in East Asia, and specialty chemical distributors for pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a crystallization-technology transition phase, with in-line spectroscopic monitoring systems displacing legacy batch-based purity testing across German and Japanese pharmaceutical-grade supply chains.
For Market Incumbents: Acquire port logistics assets in Brazil's Santos and Paranaguá terminals to secure agricultural-grade export channels into Mato Grosso soybean belts. Retrofit ion-exchange polishing capacity to capture REACH-certified battery-grade demand as dry-cell manufacturers consolidate supplier bases. Backward integration into captive salt brine sourcing defends margin position against natural gas volatility in non-integrated Solvay operations. For New Entrants and Emerging Players: Regional fertilizer distributors in Brazil's underpenetrated Mato Grosso region offer channel partnership pathways for agricultural-grade exporters with logistics control. Carbon-negative production claims through Solvay process CO₂ utilization convergence with cement plant flue-gas streams create differentiation in EU Green Deal-aligned procurement. Target food-grade certification convergence in India, where FSSAI protocols for edible salt substitutes open dual-use pathways for purified material. For Investors and Strategic Acquirers: The window for entry favors integrated chlor-alkali conglomerates with captive feedstock and multi-grade certification infrastructure. Long-term viability hinges on locked supply agreements with 24-month forward visibility given USP validation timelines. Watch battery-electrolyte purity standard tightening as the inflection signal for pharmaceutical-grade capacity reallocation into industrial applications.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Shandong chemical parks add pharmaceutical-grade refining lines to capture REACH-certified battery demand from German manufacturers. |
| Backward Integration | Captive salt brine sourcing in Gujarat chlor-alkali corridors secures feedstock cost control for Indian PLI scheme fertilizer supply. |
| Green Manufacturing Transition | Solvay process CO₂ utilization with cement plant flue-gas streams enables carbon-negative production claims for EU Green Deal alignment. |
| Long-term Supply Agreement | Locked contracts with Japanese dry-cell manufacturers provide 24-month forward visibility through USP certification timelines. |
| Joint Venture | Partnerships with Brazilian port operators in Santos and Paranaguá secure agricultural-grade export logistics into Mato Grosso soybean belts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving chlor-alkali plant managers, fertilizer procurement leads at Indian state agricultural departments, battery-grade buyers at Japanese dry-cell manufacturers, and REACH compliance officers at German pharmaceutical refiners. ECHA Annex XVII documentation, CDSCO pharmaceutical-grade import records, and MEE wastewater discharge permits supplemented bottom-up capacity modeling. Top-down demand validation triangulated against customs export flows and state subsidy distribution data.
Granularity-level modeling distinguished pharmaceutical, industrial, agricultural, and food-grade tiers across application segments including metalwork fluxing, battery electrolyte formulation, fertilizer blending, and processed food formulations. Value projections across the analysis window derived from price-premium differentials between certification grades and volume-weighted average realization rates. Forecast inputs incorporated PLI scheme offtake commitments, REACH Annex XVII heavy metal threshold tightening, and galvanizing bath expansion in East Asian automotive supply chains.
Caveats apply where MEE wastewater retrofit mandates, natural gas feedstock volatility, or alternative battery chemistry adoption could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline stability and subsidy program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Cyclohexane Market