
 Magnesium Citrate Market | 2026-2036
Magnesium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Citrate Market Foresight
Buyer concentration among pharmaceutical contract manufacturers is restructuring procurement patterns for magnesium citrate active pharmaceutical ingredients. Jungbunzlauer leverages its Swiss fermentation expertise to supply citrate precursors with documented supply chain transparency. Dr. Paul Lohmann anchors German production of pharma-grade magnesium compounds through dedicated GMP facilities. Cargill Inc. competes across food and pharmaceutical-grade segments with integrated citric acid manufacturing.
Magnesium citrate is a magnesium salt of citric acid, typically prepared by neutralizing citric acid with magnesium carbonate or hydroxide to yield a compound containing approximately 16% elemental magnesium by weight. The substance functions primarily as an osmotic laxative, antacid, and bioavailable magnesium supplement in pharmaceutical and nutraceutical applications. Powder formulations dominate bulk ingredient shipments to pharmaceutical compounders, while liquid preparations lead consumer-facing laxative products through pharmacy and hospital channels. Dietary supplements represent the fastest-expanding application segment, driven by magnesium deficiency awareness and sports nutrition demand. Pharmaceutical applications sustain the highest margin pools due to USP-grade certification requirements and prescriber-driven volume.
FDA enforces USP monograph compliance for magnesium citrate drug products, while EMA oversees EP-grade certification for European market access. ISO 22000 and FSSC 22000 standards govern food-additive applications, creating parallel compliance pathways for multi-segment suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as divergence in heavy metal limits and hydration specifications threatens cross-border formulation consistency.
Market Dynamics
Pharmaceutical-grade magnesium citrate supply is consolidating around GMP-certified fermentation and chemical synthesis clusters, tightening access for non-integrated compounders and reshaping procurement toward long-term offtake agreements with qualified manufacturers.
Growth Catalysts
- USP Monograph Harmonization:FDA enforcement of updated heavy metal and hydration specifications is elevating certified supplier premiums and locking in compliant producers.
- Sports Nutrition Formulation:Powder magnesium citrate is displacing oxide and sulfate salts in pre-workout and recovery blends due to superior bioavailability.
- German Production Cluster:Specialized GMP infrastructure in Lower Saxony and Bavaria is anchoring European pharmaceutical-grade supply security.
Market Restraints
- Citric Acid Feedstock Volatility:Molasses and dextrose price swings from Brazilian sugarcane harvests transmit directly to magnesium citrate production costs.
- Chinese Supply Concentration:Over half of global citric acid precursor output originates from Shandong and Jiangsu provinces, creating single-geography risk.
- Magnesium Oxide Substitution:Lower-cost magnesium oxide retains share in antacid and supplement applications where bioavailability is secondary to price.
Strategic Opportunities
- Indian Nutraceutical Expansion:FSSAI's streamlined health supplement regulations and PLI scheme incentives are opening formulation manufacturing for export.
- Direct-to-Consumer Liquid Formats:Ready-to-drink magnesium citrate beverages are bypassing pharmacy distribution through subscription wellness platforms.
- REACH-Compliant Green Chemistry:ECHA pressure on solvent-intensive processes is rewarding fermentation-based citrate producers with preferential supplier status.
Industry Challenges
- Pharmacopeial Divergence Management:USP, EP, and JP monograph inconsistencies on hydration states and assay methods force multi-standard inventory and testing redundancy.
- Specialized Fermentation Talent Scarcity:GMP-scale citric acid bioprocess engineering expertise concentrates at Jungbunzlauer and select German facilities, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Citrate Market |
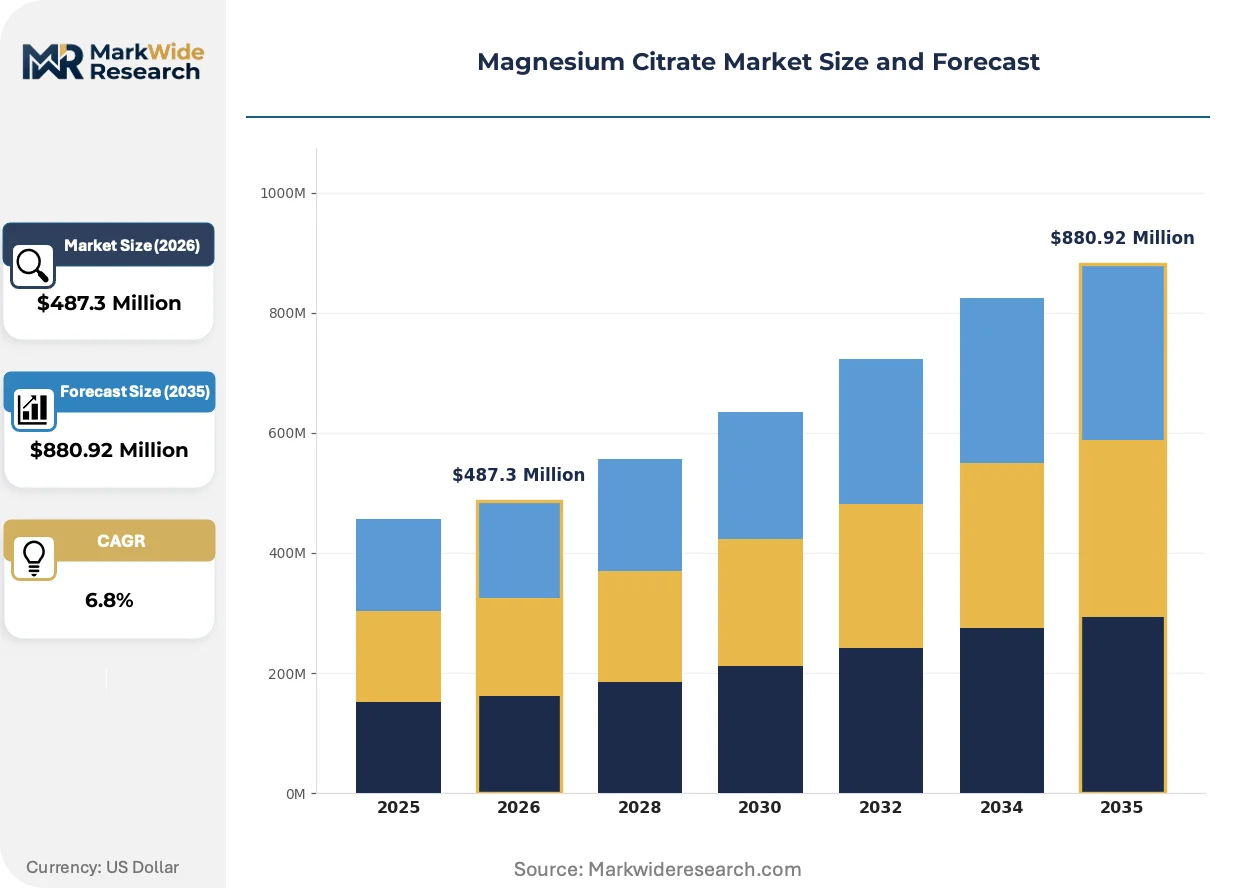
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Chewable Tablet End User: Households, Pharmacies, Health Clubs, Hospitals Distribution Channel: Online Retail, Supermarkets, Drug Stores, Specialty Stores Application: Dietary Supplements, Pharmaceuticals, Food Additives, Cosmetics |
| Companies Covered | Cargill Inc., Dr. Paul Lohmann, Jungbunzlauer, Sucroal, Archer Daniels Midland Company, Global Calcium, Tate & Lyle PLC, Shandong Juxian Hongde Citric Acid Co. Ltd., Gadot Biochemical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Citrate Market Shifts & Advancements
Continuous manufacturing and real-time release testing are compressing batch cycle times for pharmaceutical-grade magnesium citrate, while regulatory data integrity requirements are digitizing quality documentation across the supply chain.
Continuous flow chemistry for citrate salt synthesis is consolidating batch pharmaceutical production into integrated manufacturing trains. Contract manufacturers in Germany and Switzerland are adopting these systems to reduce solvent waste and accelerate USP-grade batch release. This compression is squeezing traditional stirred-tank compounders out of high-margin prescription laxative supply.
EMA's updated excipient risk assessment guidelines are forcing magnesium citrate suppliers to document nitrosamine and elemental impurity profiles beyond current EP monographs. Pharmaceutical formulators must now qualify suppliers on extended toxicological data packages. European generic drug manufacturers are responding by dual-sourcing from REACH-registered producers with dedicated GMP lines.
Sports nutrition brands are compressing supplier rosters from multi-source commodity buying to single-qualified partnerships with fermentation-traceable magnesium citrate producers. This consolidation prioritizes lot-level carbon footprint documentation and clean-label positioning over spot-price optimization. North American direct-to-consumer supplement brands are driving this shift most aggressively.
Magnesium Citrate Market Segmentation
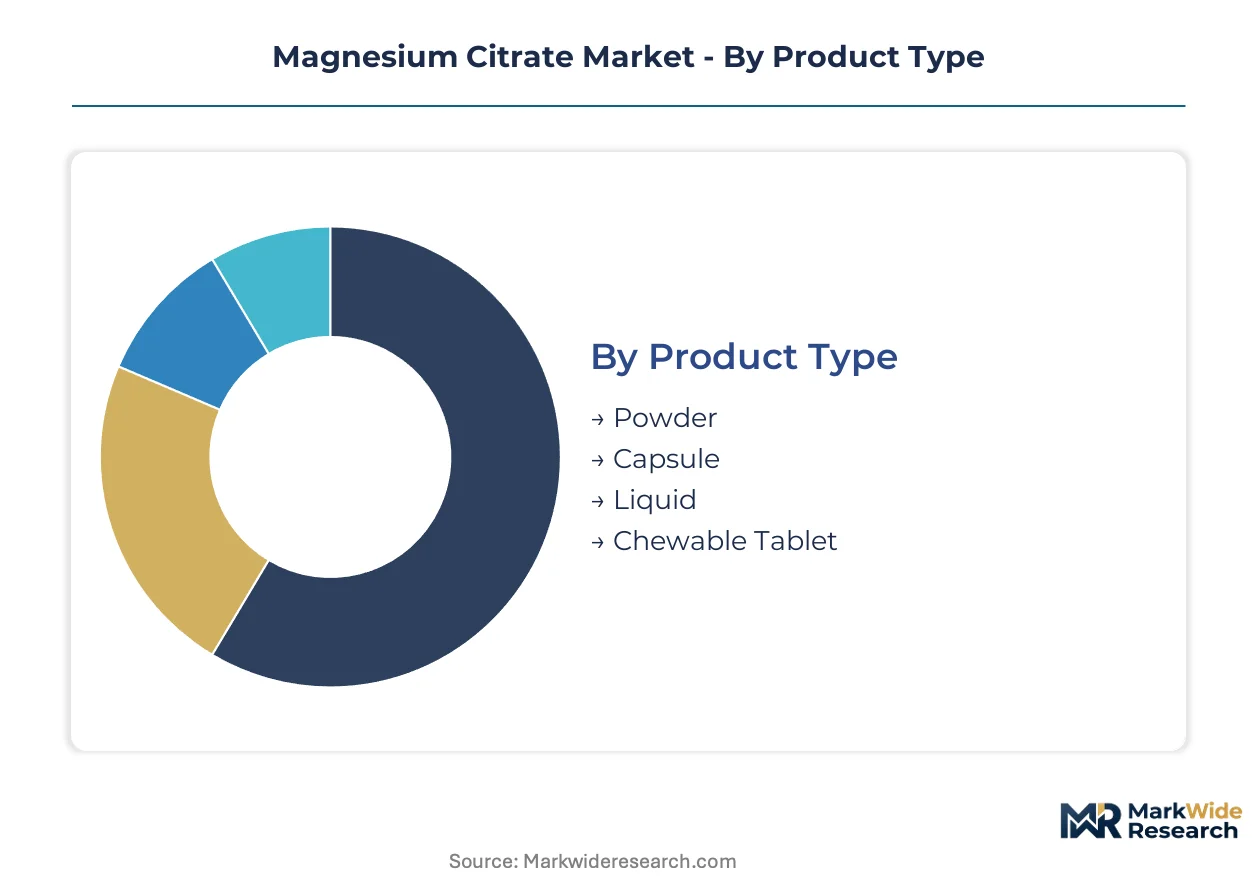
Magnesium citrate segmentation reflects divergent certification burdens across pharmaceutical, food, and cosmetic pathways. Product form and distribution channel selection directly determines which USP, EP, or FSSC 22000 standards apply, locking suppliers into compliance-specific customer pools.
Product Type:
USP-grade powder carries the heaviest certification burden for pharmaceutical compounders, while liquid and chewable formats face FDA drug product regulations plus state pharmacy board oversight.
- Powder:Bulk pharmaceutical ingredient supplying compounding pharmacies and contract manufacturers. Demand concentrates in Germany and Switzerland where Jungbunzlauer and Dr. Paul Lohmann maintain GMP fermentation lines for citrate precursors. FDA USP monograph compliance for elemental magnesium assay and heavy metal limits sustains premium positioning over food-grade alternatives.
- Liquid:Ready-to-dose osmotic laxative requiring FDA drug product approval and child-resistant packaging compliance. North American pharmacy chains and hospital formularies drive volume through prescriber-driven bowel preparation protocols. EMA's updated excipient risk guidelines now demand nitrosamine impurity documentation beyond baseline EP standards.
- Capsule:Dietary supplement format governed by FDA 21 CFR 101 labeling and cGMP manufacturing rules. Sports nutrition brands in the United States source capsule-grade powder from FSSC 22000-certified suppliers for direct-to-consumer subscription models.
- Chewable Tablet:Palatability-focused delivery for pediatric and geriatric populations. Manufacturing requires excipient compatibility testing and stability validation under ICH Q1A guidelines.
Leading the category by volume: Powder. Growing fastest: Liquid.
End User:
Procurement authority and specification power vary sharply across end-user categories, with hospitals and pharmacies dictating pharmaceutical-grade standards that households and health clubs rarely trigger.
- Pharmacies:Primary channel for prescription laxative and high-dose supplement dispensing. German pharmacy chains anchor European demand through mandatory pharmacist consultation requirements that reinforce USP-grade sourcing.
- Hospitals:Institutional purchasing of bowel preparation kits for colonoscopy protocols. GPO contracting in the United States concentrates volume with suppliers holding FDA drug master files and verified nitrosamine-free certifications.
- Households:Direct and retail-acquired consumption for routine magnesium supplementation. Amazon and subscription wellness platforms disintermediate traditional pharmacy distribution for powder and capsule formats.
- Health Clubs:Sports nutrition retail and on-premise recovery product sales. Pre-workout formulation demand favors bioavailable citrate salts over oxide alternatives for muscle function positioning.
Pharmacies dominate procurement value. Health clubs are climbing the fastest as sports nutrition penetration deepens.
Distribution Channel:
Channel selection determines regulatory exposure depth, with drug stores triggering full pharmaceutical compliance and online retail enabling cross-border complexity.
- Drug Stores:CVS, Walgreens, and Rite Aid in the United States enforce supplier qualification programs exceeding baseline FDA requirements. Shelf placement for laxative products demands documented USP-grade certification and lot-level traceability.
- Online Retail:Amazon, iHerb, and brand-direct subscription platforms bypass pharmacy distribution. FSSAI-registered Indian exporters access North American consumers through this channel despite lacking traditional wholesale drug distribution relationships.
- Supermarkets:Mass-market supplement placement governed by FDA dietary supplement regulations and retailer-specific quality audits. Costco and Walmart require third-party GMP certification and heavy metal testing documentation.
- Specialty Stores:Independent health food retailers and practitioner-exclusive channels. Practitioner-grade positioning demands transparent supply chain documentation and fermentation-origin verification for clean-label differentiation.
Drug stores anchor pharmaceutical-grade volume. Online retail is expanding most quickly as direct-to-consumer brands bypass traditional wholesale.
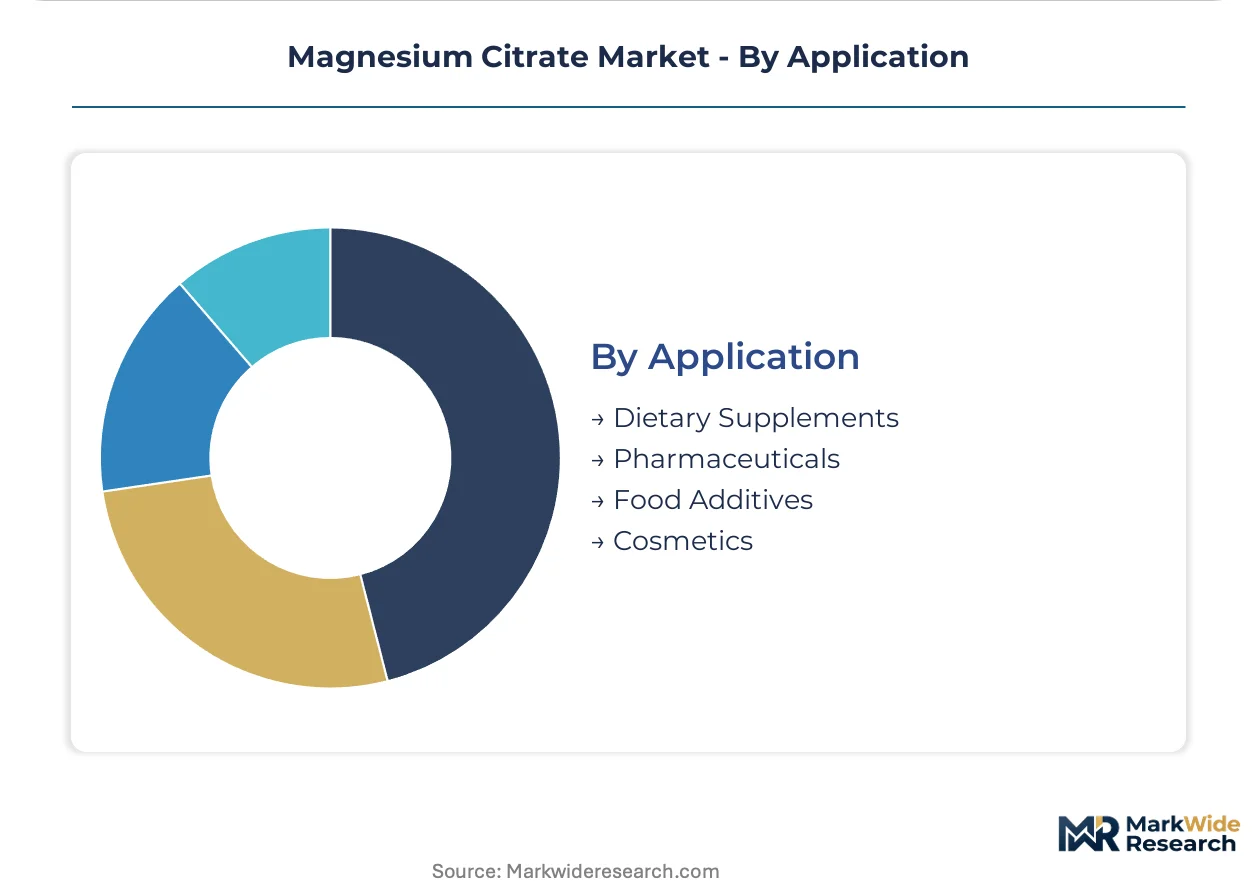
Application:
Application-driven segmentation separates margin pools, with pharmaceutical applications commanding steepest certification premiums and food additives operating under parallel but less stringent safety frameworks.
- Pharmaceuticals:Osmotic laxative and antacid applications requiring USP or EP monograph compliance. FDA enforcement of updated heavy metal specifications is elevating certified supplier premiums and locking in compliant producers like Jungbunzlauer and Dr. Paul Lohmann.
- Dietary Supplements:Fastest-expanding segment driven by magnesium deficiency awareness and sports nutrition formulation. Powder magnesium citrate is displacing oxide and sulfate salts in pre-workout blends due to superior bioavailability.
- Food Additives:Fortification applications in beverages and functional foods governed by FDA GRAS and EFSA food additive regulations. ISO 22000 certification enables multi-segment suppliers to serve food and pharmaceutical customers from shared fermentation assets.
- Cosmetics:Topical magnesium products and personal care formulations. Cosmetic-grade specifications lack pharmacopeial harmonization, creating regional fragmentation in purity standards.
Pharmaceuticals lead by margin contribution. Dietary supplements are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade magnesium citrate procurement concentrates in Germany, where GMP-certified fermentation infrastructure anchors European supply security. Sports nutrition brands in the United States drive powder demand through direct-to-consumer channels. Chinese citric acid precursor output supplies cost-sensitive food additive applications worldwide.
Germany
Dr. Paul Lohmann and Jungbunzlauer sustain pharmaceutical-grade magnesium compound production through dedicated Lower Saxony and Bavaria facilities. EMA oversight of EP monograph compliance elevates certified supplier premiums above food-grade alternatives. The German pharmacy chain network reinforces USP-grade sourcing through mandatory pharmacist consultation requirements.
United States
CVS, Walgreens, and hospital GPOs concentrate prescription laxative volume with FDA drug master file holders. FDA enforcement of updated USP heavy metal specifications locks in compliant producers and squeezes non-certified compounders. Greater Boston and New Jersey pharmaceutical corridors host contract manufacturers adopting continuous flow chemistry for batch compression.
China
Shandong and Jiangsu provinces generate over half of global citric acid precursor output for magnesium salt synthesis. NMPA alignment with international pharmacopeial standards remains uneven, limiting direct pharmaceutical-grade export penetration. Tianjin and Qingdao chemical clusters supply cost-optimized feedstock to Indian and Southeast Asian compounders.
India
FSSAI's streamlined health supplement regulations and PLI scheme incentives attract formulation manufacturing for North American export. Maharashtra and Gujarat nutraceutical clusters expand encapsulation capacity for sports nutrition brands. CDSCO's evolving active pharmaceutical ingredient registration requirements create compliance friction for imported magnesium citrate.
Switzerland
Swissmedic oversight of excipient quality documentation supports Jungbunzlauer's fermentation-traceable supply chain positioning. Basel and Zurich pharmaceutical service corridors specialize in nitrosamine-free certification packages for European generic drug manufacturers. Swiss franc-denominated production costs limit penetration in price-sensitive food additive segments.
Magnesium Citrate Market Competitive Landscape
German producers anchor the premium pharmaceutical tier; Chinese specialists hold commodity food-grade supply. The market structure bifurcates between GMP-certified fermentation clusters serving regulated drug applications and cost-optimized chemical synthesis operations supplying bulk mineral fortification. Three archetypes dominate: integrated citric acid-magnesium salt manufacturers, dedicated pharma-grade compounders, and regional trading distributors. Capacity expansion and strategic offtake agreements constitute the dominant competitive moves as procurement shifts from spot buying to qualified supplier partnerships.
Within the integrated manufacturing tier, Jungbunzlauer and Dr. Paul Lohmann exemplify fermentation-based supply chain transparency archetypes. Cargill Inc. occupies a position spanning food and pharmaceutical-grade segments through captive citric acid production. These three entities represent contrasting geographic and vertical integration strategies without implying specific market share or technological superiority.
| Leading Market Players |
|---|
| Cargill Inc. |
| Dr. Paul Lohmann |
| Jungbunzlauer |
| Sucroal |
| Archer Daniels Midland Company |
| Global Calcium |
| Tate & Lyle PLC |
| Shandong Juxian Hongde Citric Acid Co. Ltd. |
| Gadot Biochemical Industries |
| Others |
Supply & Pricing Matrix
Hospital GPOs and pharmacy chain procurement offices concentrate buying power for USP-grade magnesium citrate, enforcing contract-based long-term offtake agreements that compress spot-market premiums and lock in qualified suppliers. This buyer concentration rewards Jungbunzlauer and Dr. Paul Lohmann with pricing power while squeezing non-certified compounders toward commodity food-grade segments.
Pricing Analysis
Volume concentrates in food-grade powder shipments to Indian and Chinese compounders, while margins pool in pharmaceutical-grade supply to German and Swiss GMP facilities. Certification grade and fermentation-origin traceability drive price differentiation, with USP monograph compliance commanding substantial premiums over FSSC 22000 alternatives. Cost compression in standard-grade supply stems from Chinese citric acid feedstock volatility. Hospital procurement teams show lowest price sensitivity due to colonoscopy protocol compliance requirements, while direct-to-consumer subscription brands negotiate aggressively on capsule-grade powder.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European pharmaceutical-grade fulfillment, with hub-and-spoke patterns radiating to German pharmacy chains and Swiss contract manufacturers. Supply concentrates in China for citric acid precursors, Germany for GMP magnesium salt synthesis, and India for encapsulation and formulation. Production rests on molasses and dextrose feedstocks, magnesium carbonate or hydroxide reagents, and specialized fermentation equipment. Single-source vulnerability runs through Shandong citric acid clusters exposed to Brazilian sugarcane harvest swings. Distribution runs through qualified supplier partnerships rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around GMP-certified fermentation infrastructure, with FDA and EMA pharmacopeial divergence forcing sub-scale compounders toward exit or acquisition. Regulatory compliance burdens are accelerating this consolidation play.
For Market Incumbents: Deploy nitrosamine-free certification packages as a defensive moat against emerging Indian nutraceutical compounders. Secure backward integration into citric acid fermentation through offtake agreements with Brazilian dextrose suppliers, insulating against feedstock volatility that threatens margin stability. Lock in hospital GPO contracts with documented heavy metal compliance to preempt substitution by lower-cost oxide salts. For New Entrants and Emerging Players: Begin with direct-to-consumer liquid magnesium citrate beverages targeting North American subscription wellness platforms, the most penetrable channel bypassing pharmacy distribution barriers. Exploit FSSAI-registered Indian export pathways to access Amazon and iHerb without traditional wholesale drug relationships. Anchor initial positioning on clean-label fermentation traceability rather than price competition with established GMP suppliers. For Investors and Strategic Acquirers: The window for entry favors fermentation-traceable mid-cap specialists with existing REACH registration and dedicated GMP lines. Long-term viability hinges on pharmacopeial harmonization enforcement tightening over the next decade. Target acquisition archetypes: German or Swiss compounders with nitrosamine-free documentation and hospital formulary relationships. Watch EMA excipient risk assessment guideline updates as the signal for accelerated supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in citric acid feedstock from Brazilian dextrose producers ahead of harvest volatility. |
| GMP Certification Investment | Opens hospital GPO contracting channels requiring FDA drug master file documentation. |
| Backward Integration | Captures fermentation capacity for citrate precursors, securing supply chain transparency. |
| Direct-to-Consumer Launch | Bypasses pharmacy distribution through subscription wellness platforms for liquid formats. |
| Regulatory Harmonization Monitoring | Anticipates USP-EP-JP convergence to reduce multi-standard inventory redundancy costs. |
Research Methodology
Multi-period observation of USP monograph enforcement patterns, citric acid feedstock pricing, and hospital GPO contracting volumes anchored the trend analysis, supplemented by interviews with pharmaceutical procurement directors, GMP facility managers, regulatory affairs specialists, and sports nutrition brand formulators. Secondary validation drew from FDA warning letters, EMA excipient guidelines, SEC filings of citric acid producers, and customs trade data for magnesium salt imports. Bottom-up demand modeling across dosage forms and end-use segments was cross-checked against top-down market sizing from fermentation capacity assessments.
Segment-weighting applied differential growth assumptions across pharmaceutical, dietary supplement, food additive, and cosmetic applications, with additional granularity by powder, liquid, capsule, and chewable formats. CAGRs were derived from trajectory fitting to historical volume data and elasticity-adjusted demand projections across the analysis window. Forecast inputs incorporated citric acid price volatility indices, GMP certification penetration rates, and direct-to-consumer channel expansion metrics.
Underlying measurement precision varies by segment; pharmaceutical-grade supply carries tighter precision due to documented production volumes and regulatory filings, while cosmetic-grade estimates rely on broader trade data proxies. Forecasts reflect documented assumptions on pharmacopeial harmonization timing and feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Banlangen Granules Market