
 Calcium Diglutamate Market | 2026-2036
Calcium Diglutamate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Diglutamate Market Outlook
Flavor enhancement licensing is rewriting how ingredient suppliers capture value downstream. Ajinomoto Co., Inc. leverages decades of fermentation expertise to anchor premium positioning in food-grade calcium diglutamate. Meihua Holdings Group Co., Ltd. dominates bulk amino acid manufacturing with backward integration into corn-derived feedstock processing. Cargill Incorporated extends its global distribution infrastructure to secure channel control across multiple end-user categories.
Calcium diglutamate is the calcium salt of L-glutamic acid, typically manufactured through controlled fermentation of carbohydrate substrates followed by calcium salt crystallization, yielding a white crystalline powder with enhanced thermal stability compared to monosodium glutamate. It functions primarily as an umami-intensifying flavor enhancer in reduced-sodium food systems and as a calcium fortificant in nutraceutical matrices. The powder form occupies the largest volume share due to its compatibility with dry seasoning blends and extended shelf stability, while the nutraceuticals application records the fastest expansion as supplement brands reformulate around mineral bioavailability claims. Food manufacturers represent the most concentrated end-user margin pool, though pharmaceutical firms are gaining procurement sophistication around excipient-grade specifications.
The FDA's GRAS self-affirmation pathway and EFSA's food additive re-evaluation program shape calcium diglutamate market access and label positioning requirements in North America and Europe. China's SAMR enforces GB standards for food-grade amino acid salts, creating compliance differentiation between domestic and export-oriented producers. Stakeholders must monitor evolving sodium-reduction mandates and their direct translation into calcium-salt substitution timelines across processed food categories.
Market Dynamics
Sodium-reduction mandates from the FDA and EFSA are forcing food manufacturers to reformulate around calcium-based umami salts, redirecting R&D budgets toward mineral salt alternatives that preserve flavor intensity while meeting clean-label requirements.
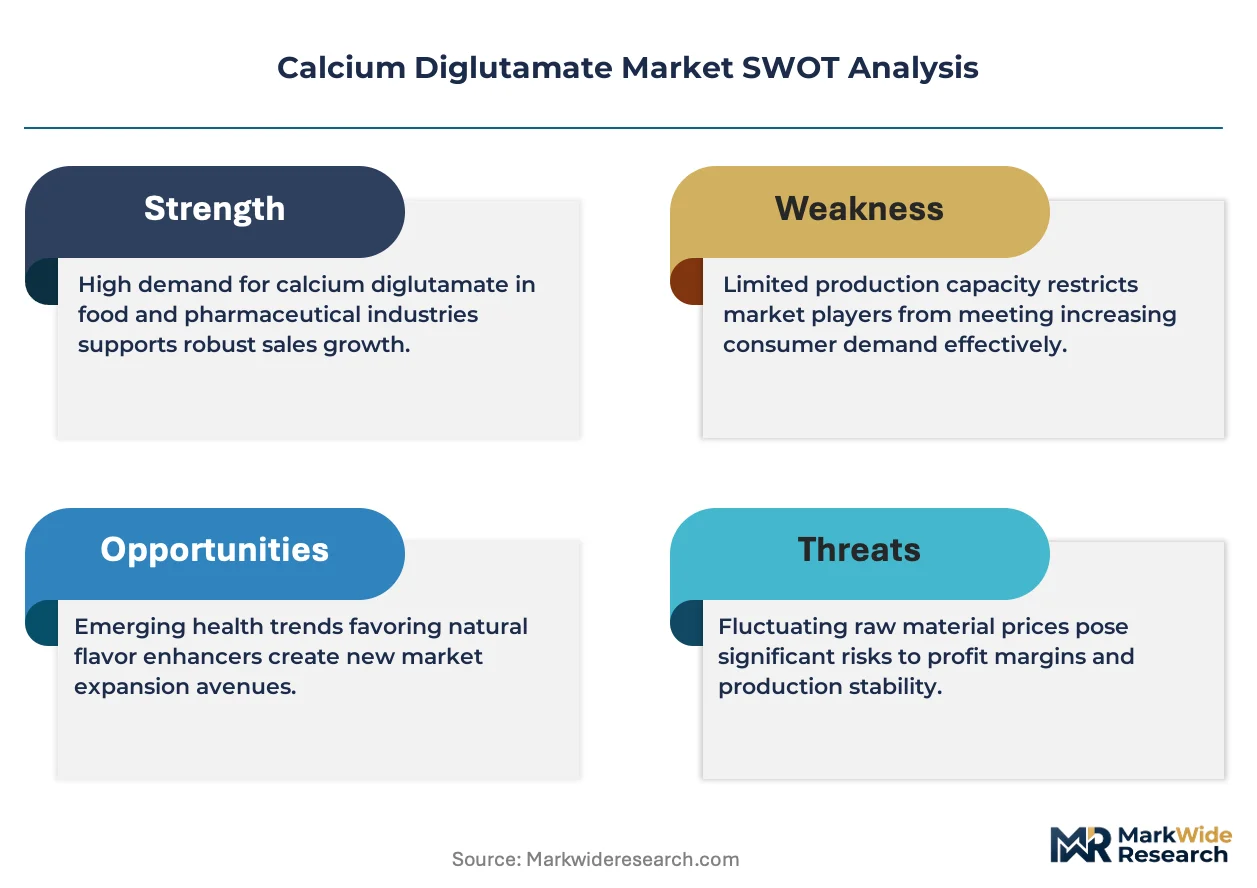
Growth Catalysts
- EFSA additive re-evaluation:The European food safety framework is accelerating calcium diglutamate approvals for reduced-sodium product lines across processed meat and savory snack categories.
- Fermentation process intensification:Continuous bioreactor technologies are cutting production cycle times for L-glutamic acid precursors, lowering unit costs for calcium salt crystallization.
- China:Domestic biotechnology clusters in Shandong and Jiangsu provinces are scaling food-grade amino acid output to supply both local processors and export channels.
Market Restraints
- Corn feedstock volatility:Carbohydrate substrate costs fluctuate with agricultural commodity cycles, squeezing margin predictability for fermentation-based manufacturers.
- Supplier concentration in East Asia:Bulk amino acid production clusters heavily in Chinese coastal provinces, creating geographic risk exposure for Western formulators.
- Technical substitution ceiling:Calcium diglutamate cannot fully replicate sodium glutamate's solubility profile in high-moisture applications, limiting penetration in certain sauce categories.
Strategic Opportunities
- India nutraceutical expansion:FSSAI regulatory clarity on mineral fortification is opening formulation partnerships between calcium salt suppliers and domestic supplement brands.
- Plant-based meat analogues:Clean-label umami enhancement in textured protein systems represents an emerging application vector with limited incumbent penetration.
- US FDA sodium targets:Voluntary industry guidelines for restaurant and packaged food sodium reduction are creating procurement pull for GRAS-affirmed calcium alternatives.
Industry Challenges
- Excipient-grade certification timelines:Pharmaceutical qualification protocols for mineral salt purity are extending customer onboarding cycles beyond standard food-grade timelines.
- Legacy flavor house relationships:Established sodium glutamate supply contracts create switching friction for reformulating manufacturers despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Diglutamate Market |
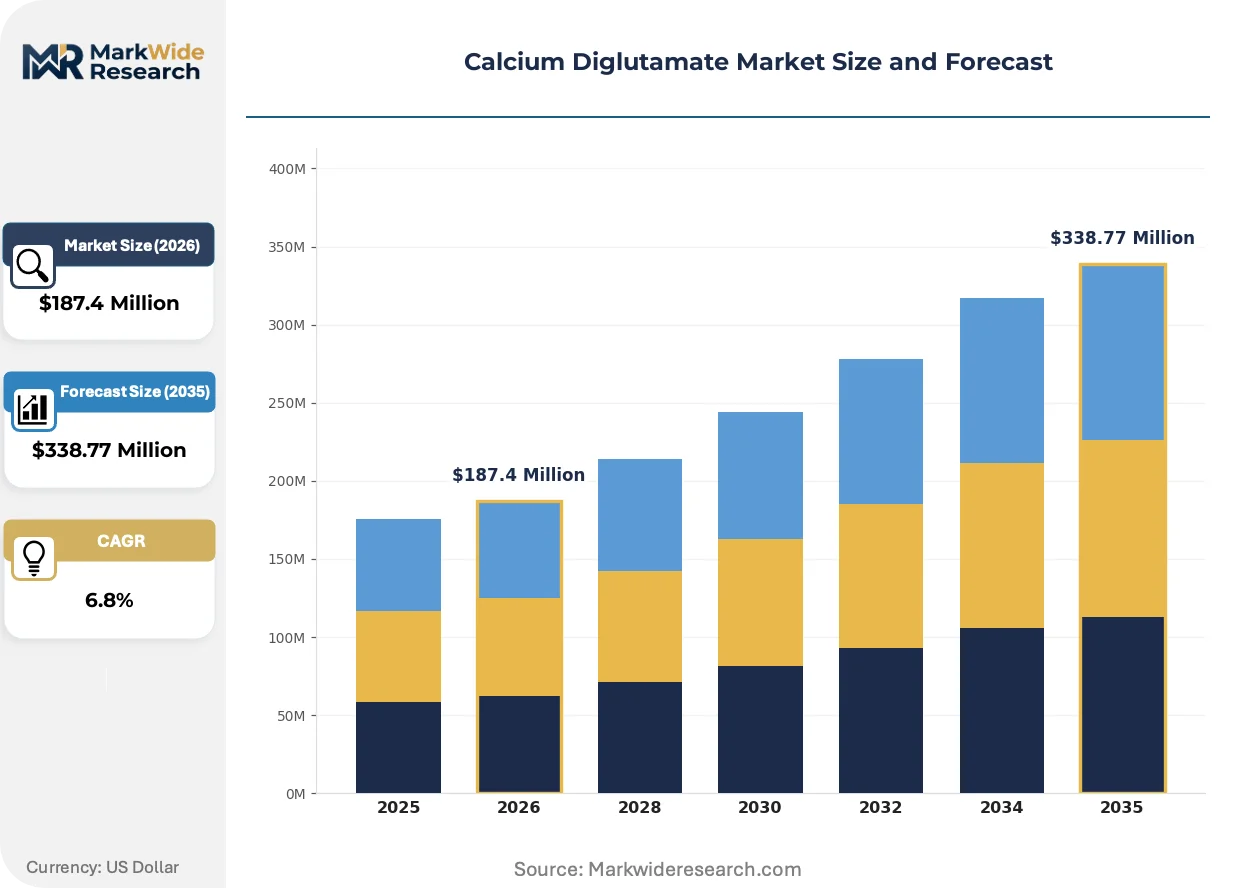
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Liquid, Tablet Application: Food Additive, Nutraceuticals, Pharmaceuticals, Animal Feed End User: Food Manufacturers, Nutraceutical Companies, Pharmaceutical Firms, Livestock Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Ajinomoto Co., Inc., Hangzhou Hikang Biotechnology Co., Ltd., Ningbo Chengyao Fine Chemicals Co., Ltd., COFCO, Ningxia Eppen Biotech Co., Ltd., Meihua Holdings Group Co., Ltd., Gremount International Company Limited, Cargill Incorporated, Shandong Qilu Biotechnology Group Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Diglutamate Market Strategic Shifts
Fermentation process control is digitizing quality assurance protocols, while regulatory frameworks on both sides of the Atlantic harden sodium-reduction requirements. These forces are compressing traditional formulation cycles and elevating mineral salt alternatives in procurement hierarchies.
Precision fermentation monitoring is digitizing calcium diglutamate batch consistency. Food-grade manufacturers are deploying real-time metabolite sensors to optimize L-glutamic acid titer before calcium salt crystallization. This sensor integration is digitizing quality control, reducing batch-to-batch variation that previously required post-hoc laboratory verification.
REACH chemical registration requirements are tightening documentation burdens for amino acid salt imports into the European Union. ECHA substance evaluation protocols now demand extended toxicological dossiers for food-contact applications. Specialty chemical distributors serving EU food manufacturers are absorbing compliance costs through dedicated regulatory affairs staffing.
Clean-label purchasing criteria are compressing supplier evaluation cycles for savory flavor enhancers. North American processed food procurement teams now prioritize mineral salt alternatives with single-ingredient declarations over traditional MSG in reformulation briefs. This specification tightening is most visible in private-label retail channels competing on ingredient transparency.
Calcium Diglutamate Market Segmentation
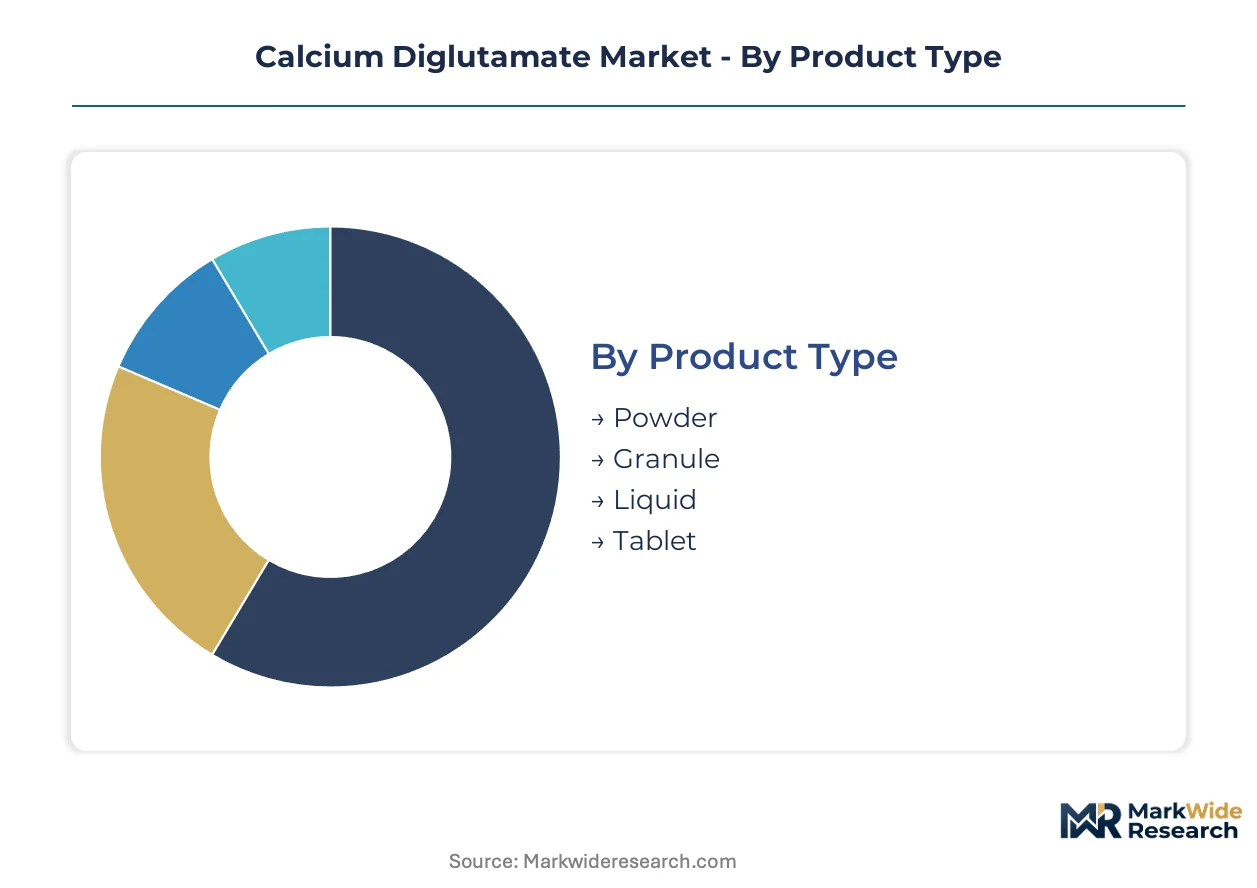
Calcium diglutamate procurement varies sharply by downstream processing requirements. Fermentation-derived specifications differ for dry blending versus liquid injection systems. Each segment demands distinct technical support intensity from suppliers.
Product Type:
After-sales technical service intensity escalates with formulation complexity. Powder and liquid forms require divergent handling protocols and stability guidance.
- Powder:Crystalline white solid produced through controlled calcium salt precipitation from fermented L-glutamic acid broth. Dry seasoning manufacturers in China and Japan specify powder for extended shelf stability in ambient distribution. Food processors value its compatibility with high-shear blending equipment and low moisture sensitivity.
- Liquid:Aqueous solution or suspension requiring pH buffering and microbial stabilization. Beverage fortification and ready-to-drink applications in the US drive procurement, though thermal processing limits challenge high-temperature pasteurization workflows. Technical service teams address solubility optimization and precipitation prevention.
- Granule:Agglomerated form engineered for controlled dissolution in wet mixes. Intermediate processing characteristics suit sauce manufacturers seeking reduced dusting versus powder.
- Tablet:Direct-compression grade with specified disintegration profiles. Nutraceutical brands specify tablet-grade calcium diglutamate for mineral supplement lines targeting bone health positioning.
Powder holds the largest share; momentum sits with liquid as beverage fortification accelerates.
Application:
Cost tier stratification separates commodity food-grade from premium pharmaceutical specifications. Regulatory qualification burden increases steeply up the value chain.
- Food Additive:Umami enhancement in reduced-sodium formulations. EFSA and FDA sodium-reduction mandates redirect savory snack and processed meat R&D budgets toward calcium salt alternatives. Clean-label positioning drives specification upgrades.
- Nutraceuticals:Mineral fortification with bioavailability claims. Supplement brands in India and the US reformulate around calcium diglutamate for dual-function positioning. FSSAI clarity on mineral additives supports domestic Indian partnerships.
- Pharmaceuticals:Excipient-grade specifications for tablet binders and mineral supplements. Extended qualification timelines and pharmacopeial compliance create margin premiums over food-grade material.
- Animal Feed:Palatability enhancement and mineral supplementation for livestock. Price-sensitive procurement with lower purity thresholds versus human-grade applications.
Food additive dominates volume; nutraceuticals climb fastest on supplement premiumization.
End User:
Customer type determines contract structure and technical engagement depth. Pharmaceutical firms demand audited supply chains; livestock producers prioritize spot pricing.
- Food Manufacturers:Integrated savory flavor houses and private-label processors. Procurement teams specify calcium diglutamate for sodium reduction compliance in retail-ready products. Legacy MSG contracts create reformulation friction despite regulatory pressure.
- Nutraceutical Companies:Contract manufacturers and branded supplement firms. Mineral bioavailability claims require certificate-of-analysis documentation and batch traceability.
- Pharmaceutical Firms:Generic drug manufacturers and specialty pharmaceutical companies. Excipient qualification protocols extend onboarding cycles beyond standard food-grade timelines.
- Livestock Producers:Integrated feed mills and agricultural cooperatives. Volume procurement with limited technical service requirements.
Food manufacturers command the largest procurement volume; pharmaceutical firms deliver the steepest margin expansion.
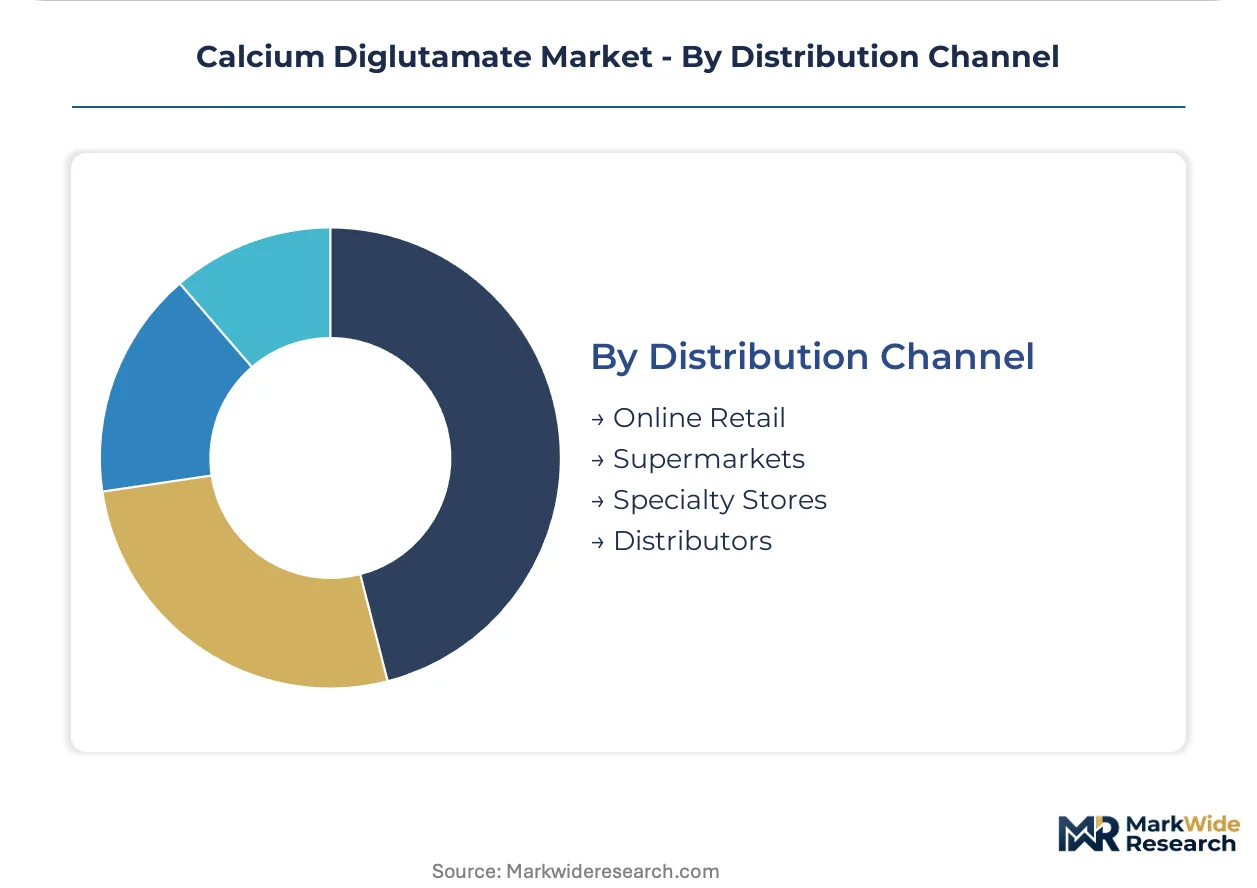
Distribution Channel:
Geographic reach and customer scale dictate channel selection. Bulk industrial buyers bypass retail infrastructure entirely.
- Distributors:Specialty chemical and ingredient distributors serving mid-scale food processors. Technical sales support and inventory financing differentiate regional players.
- Online Retail:E-commerce platforms targeting small-scale nutraceutical formulators and research institutions. Limited volumes with high service expectations.
- Supermarkets:Consumer-facing mineral supplement products. End-product retail rather than ingredient sales.
- Specialty Stores:Health food and professional supplement channels. Niche positioning for premium-grade calcium diglutamate in finished goods.
Distributors anchor industrial volume; online retail gains traction among small-batch formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement markets. Chinese buyers negotiate aggressively on bulk amino acid contracts, while Western pharmaceutical formulators absorb premiums for excipient-grade certification. Japanese and South Korean food manufacturers occupy the middle ground, trading volume commitments for technical service guarantees.
China
Domestic fermentation capacity expansion is outpacing regional demand growth. SAMR's GB standards enforcement differentiates export-grade from domestic-consumption specifications. Shandong and Jiangsu provinces host concentrated biotechnology clusters supplying both local processors and international channels.
United States
FDA voluntary sodium reduction targets for packaged foods and restaurant chains are redirecting savory formulation budgets. GRAS self-affirmation pathways enable faster market entry versus full food additive petitions. Midwestern food processing corridors and California-based clean-label brands drive differentiated procurement requirements.
Japan
Established umami ingredient supply relationships create reformulation friction despite regulatory pressure. METI guidance on processed food sodium content is tightening label claim requirements. Kanto and Kansai industrial belts maintain legacy fermentation infrastructure with incremental capacity upgrades.
Germany
REACH registration documentation burdens are filtering non-EU suppliers from direct market access. EFSA additive re-evaluation timelines are accelerating calcium salt approvals for reduced-meat and savory snack categories. Bavarian and North Rhine-Westphalian food technology clusters import through specialized chemical distributors.
India
FSSAI regulatory clarity on mineral fortification is unlocking nutraceutical partnerships between domestic supplement brands and imported calcium salt suppliers. Price-sensitive procurement dominates food additive applications. Maharashtra and Gujarat-based contract manufacturers are upgrading formulation capabilities for export markets.
Calcium Diglutamate Market Competitive Environment
Fermentation specialists and diversified agricultural processors split the market into distinct capability tiers. Bulk amino acid production concentrates among biotechnology-focused entities with captive carbohydrate feedstock access. Three archetypes dominate: integrated fermentation houses with backward control over corn processing, diversified ingredient distributors leveraging global logistics networks, and regional fine chemical specialists serving pharmaceutical qualification requirements. Capacity expansion and strategic licensing of flavor enhancement protocols represent the dominant competitive moves.
Within the integrated fermentation tier, Meihua Holdings Group Co., Ltd. and Ningxia Eppen Biotech Co., Ltd. exemplify Chinese producers with upstream control over agricultural inputs. Ajinomoto Co., Inc. occupies a position representing decades of specialized amino acid fermentation expertise. These anchors illustrate how geographic concentration in East Asian biotechnology clusters shapes supply availability for Western formulators seeking sodium-reduction alternatives.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Hangzhou Hikang Biotechnology Co., Ltd. |
| Ningbo Chengyao Fine Chemicals Co., Ltd. |
| COFCO |
| Ningxia Eppen Biotech Co., Ltd. |
| Meihua Holdings Group Co., Ltd. |
| Gremount International Company Limited |
| Cargill Incorporated |
| Shandong Qilu Biotechnology Group Co. |
| Others |
Value Chain & Pricing Dynamics
The Qingdao-Shanghai-Ningbo maritime corridor anchors bulk amino acid logistics costs, compressing margins for Shandong-based fermentation houses while amplifying price differentiation between food-grade and excipient-grade calcium diglutamate tiers. Corn feedstock procurement cycles and pharmaceutical certification timelines feed directly into contract pricing structures across Western formulator markets.
Pricing Analysis
After-sales technical service contracts drive lifetime value capture for calcium diglutamate suppliers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates excipient-certified batches from commodity savory applications. Price differentiation centers on pharmacopeial compliance documentation and fermentation titer consistency. Cost compression in food-grade powder runs through corn substrate volatility and Chinese capacity expansion. Livestock producers exhibit highest price sensitivity; pharmaceutical formulators absorb certification premiums.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for Western amino acid salt importers. Bulk L-glutamic acid production concentrates in China, South Korea, and Japan, with crystallization finishing distributed across EU and North American compounding facilities. Corn-derived carbohydrate substrates, calcium carbonate reagents, and fermentation nutrient media anchor input dependencies. Single-source vulnerability in Shandong biotechnology clusters threatens supply continuity for export-oriented customers. Distribution runs through specialty chemical distributors with dedicated regulatory affairs capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation process control expertise and pharmacopeial certification infrastructure represent scarce capabilities that constrain market entry and consolidation trajectories. The gap between food-grade and pharmaceutical-grade production standards creates asymmetric competitive positioning.
For Market Incumbents: Entrench backward integration into corn processing and captive fermentation capacity to defend against substrate cost volatility. Lock in multi-year supply agreements with EFSA-aligned European distributors before additive re-evaluation timelines accelerate. Prioritize excipient-grade certification investments to capture pharmaceutical margin premiums. For New Entrants and Emerging Players: Build out precision fermentation monitoring capabilities to differentiate on batch consistency metrics. Target India's nutraceutical contract manufacturing segment where FSSAI regulatory clarity supports faster market entry than EU REACH registration burdens. Lead with bioavailability documentation partnerships for domestic supplement brands. For Investors and Strategic Acquirers: FDA voluntary sodium reduction targets for packaged foods reshape the acquisition landscape toward mineral salt alternative suppliers with GRAS affirmation infrastructure. Five-to-ten year viability favors integrated fermentation houses with upstream agricultural input control. Monitor EFSA additive re-evaluation completion as signal for European procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Captive carbohydrate feedstock supply insulates Shandong fermentation clusters from agricultural commodity cycles. |
| Excipient-Grade Certification Investment | Pharmacopeial compliance unlocks pharmaceutical tablet binder contracts with extended qualification timelines. |
| Precision Fermentation Monitoring Deployment | Real-time metabolite sensors reduce batch-to-batch variation for clean-label savory applications. |
| EFSA-Aligned Distribution Partnership | Specialized chemical distributors absorb REACH documentation burdens for EU food manufacturer access. |
| India Nutraceutical Formulation Alliance | FSSAI regulatory clarity enables mineral fortification partnerships with domestic supplement brands. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, savory flavor house procurement leads, pharmaceutical excipient qualification specialists, and specialty chemical distribution channel partners. Secondary validation drew from SAMR GB standards filings, EFSA additive re-evaluation dossiers, FDA GRAS affirmation notices, and customs trade flow records. Bottom-up capacity modeling and top-down demand segmentation were triangulated to anchor volume estimates.
Calibration against historical amino acid salt pricing cycles and regulatory approval timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, application grade tier, end-user industry, and regional regulatory cluster. CAGRs were derived from intensity-of-use coefficients in sodium-reduction formulation scenarios and supplement premiumization trajectories. Fermentation yield improvements and excipient certification penetration curves served as industry-specific forecast inputs.
Stress conditions across corn feedstock price bands, REACH registration timeline extensions, and pharmaceutical qualification delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and clean-label procurement acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Inorganic Rheology Modifiers Market
Additives
Anti-Pollution Ingredients Market
Additives
Printing Ink Additives Market
Additives
1,4 Butanediol Derivatives Market
Additives
Ammonium Acetate Market
Additives
Sodium Citrate Dihydrate Market
Additives
Global PVC Additives Market
Additives
Global Pearlizing Agent Market
Additives
Biofuel Additives Market
Additives
Global Silica-Based Matting Agents Market
Additives
Carboxymethyl Cellulose Market
Additives
Tricalcium Citrate Market
Additives
Packaging Coating Additives Market
Additives
Sorbitan Oleate Market
Additives
Encapsulated Citric Acid Market
Additives
Sodium Citrate Anhydrous Market