
 Methyl Chloroform Market | 2026-2036
Methyl Chloroform Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Chloroform Market Analytics
The Montreal Protocol is hardening compliance costs for methyl chloroform producers still reliant on ozone-depleting substance exemptions. Occidental Petroleum Corporation leverages its integrated chlor-alkali infrastructure to buffer feedstock volatility. Kem One SAS anchors its European position through specialized solvent-grade output for precision cleaning. Gujarat Alkalies and Chemicals Limited competes on cost structure across industrial-grade volumes in South Asian markets.
Methyl chloroform, chemically 1,1,1-trichloroethane, functions as a non-flammable chlorinated solvent with a boiling point near 74 degrees Celsius and excellent grease-cutting properties for metal degreasing and electronics cleaning. Solvent-grade formulations dominate volume flows due to entrenched use in aerospace and automotive maintenance protocols. Reagent-grade and electronic-grade segments command premium pricing from pharmaceutical and semiconductor end users where purity thresholds exclude lower-specification alternatives.
EPA regulations in the United States restrict methyl chloroform under Clean Air Act provisions, while REACH in Europe mandates phase-out timelines for ozone-depleting substances in industrial applications. The country's national chemical regulator in China enforces GB standards for chlorinated solvent emissions, tightening plant-level compliance. Stakeholders must monitor regulatory divergence across jurisdictions to anticipate supply reallocations and grade-specific demand shifts.
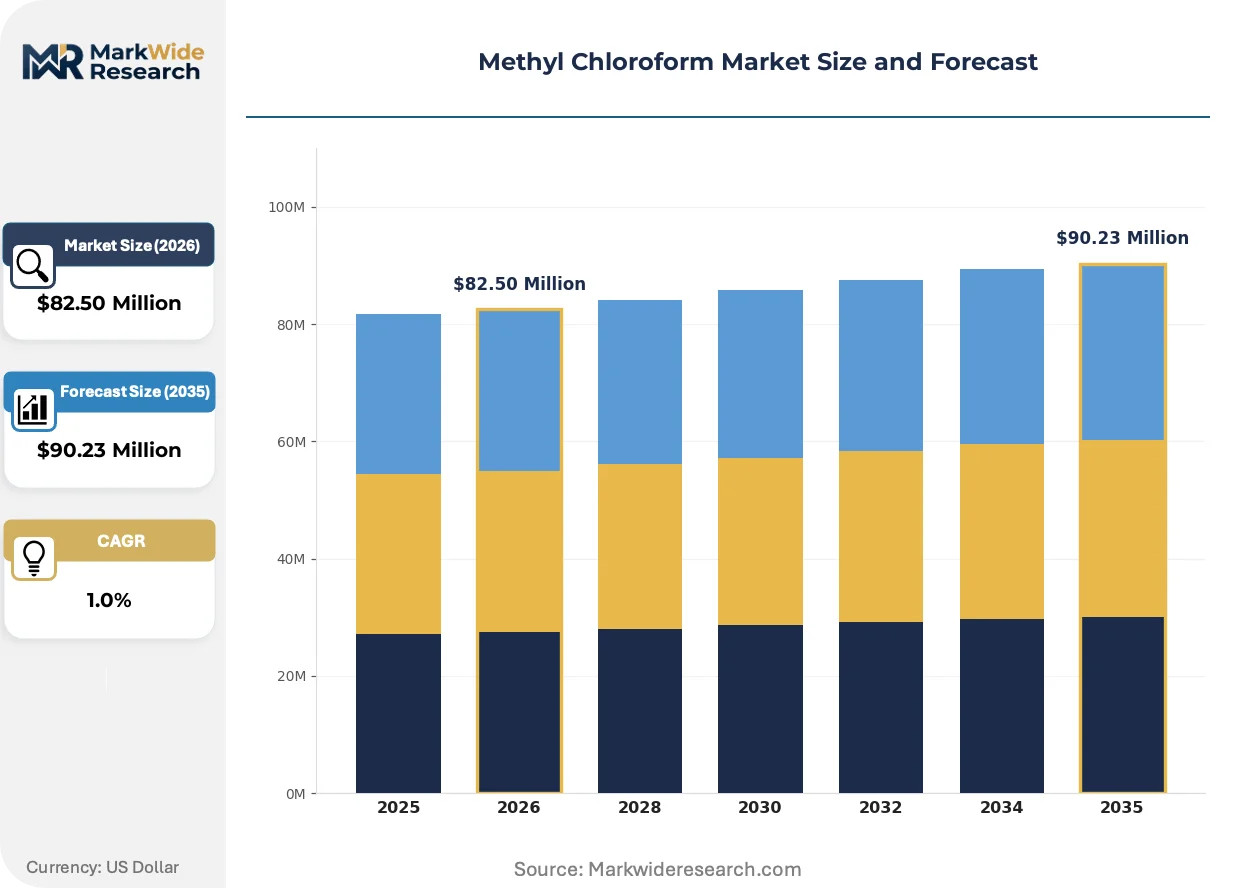
Market Dynamics
The Montreal Protocol's phase-down mandates are compressing methyl chloroform production economics while semiconductor cleaning demand sustains solvent-grade volumes. Manufacturers face escalating compliance costs against a backdrop of concentrated feedstock supply and persistent industrial degreasing applications.
Growth Catalysts
- Semiconductor fabrication expansion:Advanced node production in Taiwan and South Korea requires high-purity methyl chloroform for wafer cleaning, sustaining electronic-grade demand despite broader phase-out pressures.
- Aerospace maintenance protocols:Military and commercial aviation sectors in the United States retain exempted-use authorizations under EPA Clean Air Act provisions for precision degreasing of turbine components.
- REACH transitional allowances:European Union derogations for critical industrial applications extend solvent-grade consumption timelines while alternative chemistries mature.
Market Restraints
- Feedstock chlorine volatility:Chlor-alkali capacity concentration in China and the United States exposes producers to caustic soda market swings and energy cost pass-throughs.
- Ozone-depleting substance stigma:Environmental liability concerns among multinational manufacturers accelerate substitution toward hydrofluoroethers and modified alcohols in open-loop cleaning systems.
- Production quota compression:Montreal Protocol baseline reductions tighten licensed output volumes, forcing asset idling and stranded capital in legacy chlorinated solvent infrastructure.
Strategic Opportunities
- Closed-loop recovery systems:Vapor degreasing equipment retrofits in Germany and Japan enable solvent reclamation rates exceeding 95 percent, extending effective supply under tightening production caps.
- Reagent-grade pharmaceutical applications:Laboratory and synthesis uses in India command premium pricing with less regulatory pressure than industrial solvent markets.
- Carbon border adjustment alignment:EU CBAM implementation creates competitive openings for producers with verified low-emission chlor-alkali integration versus import-dependent competitors.
Industry Challenges
- Specialized chemical engineering talent:Chlorinated solvent process expertise is aging out of the workforce faster than universities replenish organochlorine chemistry programs.
- Dual-use export licensing:Precursor chemical controls under national security frameworks complicate cross-border shipments to semiconductor fabrication facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Chloroform Market |
| Market Size in 2026 | $82.50 Million |
| Market Size in 2035 | $90.23 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Industrial Grade, Reagent Grade, Electronic Grade Application: Degreasing Agent, Cleaning Solvent, Paint Thinner, Adhesive End User: Automotive, Electronics, Pharmaceuticals, Textiles Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Gujarat Alkalies and Chemicals Limited, Merck KGaA, Occidental Petroleum Corporation, Kem One SAS, Ineos AG, Shin-Etsu Chemical Co., Ltd., Solvay S.A., SRF Limited, Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Chloroform Market Evolving Landscape
Process intensification and regulatory arbitrage are fragmenting methyl chloroform demand along purity-grade lines. Innovators are capturing value through solvent recovery integration and alternative chemistry development rather than volume expansion.
Supercritical carbon dioxide cleaning systems are converging with precision manufacturing requirements in aerospace and medical device sectors. Japanese automotive suppliers are piloting these systems for complex geometry components previously dependent on chlorinated solvent immersion. This convergence is compressing addressable market scope for methyl chloroform in open-loop metal finishing applications.
EPA Significant New Alternatives Policy program revisions are accelerating hydrofluoroether solvent approvals for electronics cleaning. Industrial consequence includes rapid qualification of 3M Novec and Chemours Vertrel formulations by semiconductor original equipment manufacturers. Memory chip fabricators in South Korea and the United States are responding fastest, with logic foundries maintaining methyl chloroform for legacy process nodes.
Buyer consolidation among contract electronics manufacturers is concentrating solvent procurement decisions at fewer headquarters locations. Flex and Jabil procurement teams are unbundling chemical supply from equipment service contracts, pressuring distributors on spot pricing transparency. This pattern is most visible in Penang and Shenzhen manufacturing clusters where volume concentration enables direct producer negotiations.
Methyl Chloroform Market Segmentation
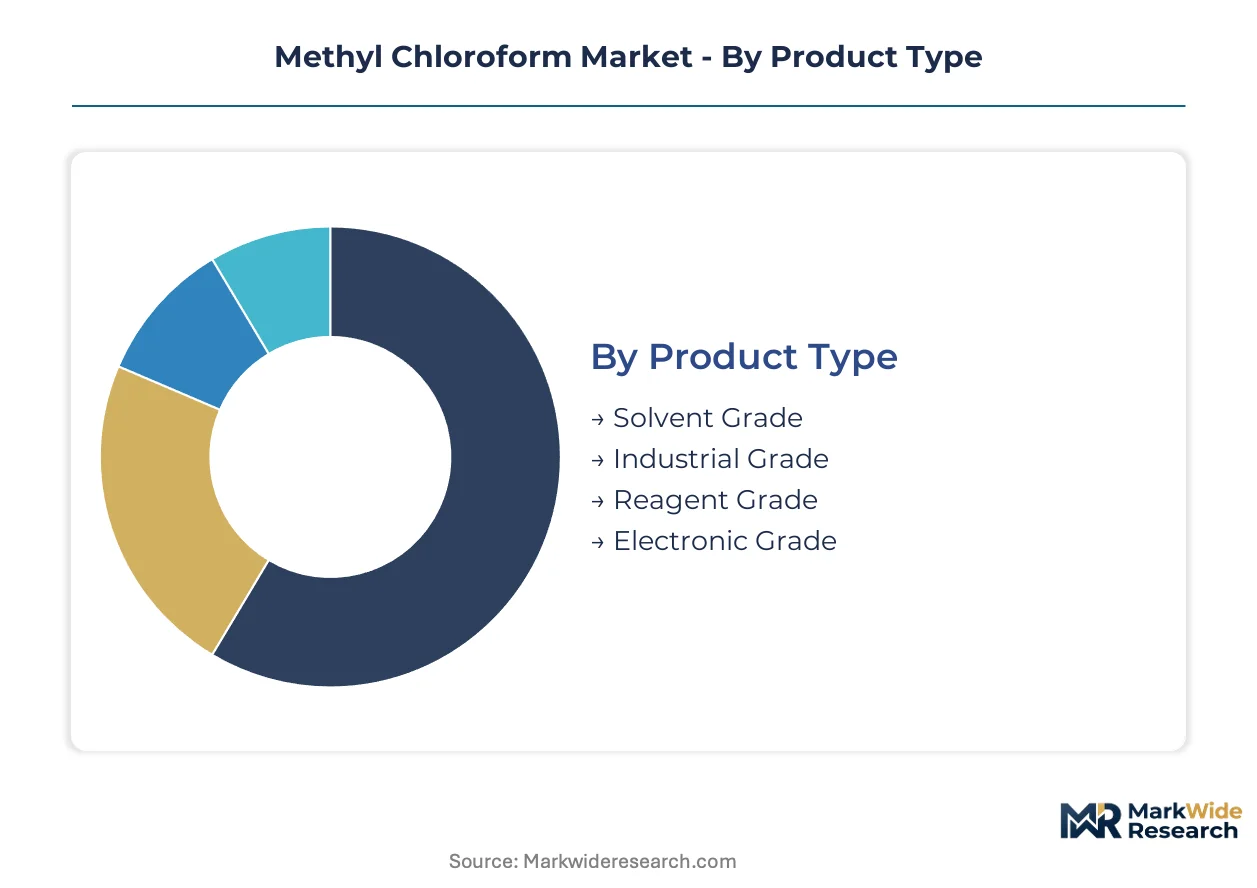
Methyl chloroform demand fragments sharply across purity specifications and regulatory exposure tiers. Semiconductor fabs, aerospace maintenance depots, and pharmaceutical laboratories each impose distinct compositional thresholds that reshape supplier economics and channel strategy.
Product Type:
Purity specifications determine pricing power and regulatory vulnerability across the four-grade spectrum.
- Electronic Grade:Ultra-high purity formulations with sub-ppm metallic impurity limits serve wafer cleaning in Taiwan and South Korean semiconductor fabs. Advanced node production at Samsung and TSMC sustains premium pricing despite Montreal Protocol production caps tightening supply.
- Solvent Grade:Standardized formulations with controlled moisture and acidity levels dominate aerospace degreasing applications in United States military maintenance facilities. EPA exempted-use authorizations under Clean Air Act provisions preserve demand for turbine component cleaning where alternative chemistries fail performance thresholds.
- Industrial Grade:Cost-optimized formulations serve metal finishing and general manufacturing in Chinese industrial clusters.
- Reagent Grade:Laboratory-certified purity for pharmaceutical synthesis and analytical chemistry applications in Indian and European research institutions.
Mature deployment sits with Solvent Grade in aerospace maintenance. Newer deployment is concentrated in Electronic Grade for semiconductor fabrication.
Application:
Functional use cases split between open-loop consumption with high environmental scrutiny and closed-loop systems with recovery economics.
- Cleaning Solvent:Precision removal of photoresist and particulate contamination in semiconductor wafer processing commands the steepest expansion trajectory among application segments. South Korean memory chip fabricators drive volume concentration as logic foundries maintain methyl chloroform for legacy nodes while transitioning advanced processes to hydrofluoroether alternatives.
- Degreasing Agent:Vapor phase metal cleaning in automotive and aerospace manufacturing retains entrenched demand in German and Japanese precision engineering clusters. Closed-loop vapor degreasing equipment retrofits enable reclamation rates exceeding 95 percent, extending effective supply under tightening Montreal Protocol quotas.
- Paint Thinner:Declining industrial coatings applications face rapid substitution by low-VOC alternatives in European and North American regulatory jurisdictions.
- Adhesive:Niche solvent cement applications for plastics bonding in specialty manufacturing.
Volume concentration favors Degreasing Agent in mature industrial maintenance. Value expansion is climbing the fastest in Cleaning Solvent for electronics manufacturing.
End User:
Customer sophistication and compliance capacity create divergent procurement patterns across industrial sectors.
- Electronics:Contract manufacturers in Penang and Shenzhen manufacturing clusters concentrate procurement decisions at Flex and Jabil headquarters, unbundling chemical supply from equipment service contracts. Direct producer negotiations displace distributor intermediaries where volume thresholds permit.
- Automotive:Japanese automotive suppliers pilot supercritical carbon dioxide cleaning systems for complex geometry components, compressing addressable scope for chlorinated solvent immersion in open-loop metal finishing.
- Pharmaceuticals:Laboratory and synthesis uses in Indian pharmaceutical hubs command premium pricing with less regulatory pressure than industrial solvent markets.
- Textiles:Spot cleaning and dry cleaning applications face accelerating substitution by perchloroethylene and hydrocarbon alternatives.
Procurement sophistication concentrates in Electronics. Regulatory shelter exists in Pharmaceuticals.
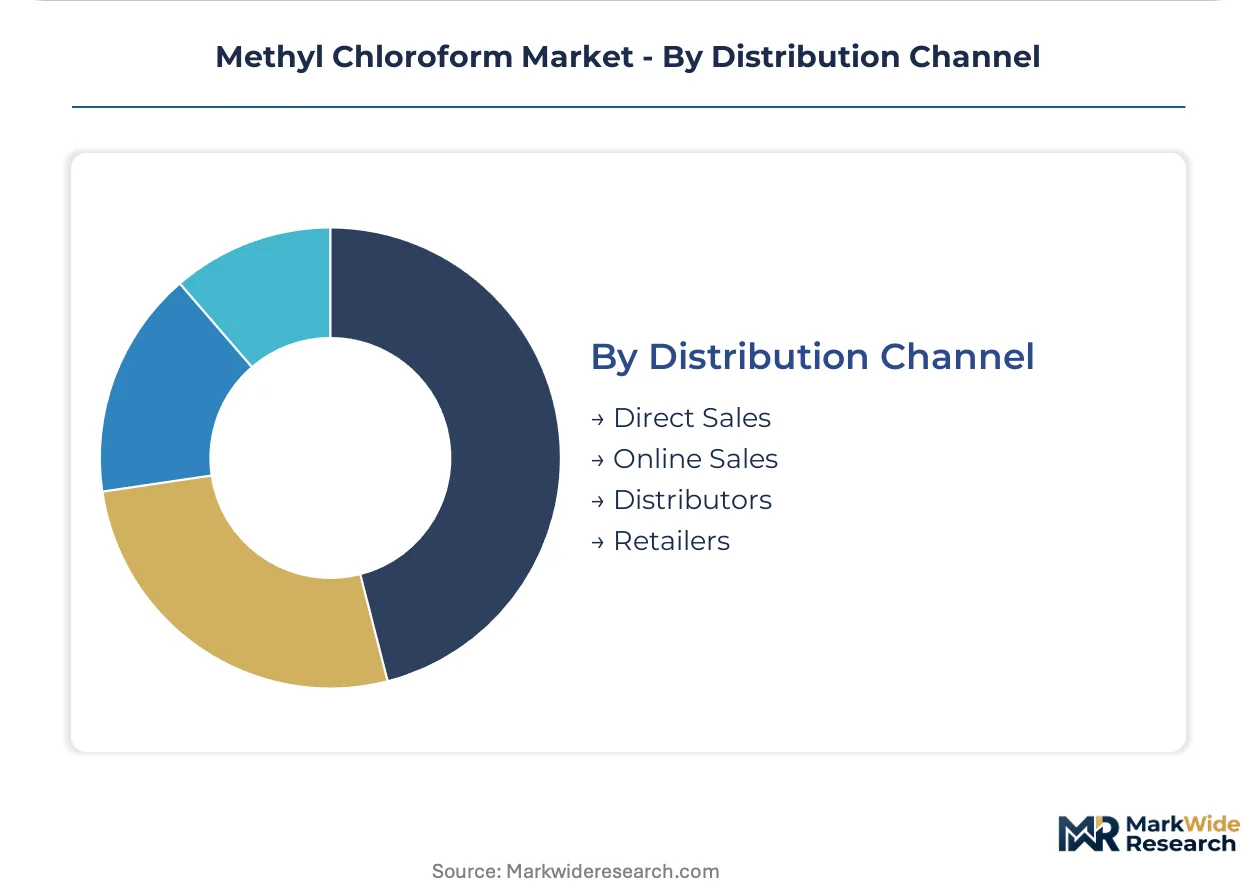
Distribution Channel:
Channel economics reflect customer scale, geographic concentration, and regulatory documentation burdens.
- Direct Sales:Large-volume semiconductor fabricators and aerospace contractors negotiate supply agreements directly with Occidental Petroleum and Kem One, capturing price transparency and technical service integration. Dual-use export licensing under national security frameworks complicates cross-border shipments, favoring producer-direct relationships with compliance expertise.
- Distributors:Regional chemical distributors serve fragmented metal finishing and maintenance customers in South Asian and Southeast Asian industrial zones.
- Online Sales:Laboratory-scale reagent-grade procurement through specialized chemical supply platforms.
- Retailers:Limited consumer-facing hardware and automotive maintenance channels with declining relevance.
Relationship intensity clusters in Direct Sales. Transaction efficiency gains share fastest in Online Sales for reagent-grade volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces concentrate methyl chloroform consumption through clustered electronics manufacturing and chemical processing incentives. Taiwan's Hsinchu Science Park and South Korea's Yongin semiconductor corridor anchor high-purity solvent demand. Regulatory divergence across these jurisdictions reshapes trade flows and production economics.
China
Semiconductor fabrication expansion in Jiangsu and Zhejiang provinces sustains electronic-grade methyl chloroform consumption despite tightening Montreal Protocol quotas. The country's national chemical regulator enforces GB standards for chlorinated solvent emissions, tightening plant-level compliance in Shandong chemical clusters. Yangtze River Delta industrial zones concentrate solvent-grade demand for metal finishing applications serving automotive supply chains.
United States
Aerospace maintenance depots in Texas and Georgia retain exempted-use authorizations under EPA Clean Air Act provisions for precision turbine degreasing. Gulf Coast chlor-alkali infrastructure supports integrated methyl chloroform production with captive chlorine supply. California's semiconductor fabrication facilities in Silicon Valley drive electronic-grade procurement despite state-level air quality restrictions.
Germany
Automotive precision engineering clusters in Bavaria and Baden-Württemberg deploy closed-loop vapor degreasing systems with solvent recovery rates exceeding 95 percent. REACH transitional allowances for critical industrial applications extend consumption timelines while alternative chemistries mature. Ruhr Valley chemical processing sites maintain industrial-grade demand for metal finishing applications.
South Korea
Memory chip fabricators in Yongin and Pyeongtaek sustain methyl chloroform consumption for wafer cleaning processes at Samsung and SK Hynix facilities. MFDS chemical substance regulations align with international phase-down schedules while permitting critical-use exemptions. Gyeonggi Province semiconductor clusters concentrate procurement decisions for high-purity solvent grades.
India
Pharmaceutical synthesis laboratories in Maharashtra and Gujarat command premium pricing for reagent-grade methyl chloroform with less regulatory pressure than industrial solvent markets. CDSCO oversight of chemical substances maintains import licensing requirements for ozone-depleting precursors. Dahej and Mundra port zones facilitate solvent-grade distribution to metal finishing operations across western industrial corridors.
Methyl Chloroform Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across methyl chloroform production tiers, creating a bifurcated competitive structure. The market consolidates around integrated chlor-alkali operators with captive feedstock supply and regional specialists serving grade-specific niches. Three archetypes dominate: multinational chemical conglomerates with backward integration into chlorine production, regional specialists leveraging geographic proximity to demand clusters, and diversified industrial holding companies with portfolio breadth across chlorinated solvents. Capacity rationalization under Montreal Protocol quotas and closed-loop recovery system partnerships represent the dominant competitive moves reshaping positioning.
Among integrated petrochemical operators, Occidental Petroleum Corporation anchors the North American supply base through Gulf Coast chlor-alkali infrastructure. Kem One SAS exemplifies the European specialist archetype with concentrated solvent-grade production serving precision cleaning applications. Gujarat Alkalies and Chemicals Limited occupies a position within the cost-optimized industrial-grade segment, leveraging proximity to South Asian manufacturing demand. These three entities represent distinct strategic postures: feedstock-integrated scale, regional grade specialization, and emerging-market cost positioning.
| Leading Market Players |
|---|
| Gujarat Alkalies and Chemicals Limited |
| Merck KGaA |
| Occidental Petroleum Corporation |
| Kem One SAS |
| Ineos AG |
| Shin-Etsu Chemical Co., Ltd. |
| Solvay S.A. |
| SRF Limited |
| Tokuyama Corporation |
| Others |
Value Network & Pricing Analysis
Closed-loop vapor recovery system retrofits in German and Japanese precision engineering clusters simultaneously compress unit consumption volumes and concentrate procurement power among buyers with capital-intensive reclamation infrastructure. This technology transition rewards integrated chlor-alkali producers with captive feedstock supply while squeezing margin capture for distributors serving fragmented metal finishing customers without recovery capabilities.
Pricing Analysis
Short lead-time premiums for electronic-grade methyl chloroform sustain pricing power at Taiwan and South Korean semiconductor fabs where process continuity commands priority over cost optimization. Three-tier pricing structure across electronic, solvent, and industrial grades reflects purity thresholds and regulatory documentation burdens rather than commodity spot dynamics. Pricing pressure stems from hydrofluoroether substitution accelerating at advanced memory chip nodes. Contract electronics manufacturers in Penang and Shenzhen manufacturing clusters exhibit highest price sensitivity through unbundled chemical procurement from equipment service contracts.
Supply Chain Analysis
Chlorine feedstock supply rests on concentrated chlor-alkali capacity in China and the United States with energy cost pass-throughs tethered to regional electricity markets. Methyl chloroform production draws from caustic soda co-product economics and vinyl chloride monomer demand cycles as parallel chlorine sinks. Single-source vulnerability concentrates in Gulf Coast infrastructure exposed to hurricane disruption and EPA enforcement actions. Distribution runs through direct producer relationships with large-volume semiconductor fabricators and aerospace contractors, displacing distributor intermediaries where compliance expertise and dual-use export licensing capabilities prove critical.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics under Montreal Protocol production quotas prop pricing power for licensed manufacturers with integrated chlor-alkali assets and recovery system partnerships.
For Market Incumbents: Deploy closed-loop recovery system partnerships as the anchor retention mechanism against hydrofluoroether substitution at South Korean memory chip fabricators. Deepen backward integration into chlorine production through Gulf Coast and Yangtze River Delta capacity positions to buffer caustic soda market swings. Capture stranded distributor volume by unbundling technical service from chemical supply for contract electronics manufacturers in Penang and Shenzhen clusters. For New Entrants and Emerging Players: Indian pharmaceutical synthesis laboratories represent the most penetrable buyer archetype for reagent-grade methyl chloroform with less regulatory pressure than industrial solvent markets and premium pricing tolerance. Target closed-loop vapor degreasing equipment retrofits in German automotive precision engineering clusters as a service-anchored entry path. Pursue direct sales relationships with aerospace maintenance depots in Texas and Georgia holding EPA exempted-use authorizations for turbine component cleaning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional specialists with grade-specific certification capabilities and geographic proximity to demand clusters. Long-term viability frames around carbon border adjustment alignment for EU market access and Montreal Protocol license transferability across jurisdictions. Watch EPA Significant New Alternatives Policy program revisions as the signal for inflection in electronics cleaning substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Capacity | Captive chlorine supply buffers Occidental Petroleum against feedstock volatility and energy cost pass-throughs. |
| Closed-Loop Recovery System Partnerships | German automotive suppliers achieve reclamation rates exceeding 95 percent under tightening Montreal Protocol quotas. |
| Reagent-Grade Certification Investment | Indian pharmaceutical laboratories command premium pricing with less regulatory pressure than industrial solvent markets. |
| Direct Sales Channel Expansion | Flex and Jabil procurement teams in Penang and Shenzhen displace distributor intermediaries for volume transparency. |
| Long-Term Supply Agreement with Semiconductor Fabs | Samsung and TSMC anchor electronic-grade demand through advanced node production requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this methyl chloroform market analysis. Primary interviews with plant managers at chlor-alkali facilities, procurement leads at semiconductor fabricators, distribution channel partners in South Asian industrial zones, and technical R&D directors at solvent recovery equipment manufacturers combined with bottom-up and top-down triangulation. Secondary sources included EPA enforcement databases, ECHA REACH registration dossiers, MFDS chemical substance notifications, SEC 10-K filings from integrated petrochemical operators, and customs trade flow records from Dahej and Mundra port zones.
Data-stream reconciliation across production volume estimates, import-export flows, and end-use consumption surveys shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed grade tier purity specifications, end-use industry exposure to regulatory phase-down timelines, packaging format for laboratory versus bulk industrial delivery, and regional production hub concentration under Montreal Protocol quotas. CAGRs derived from license-constrained supply trajectories intersecting with semiconductor fabrication expansion curves and aerospace maintenance protocol persistence.
Revisions become necessary when EPA Significant New Alternatives Policy program accelerates hydrofluoroether approvals, when Montreal Protocol baseline reductions tighten beyond licensed output assumptions, or when carbon border adjustment mechanisms reshape competitive access to European Union markets. Forecasts reflect documented assumptions regarding exempted-use authorization renewal timelines and closed-loop recovery system adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Potassium Cryolite Market