
 Alkalinity Control Chemicals Market | 2026-2036
Alkalinity Control Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Alkalinity Control Chemicals Market Analysis
Power generation's cooling tower chemistry requirements is recalibrating procurement volumes across the alkalinity control chemicals value chain. Nalco Water dominates large-scale utility contracts through captive supply of on-site chemical management systems. BASF differentiates via specialized sodium bicarbonate grades engineered for high-pH buffering in combined-cycle plants. Ecolab leverages digital water-monitoring platforms to anchor recurring chemical replenishment schedules.
Alkalinity control chemicals comprise pH-buffering compounds—primarily carbonates, bicarbonates, and hydroxides—dosed to stabilize water chemistry within a target pH range of 6.5 to 8.5, preventing corrosive or scaling conditions in industrial and municipal systems. Sodium bicarbonate leads product-type demand due to its gradual dissolution kinetics and safe handling profile across aquaculture and water treatment applications. Industrial processes represent the fastest-growing application segment as semiconductor fabrication and food processing adopt closed-loop cooling architectures requiring precise alkalinity management. Municipalities anchor end-user value pools through multi-year framework contracts tied to drinking-water and wastewater compliance.
EPA effluent limitation guidelines and OSHA process safety management standards shape product formulation and handling protocols across United States manufacturing and distribution channels. China's MEE enforces stricter discharge permits for thermal power and chemical complexes, compelling upstream adoption of advanced alkalinity control systems. ISO 14001 environmental management certification increasingly gates supplier qualification for multinational water treatment tenders. Stakeholders must monitor regulatory divergence between carbon-intensive industrial clusters and jurisdictions accelerating decarbonization mandates.
Market Dynamics
Cooling water chemistry standards under the EPA Clean Water Act are recalibrating procurement volumes across power generation and desalination facilities, forcing specification upgrades that ripple through municipal and industrial water treatment supply chains.
Growth Catalysts
- Zero-liquid-discharge mandates:China's MEE enforces stricter discharge permits for thermal power complexes, compelling upstream adoption of advanced alkalinity control systems.
- Semiconductor fabrication expansion:Closed-loop cooling architectures in chip manufacturing require precise alkalinity management, driving chemical demand from fabrication facilities.
- ISO 14001 certification gates:Environmental management certification increasingly qualifies suppliers for multinational water treatment tenders, expanding addressable contract pools.
Market Restraints
- Soda ash supply concentration:Synthetic soda ash production clusters in the United States and China create input cost volatility for carbonate-based alkalinity control formulations.
- Caustic soda substitution pressure:Sodium hydroxide offers faster pH adjustment kinetics, threatening bicarbonate market share in time-sensitive industrial applications.
- OSHA process safety friction:Handling protocols for hydroxide-based products add compliance layers that slow adoption in small-scale municipal systems.
Strategic Opportunities
- India's industrial water reuse:Central Electricity Authority mandates for thermal power plant water efficiency create untapped demand for on-site alkalinity management systems.
- Digital water-monitoring convergence:IoT sensor networks paired with automated dosing equipment enable predictive chemical replenishment models.
- Aquaculture pH stabilization:Shrimp and salmon farming operations in coastal zones adopt bicarbonate buffering for intensive recirculating systems.
Industry Challenges
- Skilled water chemist scarcity:Facilities struggle to staff operators capable of interpreting complex buffering curves and adjusting multi-chemical dosing regimes.
- Legacy SCADA integration:Automated alkalinity control systems face protocol mismatches when retrofitting into decades-old distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkalinity Control Chemicals Market |
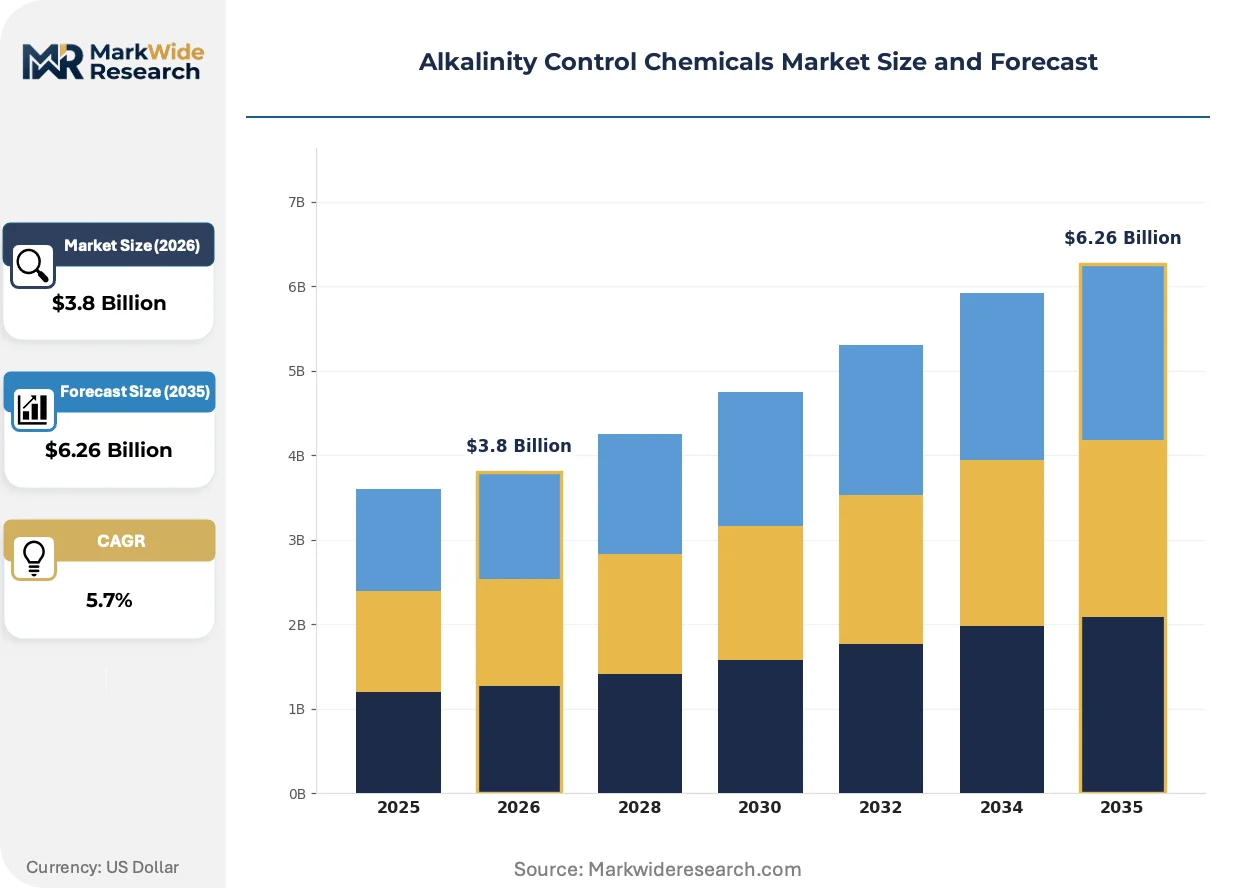
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium bicarbonate, Calcium carbonate, Potassium carbonate, Sodium hydroxide Application: Aquaculture, Water treatment, Agriculture, Industrial processes End User: Municipalities, Agricultural producers, Chemical manufacturers, Aquaculture farms Distribution Channel: Direct sales, Distributors, Online retail, Wholesalers |
| Companies Covered | ChemTreat, IXOM, Nalco Water, BASF, SUEZ Water Technologies & Solutions, Kurita Water Industries, Ecolab, Solvay, Veolia Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkalinity Control Chemicals Market Emerging Trajectories
Digitalization of water chemistry management is displacing manual titration and paper-based dosing logs across industrial and municipal treatment facilities, compressing response times and reducing chemical overfeed.
Membrane-based pH adjustment technology is converging with conventional chemical dosing in zero-liquid-discharge installations. Semiconductor fabs in Taiwan and South Korea pilot electrochemical pH control alongside bicarbonate buffering. This hybrid approach is converging with traditional supply contracts, forcing chemical suppliers to bundle equipment leasing with consumable supply.
REACH authorization requirements for boron compounds are restricting certain alkalinity control formulations across EU manufacturing and distribution channels. Industrial users face reformulation costs or supply chain requalification. Germany's chemical complexes respond fastest, accelerating sodium bicarbonate grade development for high-pH buffering applications.
Buyers increasingly unbundle chemical supply from equipment service contracts that previously locked in multi-year replenishment schedules. Municipal water authorities in the United States negotiate spot pricing for alkalinity control chemicals while retaining digital monitoring platforms. This decoupling is most visible in California and Texas, where procurement officers prioritize flexibility over captive supply arrangements.
Alkalinity Control Chemicals Market Segmentation
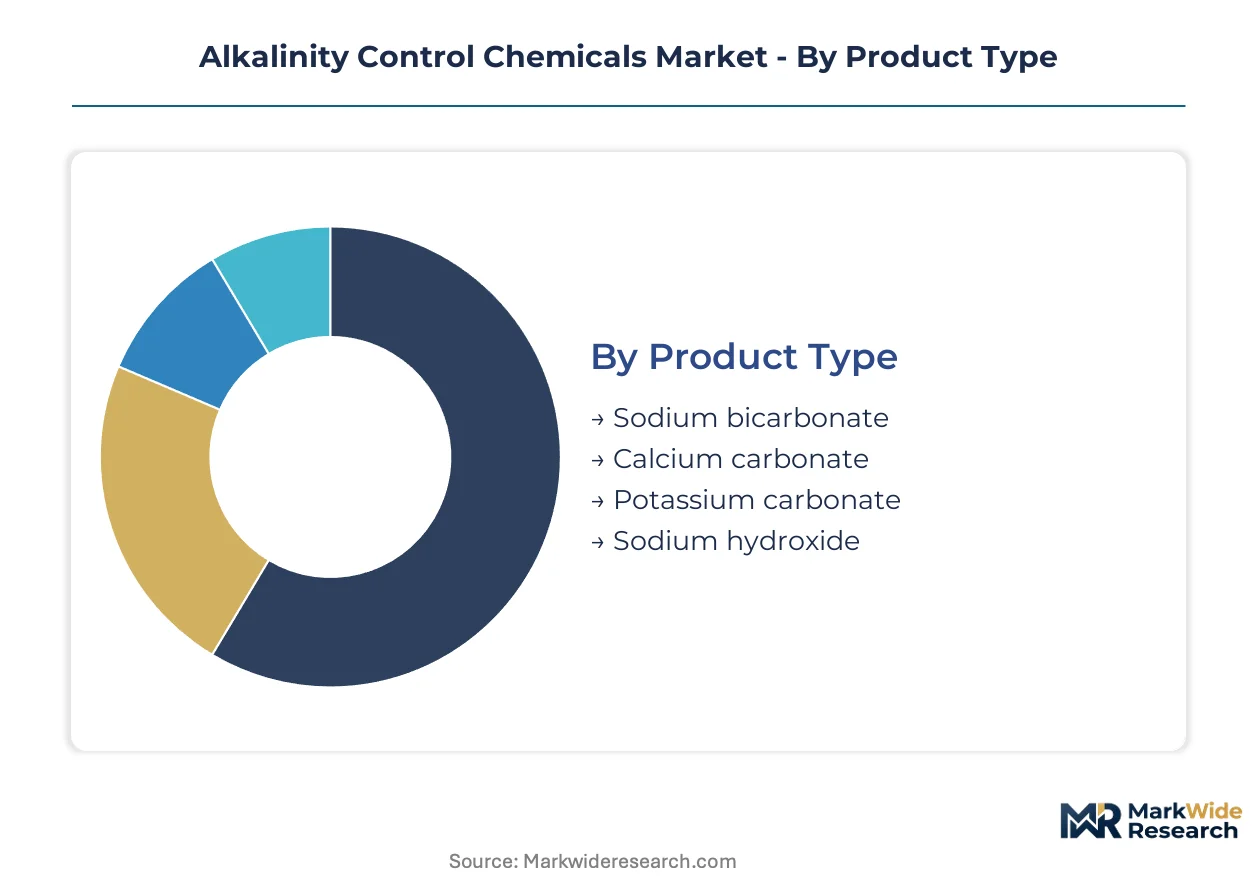
Alkalinity control chemicals serve divergent performance requirements across pH buffering intensity, dissolution kinetics, and regulatory compliance profiles. Segment boundaries reflect trade-offs between handling safety, reaction speed, and cost per treated volume that reshape procurement patterns across municipal and industrial accounts.
Product Type:
Standardization dominates commodity carbonates while hydroxide formulations demand customized safety protocols and application engineering.
- Sodium bicarbonate:Gradual dissolution kinetics and non-corrosive handling profile make this the default specification for aquaculture recirculating systems and municipal drinking-water adjustment. Demand concentrates in Germany and the United States where EPA and REACH-compliant formulations anchor multi-year utility contracts.
- Sodium hydroxide:Rapid pH elevation kinetics serve time-sensitive industrial applications including semiconductor fabrication rinse-water neutralization. OSHA process safety management requirements add compliance friction that slows adoption in small-scale municipal systems lacking trained chemists.
- Calcium carbonate:Lower solubility limits deployment to open-loop cooling towers and agricultural liming where slower reactivity is acceptable.
- Potassium carbonate:Premium pricing restricts use to specialized food-processing and pharmaceutical buffering where sodium content must be minimized.
Most installed capacity flows through sodium bicarbonate. Expansion is steepest in sodium hydroxide.
Application:
Volume scale separates continuous-flow municipal systems from batch-process industrial deployments with intermittent dosing requirements.
- Water treatment:Municipal drinking-water and wastewater facilities specify carbonate-based buffering to maintain pH 6.5-8.5 through distribution networks. China's MEE discharge permit tightening drives specification upgrades across thermal power cooling circuits.
- Industrial processes:Closed-loop cooling architectures in semiconductor fabrication demand precise alkalinity management with minimal chemical overfeed. Taiwan and South Korea fabrication clusters pilot hybrid electrochemical-chemical systems that compress response times.
- Aquaculture:Intensive shrimp and salmon recirculating systems in coastal Vietnam and Norway deploy bicarbonate buffering to stabilize pH against respiratory acidification.
- Agriculture:Soil liming and irrigation-water adjustment follow seasonal patterns with price-sensitive procurement concentrated in Brazil and India.
Water treatment commands the largest volume share. Industrial processes are climbing the fastest.
End User:
Contract structure divides framework agreements with creditworthy municipalities from spot purchasing by fragmented agricultural producers.
- Municipalities:Multi-year tenders with ISO 14001 certification gates favor suppliers bundling digital monitoring platforms with chemical replenishment. California and Texas authorities increasingly unbundle equipment service from consumable supply to retain pricing flexibility.
- Chemical manufacturers:Process-water chemistry requirements in combined-cycle power plants and desalination facilities drive large-volume procurement through Nalco Water captive supply arrangements.
- Aquaculture farms:Coastal intensive operations in Ecuador and Indonesia prioritize safe-handling bicarbonate grades over caustic alternatives.
- Agricultural producers:Seasonal demand peaks and price sensitivity concentrate purchasing through distributor networks rather than direct manufacturer relationships.
Municipalities anchor value capture. Chemical manufacturers are gaining share fastest.
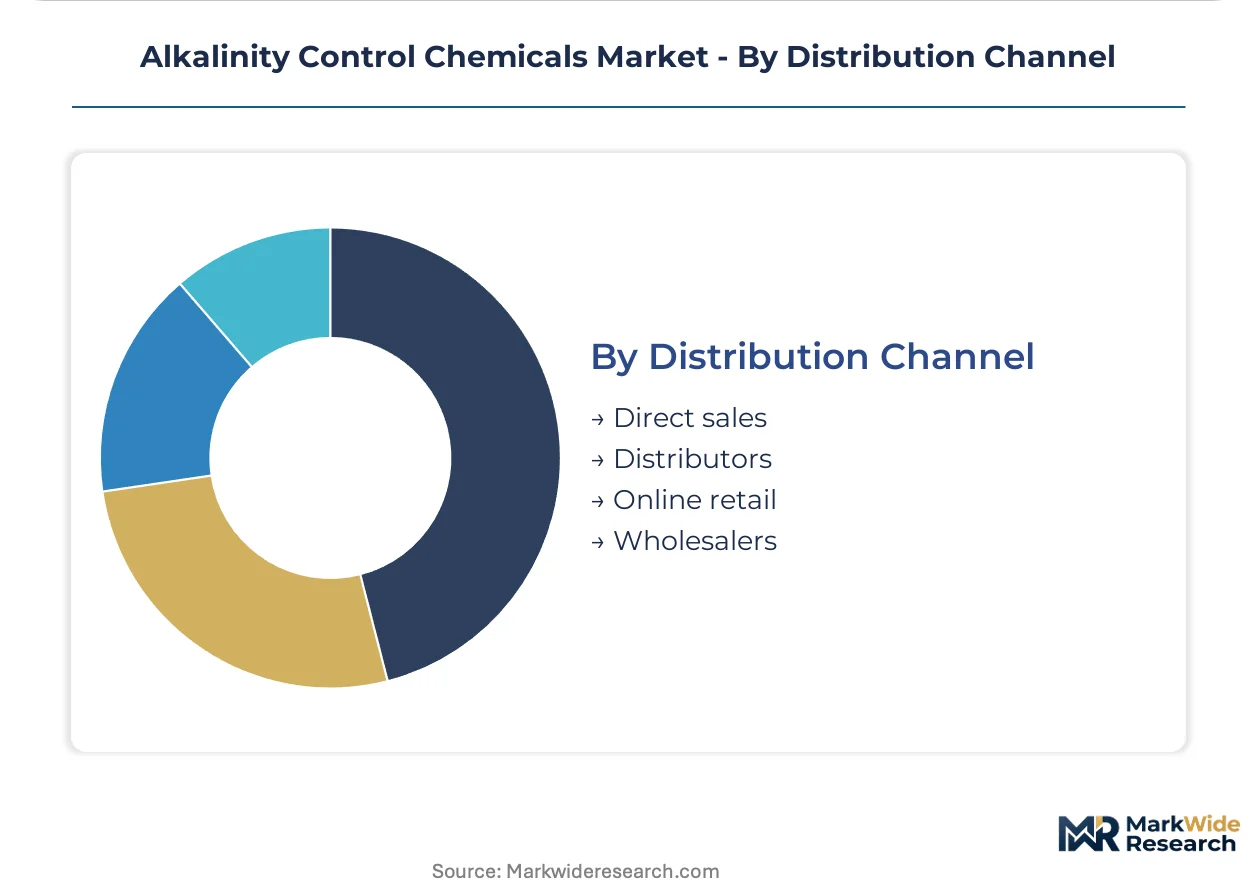
Distribution Channel:
Customer scale and technical service requirements determine route selection between direct manufacturer engagement and intermediated fulfillment.
- Direct sales:Large utilities and industrial complexes negotiate site-specific formulations with technical service attachments. Ecolab digital water-monitoring platforms anchor recurring replenishment schedules through direct relationships.
- Distributors:Regional chemical distributors serve mid-scale industrial accounts requiring local inventory and emergency response capabilities across the US Gulf Coast and German Rhine-Ruhr chemical clusters.
- Wholesalers:Agricultural and small-municipal segments access standard-grade carbonates through bulk purchasing cooperatives with limited technical support.
- Online retail:Laboratory-scale quantities and specialty grades reach research facilities and small aquaculture operators through B2B platforms with documented safety data sheet compliance.
Direct sales capture the highest margin pool. Distributors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power generation corridors across the United States, China, and Germany concentrate procurement volumes for alkalinity control chemicals as cooling water chemistry standards tighten under national environmental regulations.
United States
Thermal power utilities along the Ohio River Valley and Gulf Coast expand chemical procurement to meet EPA Clean Water Act effluent guidelines. The agency's cooling water intake structure rules force specification upgrades across legacy coal and combined-cycle plants. Texas and California municipal water authorities unbundle equipment service from chemical supply contracts to retain pricing flexibility.
China
Zero-liquid-discharge mandates from the Ministry of Ecology and Environment reshape procurement across the Yangtze River Delta and Pearl River Delta industrial clusters. Stricter discharge permits for thermal power complexes accelerate adoption of advanced alkalinity management systems. Semiconductor fabrication facilities in Shanghai and Shenzhen deploy closed-loop cooling architectures requiring precise pH buffering.
Germany
REACH authorization requirements for boron compounds restrict certain alkalinity control formulations across EU manufacturing channels. Chemical complexes in the Rhine-Ruhr region respond fastest, accelerating sodium bicarbonate grade development for high-pH buffering applications. BASF anchors supply relationships with specialized formulations engineered for combined-cycle power plants.
India
Central Electricity Authority mandates for thermal power plant water efficiency create demand for on-site alkalinity management systems across the National Capital Region and Gujarat industrial corridors. Coal-fired units retrofit cooling circuits to comply with tightened wastewater discharge norms. Fabrication clusters in Maharashtra and Tamil Nadu pilot digital monitoring platforms for predictive chemical replenishment.
Japan
Semiconductor fabrication expansion in the Kyushu region drives demand for precise alkalinity control in ultra-pure water systems. METI industrial water reuse guidelines pressure chip manufacturers toward closed-loop architectures. Kurita Water Industries leverages domestic supply chains to anchor recurring replenishment contracts with fabrication facilities.
Alkalinity Control Chemicals Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers retrofit carbonate production lines to serve tightening industrial water chemistry standards. The vendor base stratifies across three tiers: integrated chemical majors with captive mineral sourcing, regional water treatment specialists bundling equipment with consumables, and commodity distributors serving price-sensitive agricultural segments. Two strategic archetypes define competitive positioning: full-service providers embedding digital monitoring platforms, and formulation specialists engineering application-specific buffering compounds. Geographic expansion and technology licensing represent the dominant competitive moves, with European suppliers targeting Asian semiconductor clusters and Japanese firms licensing electrochemical pH control patents.
Among integrated chemical majors, BASF and Solvay exemplify the formulation-specialist archetype through engineered sodium bicarbonate grades for high-pH buffering applications. Nalco Water occupies a position within the full-service tier, anchoring large-scale utility contracts through bundled equipment and consumable supply. These three companies represent distinct competitive vectors: European chemical heritage, Belgian multinational scale, and American utility-centric service integration.
| Leading Market Players |
|---|
| ChemTreat |
| IXOM |
| Nalco Water |
| BASF |
| SUEZ Water Technologies & Solutions |
| Kurita Water Industries |
| Ecolab |
| Solvay |
| Veolia Water Technologies |
| Others |
Supply Flow & Price Mechanics
Certified water chemist scarcity in the Ohio River Valley widens labor-cost differentials between ISO 14001-compliant premium tiers and standard commodity grades. These workforce concentration effects ripple through municipal tender pricing, compressing margins for distributors serving small-scale systems lacking in-house technical staff.
Pricing Analysis
Input-cost pass-through from synthetic soda ash volatility dominates contract renegotiations across carbonate-based formulations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified specialty grades from industrial bulk carbonates and agricultural liming products. Price differentiation hinges on certification level and after-sales technical service bundling. Cost compression in standard grades is intensifying because caustic soda substitution threatens bicarbonate market share in time-sensitive semiconductor rinse applications. Agricultural producers exhibit highest price sensitivity, while semiconductor fabs prioritize reaction kinetics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with China's synthetic soda ash production clusters, which feed carbonate formulations across Asia-Pacific and European conversion facilities. Geographic supply concentration centers on the United States, China, and Germany for both raw material extraction and downstream chemical processing. Raw material dependencies rest on trona ore deposits, chlorine-alkali co-production economics, and natural brine extraction. Tariff exposure on caustic soda imports from China creates reformulation pressure for European buffer compound manufacturers. Distribution runs through direct manufacturer relationships for large utilities, regional chemical distributors for mid-scale industrial accounts, and agricultural cooperatives for seasonal liming demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
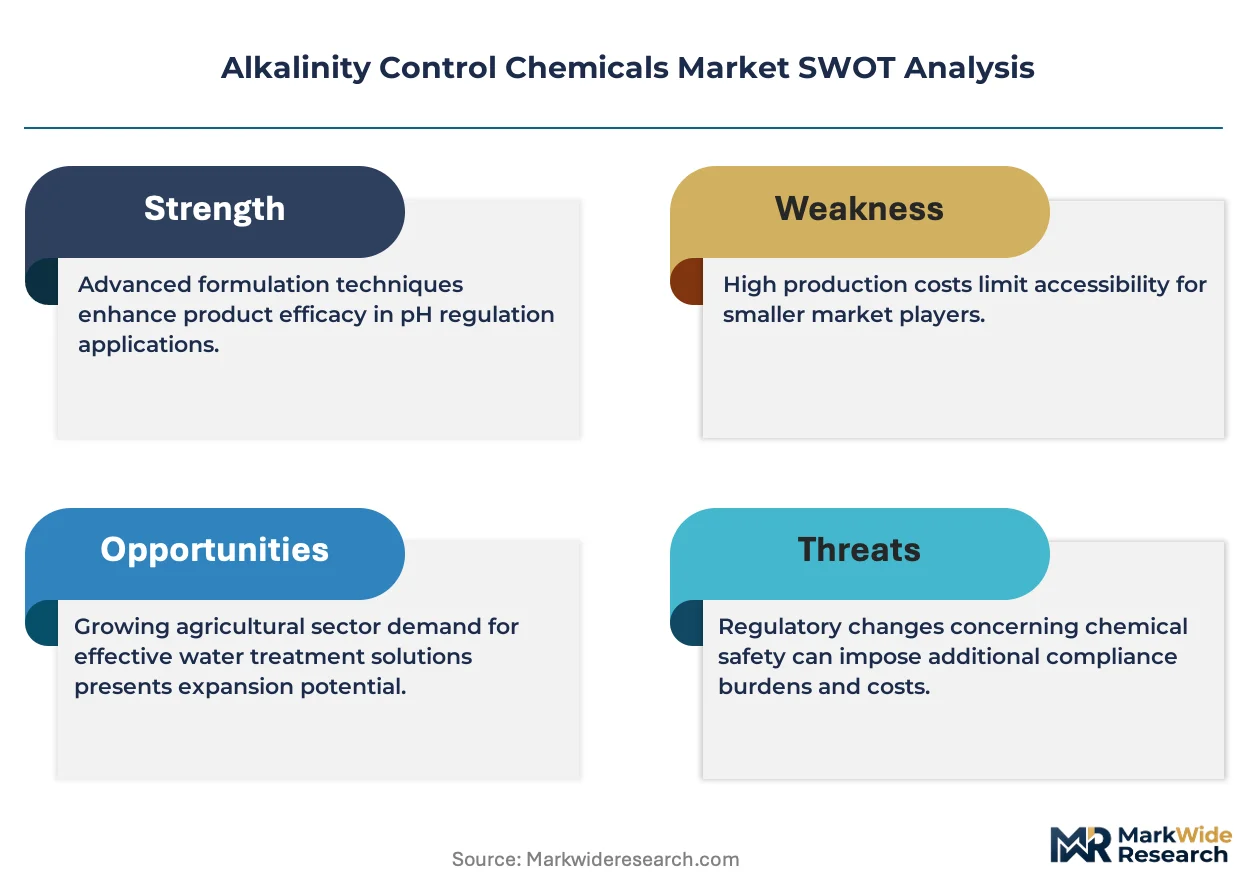
This market functions as a stable compounder, with EPA Clean Water Act cooling water standards providing durable demand visibility across power generation and desalination infrastructure cycles.
For Market Incumbents: Anticipate membrane-based pH adjustment technology displacing chemical-only contracts in zero-liquid-discharge installations. BASF and Solvay should deepen backward integration into trona sourcing to defend margin position against soda ash price volatility. Nalco Water must accelerate digital platform standardization to retain captive replenishment schedules as municipal authorities unbundle equipment from consumable supply.
For New Entrants and Emerging Players: Electrochemical pH control patents represent a technology-first wedge for licensing arrangements with Taiwanese and South Korean semiconductor clusters. White-space targets include India's thermal power retrofit market under Central Electricity Authority mandates and Vietnam's intensive shrimp aquaculture recirculating systems. A service-heavy go-to-market angle bundling predictive dosing algorithms with bicarbonate supply contracts bypasses established distributor relationships.
For Investors and Strategic Acquirers: Water treatment specialists are the most active acquirer in this space, seeking digital monitoring capabilities to anchor recurring revenue streams. The five-to-ten-year viability window favors platforms combining consumable supply with predictive equipment service. Acquisition target archetype: regional distributors with ISO 14001 certification and established utility relationships. The signal to watch is municipal procurement officer turnover toward unbundled spot purchasing in California and Texas.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trona Sourcing | Captive mineral supply insulates BASF and Solvay from Wyoming-Trona price volatility. |
| Digital Platform Standardization | Ecolab's IoT sensor networks compress response times and lock in recurring replenishment. |
| Electrochemical pH Control Licensing | Kurita Water Industries leverages Japanese patents to penetrate Taiwan semiconductor clusters. |
| ISO 14001 Certification Investment | Environmental management gates qualify suppliers for multinational framework tenders. |
| Regional Distributor Acquisition | Consolidation of US Gulf Coast and Rhine-Ruhr chemical distributors accelerates channel control. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged plant managers at thermal power facilities, procurement leads at semiconductor fabs, distribution channel partners across the US Gulf Coast and German Rhine-Ruhr clusters, and technical R&D directors at integrated chemical majors. Secondary validation drew from EPA effluent guideline filings, MEE discharge permit databases, SEC 10-K chemical segment disclosures, and ACC trade flow data. Bottom-up volume modeling triangulated against top-down value estimates from utility tender databases and industrial water treatment contract registries.
Segment-weighting approaches distributed growth assumptions across product type, application intensity, end-user contract structure, and regional regulatory enforcement patterns. The analytical framework modeled sodium bicarbonate, sodium hydroxide, calcium carbonate, and potassium carbonate formulations separately, with cross-elasticity parameters capturing substitution effects from caustic soda. CAGRs were derived from installed base depreciation schedules, regulatory compliance deadline clustering, and capacity expansion announcements. Forecast inputs included semiconductor fabrication buildout pipelines and thermal power water efficiency mandate timelines.
The model holds under steady regulatory enforcement; deviation in EPA rulemaking delays or MEE permit relaxation would shift volume trajectories. Forecasts reflect documented assumptions about cooling water chemistry standard adoption curves and digital monitoring platform penetration rates. Specific risks include skilled chemist labor shortages slowing automated system deployment and legacy SCADA retrofit friction delaying specification upgrades. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Water Softening Systems Market