
 Transportation Composites Market | 2026-2036
Transportation Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Composites Market Outlook
Multi-source procurement is shifting toward captive fiber supply as resin and precursor costs destabilize. Toray Industries anchors Japanese aerospace qualification chains through in-house carbon fiber production. Hexcel Corporation dominates North American defense and commercial aviation pre-preg supply. SGL Group specializes in automotive-grade carbon fiber for BMW and Volkswagen structural programs.
Transportation composites integrate engineered fiber reinforcements with thermoset or thermoplastic matrices to achieve strength-to-weight ratios exceeding conventional aluminum alloys. Vacuum infusion and resin transfer molding yield void contents below 1% for primary aircraft structures, enabling fuel burn reductions. Carbon fiber leads aerospace applications where qualification cycles lock in multi-decade supply agreements. Glass fiber occupies automotive underbody and rail interior segments where cost thresholds override performance premiums. Resin transfer molding is accelerating in marine hull production as shipyards automate layup sequences.
FAA certification standards govern composite airworthiness for US-registered aircraft, while EASA's CS-25 framework mirrors these requirements across European jurisdictions. EPA Corporate Average Fuel Economy rules and the EU F-Gas Regulation are forcing automakers and rail operators to lightweight structures through validated composite architectures. OEMs and Tier-1 suppliers must monitor qualification bottlenecks in recycled fiber certification as circularity mandates tighten.
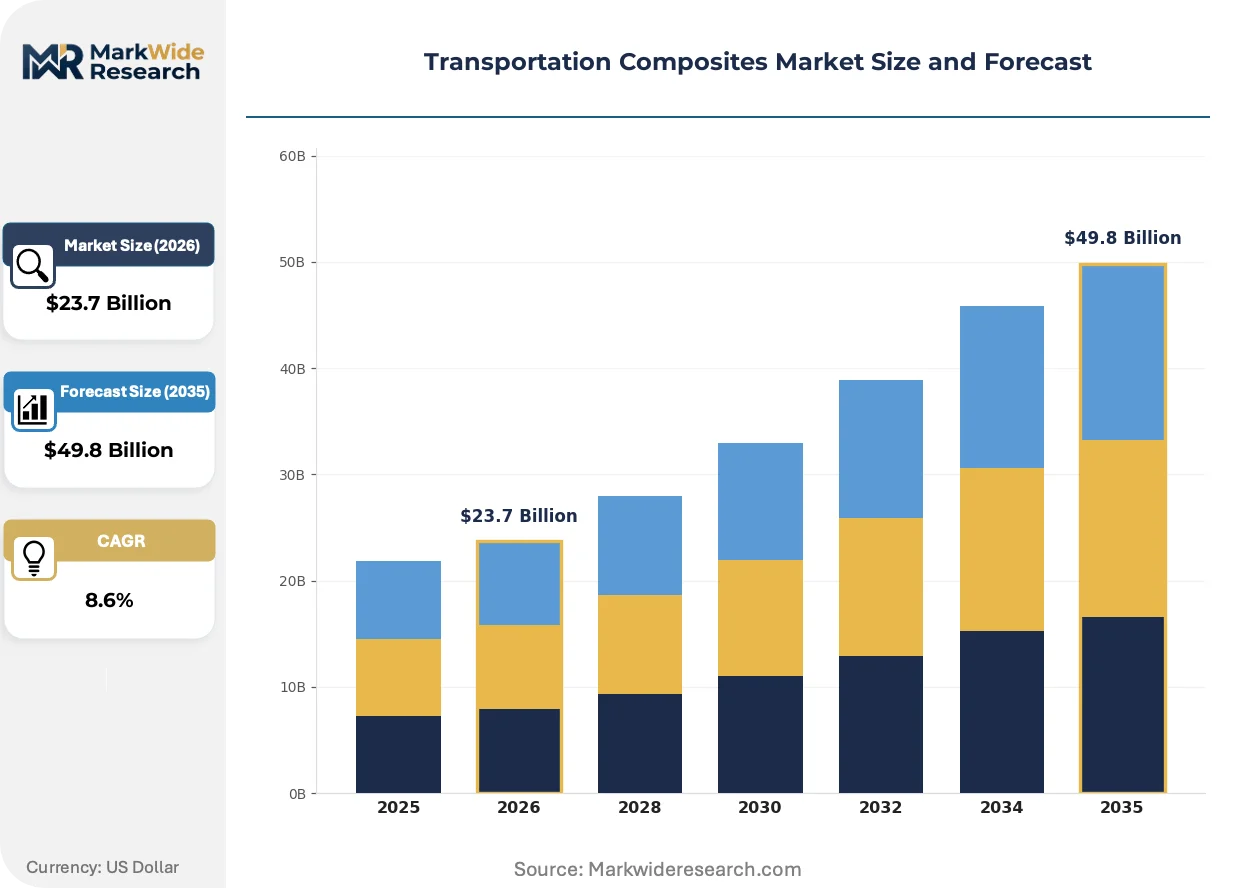
Market Dynamics
Automotive OEMs and aerospace manufacturers face mounting pressure to lightweight structures as EPA Corporate Average Fuel Economy mandates and the EU Green Deal's emissions targets tighten material performance requirements. The shift from metal-intensive architectures to fiber-reinforced composites is compressing qualification timelines and reshaping supplier relationships.
Growth Catalysts
- EPA Fuel-Economy Mandates:US automakers must achieve fleet-wide efficiency improvements that aluminum alone cannot satisfy, driving structural composite adoption in body-in-white applications.
- High-Speed Rail Expansion:China's manufacturing hubs are specifying carbon fiber interiors and glass fiber exterior panels to reduce axle loads and enable higher operating speeds.
- Thermoplastic Resin Maturation:Automated fiber placement with PEEK and PPS matrices is cutting cycle times from hours to minutes for aerospace secondary structures.
Market Restraints
- Precursor Cost Volatility:Acrylonitrile feedstock prices fluctuate with oil markets, destabilizing carbon fiber economics for price-sensitive automotive programs.
- Japanese Supply Concentration:Toray Industries, Mitsubishi Chemical, and Toho Tenax control over 60% of global aerospace-grade carbon fiber capacity, creating single-source vulnerability.
- Aluminum-Lithium Substitution:Airbus and Boeing suppliers retain qualified metal solutions for wing ribs and brackets, slowing full composite conversion.
Strategic Opportunities
- India Automotive Manufacturing:Maruti Suzuki and Tata Motors are localizing composite component production under the PLI scheme for electric vehicle platforms.
- Hydrogen Storage Vessels:Type IV pressure vessels using filament-wound carbon fiber are penetrating heavy-duty truck and bus applications.
- EU Circular Economy Action Plan:Recycled fiber certification pathways are opening for non-structural rail interiors and automotive underbody shields.
Industry Challenges
- Non-Destructive Inspection Talent Scarcity:Phased-array ultrasonic testing and thermography specialists are concentrated at FAA-approved repair stations, constraining MRO expansion.
- Qualification Timeline Compression:EASA CS-25 and FAA AC 20-107B certification cycles for new resin systems extend 18-36 months, blocking rapid formulation innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Composites Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Composites End User: Aerospace, Automotive, Marine, Rail Application: Structural Components, Interiors, Exterior Body Panels, Electrical Insulation Manufacturing Process: Hand Layup, Resin Transfer Molding, Vacuum Infusion, Pultrusion |
| Companies Covered | Toray Industries Inc., Teijin Limited, Owens Corning, Mitsubishi Chemical Holdings Corporation, Hexcel Corporation, SGL Group, Solvay S.A., Royal DSM, Jushi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Composites Market Strategic Shifts
Material science breakthroughs and automated manufacturing processes are collapsing the cost-performance gap between composites and conventional metals. Three developments are restructuring competitive positioning across transportation end-uses.
Out-of-autoclave thermoplastic composites are electrifying primary structure fabrication by eliminating autoclave bottlenecks and enabling welding-based assembly. Boeing and Airbus tier suppliers are qualifying carbon fiber/PEKK laminates for fuselage frames and floor beams. The technology is compressing capital requirements and cycle times for mid-volume aerospace programs.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in polyurethane core materials for marine and rail sandwich panels. Manufacturers are reformulating with CO2 and pentane alternatives to maintain thermal performance. German shipyards and French rail OEMs are most affected, accelerating bio-based epoxy and thermoplastic core adoption.
Long-term supply agreements with pre-payment structures are displacing spot-market resin purchasing among Tier-1 aerospace suppliers. Solvay and Hexcel customers are locking five-to-seven-year carbon fiber and pre-preg contracts with volume commitments. This pattern concentrates most visibly in North American defense programs where qualification locks create captive supply relationships.
Transportation Composites Market Segmentation
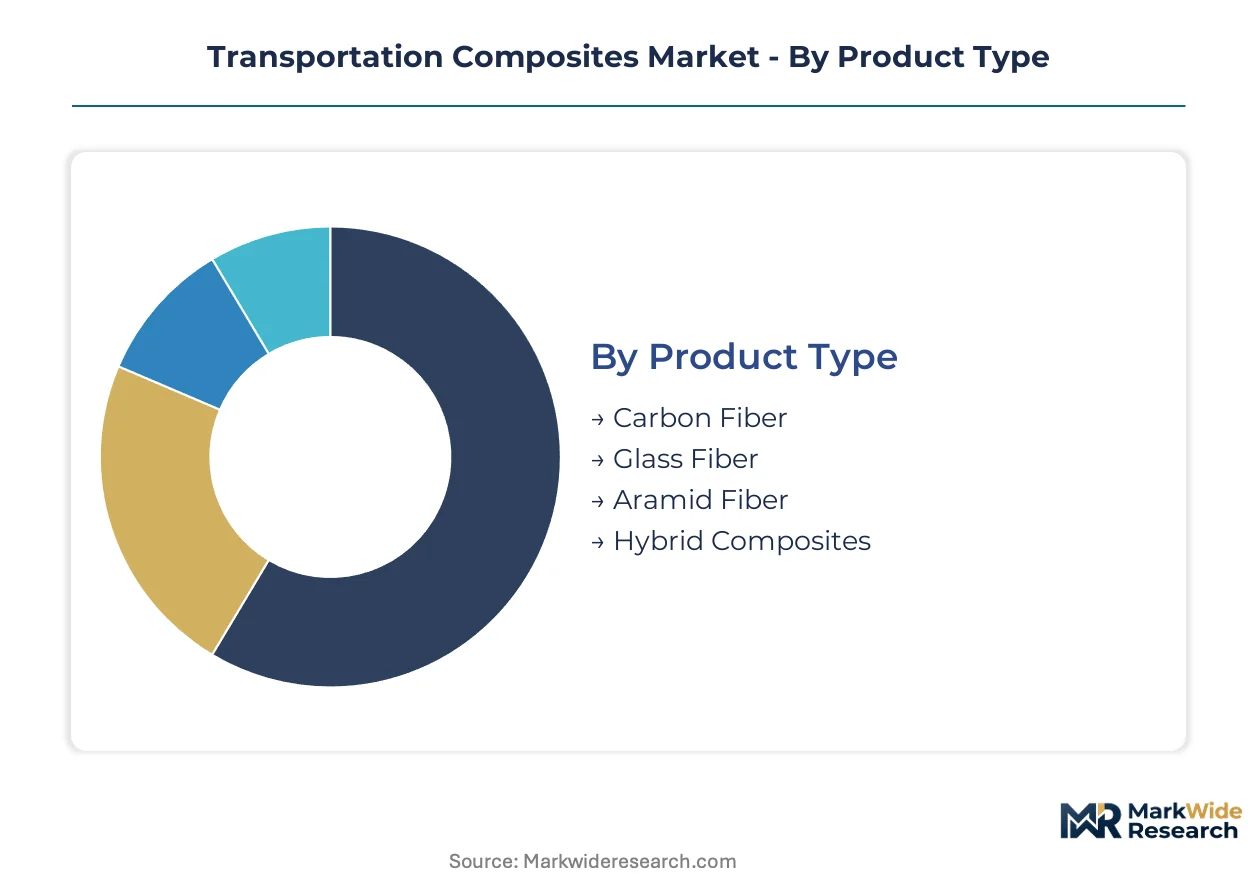
Transportation composites fragment across fiber chemistry, manufacturing process, and application depth. Each segmentation axis reveals distinct margin structures and qualification barriers that shape supplier strategies.
Product Type:
Carbon fiber dominates aerospace integration where embedded structural performance justifies premium positioning, while glass fiber serves standalone applications where cost thresholds override mechanical requirements.
- Carbon Fiber:PAN-based precursors deliver modulus values exceeding 230 GPa for primary aircraft structures. Boeing 787 and Airbus A350 programs anchor demand in US and French manufacturing corridors, with EASA CS-25 qualification cycles locking in multi-decade supply agreements.
- Glass Fiber:E-glass and S-glass formulations occupy automotive underbody shields and rail interior panels where specific strength requirements sit below carbon fiber thresholds. China's high-speed rail manufacturing hubs specify glass fiber exterior panels to manage axle load economics.
- Aramid Fiber:Kevlar and Twaron aramids penetrate ballistic protection and tire reinforcement layers in heavy-duty truck applications.
- Hybrid Composites:Carbon-glass combinations balance cost and performance in marine hull structures and automotive crash-absorbing elements.
Glass fiber leads volumes today; carbon fiber is gaining share fastest in primary structural applications.
End User:
Customer segments separate by qualification intensity, with aerospace demanding embedded system integration and marine accepting standalone component supply.
- Aerospace:FAA AC 20-107B and EASA CS-25 frameworks govern composite airworthiness for fuselage and wing structures. Boeing and Airbus tier suppliers maintain captive fiber supply chains with five-to-seven-year pre-payment contracts.
- Automotive:EPA Corporate Average Fuel Economy mandates force structural composite adoption in body-in-white applications. Maruti Suzuki and Tata Motors localize production under India's PLI scheme for electric vehicle platforms.
- Marine:German shipyards automate resin transfer molding sequences for hull production, with EU F-Gas Regulation driving reformulation of polyurethane core materials.
- Rail:China's manufacturing hubs specify carbon fiber interiors and glass fiber exterior panels to enable higher operating speeds on expanded high-speed networks.
Automotive commands the broadest volume base; aerospace delivers the steepest margin expansion trajectory.
Application:
Application depth correlates with certification burden, from primary load-bearing structures requiring embedded system validation to non-structural interiors with standalone qualification pathways.
- Structural Components:Primary aircraft structures demand void contents below 1% through vacuum infusion or resin transfer molding. Out-of-autoclave thermoplastic composites with PEEK and PEKK matrices are compressing cycle times for fuselage frames.
- Interiors:Recycled fiber certification pathways are opening for rail interiors and automotive underbody shields under EU Circular Economy Action Plan mandates.
- Exterior Body Panels:Class-A surface requirements drive thermoplastic composite adoption in automotive hoods and decklids.
- Electrical Insulation:Glass-epoxy laminates serve traction motor housings and battery enclosures in electric bus platforms.
Structural components dominate value capture; interiors are expanding most quickly through circularity mandates.
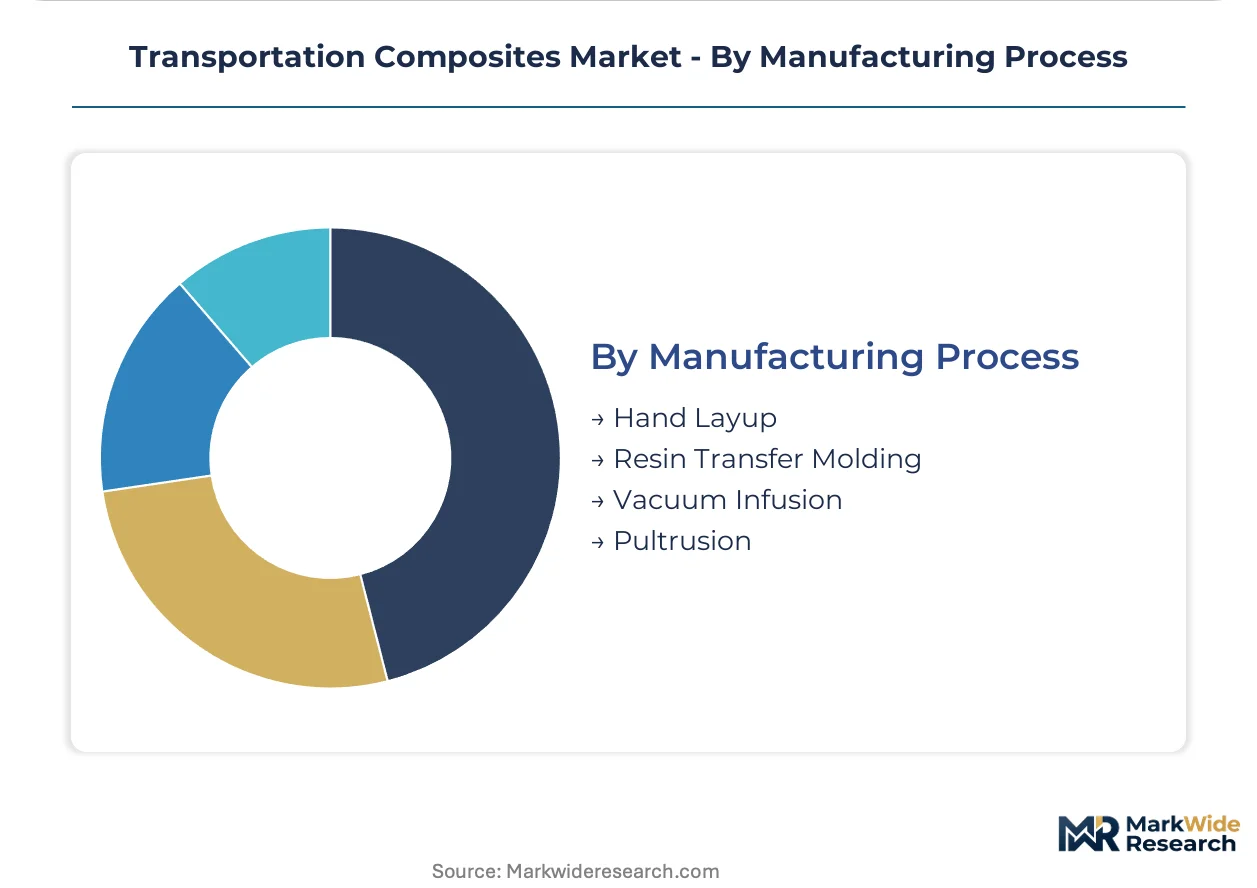
Manufacturing Process:
Process selection hinges on volume scale and geometric complexity, with automated methods displacing manual layup in mid-volume aerospace and automotive programs.
- Resin Transfer Molding:Closed-mold injection yields consistent fiber volume fractions for marine hulls and automotive structural members. German shipyards automate layup sequences to compress labor content.
- Vacuum Infusion:Dry fiber preforms and vacuum-driven resin distribution achieve aerospace-grade void contents without autoclave capital intensity.
- Hand Layup:Open-mold contact molding persists in low-volume marine and rail applications where tooling amortization dominates economics.
- Pultrusion:Continuous profile manufacture serves rail platform edges and automotive bumper beams with consistent cross-sectional properties.
Resin transfer molding anchors current capacity; vacuum infusion is climbing the fastest through out-of-autoclave aerospace qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor anchors composite demand through structural lightweighting programs serving BMW and Volkswagen electric platforms. EPA fuel-economy mandates in the United States and the EU Green Deal's emissions framework are tightening material specifications across all major manufacturing hubs.
United States
Boeing and defense contractors anchor aerospace composite demand through multi-decade supply agreements with pre-payment structures. FAA AC 20-107B certification governs airworthiness standards for primary aircraft structures. The Pacific Northwest manufacturing cluster concentrates autoclave capacity and out-of-autoclave thermoplastic qualification programs.
Germany
BMW and Volkswagen structural programs drive automotive-grade carbon fiber consumption for body-in-white applications. The EU F-Gas Regulation is phasing hydrofluorocarbon blowing agents from polyurethane core materials used in rail and marine sandwich panels. Bavarian shipyards automate resin transfer molding sequences for hull production.
China
High-speed rail manufacturing hubs specify carbon fiber interiors and glass fiber exterior panels to reduce axle loads and enable higher operating speeds. The country's national railway regulator mandates lightweighting standards for expanded network capacity. Yangtze River Delta production centers concentrate filament-winding capacity for hydrogen storage vessels.
Japan
Toray Industries, Mitsubishi Chemical, and Toho Tenax control aerospace-grade carbon fiber precursor supply through integrated PAN production. METI industrial policy supports qualification chains for next-generation aircraft programs. Nagoya aerospace manufacturing corridors embed composite fabrication within tier supplier networks.
India
Maruti Suzuki and Tata Motors localize composite component production under the PLI scheme for electric vehicle platforms. The country's national automotive regulator aligns safety standards with UN ECE frameworks for lightweight structural materials. Gujarat and Tamil Nadu manufacturing corridors attract thermoset and thermoplastic processing investments.
Transportation Composites Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue recycled fiber certification and hydrogen vessel specialization. The supplier base concentrates around aerospace qualification chains and automotive cost-down programs. Three archetypes dominate: integrated fiber-resin producers, independent pre-preg specialists, and regional fabricators serving marine and rail segments. Capacity expansion and backward integration into precursor supply represent the dominant competitive vectors.
Among Japanese integrated producers, Toray Industries Inc. and Mitsubishi Chemical Holdings Corporation exemplify the captive fiber archetype through in-house PAN precursor production. Hexcel Corporation occupies a position within the North American defense and commercial aviation pre-preg tier. Owens Corning anchors glass fiber supply for automotive underbody and rail interior applications where cost thresholds override carbon fiber performance premiums.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Teijin Limited |
| Owens Corning |
| Mitsubishi Chemical Holdings Corporation |
| Hexcel Corporation |
| SGL Group |
| Solvay S.A. |
| Royal DSM |
| Jushi Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between aerospace-qualified pre-preg and commodity glass fiber creates divergent margin architectures that reshape procurement patterns. EASA CS-25 and FAA AC 20-107B qualification cycles lock premium-tier suppliers into multi-year offtake agreements with pre-payment structures, while automotive and rail buyers negotiate spot-market positions on standardized E-glass formulations.
Pricing Analysis
Acrylonitrile feedstock volatility passes through directly to PAN-based carbon fiber quotations, with oil-indexed precursor contracts creating quarterly repricing exposure for Tier-1 aerospace suppliers. Three-tier pricing structure across aerospace-qualified, automotive-structural, and commodity-industrial grades differentiates by certification burden and void-content specifications. Cost compression in automotive-grade carbon fiber is intensifying because BMW and Volkswagen structural programs demand cost-down trajectories incompatible with legacy aerospace margin models. Glass fiber buyers in rail interior applications exhibit highest price sensitivity, while defense contractors absorbing North American pre-preg supply accept premium positioning without volume negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Japanese integrated producers controlling aerospace-grade PAN precursor capacity. Manufacturing concentration clusters in Japan, Germany, and China's Yangtze River Delta, with Toray Industries and Mitsubishi Chemical anchoring qualification chains through in-house fiber production. Raw material dependencies rest on acrylonitrile monomer, petroleum-derived epoxy resins, and thermoplastic PEEK pellets subject to specialty chemical allocation protocols. Tariff exposure on carbon fiber imports into European automotive corridors threatens cost structures for BMW body-in-white programs. Distribution runs through qualified Tier-1 aerospace fabricators and direct OEM supply agreements for high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
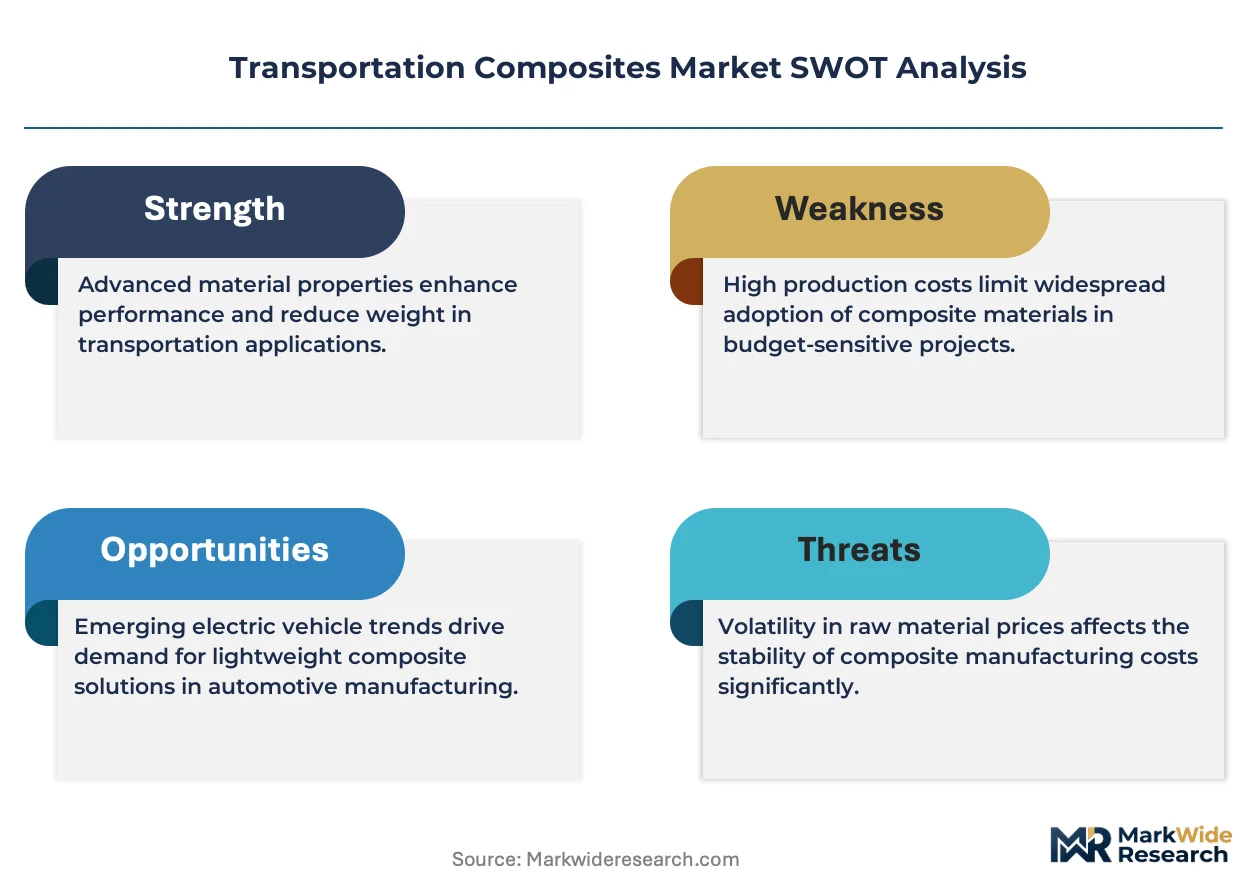
Transportation composites constitute a late-cycle quality story as EPA Corporate Average Fuel Economy mandates and EU Green Deal emissions targets force structural lightweighting beyond aluminum substitution limits. Demand is shifting toward primary-structure aerospace qualifications and hydrogen vessel filament-winding specifications that command premium positioning.
For Market Incumbents: Cement captive fiber supply through backward integration into PAN precursor production or five-to-seven-year pre-payment contracts with aerospace Tier-1 suppliers. Expand out-of-autoclave thermoplastic qualification capacity in the Pacific Northwest and Bavarian manufacturing corridors to defend against aluminum-lithium substitution in wing rib applications. Lock EASA CS-25 certification timelines early to block rapid formulation innovation from emerging resin competitors. For New Entrants and Emerging Players: Begin with recycled fiber certification pathways for non-structural rail interiors and automotive underbody shields under EU Circular Economy Action Plan mandates. India's PLI scheme for electric vehicle platforms offers the most penetrable geography, with Maruti Suzuki and Tata Motors localizing composite component production. Pursue filament-winding specialization for Type IV hydrogen storage vessels serving heavy-duty truck and bus applications as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where qualification bottlenecks and 18-36 month certification cycles create moats around incumbent positions. Long-term viability favors integrated fiber-resin producers with captive precursor supply and established FAA-EASA qualification chains over standalone fabricators. Watch recycled fiber certification throughput rates as the inflection indicator for circularity-mandated segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray Industries and Mitsubishi Chemical anchor margin control through in-house acrylonitrile conversion capacity. |
| Out-of-Autoclave Thermoplastic Qualification | Boeing and Airbus tier suppliers compress cycle times for carbon fiber/PEKK fuselage frames and floor beams. |
| Long-term Supply Agreement with Pre-payment | North American defense programs lock five-to-seven-year pre-preg contracts creating captive supplier relationships. |
| Recycled Fiber Certification Investment | EU Circular Economy Action Plan opens pathways for non-structural rail interiors and automotive underbody shields. |
| Hydrogen Vessel Filament-winding Capacity | Yangtze River Delta production centers capture Type IV pressure vessel demand from heavy-duty truck programs. |
Study Parameters
Direct dialogue with aerospace procurement directors, automotive platform engineers, marine hull production managers, and rail interior specification leads grounded the qualitative foundation. Secondary validation drew from FAA AC 20-107B certification databases, EASA CS-25 airworthiness filings, EPA Corporate Average Fuel Economy compliance reports, and EU F-Gas Regulation implementation tracking. Bottom-up fiber volume estimates by application depth were triangulated against top-down OEM procurement disclosures across the analysis window.
Bottom-up modeling segmented demand by fiber chemistry, manufacturing process, application depth, and end-use qualification intensity. Aerospace primary structures, automotive body-in-white, marine hulls, and rail interiors formed the core segmentation axes, with hydrogen storage vessels modeled as an emerging application cluster. CAGRs were derived from production capacity expansion announcements, OEM platform launch timelines, and regulatory mandate phase-in schedules. Forecast inputs incorporated acrylonitrile price trajectory assumptions and thermoplastic resin maturation curves for PEEK and PEKK matrices.
Several conditions sit outside the modeled scope, including breakthrough aluminum-lithium alloy formulations displacing composite wing ribs, trade policy disruptions affecting Japanese carbon fiber exports, and revolutionary recycling technologies collapsing recycled fiber certification timelines. Forecasts reflect documented assumptions regarding qualification cycle durations and precursor cost pass-through elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Composite Rollers Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
High Performance Composites Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Tow Prepreg Market
Composite Materials
Global Composite Materials Market
Composite Materials
Biocomposites Market
Composite Materials
United States Marine Composites Market