
 US Hydrochloric Acid Market | 2026-2036
US Hydrochloric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
US Hydrochloric Acid Market Intelligence
Technical grade specification is rotating toward higher-purity formulations as downstream oilfield service contractors tighten procurement standards. Olin Corporation leverages captive chlorine-alkali capacity to anchor supply security across the Gulf Coast. Westlake Chemical Corporation sustains cost leadership through integrated vinyl chloride monomer operations that generate hydrochloric acid as a co-product. Tronox Holdings plc differentiates via titanium dioxide-derived acid streams serving specialty chemical buyers.
Hydrochloric acid is an aqueous solution of hydrogen chloride gas, typically manufactured at concentrations ranging from 32% to 37% by weight through the combustion of chlorine with hydrogen or as a by-product of chlorination processes; its primary industrial purpose centers on pH adjustment, metal surface preparation, and carbonate matrix dissolution in oilfield stimulation. Industrial grade formulations dominate volume flows into steel pickling and water treatment applications where cost efficiency outweighs purity thresholds. Reagent grade segments occupy concentrated margin pools serving analytical laboratories and pharmaceutical quality control operations, while food grade certification requirements constrain supplier participation to a narrow set of FDA-registered producers. Direct sales channels control the majority of bulk tonnage movements to integrated chemical processors and major oilfield service companies.
EPA oversees discharge limitations under the Clean Water Act that constrain spent acid disposal practices, while OSHA enforces workplace exposure ceilings at 5 parts per million that shape packaging and handling infrastructure investments. DOT hazardous materials regulations govern tanker and IBC transport modes across interstate corridors, with particular enforcement intensity along Texas and Louisiana chemical artery highways. Stakeholders must monitor evolving PFAS contamination screening protocols that could extend to acid-supplied water treatment chemistries and alter product qualification requirements for municipal utility contracts.
Market Dynamics
EPA effluent limitation guidelines are compressing disposal pathways for spent acid from steel pickling and oilfield operations, forcing capital redeployment toward closed-loop regeneration systems and zero-liquid-discharge infrastructure across Gulf Coast processing corridors.
Growth Catalysts
- Permian Basin acidizing intensity:Oilfield service contractors are expanding hydrochloric acid volumes per well completion as operators target deeper carbonate formations in West Texas and southeastern New Mexico.
- OSHA permissible exposure limit enforcement:Tighter workplace safety inspections are accelerating packaging upgrades to closed-loop transfer systems and vapor-recovery units at bulk terminals.
- Membrane cell technology diffusion:Chlor-alkali producers deploying membrane electrolysis generate higher-purity acid by-product streams that satisfy tightening technical grade specifications without incremental purification investment.
Market Restraints
- Chlorine feedstock volatility:Natural gas price swings directly transmit to chlorine production economics, compressing margins for integrated acid manufacturers during winter demand spikes.
- Gulf Coast supply concentration:Over sixty percent of domestic merchant capacity clusters within Texas and Louisiana hurricane exposure zones, creating force majeure vulnerability during Atlantic storm seasons.
- Organic acid substitution in food processing:Citric and phosphoric acid blends are displacing hydrochloric acid in certain pH adjustment applications where flavor neutrality commands premium positioning.
Strategic Opportunities
- Appalachian shale reactivation:Marcellus and Utica formation operators are reviving acidizing programs as natural gas prices recover, opening underserved demand nodes in Ohio and Pennsylvania.
- Carbon capture solvent regeneration:Amine-based post-combustion capture systems require continuous acid make-up for solvent reclamation, creating incremental offtake from power sector retrofits.
- Rail-to-barge modal shift:New Ohio River terminal infrastructure enables cost-competitive supply to inland refineries and chemical processors currently served by higher-cost truck delivery.
Industry Challenges
- Corrosion engineering specialization:Qualified metallurgists and materials scientists capable of specifying alloy selection for high-temperature acid service remain scarce across the domestic talent pool.
- Zero-liquid-discharge capex burden:Full regeneration system installations demand eight-figure capital commitments that strain mid-size merchant producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hydrochloric Acid Market |
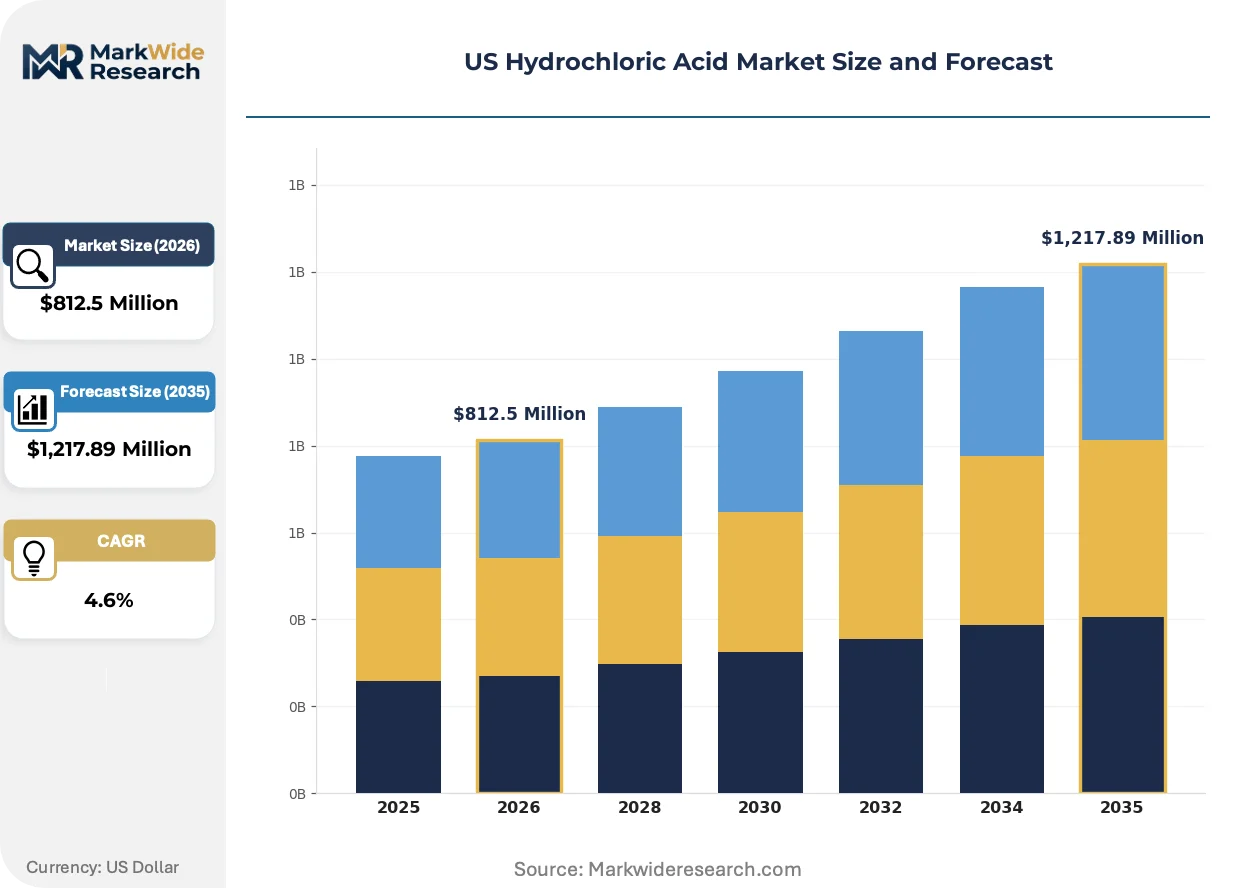
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,217.89 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Industrial Grade, Reagent Grade End Use Industry: Metal Processing, Oil & Gas, Water Treatment, Fertilizers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Packaging Type: Drums, Tankers, IBCs, Cylinders |
| Companies Covered | Olin Corporation, Westlake Chemical Corporation, Tronox Holdings plc, Occidental Petroleum Corporation, ASHTA Chemicals, Thermo Fisher Scientific Inc., ERCO Worldwide, Detrex Corporation, Formosa Plastics Corporation, U.S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hydrochloric Acid Market Strategic Shifts & Innovations
Process intensification and regulatory digitization are compressing traditional supply chain configurations while opening new service-layer revenue pools for asset-light intermediaries and technology-enabled logistics platforms.
On-site acid generation through electrochemical chlorine-alkali mini-plants is miniaturizing bulk transport requirements for remote oilfield locations. Permian Basin operators with scattered well pads are piloting containerized systems that eliminate tanker truck dependency. This distributed production architecture is compressing terminal infrastructure utilization rates in peripheral supply zones.
EPA's forthcoming PFAS analytical methods expansion under the Safe Drinking Water Act is tightening qualification protocols for acid-supplied water treatment chemistries. Municipal utility procurement departments are demanding expanded chain-of-custody documentation and third-party contamination screening. Technical grade suppliers with pre-positioned testing capabilities are capturing specification advantage in Great Lakes and Northeast utility contracts.
Digital freight matching platforms are fragmenting traditional tanker fleet contracting relationships. Oilfield service companies now source spot acid deliveries through algorithmic load boards rather than annual master service agreements. This liquidity injection is compressing contract tenors and amplifying price volatility during peak drilling windows in the Eagle Ford and Bakken formations.
US Hydrochloric Acid Market Segmentation
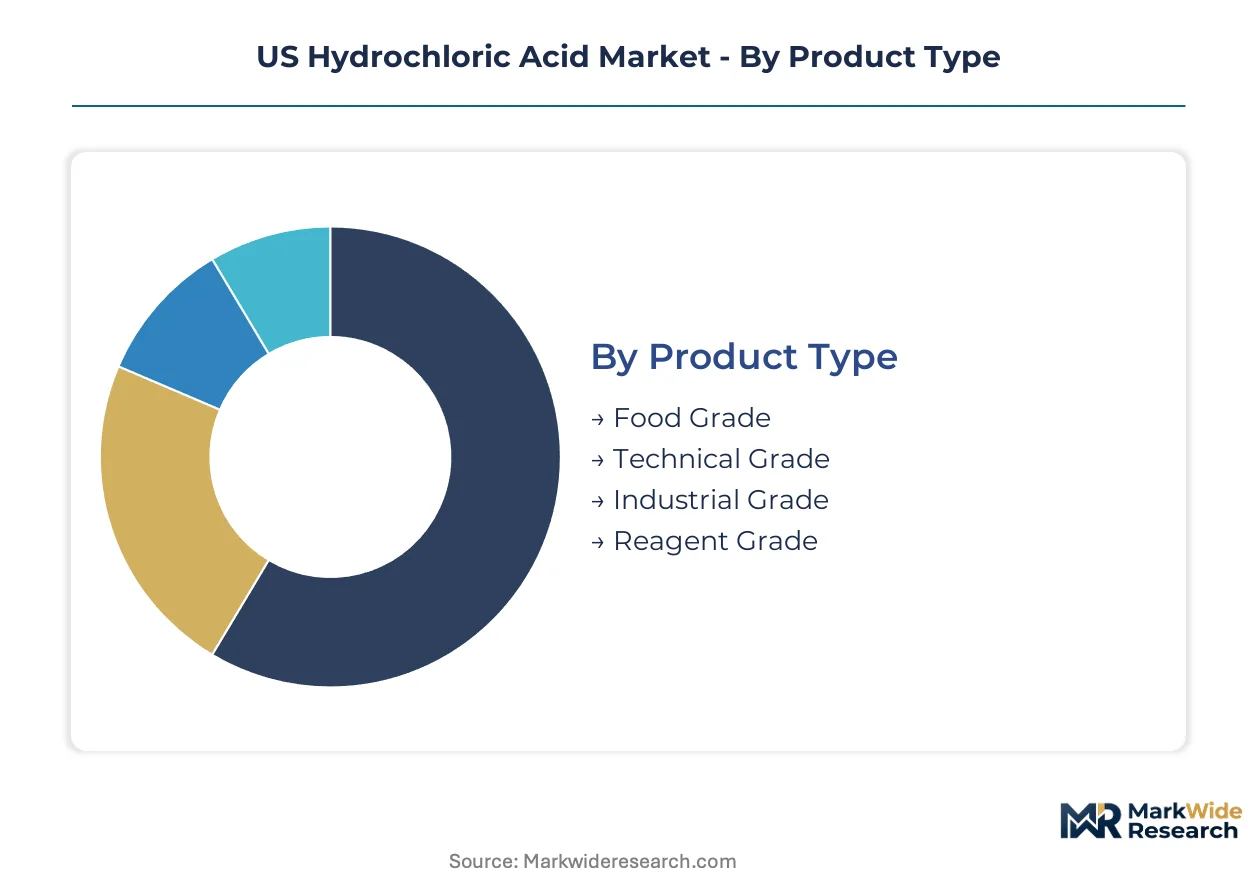
Grade purity thresholds and packaging specifications fragment the US hydrochloric acid landscape into distinct procurement tiers. Oilfield service contractors, steel mills, and municipal utilities each impose qualification protocols that reshape supplier positioning across product and channel dimensions.
Product Type:
Technical and industrial grades dominate domestic merchant flows, while food and reagent grades serve narrower export-adjacent certification requirements.
- Technical Grade:Formulations meeting 32-37% concentration with controlled heavy metal specifications anchor Permian Basin acidizing programs. West Texas operators demand this grade for carbonate formation dissolution where corrosion inhibitors must integrate predictably.
- Industrial Grade:Standard concentration solutions serve steel pickling baths across Ohio and Indiana mill corridors where cost efficiency outweighs trace impurity constraints. EPA effluent guidelines are compressing spent acid disposal economics for this segment.
- Food Grade:FDA-registered production protocols constrain supplier participation to chlor-alkali operators with dedicated equipment trains and batch certification documentation.
- Reagent Grade:Ultra-high purity specifications serve analytical laboratories and pharmaceutical quality control operations with lot-specific assay certificates.
Industrial grade commands the established base. The steepest expansion runs through technical grade.
End Use Industry:
Volume concentration tilts toward oilfield and metal processing applications where supply security and logistics integration determine contract awards.
- Oil & Gas:Well acidizing operations in the Permian Basin and Eagle Ford shale formations consume bulk technical grade for carbonate matrix stimulation. Deeper lateral lengths per well completion are intensifying acid volumes per stage.
- Metal Processing:Steel pickling lines in Indiana, Ohio, and Pennsylvania rely on industrial grade for oxide scale removal prior to cold rolling operations.
- Water Treatment:Municipal pH adjustment and ion exchange regeneration applications favor technical grade with expanded chain-of-custody documentation under tightening PFAS screening protocols.
- Fertilizers:Phosphate rock digestion and intermediate chemical synthesis consume industrial grade in Florida and Louisiana processing corridors.
Oil & Gas anchors volume concentration. Water Treatment is climbing the fastest on regulatory compliance spending.
Distribution Channel:
Channel selection tracks customer scale and integration depth, with direct sales controlling bulk movements and intermediaries serving fragmented accounts.
- Direct Sales:Annual master service agreements govern tanker deliveries to integrated chemical processors and major oilfield service companies with dedicated terminal access.
- Distributors:Regional chemical distributors maintain drum and IBC inventories for mid-size industrial accounts lacking bulk storage infrastructure.
- Wholesalers:Secondary market participants aggregate spot volumes for construction and maintenance contractors with intermittent demand patterns.
- Online Retail:E-commerce platforms serve laboratory and small-scale industrial buyers requiring rapid fulfillment of packaged quantities.
Direct sales commands the established base. Digital freight matching is gaining share fastest in spot market segments.
Packaging Type:
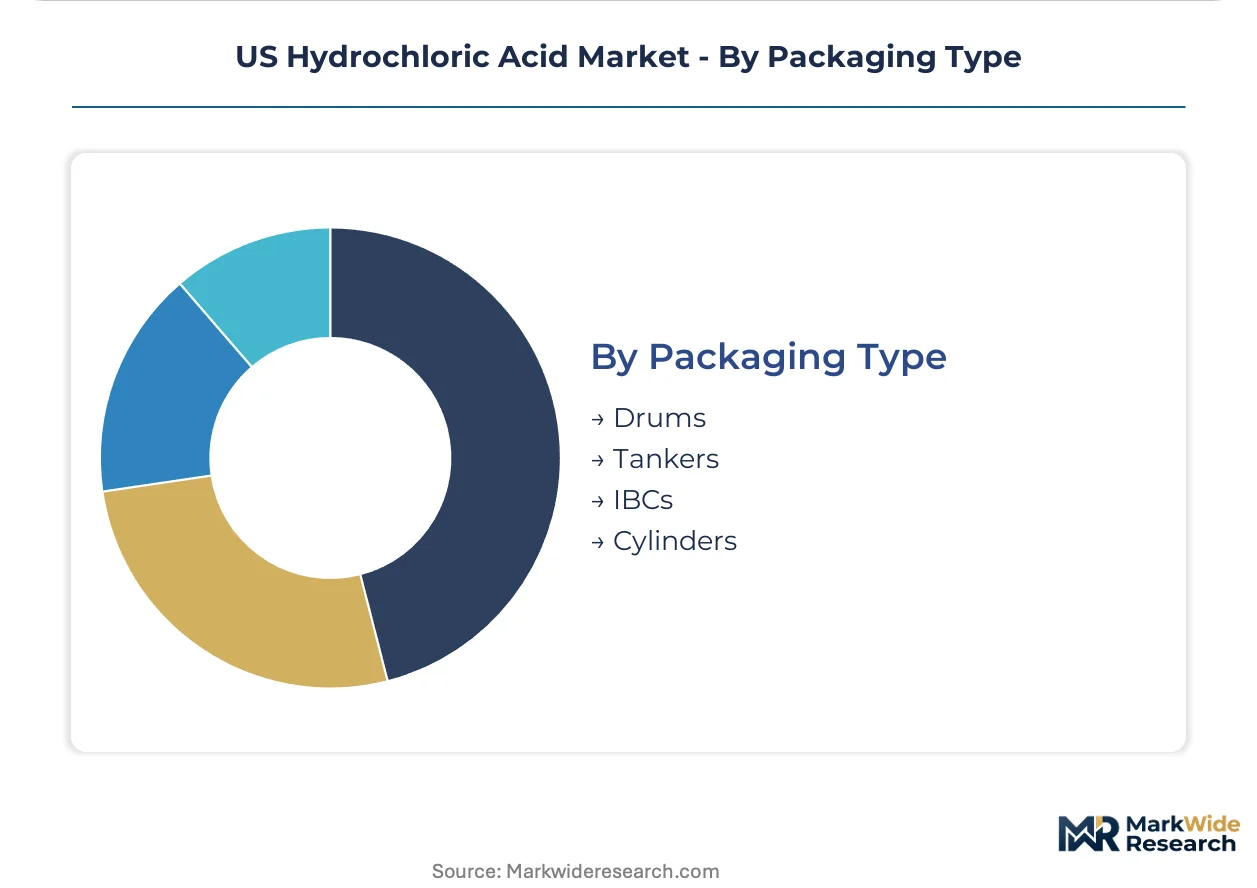
Packaging selection reflects transport economics and OSHA exposure limit compliance, with bulk modes dominating Gulf Coast corridors and containerized solutions penetrating inland markets.
- Tankers:Dedicated acid-resistant tank trailers and railcars move bulk technical and industrial grades along Texas and Louisiana chemical artery highways under DOT hazardous materials enforcement.
- IBCs:Intermediate bulk containers enable closed-loop transfer systems that satisfy tightening OSHA permissible exposure limit inspections at bulk terminals.
- Drums:Standardized polyethylene and composite drums serve metal processing and water treatment accounts with moderate volume requirements and limited handling infrastructure.
- Cylinders:Pressurized containers support specialized applications requiring anhydrous hydrogen chloride gas rather than aqueous solution delivery.
Tankers command the established base. IBCs are expanding most quickly on safety infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant acid capacity clusters along the Texas-Louisiana chemical corridor, with hurricane exposure creating recurring force majeure risks that reshape inland supply routing during Atlantic storm seasons.
Texas Gulf Coast
Permian Basin acidizing programs and Eagle Ford shale completions consume technical grade for carbonate formation stimulation. EPA Region 6 enforces Clean Water Act discharge limits that constrain spent acid disposal from oilfield operations. Houston and Beaumont host integrated chlor-alkali complexes generating acid as captive co-product for regional distribution.
Louisiana Chemical Corridor
Petrochemical processors along the Mississippi River between Baton Rouge and New Orleans demand industrial grade for vinyl chloride monomer synthesis and intermediate chemical production. Louisiana Department of Environmental Quality administers state-level air quality permits affecting acid handling infrastructure. Lake Charles regeneration facilities service steel pickling accounts across the lower Midwest with closed-loop recovery systems.
Appalachian Basin
Marcellus and Utica shale operators in Ohio and Pennsylvania are reviving acidizing intensity as natural gas prices recover from cyclical lows. Ohio EPA oversees underground injection control permits for produced water and spent acid management. Youngstown and Pittsburgh corridor distributors are expanding rail-served terminal capacity to capture reactivated demand.
Midwest Industrial Belt
Indiana and Ohio steel mills operate continuous pickling lines requiring industrial grade for hot-rolled coil surface preparation. OSHA Region 5 conducts workplace exposure inspections at bulk handling facilities serving metal processing accounts. Gary and Cleveland mill complexes maintain dedicated acid regeneration partnerships with merchant suppliers to minimize disposal liabilities.
Great Lakes Water Treatment Corridor
Municipal utilities across Michigan and Wisconsin are tightening procurement standards under emerging PFAS screening protocols for acid-supplied treatment chemistries. EPA Region 5 Safe Drinking Water Act enforcement is expanding chain-of-custody documentation requirements. Milwaukee and Detroit metropolitan water authorities now mandate third-party contamination certification for technical grade suppliers.
US Hydrochloric Acid Market Key Industry Players
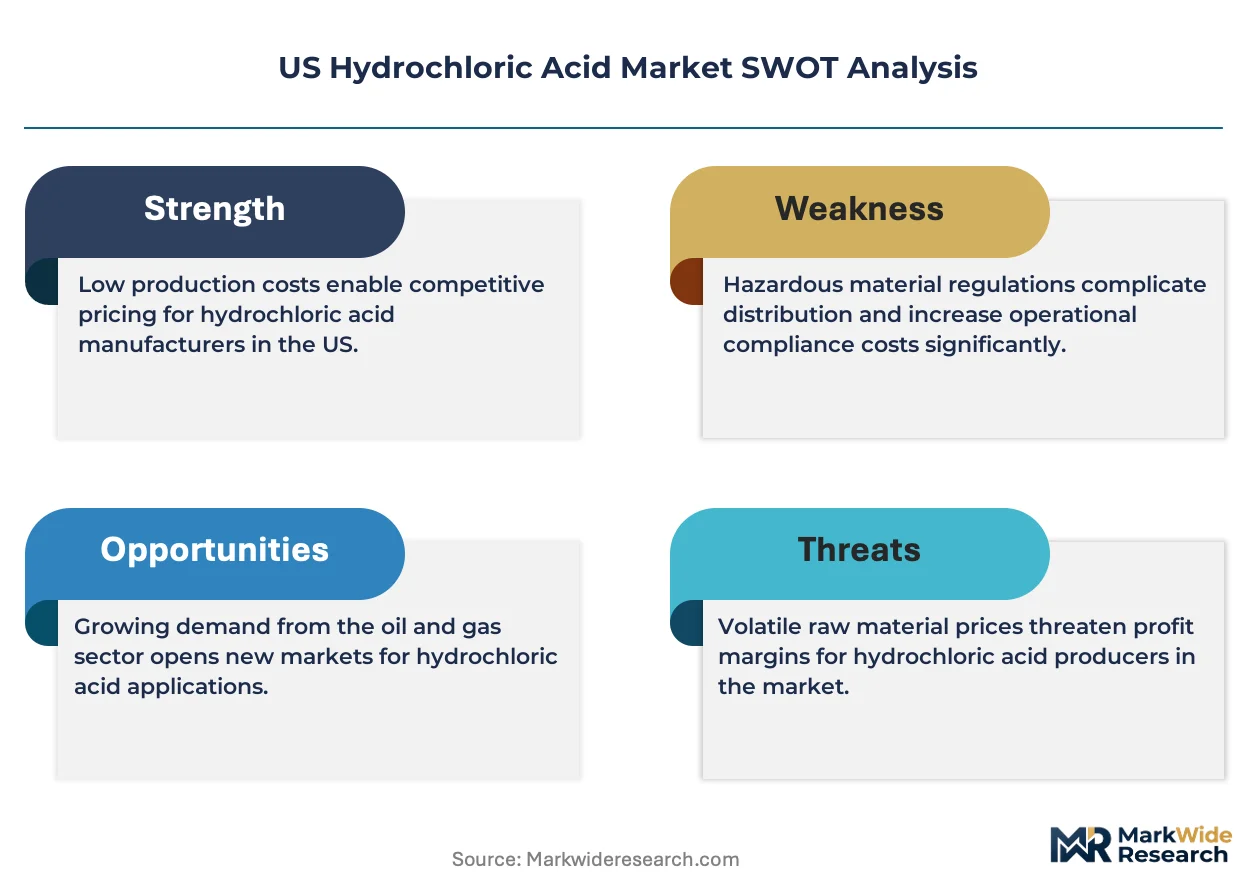
Concentration sits with integrated chlor-alkali operators possessing captive chlorine feedstock and co-product acid streams. The competitive structure tiers across three archetypes: multinational chemical conglomerates with membrane cell technology, regional merchant producers dependent on purchased chlorine, and specialty titanium dioxide-derived acid suppliers. Dominant competitive moves include backward integration into salt and power inputs, and strategic terminal infrastructure expansion along rail and barge corridors serving inland markets.
Among integrated chemical producers, Olin Corporation, Westlake Chemical Corporation, and Tronox Holdings plc exemplify divergent feedstock positioning within the merchant acid value chain. Olin represents the captive chlor-alkali archetype leveraging membrane electrolysis for high-purity acid generation. Westlake occupies the vinyl chloride monomer co-product position where acid emerges as economically advantaged secondary output. Tronox sits within the titanium dioxide-derived specialty tier serving chemical buyers requiring specific impurity profiles.
| Leading Market Players |
|---|
| Olin Corporation |
| Westlake Chemical Corporation |
| Tronox Holdings plc |
| Occidental Petroleum Corporation |
| ASHTA Chemicals |
| Thermo Fisher Scientific Inc. |
| ERCO Worldwide |
| Detrex Corporation |
| Formosa Plastics Corporation, U.S.A. |
| Others |
Cost & Logistics Intelligence
Membrane cell technology substitution for diaphragm and mercury cell processes is redrawing the Gulf Coast production map while compressing technical grade premiums as higher-purity acid becomes standard co-product output rather than specialty manufacture.
Pricing Analysis
OSHA permissible exposure limit enforcement dictates the pricing tier structure across packaging and handling infrastructure investments. Three-tier pricing structure across technical, industrial, and reagent grade levels segments buyers by purity certification and chain-of-custody documentation requirements. Cost compression in industrial grade is intensifying because EPA effluent guidelines are raising spent acid disposal costs for steel pickling accounts. Municipal utilities demonstrate highest price sensitivity due to budget constraints, while pharmaceutical quality control operations show least sensitivity given lot-specific assay requirements.
Supply Chain Analysis
Port congestion along Houston Ship Channel and container availability constraints in Gulf Coast chemical terminals are amplifying inbound logistics costs for specialty chemical feedstocks. Domestic merchant capacity draws from Texas, Louisiana, and Ohio production corridors. Raw material dependencies center on chlorine gas, hydrogen feedstock, and salt brine inputs. Single-source vulnerability concentrates in Gulf Coast hurricane exposure zones where over sixty percent of capacity faces recurring force majeure risk. Distribution runs through dedicated tanker fleets and rail-served terminals with emerging digital freight matching penetration in spot market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified corrosion engineers and materials scientists capable of specifying alloy selection for high-temperature acid service remain scarce across the domestic talent pool, constraining operational expansion and maintenance reliability for merchant producers and downstream processors alike.
For Market Incumbents: Consolidate terminal infrastructure positions along rail and barge corridors serving inland markets to defend against digital freight matching platform disintermediation. Deepen backward integration into captive salt and power inputs to buffer chlorine feedstock volatility. Expand closed-loop regeneration partnerships with steel pickling accounts to lock in long-term offtake and minimize disposal liability exposure. For New Entrants and Emerging Players: Lead with Appalachian Basin rail-served terminal capacity to capture reactivated Marcellus and Utica shale acidizing demand as natural gas prices recover. Target carbon capture solvent regeneration applications at power sector retrofit sites where amine-based post-combustion systems require continuous acid make-up. Pursue direct sales channel relationships with mid-size oilfield service contractors bypassing incumbent distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chlor-alkali operators with membrane cell technology and captive infrastructure assets. Long-term viability hinges on regulatory compliance capabilities and zero-liquid-discharge system deployment across the projection horizon. Acquisition targets should demonstrate pre-positioned PFAS testing capabilities and EPA Region 5 utility contract penetration. Monitor EPA Safe Drinking Water Act analytical methods expansion as inflection indicator for qualification protocol tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt and Power Inputs | Captive chlorine feedstock secures margin stability against natural gas price volatility. |
| Zero-Liquid-Discharge System Deployment | EPA effluent guidelines are compressing disposal economics for spent acid regeneration. |
| Rail-to-Barge Modal Infrastructure Expansion | Ohio River terminal access enables cost-competitive supply to inland chemical processors. |
| PFAS Contamination Screening Capabilities | Third-party certification pre-positioning captures Great Lakes municipal utility procurement. |
| Digital Freight Matching Platform Integration | Algorithmic load board liquidity is fragmenting traditional tanker fleet contracting relationships. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, American Chemistry Council industry reports, EPA enforcement databases, and customs trade records. Primary interviews engaged chlor-alkali plant managers, oilfield service procurement leads, steel mill technical directors, municipal utility chemical buyers, and hazardous materials logistics operators. Bottom-up volume modeling triangulates against top-down macroeconomic demand indicators across the analysis window.
Segmentation dimensions modeled include grade purity tier, end-use industry vertical, packaging format specification, and regional production hub concentration. CAGRs derive from regression analysis against oil and gas drilling activity indices, steel production forecasts, and water treatment capital expenditure trajectories. Industry-specific inputs incorporate Permian Basin well completion intensity projections and membrane cell technology diffusion curves.
The analysis sits within stated boundaries; outcomes outside sustained oilfield activity levels, stable regulatory enforcement intensity, and intact Gulf Coast infrastructure would require recalibration. Forecasts reflect assumptions regarding chlorine feedstock cost trajectories and hurricane season severity patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Global Capric Acid Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
China Starch and Starch Derivatives Market