
 North America Potassium Formate Market | 2026-2036
North America Potassium Formate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Potassium Formate Market Analytics
Premium pharmaceutical and food-grade potassium formate is consolidating around specialized purification capabilities and certified supply chains, while commodity industrial grades compete on bulk volume and regional logistics. Eastman Chemical Company leverages its integrated acetic acid and formate chemistry platform to sustain cost-advantaged production at scale. TETRA Technologies anchors its position through dedicated oilfield service channels and downhole fluid formulation expertise. BASF SE differentiates via global technical service networks that extend specification-grade reliability into North American specialty applications.
Potassium formate is the potassium salt of formic acid, typically supplied as a clear aqueous solution with density ranging from 1.57 to 2.30 g/cm³ depending on concentration, valued for its high thermal stability, low corrosion profile, and complete biodegradability in environmental release scenarios. Industrial grade material dominates current volume flows through oilfield drilling and completion applications, while pharmaceutical grade commands the strongest margin pool due to stringent USP certification and batch-level documentation requirements. The deicing application segment shows structural expansion potential as transportation departments evaluate chloride-free runway and bridge deck treatments across freeze-thaw cycling environments.
The EPA regulates potassium formate discharge under the Clean Water Act and oilfield waste classifications, while OSHA mandates handling protocols through Hazard Communication Standard provisions for formate salt exposure. FDA oversight applies to food-grade and pharmaceutical-grade specifications through Food Chemicals Codex and USP monograph compliance, directly shaping product certification costs and market access barriers. Stakeholders must monitor evolving state-level groundwater protection rules and procurement specifications from departments of transportation to anticipate grade-mix shifts and certification investments.
Market Dynamics
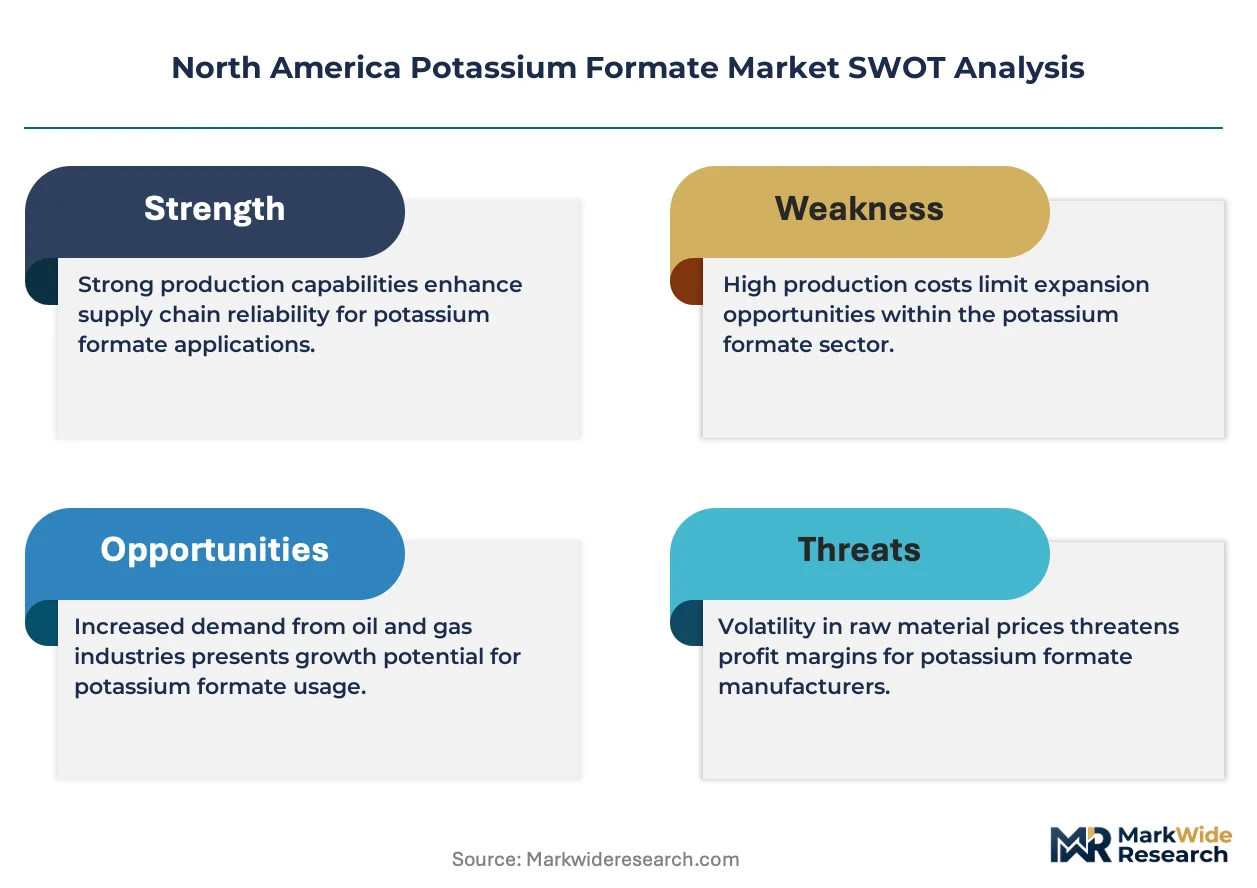
The EPA's groundwater protection mandates for oilfield operations are systematically displacing calcium chloride and sodium bromide brines across the Permian Basin and Bakken formation, compressing demand timelines for biodegradable alternatives.
Growth Catalysts
- EPA Underground Injection Control revisions:Stricter Class II well standards accelerate operator migration from halide salts to formate-based completion fluids in Texas and North Dakota shale plays.
- Freeze-thaw infrastructure degradation:State transportation departments in Minnesota, Wisconsin, and Michigan pilot potassium formate runway deicers to extend concrete service life versus magnesium chloride treatments.
- Shale well complexity escalation:Extended-reach laterals above 15,000 feet demand thermally stable, low-corrosion brines that potassium formate delivers at 180°C bottom-hole temperatures.
Market Restraints
- Formic acid feedstock volatility:Methyl formate and carbon monoxide pricing swings compress margin predictability for integrated producers.
- Gulf Coast supply concentration:Over 70% of North American formate capacity clusters within 200 miles of Houston, creating hurricane exposure and logistics chokepoints.
- Technical density ceiling:Saturated potassium formate solutions top out at 2.30 g/cm³, forcing heavy oil operators to blend with cesium formate or zinc bromide for ultra-high-pressure wells.
Strategic Opportunities
- Canadian oil sands thermal operations:SAGD producers in Alberta evaluate formate brines for steam chamber stability versus traditional sodium silicate systems.
- Pharmaceutical-grade purification arbitrage:USP certification capacity scarcity creates margin expansion for batch-level documentation and endotoxin-controlled supply chains.
- Department of Transportation procurement mandates:Chloride-free bridge deck specifications in New York, Massachusetts, and Illinois open specification-grade deicing contracts.
Industry Challenges
- Specialized formate chemistry expertise:Oilfield fluid engineers with downhole formate formulation experience command 40% wage premiums versus conventional brine specialists.
- Multi-grade certification timelines:Simultaneous FDA Food Chemicals Codex, USP, and EPA Safer Choice approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Potassium Formate Market |
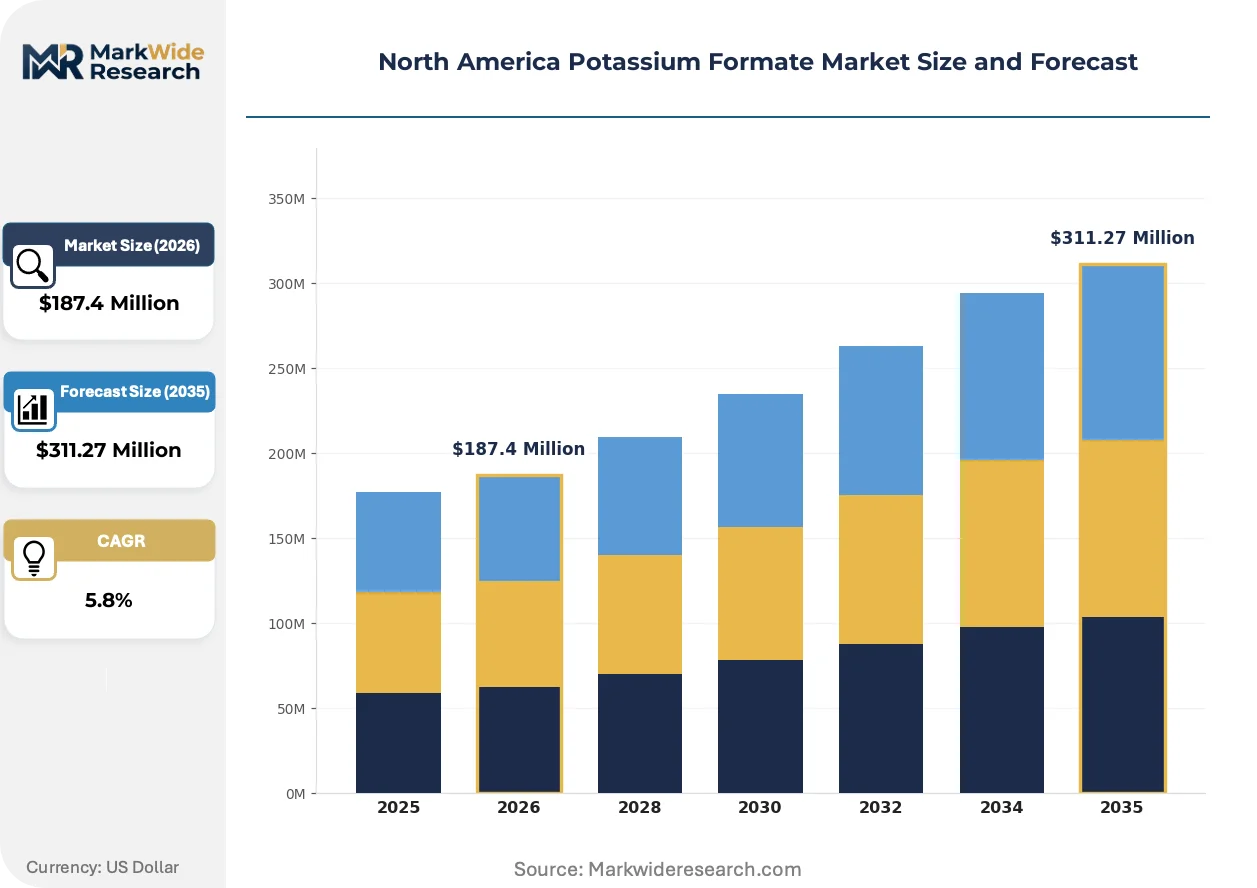
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Agricultural Grade Application: Deicing, Animal Feed, Oilfield, Chemical Processing End User: Agriculture, Oil & Gas, Food Industry, Manufacturing Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Eastman Chemical Company, American Elements, TETRA Technologies, BASF SE, Dynalene, Hawkins, Honeywell International, Clariant, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Potassium Formate Market Evolving Landscape
Formate chemistry platforms are converging with digital fluid monitoring systems and regenerative brine recovery loops, compressing the traditional single-use model toward closed-loop economics.
Continuous density and corrosion sensors embedded in drilling risers are unifying real-time formate concentration management with automated chemical injection skids. Operators in the Delaware Basin deploy these integrated systems to cut brine waste volumes by half. The technology is unifying formate service contracts around performance-per-barrel metrics rather than bulk volume supply.
EPA's finalized methane emissions rules and state-level groundwater protection statutes in Colorado, New Mexico, and Pennsylvania now explicitly reference biodegradable drilling fluid alternatives in permit scoring. Oilfield service procurement teams weight formate formulations higher in environmental compliance matrices. Heavy oil thermal projects in California's Kern County face the steepest compliance cost escalation, accelerating local formate adoption.
Integrated supply contracts are displacing spot-market potassium formate purchases among Permian Basin independents. Large operators now demand five-year volume commitments with embedded price collars and dedicated storage infrastructure. This consolidation is most visible among Delaware Basin private equity-backed producers seeking to lock in chemical costs across multi-pad development programs.
North America Potassium Formate Market Segmentation
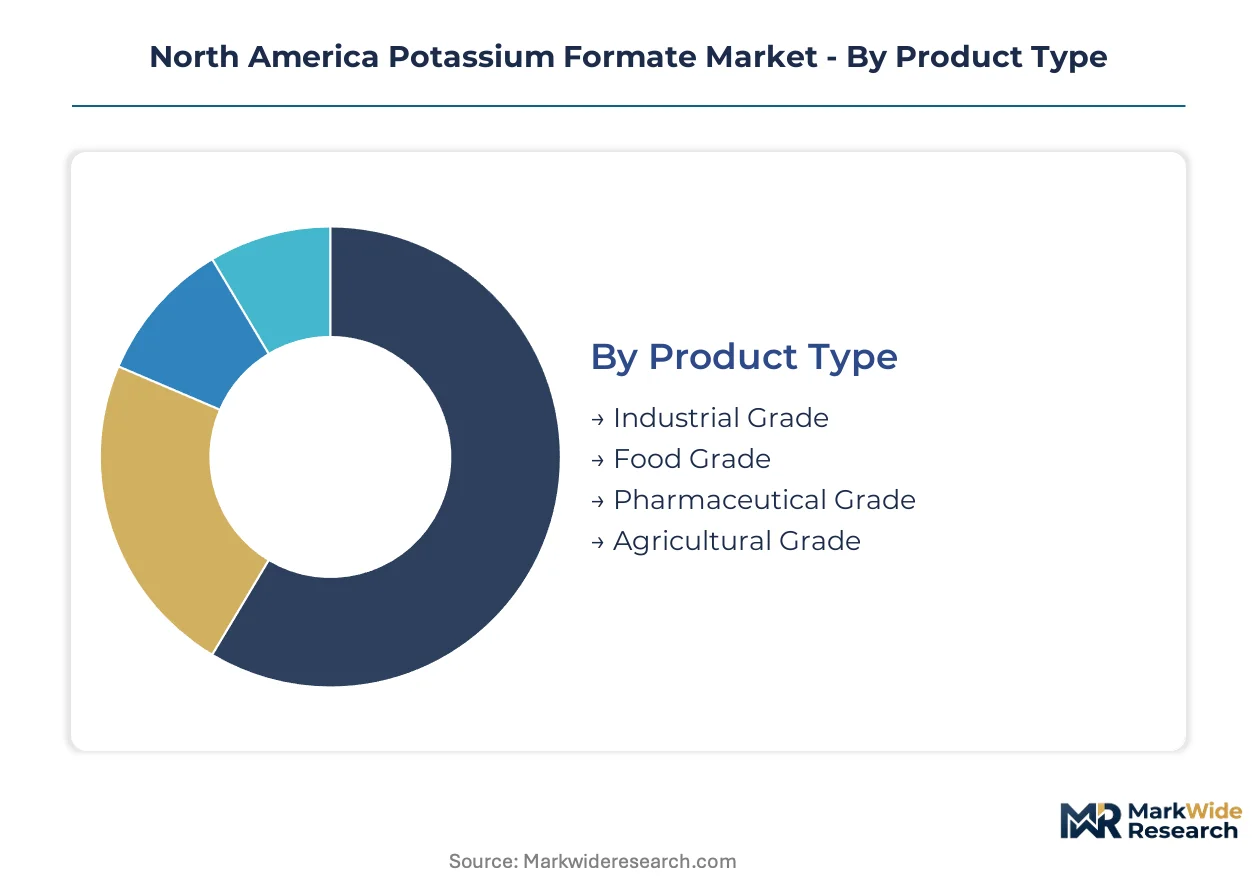
Potassium formate supply chains stratify sharply across certification tiers, with oilfield procurement dominating volume flows while pharmaceutical and food-grade channels extract premium returns through purification overhead. Understanding these segment boundaries clarifies where capital deploys for margin defense versus market share expansion.
Product Type:
Capacity concentrates along the Texas Gulf Coast, where integrated acetic acid and formate chemistry platforms achieve feedstock arbitrage unavailable to standalone producers.
- Industrial Grade:Clear aqueous solutions ranging from 1.57 to 2.30 g/cm³ density serve drilling fluid formulations across the Permian Basin and Bakken formation. EPA groundwater protection mandates in Texas and North Dakota are systematically displacing calcium chloride brines, concentrating procurement among operators with multi-pad development programs.
- Pharmaceutical Grade:USP-certified material demands batch-level documentation, endotoxin control, and dedicated purification trains. Scarcity of certified capacity creates margin expansion for producers willing to absorb 18-24 month approval timelines and specialized quality systems.
- Food Grade:FDA Food Chemicals Codex compliance shapes specification requirements for preservation and acidulant applications. Distribution runs through certified food chemical distributors with temperature-controlled logistics.
- Agricultural Grade:Lower-purity material serves silage preservation and feed acidification with reduced documentation overhead. Regional blending operations in the Midwest capture volume through proximity to concentrated livestock operations.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
Cost tier differentiation separates commodity brine replacement from specification-driven deicing contracts with extended performance guarantees.
- Oilfield:Completion and workover fluids leverage thermal stability above 180°C and low corrosion profiles for extended-reach laterals. Delaware Basin operators deploy regenerative brine recovery loops to compress single-use economics toward closed-loop contracts.
- Deicing:Chloride-free runway and bridge deck treatments command specification premiums in Minnesota, Wisconsin, and Michigan as transportation departments pilot alternatives to magnesium chloride. Freeze-thaw cycling damage drives procurement mandates in New York, Massachusetts, and Illinois.
- Animal Feed:Silage preservation and rumen acidification applications compete on delivered cost against propionic acid and other organic acid alternatives. Midwest dairy concentration shapes regional demand clusters.
- Chemical Processing:Intermediate applications in organic synthesis and catalyst systems require custom concentration and impurity specifications. Batch chemical producers in the Gulf Coast petrochemical corridor anchor procurement.
Oilfield applications command the dominant share of current volume; deicing is gaining share fastest as infrastructure specifications tighten.
End User:
Customer type determines contract structure, with integrated oilfield operators demanding five-year volume commitments and embedded price collars.
- Oil & Gas:Shale operators across Texas, North Dakota, and New Mexico specify formate brines for Class II well compliance under EPA Underground Injection Control revisions. Private equity-backed independents in the Delaware Basin consolidate procurement through integrated supply contracts.
- Agriculture:Livestock operations and silage contractors prioritize delivered cost and regional availability over certification tiers. Iowa, Wisconsin, and Kansas anchor consumption geography.
- Food Industry:Processors demand Food Chemicals Codex documentation with lot traceability for preservation applications. Supply qualification timelines extend 12-18 months for new vendor entry.
- Manufacturing:Chemical synthesis and industrial processing applications span diverse purity requirements with procurement fragmented across spot and contract mechanisms.
Oil and gas end users absorb the dominant capacity share; food industry qualification pipelines are expanding most rapidly.
Distribution Channel:
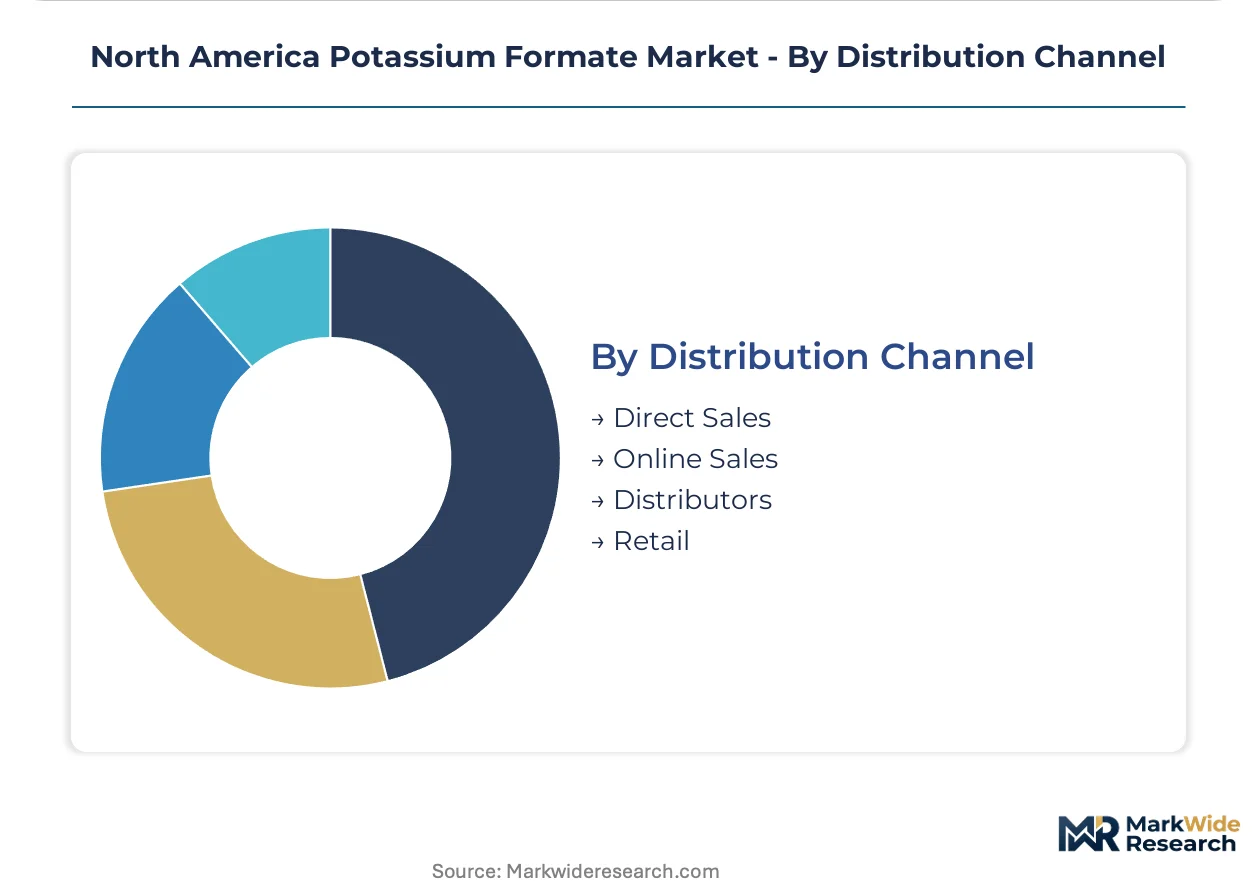
Volume maturity separates direct supply relationships from emerging digital procurement platforms serving smaller account tiers.
- Direct Sales:Integrated oilfield service companies and large chemical processors negotiate dedicated supply agreements with embedded storage infrastructure. Five-year commitments with price collars displace spot-market purchases among Permian Basin operators.
- Distributors:Regional chemical distributors manage inventory positioning for food-grade and agricultural-grade material with certified handling capabilities. Gulf Coast concentration creates hurricane exposure requiring redundant sourcing.
- Online Sales:Digital platforms serve research quantities, small-batch pharmaceutical procurement, and agricultural trial volumes with expedited documentation. Limited penetration in bulk industrial segments.
- Retail:Limited presence confined to agricultural supply cooperatives and specialty chemical outlets serving hobbyist and small-scale preservation applications.
Direct sales channels capture the dominant volume flow; online platforms are climbing the fastest as digital procurement penetrates specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American potassium formate capacity through its integrated chemical corridor, where Gulf Coast formic acid feedstock and specialized brine blending infrastructure concentrate supply-side leverage for shale operators.
United States
EPA Underground Injection Control revisions and Delaware Basin multi-pad development programs drive formate brine procurement. Texas Railroad Commission groundwater protection rules accelerate displacement of calcium chloride completion fluids. Permian Basin operators in Midland and Odessa deploy five-year integrated supply contracts with embedded price collars.
Canada
Alberta SAGD thermal operations evaluate formate brines for steam chamber stability against sodium silicate systems. Health Canada environmental release guidelines for oil sands tailings favor biodegradable alternatives. Edmonton and Calgary chemical distributors position inventory for oil sands procurement clusters.
Mexico
Chicontepec Basin shale development and offshore deepwater drilling in the Gulf of Mexico create emerging formate demand. Mexican Energy Regulatory Commission environmental compliance protocols for offshore discharge mirror EPA biodegradability preferences. Tampico and Veracruz port infrastructure supports Gulf Coast supply chain extension.
North America Potassium Formate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical and food-grade specialists commanding 40-60% margin premiums over industrial brine suppliers. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with captive formic acid supply, oilfield service specialists with downhole formulation expertise, and regional distributors with certified handling infrastructure. Dominant competitive moves include backward integration into formic acid production and long-term supply contract consolidation among Permian Basin independents.
Within the integrated chemical tier, Eastman Chemical Company and BASF SE exemplify scale-advantaged positioning through chemistry platform breadth. TETRA Technologies anchors the oilfield service specialist archetype with dedicated downhole fluid capabilities. These three entities occupy distinct competitive vectors—feedstock integration, global technical service networks, and field-level formulation expertise—rather than competing head-to-head on identical value propositions.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| American Elements |
| TETRA Technologies |
| BASF SE |
| Dynalene |
| Hawkins |
| Honeywell International |
| Clariant |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Formic acid feedstock costs cascade through potassium formate pricing tiers from industrial brine suppliers to USP-certified pharmaceutical specialists, with Gulf Coast methyl formate pricing volatility compressing margins most acutely at commodity-grade producers lacking captive carbon monoxide supply.
Pricing Analysis
Performance-per-barrel contracts now anchor value-based pricing for Delaware Basin operators deploying regenerative brine recovery systems. Three-tier pricing structure across pharmaceutical, industrial, and agricultural grades separates USP-certified batch documentation from commodity aqueous solutions. Cost compression in industrial-grade channels is intensifying because integrated oilfield service companies demand five-year volume commitments with embedded price collars. Agricultural end users exhibit highest price sensitivity due to substitution elasticity with propionic acid alternatives.
Supply Chain Analysis
Specialized tanker freight rates from Houston to Midland-Odessa procurement clusters shape delivered cost economics for Permian Basin independents. Production gravity centers on the Texas Gulf Coast, with secondary blending capacity in Alberta and emerging distribution nodes in Veracruz. Raw material flows draw from carbon monoxide steam reforming, methyl formate carbonylation, and imported formic acid feedstocks. Hurricane exposure along the Houston Ship Channel creates single-source vulnerability during Atlantic storm seasons. Distribution runs through dedicated oilfield service channels for bulk industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into formic acid production has become the decisive vertical-integration race, with captive carbon monoxide supply separating margin-durable producers from feedstock-price-takers across all certification tiers.
For Market Incumbents: Acquire methyl formate production capacity or carbon monoxide reforming assets to neutralize feedstock volatility that erodes commodity-grade margins. Defend pharmaceutical-grade positioning through endotoxin-controlled purification train investments before USP certification scarcity arbitrage collapses. Lock Delaware Basin independents into ten-year storage infrastructure leases to preempt spot-market disintermediation. For New Entrants and Emerging Players: Digital procurement platforms serving research-quantity pharmaceutical buyers offer the lowest barrier to initial revenue traction. Target chloride-free deicing specification pilots at Minnesota and Wisconsin transportation departments before procurement mandates solidify around incumbent distributors. Pursue toll-manufacturing arrangements with Gulf Coast formate producers to bypass capital-intensive purification train investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap industrial-grade producers with stranded formic acid offtake agreements in the Texas chemical corridor. Five-to-ten-year viability hinges on securing EPA Safer Choice certification pipelines ahead of state-level groundwater protection rule expansions. Monitor Class II well permit approval velocity at the EPA as the inflection signal for formate brine displacement acceleration versus halide salt retention.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formic Acid | Captive carbon monoxide supply insulates margin from methyl formate pricing volatility. |
| USP Certification Capacity Expansion | FDA-compliant purification trains capture 40-60% margin premiums over industrial grades. |
| Regenerative Brine Recovery Deployment | Closed-loop economics transform single-use contracts into performance-per-barrel relationships. |
| Long-term Supply Agreement Consolidation | Five-year price collars with Permian Basin operators displace spot-market procurement. |
| Chloride-free Deicing Specification Capture | Transportation department mandates in freeze-thaw states open premium contract tiers. |
Research Methodology
Independent corroboration across oilfield fluid engineers, formate plant managers, and EPA regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with completion fluid procurement leads at Delaware Basin operators, technical R&D directors at integrated chemical producers, and distribution channel partners in the Gulf Coast corridor combined with secondary validation. Trade data from U.S. Census Bureau chemical import records, SEC 10-K disclosures from listed chemical conglomerates, and American Chemistry Council market reports anchored quantitative inputs. Bottom-up capacity utilization estimates and top-down demand segmentation triangulated volume figures.
Rate-of-change decomposition across the analysis window segmented volume trajectories by grade tier, end-use industry, and regional production hub. Modeled dimensions included industrial versus pharmaceutical versus agricultural certification levels, oilfield versus deicing versus feed application splits, and Texas Gulf Coast versus Alberta versus Midwest demand clusters. CAGRs derived from regression-weighted historical trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated EPA Underground Injection Control revision timelines and state transportation department specification adoption curves.
The model holds under continued EPA groundwater protection enforcement and stable formic acid feedstock availability; deviation in hurricane frequency affecting Gulf Coast production or sudden chloride salt regulatory grandfathering would shift trajectory. Forecasts reflect documented assumptions about shale well complexity escalation and freeze-thaw infrastructure degradation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Sodium Sulphate Market