
 Brassylic Acid Market | 2026-2036
Brassylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Brassylic Acid Market Intelligence
Specialized fermentation technicians and downstream purification chemists is reorganizing production economics for brassylic acid manufacturers. Evonik Industries leverages its decades of specialty chemical expertise to sustain high-purity output standards. Cathay Industrial Biotech anchors long-chain dicarboxylic acid capacity through industrial biotechnology platforms in Asia.
Brassylic acid is a thirteen-carbon linear dicarboxylic acid produced via microbial fermentation of alkanes or plant oils, typically refined to purity levels exceeding 98% for polymer-grade applications. The compound serves as a critical intermediate for nylon 1313, fragrance macrocycles, and specialized polyamide resins where thermal stability and moisture resistance matter. Fragrance-grade material commands premium positioning due to stringent organoleptic specifications and limited qualified supply. Polymer additive volumes dominate absolute tonnage as automotive and textile manufacturers seek bio-based alternatives to petroleum-derived C12-C14 diacids.
EPA industrial chemical reporting requirements and REACH substance registration protocols govern commercialization pathways in North America and Europe, while China's MIIT sets national biosafety standards for genetically modified fermentation strains. These frameworks elevate compliance costs but simultaneously create market access barriers that favor established producers with dedicated regulatory affairs teams. Stakeholders must track evolving bio-preferred procurement mandates from defense and automotive OEMs to anticipate shifts in qualified supplier rosters.
Market Dynamics
REACH compliance tightening across the European Union is compressing qualified supplier pools for polymer-grade brassylic acid while simultaneously accelerating fermentation technology investment to meet bio-based purity thresholds.
Growth Catalysts
- Automotive undercoating specifications:Specialty polymer additive demand from vehicle manufacturers seeking moisture-resistant bio-based alternatives to petroleum-derived diacids is pulling volume through qualified supply chains.
- EU Green Deal procurement mandates:Defense and automotive OEM bio-preferred sourcing requirements are expanding addressable market for certified bio-based dicarboxylic acid producers with dedicated regulatory affairs infrastructure.
- Fragrance macrocycle formulation:Organoleptic-grade material scarcity is sustaining premium positioning for producers capable of meeting stringent sensory specifications in luxury fragrance applications.
Market Restraints
- Fermentation feedstock volatility:Plant oil and alkane input costs fluctuate with agricultural commodity cycles, compressing margin predictability for biotechnological production platforms.
- Downstream purification bottlenecks:Chromatographic and crystallization capacity concentration in Germany's Ludwigshafen-Leverkusen corridor creates geographic single-point vulnerability for high-purity output.
- Petroleum-derived C12-C14 diacid substitution:Established adipic and sebacic acid supply chains retain cost advantages in price-sensitive polymer additive segments.
Strategic Opportunities
- India specialty chemical manufacturing:PLI scheme incentives for bio-based industrial intermediates create tariff-advantaged production foothold for export-oriented fermentation capacity.
- Nylon 1313 textile fiber expansion:Thermal stability requirements in technical textiles and automotive interiors are opening specification-driven demand outside traditional fragrance channels.
- CRRD-aligned carbon accounting:EU corporate sustainability reporting requirements for Scope 3 emissions are elevating preference for fermentation-derived acids with verifiable lifecycle data.
Industry Challenges
- Specialized fermentation technician scarcity:Industrial biotechnology workforce gaps constrain scale-up velocity for new production facilities targeting polymer-grade purity.
- EPA premanufacture notification timelines:New chemical substance review periods extend commercialization cycles for modified strains or alternative feedstock pathways.
- Cross-jurisdictional strain certification:China's MIIT biosafety standards for genetically modified organisms create divergence from OECD microbial strain qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brassylic Acid Market |
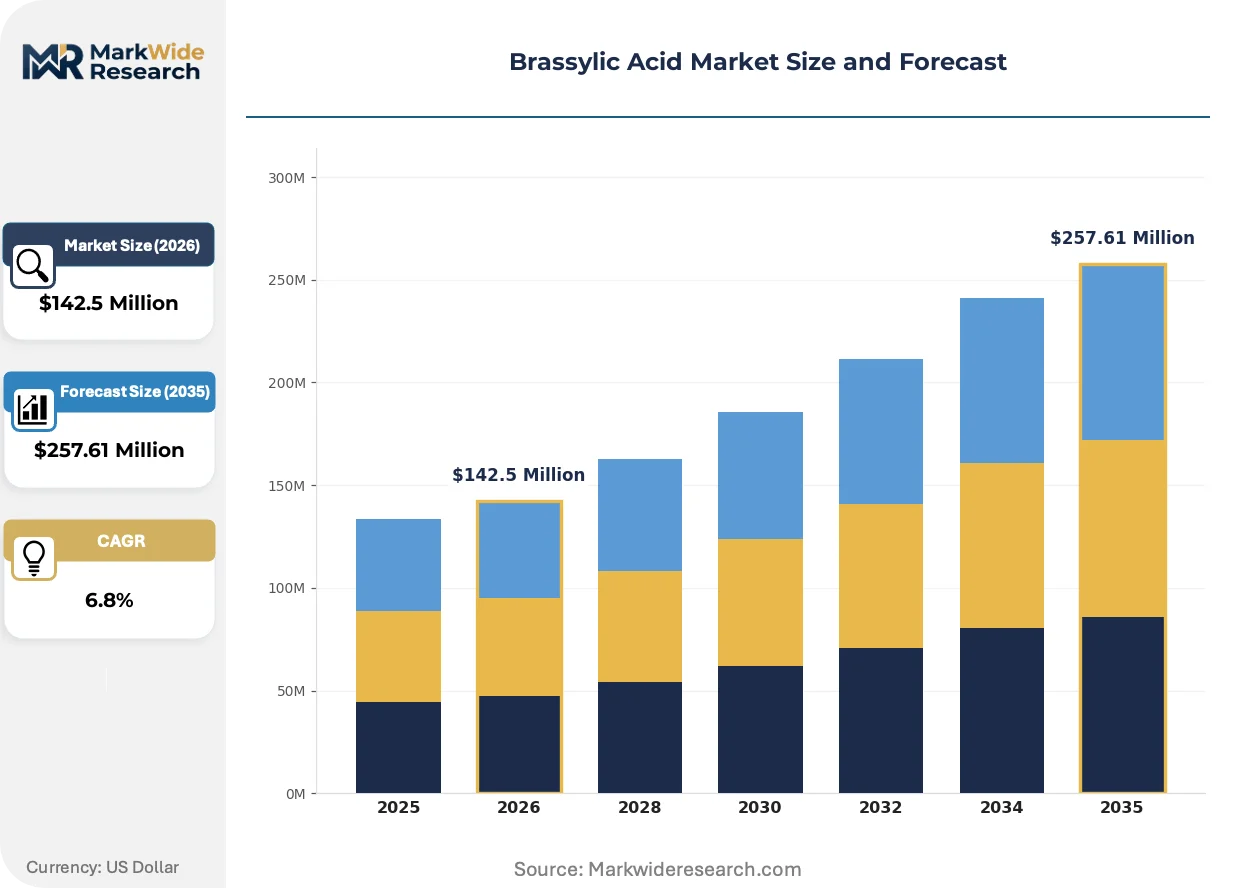
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrance, Flavoring Agent, Polymer Additive, Surfactant Application: Cosmetics, Food & Beverage, Pharmaceuticals, Industrial End Use Industry: Personal Care, Food Production, Chemical Manufacturing, Textile Packaging Type: Drums, Bulk Containers, Glass Bottles, Bagged |
| Companies Covered | Evonik Industries, Cathay Industrial Biotech, Palmary Chemical, Beyo Chemical Co., Ltd., Unisource Chemicals Pvt. Ltd., Shanghai Kaleys Holding Co., Ltd., Nantong Senos Biotechnology Co., Ltd., Larodan AB, Zibo Guangtong Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brassylic Acid Market Strategic Shifts & Innovations
Bioprocess intensification and regulatory data transparency requirements are compressing development cycles while fragmenting competitive advantage away from pure scale economics toward strain-level IP and purification know-how.
Continuous fermentation systems with real-time metabolite monitoring are fragmenting traditional batch-based production economics. Specialty chemical manufacturers in Germany and Japan are retrofitting existing alkane oxidation infrastructure with cell retention bioreactors. This technology diffusion is compressing capital requirements for entry-level polymer-grade capacity while fragmenting margin capture between upstream strain developers and downstream purification specialists.
REACH substance registration protocols now mandate full lifecycle toxicity datasets for bio-based dicarboxylic acids above 10-ton annual thresholds. ECHA's revised guidance on persistent, bioaccumulative, and toxic substance classification is extending dossier preparation timelines. Polymer additive suppliers with pre-2025 registration grandfathering are consolidating qualified supplier status before new entrant compliance burdens fully materialize.
Automotive OEMs are unbundling material certification from volume procurement contracts. Tier-1 suppliers now maintain parallel qualified supplier rosters across fragrance-grade and polymer-grade specifications. This purchasing pattern shift is most visible in Germany's automotive supply chain, where BMW and Mercedes-Benz sustainability scorecards weight bio-based content verification above unit pricing in long-term agreements.
Brassylic Acid Market Segmentation
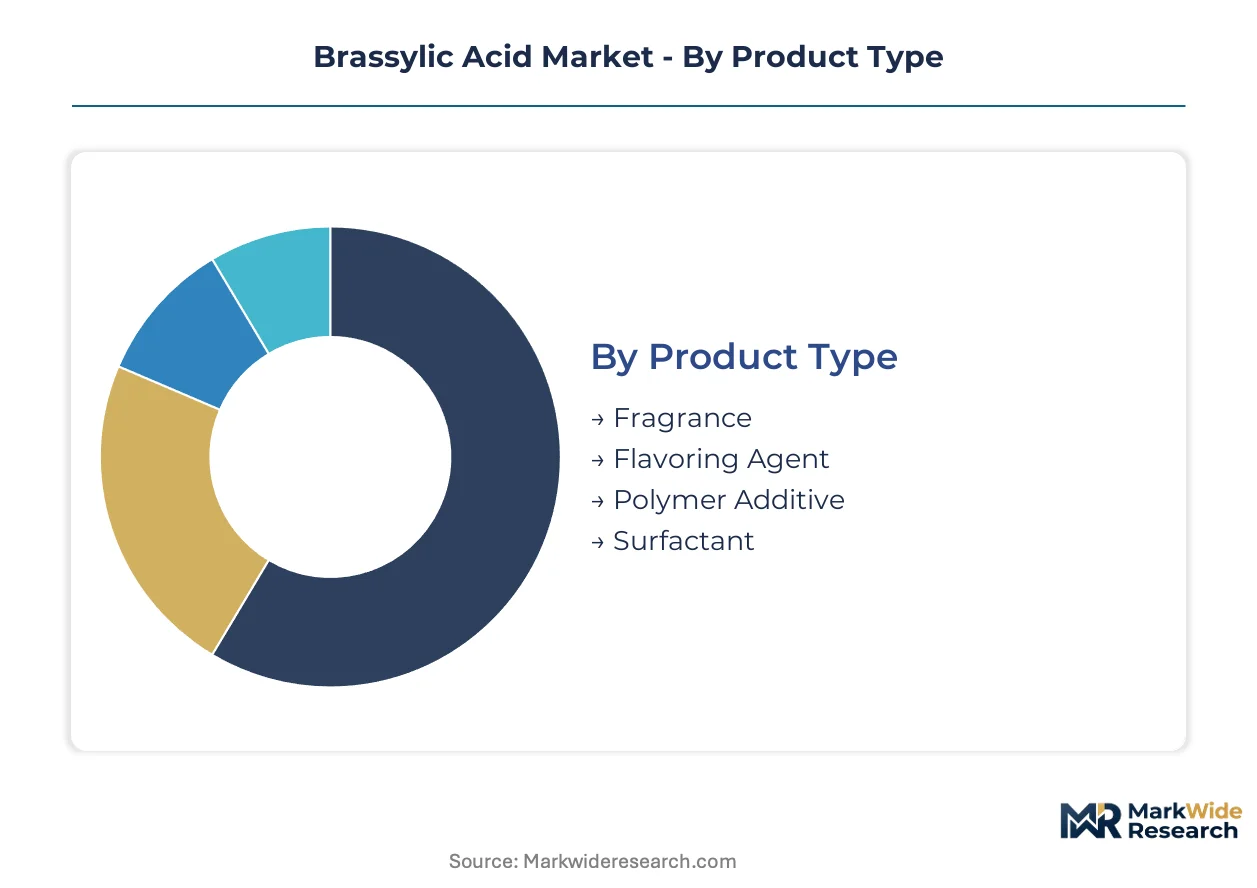
Brassylic acid specifications diverge sharply across end-use channels, with fragrance-grade purity thresholds and polymer-grade thermal stability requirements creating non-overlapping qualification pathways. Regulatory frameworks from ECHA REACH to EPA industrial chemical reporting segment commercialization routes by tonnage thresholds and toxicity dossier depth.
Product Type:
ECHA substance registration protocols mandate distinct purity certifications above 10-ton annual thresholds, fragmenting production economics between organoleptic-grade and industrial-grade outputs.
- Polymer Additive:Nylon 1313 precursor applications require 98%+ purity with verified thermal stability under 200°C processing conditions. Automotive undercoating specifications from BMW and Mercedes-Benz sustainability scorecards pull volume through qualified supply chains in Germany's Ludwigshafen corridor.
- Fragrance:Macrocyclic musk formulations demand sub-ppm impurity profiles with organoleptic certification from fragrance houses. Limited qualified supply sustains premium positioning for producers meeting Givaudan and Firmenich sensory specifications.
- Flavoring Agent:FEMA GRAS status and FDA food additive regulations govern commercialization pathways with stringent toxicology dossier requirements.
- Surfactant:Industrial cleaning formulations utilize technical-grade material with relaxed purity specifications relative to fragrance applications.
Polymer Additive handles the majority of throughput; Fragrance is expanding most quickly on share as luxury personal care brands accelerate bio-based macrocycle adoption.
Application:
Cost tier stratification separates specification-driven pharmaceutical grades from price-sensitive industrial formulations.
- Cosmetics:REACH Article 33 disclosure requirements and EU Cosmetics Regulation 1223/2009 govern ingredient traceability for macrocyclic fragrance applications.
- Industrial:Automotive undercoating and textile fiber applications dominate absolute tonnage as manufacturers substitute petroleum-derived C12-C14 diacids with fermentation-derived alternatives.
- Pharmaceuticals:USP-grade specifications for excipient applications require dedicated GMP production lines with FDA drug master file documentation.
- Food & Beverage:FEMA GRAS and EFSA flavoring substance evaluations create multi-jurisdictional approval timelines for direct food contact applications.
Industrial commands the dominant volume position; Cosmetics is gaining share fastest as EU Green Deal procurement mandates expand bio-preferred sourcing requirements.
End Use Industry:
Customer type concentration clusters around defense and automotive OEM sustainability scorecards with embedded Scope 3 carbon accounting.
- Chemical Manufacturing:Specialty polyamide resin producers in Germany and Japan anchor demand for consistent polymer-grade supply with batch-to-batch thermal stability verification.
- Personal Care:L'Oréal and Unilever bio-based procurement mandates drive fragrance-grade qualification programs with third-party lifecycle certification.
- Textile:Nylon 1313 technical fiber applications for automotive interiors require moisture resistance specifications distinct from apparel-grade polyamides.
- Food Production:Flavor house procurement concentrates on FEMA GRAS-certified volumes with documented fermentation feedstock provenance.
Chemical Manufacturing handles the majority of throughput; Personal Care is climbing the fastest on share as CRRD-aligned carbon accounting elevates preference for verifiable bio-based content.
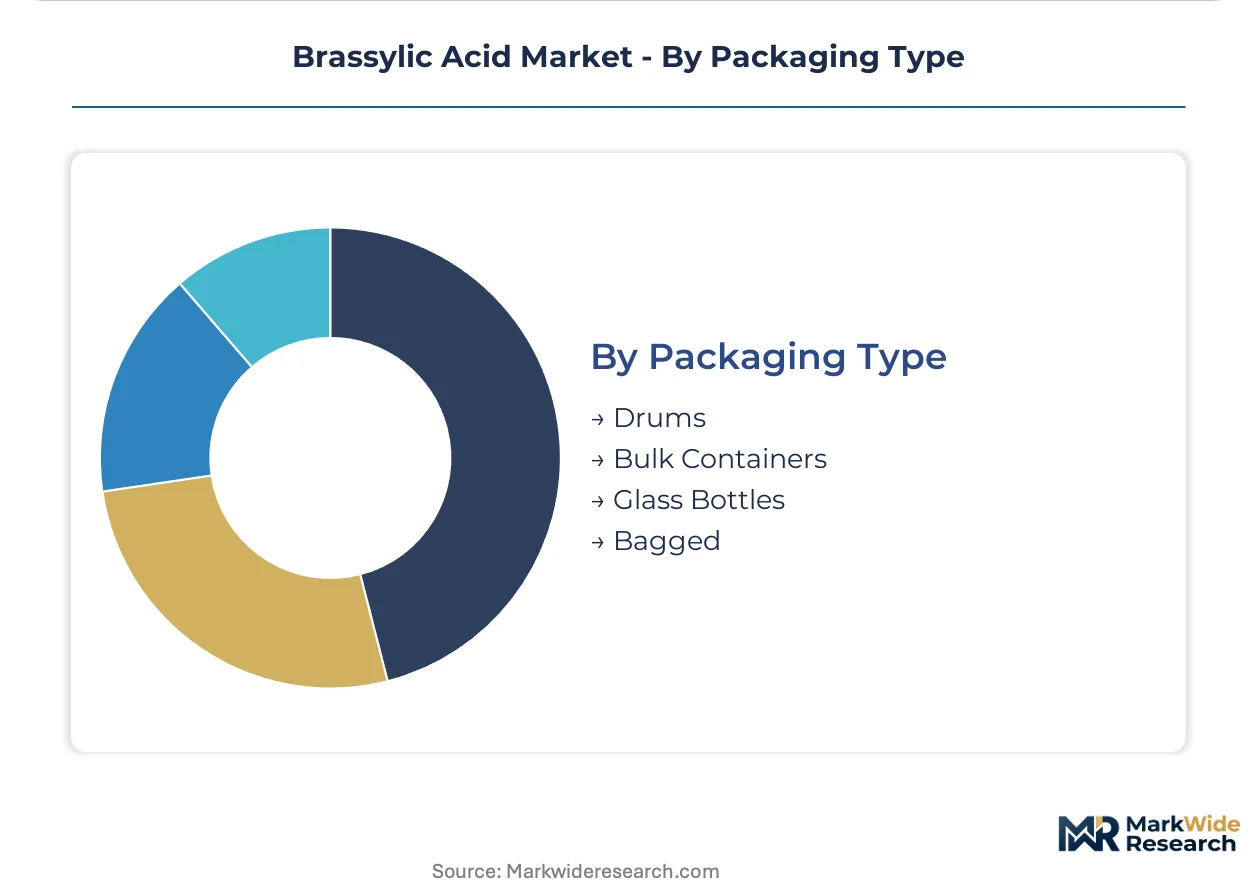
Packaging Type:
Supply concentration in Germany's Ludwigshafen-Leverkusen corridor dictates drum and bulk container availability for polymer-grade shipments.
- Bulk Containers:ISO tank and flexitank configurations serve automotive tier-1 suppliers with just-in-time delivery requirements to assembly plants.
- Drums:200-liter steel and HDPE specifications dominate fragrance-grade shipments to compounding houses with controlled atmosphere storage protocols.
- Glass Bottles:Amber and clear pharmaceutical-grade packaging with tamper-evident seals serves API and excipient applications requiring oxidation protection.
- Bagged:25kg multiwall paper sacks with polyethylene liners address price-sensitive industrial surfactant applications with lower purity requirements.
Drums handles the majority of throughput; Bulk Containers is expanding most quickly on share as automotive OEMs consolidate material certification with volume procurement contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes brassylic acid primarily for polymer-grade automotive applications, while China and India divert larger shares toward fragrance-grade outputs for personal care export markets.
United States
Automotive OEM sustainability scorecards from Detroit manufacturers pull polymer-grade volumes for undercoating specifications. EPA industrial chemical reporting requirements govern fermentation-derived acid commercialization pathways. The Gulf Coast petrochemical corridor hosts biotech retrofit projects targeting bio-based diacid capacity.
Germany
BMW and Mercedes-Benz procurement mandates weight bio-based content verification above unit pricing in long-term supply agreements. ECHA REACH substance registration protocols mandate full lifecycle toxicity datasets above 10-ton annual thresholds. The Ludwigshafen-Leverkusen corridor concentrates downstream purification capacity for high-purity output.
China
MIIT biosafety standards for genetically modified fermentation strains create divergence from OECD microbial qualification protocols. Cathay Industrial Biotech anchors long-chain dicarboxylic acid capacity through industrial biotechnology platforms. Yangtze River Delta chemical parks host expanding fermentation capacity for polymer-grade exports.
India
PLI scheme incentives for bio-based industrial intermediates create tariff-advantaged production footholds for export-oriented fermentation capacity. Unisource Chemicals and other domestic suppliers target fragrance-grade qualification for European personal care brands. Maharashtra's specialty chemical manufacturing clusters attract strain development laboratories.
Japan
METI carbon neutrality roadmaps elevate preference for fermentation-derived acids with verifiable lifecycle data in automotive supply chains. Retrofitted alkane oxidation infrastructure with cell retention bioreactors fragments traditional batch-based production economics. Osaka-Kobe industrial zones concentrate technical textile applications for nylon 1313 fiber.
Brassylic Acid Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in brassylic acid manufacturing. Evonik Industries leverages decades of specialty chemical expertise to sustain high-purity output standards, while Cathay Industrial Biotech anchors Asian capacity through industrial biotechnology platforms. The competitive terrain splits between fermentation technology licensors and downstream purification specialists. Dominant moves include backward integration into strain development capabilities and geographic expansion to capture EU Green Deal procurement mandates.
Among Germany-based integrated chemical producers, Evonik Industries exemplifies the regulatory affairs-heavy archetype with dedicated REACH compliance infrastructure. Chinese industrial biotechnology platforms, represented by Cathay Industrial Biotech, occupy positions emphasizing scale fermentation and feedstock flexibility. Specialist pure-plays including Larodan AB and Beyo Chemical Co., Ltd. sit within narrower fragrance-grade or regional supply niches, anchoring qualified supplier status in sensory-specification channels.
| Leading Market Players |
|---|
| Evonik Industries |
| Cathay Industrial Biotech |
| Palmary Chemical |
| Beyo Chemical Co., Ltd. |
| Unisource Chemicals Pvt. Ltd. |
| Shanghai Kaleys Holding Co., Ltd. |
| Nantong Senos Biotechnology Co., Ltd. |
| Larodan AB |
| Zibo Guangtong Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with automotive OEMs lock in supply access for polymer-grade brassylic acid while providing price visibility against volatile plant oil feedstock cycles. These contracts concentrate purchasing power with Germany-based tier-1 suppliers who negotiate batch-to-batch thermal stability guarantees from Ludwigshafen corridor purification specialists.
Pricing Analysis
Contract-based long-term offtake dominates polymer-grade transactions, while fragrance-grade material trades on spot markets with organoleptic certification premiums. Price differentiation hinges on purity thresholds and REACH registration status, with automotive buyers least sensitive to unit costs and industrial surfactant manufacturers most responsive to input fluctuations. Cost compression in technical-grade segments intensifies as petroleum-derived C12-C14 diacid suppliers defend volume positions.
Supply Chain Analysis
Just-in-time delivery protocols govern automotive tier-1 procurement, while fragrance houses maintain strategic stockpiles against organoleptic-grade scarcity. Supply concentrates in Germany, China, and Japan, with fermentation platforms drawing from plant oil and alkane feedstocks. Single-source vulnerability in Germany's Ludwigshafen-Leverkusen purification corridor elevates geographic risk. Distribution runs through qualified supplier rosters maintained by BMW, Mercedes-Benz, and Givaudan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
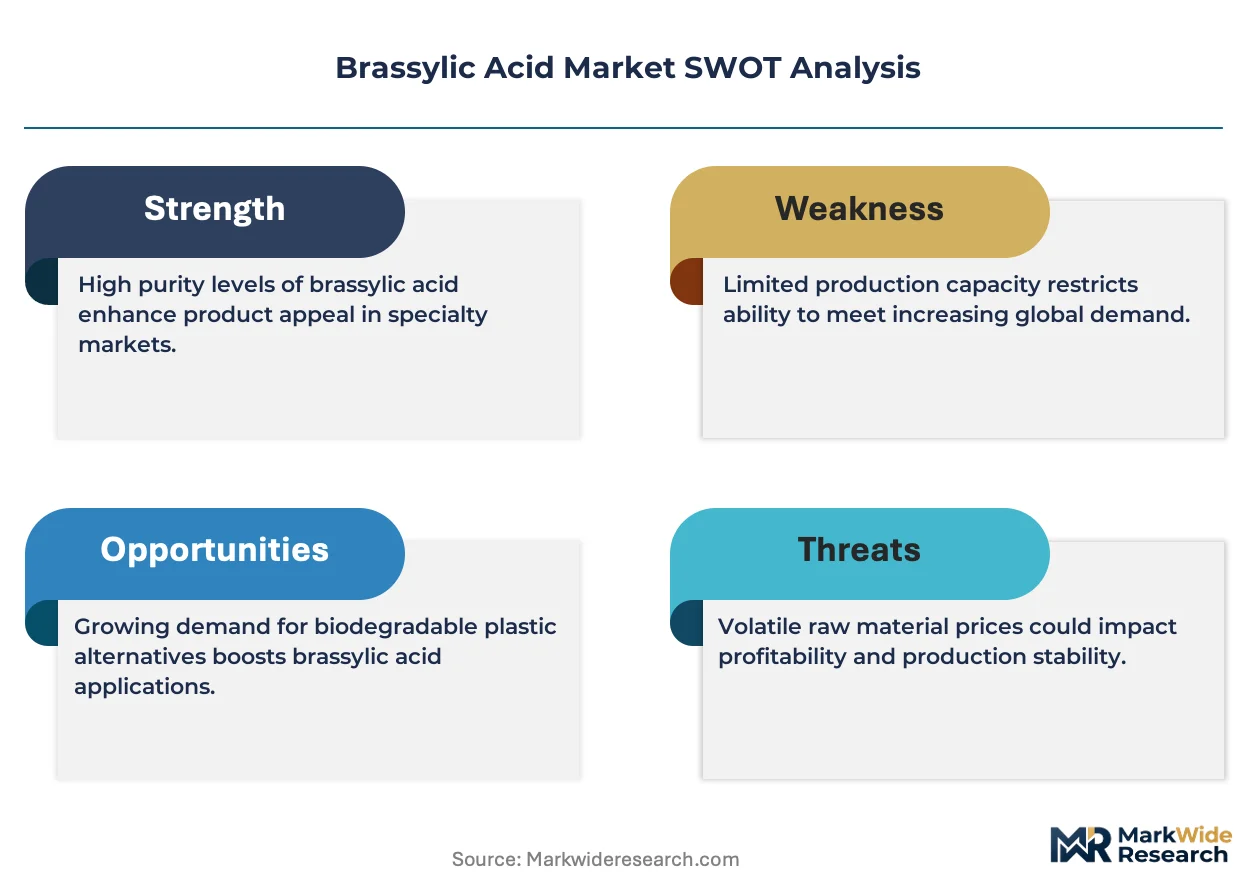
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH dossier preparation timelines and ECHA grandfathering advantages create switching costs that protect incumbent positions.
For Market Incumbents: Shield qualified supplier status by accelerating backward integration into proprietary strain development capabilities. Expand chromatographic purification capacity in tariff-advantaged jurisdictions before PLI scheme incentives attract Asian fermentation platforms. Prioritize certification investment for CRRD-aligned carbon accounting to capture EU Green Deal procurement mandates. For New Entrants and Emerging Players: Differentiate on feedstock flexibility by engineering alkane-independent fermentation pathways that bypass agricultural commodity volatility. Target India's PLI-supported specialty chemical clusters as the most penetrable geography. Pursue fragrance-grade qualification as the go-to-market angle, where organoleptic scarcity sustains premium positioning against established polymer-grade incumbents. For Investors and Strategic Acquirers: Purification specialists with captive strain licensing relationships represent the optimal acquisition archetype. Long-term viability over the coming decade rests on regulatory affairs infrastructure depth rather than pure fermentation scale. Watch for EPA premanufacture notification backlog clearance as the signal indicating accelerated new entrant commercialization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captures margin from fermentation IP while reducing feedstock dependency on external alkane suppliers. |
| Capacity Expansion in India | PLI scheme incentives create tariff-advantaged export footholds for European automotive supply chains. |
| REACH Registration Acceleration | Grandfathering advantages before ECHA's revised PBT guidance extends dossier timelines for new entrants. |
| Long-term Supply Agreement with Automotive OEMs | BMW and Mercedes-Benz sustainability scorecards weight bio-based verification above unit pricing. |
| Joint Venture with Fragrance Houses | Givaudan and Firmenich sensory specifications require dedicated organoleptic certification infrastructure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and ECHA registration dossiers. Primary interviews engaged plant managers at fermentation facilities, procurement leads at automotive tier-1 suppliers, technical R&D directors at specialty polyamide resin producers, and regulatory affairs specialists. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis.
Segmentation dimensions modeled include purity grade tier, end-use industry application, packaging format, and regional production hub concentration across the analysis window. CAGRs derive from elasticity-adjusted demand projections incorporating automotive OEM sustainability scorecard weightings and EU Green Deal procurement mandate penetration curves. Forecast inputs integrate strain development velocity metrics and chromatographic purification capacity expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance tightening or accelerated EPA notification clearance would require recalibration. Forecasts assume continued grandfathering advantages for pre-2025 registrants and stable MIIT biosafety standards for genetically modified organisms. Revision becomes warranted when fermentation feedstock volatility crosses agricultural commodity cycle thresholds or when automotive OEM bio-preferred sourcing mandates shift specification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Furfuryl Alcohol Market