
 Global Internal Olefins Market | 2026-2036
Global Internal Olefins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internal Olefins Market Foresight
Linear alpha olefins is hardening as the incumbent feedstock for surfactant and polymer applications, compelling producers to sharpen cost positions around metathesis and oligomerization routes. Sasol Limited leverages its Fischer-Tropsch-derived olefin slate to sustain integrated margins across octene and decene grades. INEOS Group Limited anchors European supply through its Grangemouth and Lavéra complexes, while Chevron Phillips Chemical Company dominates Gulf Coast production with dedicated oligomerization trains.
Internal olefins are unsaturated hydrocarbons with the double bond positioned away from the terminal carbon, typically manufactured via metathesis of linear alpha olefins or through chlorination-dehydrochlorination of paraffins, yielding carbon chain lengths from C6 to C18 for lubricant, surfactant, and drilling fluid applications. The octene and decene product types command premium positioning in synthetic lubricant base stocks where low pour points and thermal stability justify higher formulation value. Oligomerization technology leads capacity additions because producers can tune molecular weight distribution with greater precision than steam cracking allows, while surfactant applications represent the deepest volume pool though polymer production is expanding faster on polyethylene comonomer demand.
EPA regulations under the Toxic Substances Control Act constrain chlorinated paraffin intermediates in the United States, while REACH registrations in Europe mandate full toxicological dossiers for C10-C13 internal olefin streams. China's MEE enforces VOC emission caps on olefin storage and handling facilities in the Yangtze River Delta cluster. Stakeholders must monitor regulatory divergence between these jurisdictions when siting new metathesis capacity or reformulating surfactant product lines.
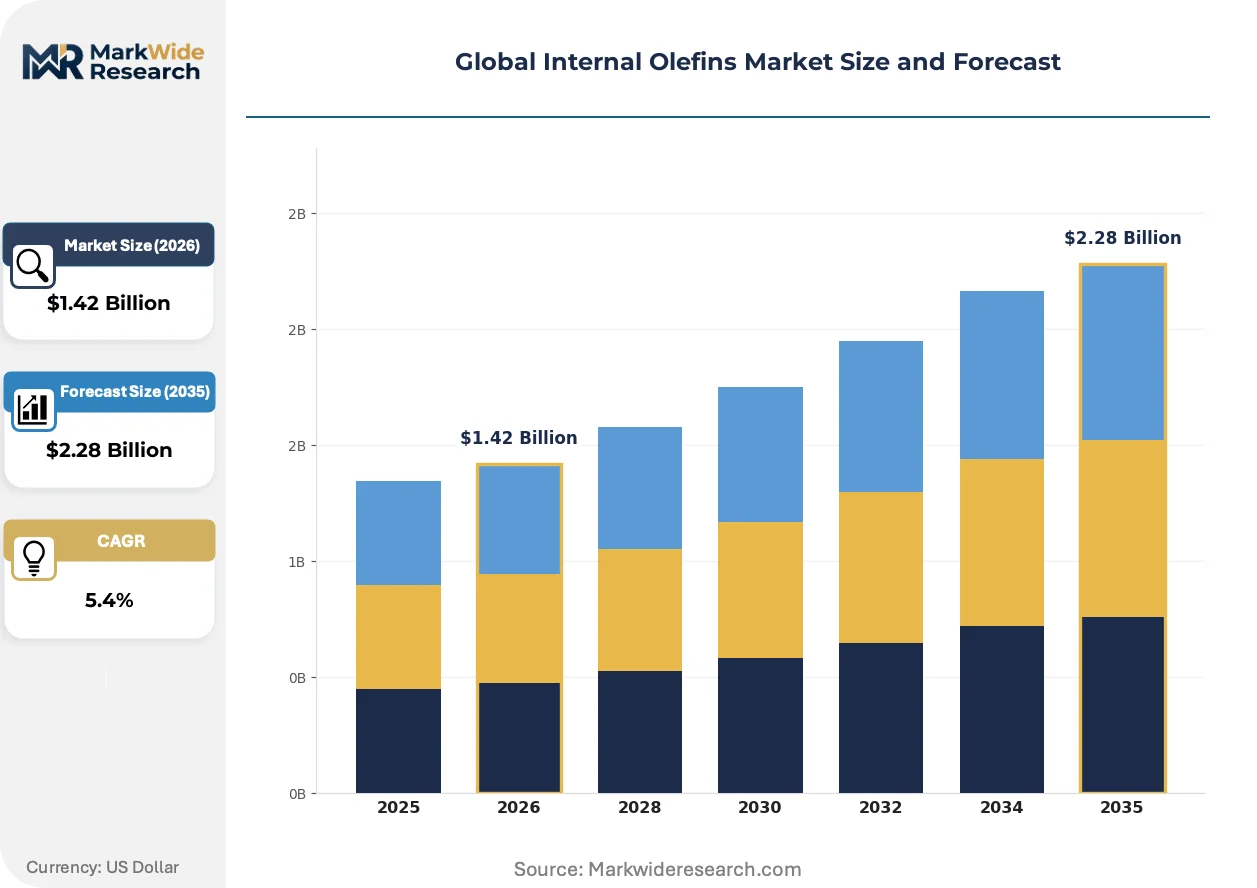
Market Dynamics
Metathesis technology maturation is compressing the cost gap between linear alpha olefins and internal olefins, forcing producers to reconfigure feedstock sourcing strategies around Fischer-Tropsch integration and shale-derived ethylene economics.
Growth Catalysts
- REACH Registration Completion:European ECHA dossier approvals for C10-C13 internal olefin streams are unlocking surfactant formulation volumes previously constrained by regulatory uncertainty.
- China Polymer Value Chain Expansion:Domestic dehydrogenation capacity additions in Jiangsu and Zhejiang provinces are creating captive demand for octene and decene comonomers.
- Oligomerization Precision Gains:Advanced catalyst systems now enable molecular weight distribution tuning that matches performance specifications for synthetic lubricant base stocks.
Market Restraints
- Chlorinated Paraffin Feedstock Constraints:EPA Toxic Substances Control Act restrictions on chlorinated intermediates limit US production routes and elevate raw material costs.
- Supply Concentration Risk:Gulf Coast oligomerization trains account for disproportionate North American capacity, exposing buyers to hurricane corridor disruption.
- Linear Alpha Olefin Substitution Pressure:Incumbent LAO producers are narrowing price premiums through metathesis integration, eroding internal olefin cost advantages.
Strategic Opportunities
- India Surfactant Formulation Growth:BIS quality standards harmonization and FSSAI cleaning product mandates are creating specification-grade demand for C12-C14 internal olefin sulfonates.
- EU Green Deal Biobased Mandates:Renewable carbon content requirements in lubricant applications favor Fischer-Tropsch derived olefins with certified sustainability credentials.
- Digital Distribution Platforms:Specialty chemical marketplaces are compressing procurement cycles for mid-volume surfactant compounders seeking spot internal olefin supplies.
Industry Challenges
- Process Control Talent Scarcity:Metathesis reactor optimization requires specialized catalysis expertise that competes with pharmaceutical and fine chemical sectors for limited personnel.
- Multi-Jurisdiction Compliance Burden:Simultaneous EPA, REACH, and China MEE registration timelines create documentation bottlenecks that delay product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internal Olefins Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene, Propylene, Butene, Hexene, Octene, Decene Technology: Steam Cracking, Catalytic Cracking, Metathesis, Polymerization, Dehydrogenation, Oligomerization Application: Polymer Production, Synthetic Rubbers, Plasticizers, Surfactants, Adhesives, Chemical Intermediates End User Industry: Packaging Manufacturers, Automotive Parts Suppliers, Textile Producers, Coating Manufacturers, Construction Material Makers, Consumer Goods Fabricators |
| Companies Covered | INEOS Group Limited, Sasol Limited, Royal Dutch Shell plc, Elevance Renewable Sciences, Chevron Phillips Chemical Company, SABIC, Halliburton Company, Schlumberger Limited, Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internal Olefins Market Shifts & Advancements
Process intensification and regulatory compliance automation are redefining operational benchmarks across internal olefin value chains, with technology adoption patterns diverging sharply between integrated majors and specialty compounders.
Membrane separation technology for olefin-paraffin recovery is converging with traditional distillation trains in metathesis units, enabling polymer-grade producers to reduce energy intensity by 15-20 percent while maintaining product purity. European integrated complexes are piloting hybrid configurations, with Grangemouth and Lavéra facilities testing modular membrane skids alongside existing fractionation columns.
China's MEE enforcement of VOC emission caps across Yangtze River Delta olefin storage terminals is compelling terminal operators to install vapor recovery units and floating roof tank retrofits. Domestic producers face capital allocation decisions between compliance upgrades and capacity expansion, with smaller dehydrogenation units delaying greenfield investments.
Specification-driven procurement now dominates synthetic lubricant base stock purchasing, with blenders unbundling technical service from material supply and conducting direct catalyst performance validation. Major formulators in Germany and Japan are establishing in-house metathesis pilot units to test internal olefin batches against pour point and oxidation stability protocols before contract commitment.
Global Internal Olefins Market Segmentation
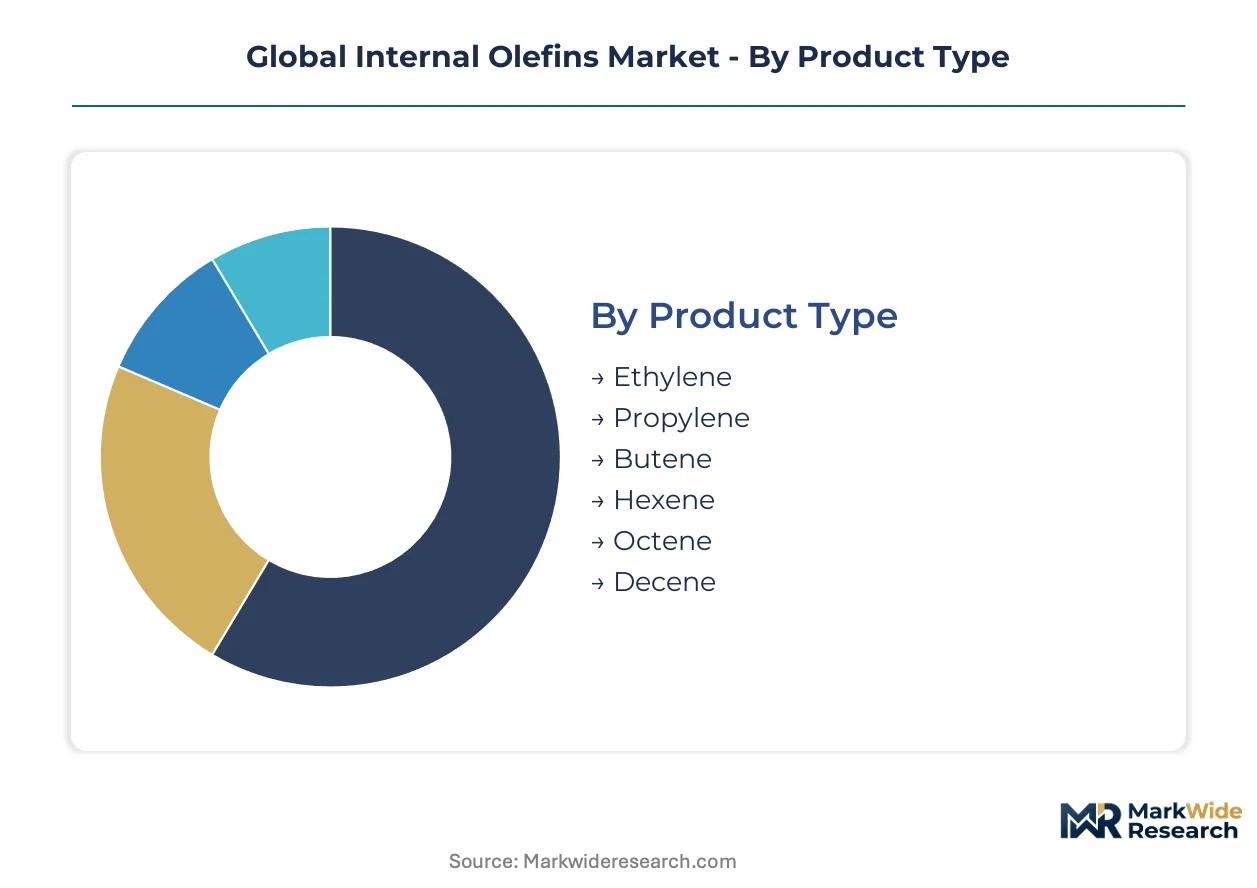
Internal olefins exhibit divergent margin profiles across molecular weights and synthesis routes, compelling producers to align capital deployment with end-use specification premiums. Segmentation clarity enables buyers to match purity grades against REACH-registered surfactant formulations or polymer comonomer requirements.
Product Type:
Capital intensity escalates sharply with carbon chain length, as C8+ fractions demand precision metathesis or oligomerization trains that C4 units bypass through simpler steam cracking.
- Octene:Synthetic lubricant base stocks absorb the majority of octene volumes, where low pour point specifications justify dedicated oligomerization capacity. German and Japanese blenders now validate batches through in-house pilot metathesis units before contract commitment. Octene absorbs the bulk of installed capacity; decene is expanding most quickly.
- Decene:Polyethylene comonomer applications in China are scaling Jiangsu and Zhejiang dehydrogenation capacity to serve domestic polymer value chains. Premium positioning in PAO synthetic lubricants reinforces margin capture for Fischer-Tropsch integrated producers.
- Ethylene:Fundamental feedstock for alpha olefin derivation via oligomerization, with Gulf Coast ethane cracking economics shaping global cost benchmarks.
- Propylene:Metathesis substrate for higher internal olefins, sourced from FCC units and propane dehydrogenation complexes.
- Butene:Intermediate for plasticizer and adhesive applications, produced through steam cracking or butane dehydrogenation routes.
- Hexene:Comonomer for linear low-density polyethylene, with demand tied to packaging film specifications.
Octene absorbs the bulk of installed capacity; decene is expanding most quickly.
Technology:
Process selection determines feedstock flexibility and product slate breadth, with integrated majors favoring routes that co-produce multiple carbon cuts.
- Oligomerization:Advanced catalyst systems enable molecular weight distribution tuning that matches synthetic lubricant pour point and oxidation stability protocols. European producers at Grangemouth and Lavéra complexes anchor supply through dedicated trains with membrane separation retrofits.
- Metathesis:Technology maturation compresses cost gaps against linear alpha olefins, requiring specialized catalysis expertise that competes with pharmaceutical sectors for talent. EPA Toxic Substances Control Act constraints on chlorinated paraffin intermediates limit US route economics.
- Steam Cracking:Conventional ethylene co-production yields light olefin fractions with limited internal olefin specificity.
- Catalytic Cracking:FCC-derived propylene and butene streams feed metathesis units for higher carbon number production.
- Polymerization:Ziegler-Natta and metallocene systems produce alpha olefin precursors for subsequent isomerization.
- Dehydrogenation:China's Jiangsu and Zhejiang capacity additions employ this route for captive octene and decene comonomer supply.
Oligomerization commands the largest existing asset base; metathesis is gaining share fastest through precision catalyst advances.
Application:
Volume concentration versus value capture splits the application map, with commodity surfactants anchoring tonnage and specialty lubricants extracting premium pricing.
- Surfactants:C12-C14 internal olefin sulfonates serve cleaning product mandates under India's FSSAI and BIS quality harmonization, with REACH-registered C10-C13 streams unlocking European formulation volumes previously constrained by regulatory uncertainty.
- Polymer Production:Polyethylene comonomer demand for packaging film performance grades is concentrating in China, where domestic dehydrogenation capacity scales to serve regional value chains. REACH compliance and EPA purity specifications tighten feedstock requirements.
- Synthetic Rubbers:EPDM and polybutadiene production consumes C4-C6 fractions for elasticity and durability specifications.
- Plasticizers:Phthalate and non-phthalate formulations employ C8-C10 cuts for PVC compatibility.
- Adhesives:Hot-melt and pressure-sensitive applications specify narrow molecular weight distributions.
- Chemical Intermediates:Oxo-alcohol and epoxide derivation routes absorb C6-C12 fractions for downstream functionalization.
Surfactants dominate current volume; polymer production is climbing the fastest on polyethylene comonomer demand.
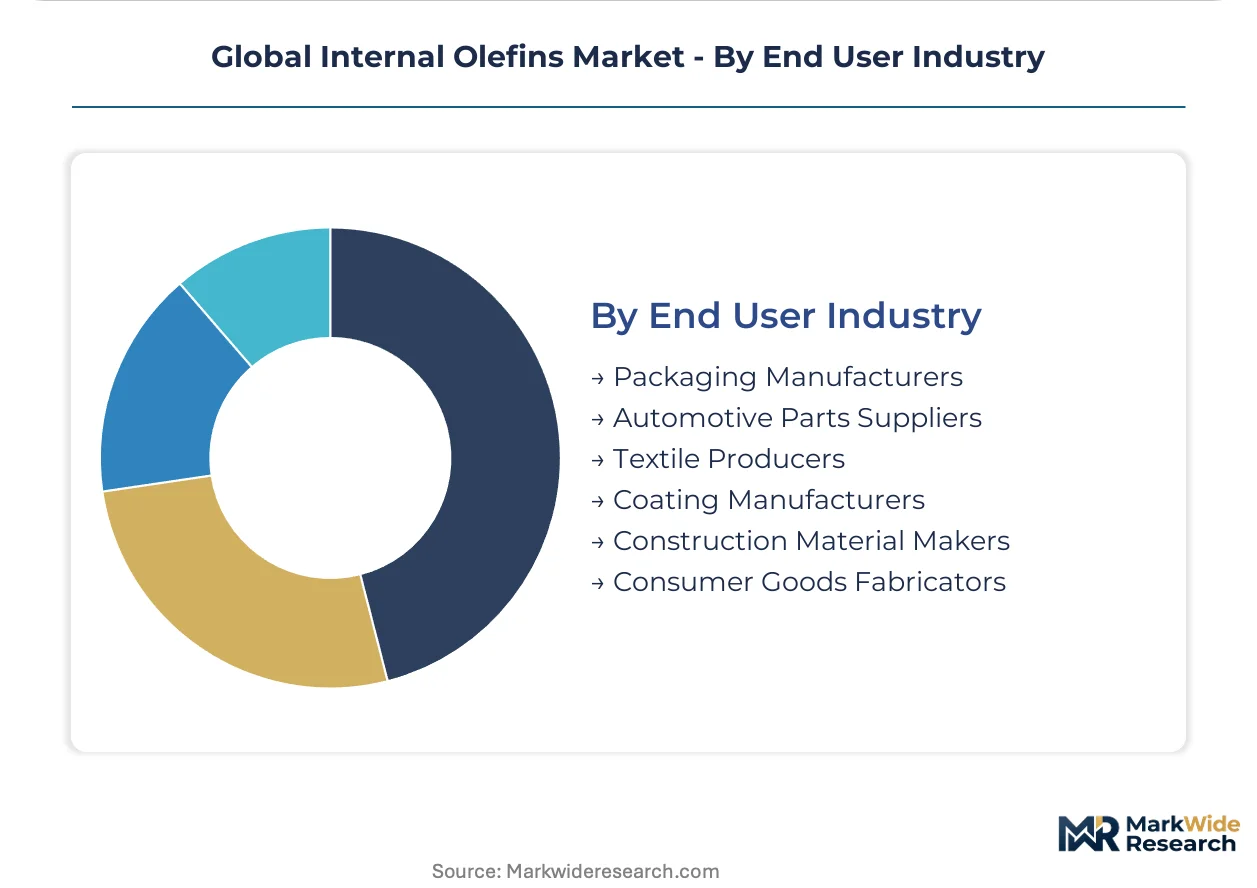
End User Industry:
Customer technical sophistication varies widely, with automotive and packaging buyers conducting direct catalyst validation while construction purchasers rely on distributor specifications.
- Packaging Manufacturers:Performance-grade film specifications for food and industrial applications drive octene and decene comonomer procurement, with blenders unbundling technical service from material supply. Yangtze River Delta concentration exposes buyers to China MEE VOC enforcement on storage terminals.
- Automotive Parts Suppliers:Synthetic lubricant base stock specifications for engine and transmission fluids justify premium internal olefin sourcing, with German formulators establishing in-house metathesis pilot units for batch validation.
- Textile Producers:Fiber lubricant and softener applications consume C12-C14 fractions for spin finish formulations.
- Coating Manufacturers:Paint and varnish applications employ C8-C10 cuts for flow and leveling properties.
- Construction Material Makers:Concrete admixtures and sealant formulations specify mid-range carbon cuts.
- Consumer Goods Fabricators:Personal care and household cleaning products drive C10-C13 sulfonate demand under evolving EPA and REACH purity standards.
Packaging manufacturers absorb the bulk of octene and decene volumes; automotive parts suppliers are expanding procurement fastest on synthetic lubricant specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate Chinese olefin dehydrogenation investments. Gulf Coast petrochemical corridors anchor North American oligomerization capacity. European integrated complexes at Grangemouth and Lavéra sustain metathesis output under REACH compliance frameworks.
United States
Shale-derived ethane cracking economics underpin Gulf Coast internal olefin supply chains. EPA Toxic Substances Control Act restrictions on chlorinated paraffin intermediates constrain alternative production routes and elevate raw material costs. Houston and Corpus Christi host concentrated oligomerization trains exposed to hurricane corridor disruption risks.
China
Domestic polyethylene comonomer demand drives Jiangsu and Zhejiang dehydrogenation capacity scaling. MEE enforces VOC emission caps on Yangtze River Delta olefin storage terminals, compelling floating roof tank retrofits and vapor recovery installations. Ningbo and Shanghai clusters integrate captive octene and decene supply for regional polymer value chains.
Germany
Synthetic lubricant base stock specifications anchor octene and decene procurement from domestic blenders. ECHA REACH registrations for C10-C13 internal olefin streams unlock surfactant formulation volumes previously constrained by regulatory uncertainty. Ludwigshafen and Marl industrial complexes pilot membrane separation retrofits alongside traditional fractionation columns.
Saudi Arabia
Fischer-Tropsch integration advantages position domestic producers for EU Green Deal biobased lubricant mandates. SAMR-aligned export certification protocols facilitate China-bound olefin shipments. Jubail petrochemical city concentrates metathesis and oligomerization capacity serving Asian polymer and surfactant markets.
India
FSSAI cleaning product mandates and BIS quality standards harmonization create specification-grade demand for C12-C14 internal olefin sulfonates. CDSCO registration pathways for surfactant intermediates remain under development. Gujarat and Maharashtra chemical corridors attract formulation investments targeting domestic consumer goods fabricators.
Global Internal Olefins Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated majors commanding polymer-grade volumes and regional compounders capturing surfactant formulation niches. The vendor base organizes around three archetypes: Fischer-Tropsch integrated producers leveraging carbon monoxide hydrogenation economics, Gulf Coast ethane crackers exploiting shale gas feedstock advantages, and Asian dehydrogenation specialists serving captive regional demand. Capacity expansion and strategic technology licensing constitute the dominant competitive moves, with membrane separation retrofits and metathesis catalyst advances reshaping cost positions.
Among Fischer-Tropsch integrated producers, Sasol Limited exemplifies the archetype through its synthetic fuels-derived olefin slate, while INEOS Group Limited anchors European supply architecture through its Grangemouth and Lavéra complex configurations. Chevron Phillips Chemical Company occupies the Gulf Coast oligomerization specialist position, sustaining dedicated train operations against shale-derived feedstock economics. These three entities represent distinct geographic and technological positioning strategies without implying specific market share claims or operational metrics.
| Leading Market Players |
|---|
| INEOS Group Limited |
| Sasol Limited |
| Royal Dutch Shell plc |
| Elevance Renewable Sciences |
| Chevron Phillips Chemical Company |
| SABIC |
| Halliburton Company |
| Schlumberger Limited |
| Idemitsu Kosan Co., Ltd. |
| Others |
Supply & Pricing Matrix
Packaging manufacturers in the Yangtze River Delta cluster anchor global octene and decene procurement, forcing suppliers into contract-based long-term offtake structures with volume-tiered discounts. Their concentration enables direct catalyst performance validation and unbundling of technical service from material supply.
Pricing Analysis
Short lead-time premiums dominate spot transactions, with surfactant compounders paying 15-20 percent markups for emergency octene batches against scheduled contract deliveries. Three-tier pricing structure across polymer-grade, surfactant-grade, and technical-grade levels separates REACH-registered streams from standard purity offerings. Cost compression in surfactant-grade tiers is intensifying because Fischer-Tropsch integrated producers narrow differentials through captive supply advantages. Mid-volume compounders exhibit highest price sensitivity, while synthetic lubricant blenders accept premium positioning for validated pour point performance.
Supply Chain Analysis
Ethane feedstock supply rests on Gulf Coast shale gas production, with oligomerization catalyst systems drawing from German and Japanese specialty chemical producers. Raw material dependencies span Fischer-Tropsch syngas, chlorinated paraffin intermediates, and metathesis-grade molybdenum catalysts. Single-source vulnerability concentrates in hurricane-exposed Corpus Christi and Houston production corridors. Distribution runs through integrated majors with direct pipeline links to polymer complexes, supplemented by specialty chemical marketplaces for spot surfactant-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. REACH registration dossiers for C10-C13 internal olefin streams create a barrier-to-entry moat that rewards early ECHA filers with unlocked European formulation volumes.
For Market Incumbents: To counter metathesis-driven linear alpha olefin substitution, Sasol and INEOS should deepen backward integration into Fischer-Tropsch syngas production and accelerate membrane separation retrofits at Grangemouth and Lavéra. Captive catalyst manufacturing secures supply continuity against molybdenum price volatility.
For New Entrants and Emerging Players: Regional surfactant compounders in Gujarat and Maharashtra present the most penetrable buyer archetype, with FSSAI cleaning product mandates creating specification-grade demand for C12-C14 internal olefin sulfonates. CDSCO registration pathway navigation offers a go-to-market angle distinct from established European and Chinese suppliers.
For Investors and Strategic Acquirers: The window for entry favors Fischer-Tropsch integrated producers with EU Green Deal biobased certification credentials. Long-term viability hinges on sustainability-linked offtake agreements with German synthetic lubricant blenders. Watch for China MEE enforcement intensity across Yangtze River Delta storage terminals as inflection indicator for regional supply disruption risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fischer-Tropsch Syngas | Sasol secures carbon monoxide hydrogenation economics against feedstock volatility. |
| Membrane Separation Retrofit | Grangemouth and Lavéra facilities reduce energy intensity while maintaining polymer-grade purity. |
| REACH Registration Completion | ECHA dossier approvals unlock surfactant formulation volumes previously constrained by regulatory uncertainty. |
| Long-term Supply Agreement | Yangtze River Delta packaging manufacturers lock in octene and decene comonomer security. |
| Joint Venture | Jiangsu and Zhejiang dehydrogenation partnerships serve captive domestic polyethylene demand. |
Research Methodology
Document review covered customs and trade databases, SEC 10-K filings, and ECHA registration dossiers, complemented by interviews with plant managers at oligomerization complexes, procurement leads at packaging manufacturers, distribution channel partners in specialty chemical marketplaces, and technical R&D directors in synthetic lubricant formulation. Bottom-up capacity modeling and top-down demand triangulation validated segment-level outputs.
Market size and growth trajectories across the analysis window reflect analytical framework segmentation by carbon chain length, synthesis technology, application grade, and regional production hub. CAGRs derive from regression against historical capacity utilization and forward projection of polyethylene comonomer intensity and surfactant formulation specifications. Forecast inputs incorporate oligomerization catalyst yield improvements and China MEE compliance cost assumptions.
Revisions become necessary when EPA Toxic Substances Control Act enforcement intensifies against chlorinated paraffin intermediates, REACH registration timelines extend beyond standard ECHA review windows, or hurricane disruption frequency escalates across Gulf Coast production corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
US Trona Market