
 Enzyme Inhibitors Market | 2026-2036
Enzyme Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Enzyme Inhibitors Market Intelligence
Strategic co-development financing models, where large pharmaceutical firms fund the clinical trials of specialized biotech startups, is reconfiguring competitive access to novel drug candidates. Pfizer leverages this approach to expand its oncology pipeline. AstraZeneca sustains its market position through partnerships in cardiovascular research. Novartis, meanwhile, specializes in kinase inhibitors for targeted therapies.
Enzyme inhibitors are molecules designed to bind to the active site of an enzyme, thereby reducing its catalytic activity. These compounds function as therapeutic agents by modulating specific metabolic or signaling pathways. Kinase inhibitors represent the fastest-growing product type, driven by their central role in oncology applications. While pharmaceutical companies remain the largest end-user segment, research institutes are showing accelerated use for studying neurodegenerative disorders.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) dictate the rigorous clinical trial requirements for market approval. In parallel, standards from Japan's PMDA influence development pathways for drugs targeting its population. The primary decision for developers is balancing speed-to-market strategies with the diverse and stringent evidence demands of these global regulators.
Market Dynamics
The central structural force in the enzyme inhibitors market is the rapid expansion of targeted therapies in oncology, enabled by high-throughput screening technologies that drastically shorten the timeline for identifying viable drug candidates against specific enzymatic pathways.
Growth Catalysts
- High-Throughput Screening:Innovations in automated HTS platforms permit the rapid testing of vast chemical libraries against enzyme targets, significantly accelerating the early phases of drug discovery and lead optimization for pharmaceutical pipelines.
- Oncology Drug Development:A deeper biological understanding of cancer pathways fuels demand for novel inhibitors, particularly for kinases. This creates a powerful pull for R&D investment into compounds that can offer more precise and effective treatments.
- Regulatory Incentives:Expedited review programs, such as the FDA's Breakthrough Therapy designation and the EMA's PRIME scheme, incentivize development of inhibitors for unmet medical needs by offering a faster path to market approval.
Market Restraints
- Development Costs:The immense financial outlay required for preclinical studies and multi-phase clinical trials represents a significant barrier to entry, concentrating market power among firms with substantial capital reserves and risk tolerance.
- Off-Target Toxicity:Achieving high specificity for a target enzyme while avoiding interactions with other structurally similar enzymes is a primary technical hurdle, with failures often leading to unacceptable toxicity profiles and late-stage trial terminations.
- Regulatory Heterogeneity:Navigating the divergent and stringent data requirements of global agencies like the US FDA, EMA, and Japan's PMDA complicates clinical trial design and can delay simultaneous global launches.
Strategic Opportunities
- Neurodegenerative Diseases:Expanding the application of enzyme inhibitors beyond oncology into areas like Alzheimer's and Parkinson's disease represents a major growth frontier, with research institutes leading early-stage pathway validation.
- AI in Drug Design:The convergence of artificial intelligence and computational biology allows for the in-silico modeling of enzyme-inhibitor interactions, creating opportunities to design novel molecules with higher potency and specificity before synthesis.
- Personalized Medicine:Developing companion diagnostics to identify patient populations most likely to respond to a specific enzyme inhibitor offers a pathway to improve efficacy, secure reimbursement, and differentiate products in crowded therapeutic areas.
Industry Challenges
- Intellectual Property Congestion:The dense and overlapping patent landscape for well-established enzyme targets, such as certain kinases, creates significant freedom-to-operate challenges and increases the risk of costly litigation for new market entrants.
- Specialized Talent Scarcity:A persistent shortage of experienced computational biologists, toxicologists, and clinical pharmacologists capable of navigating complex inhibitor development programs constrains the operational capacity of many research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzyme Inhibitors Market |
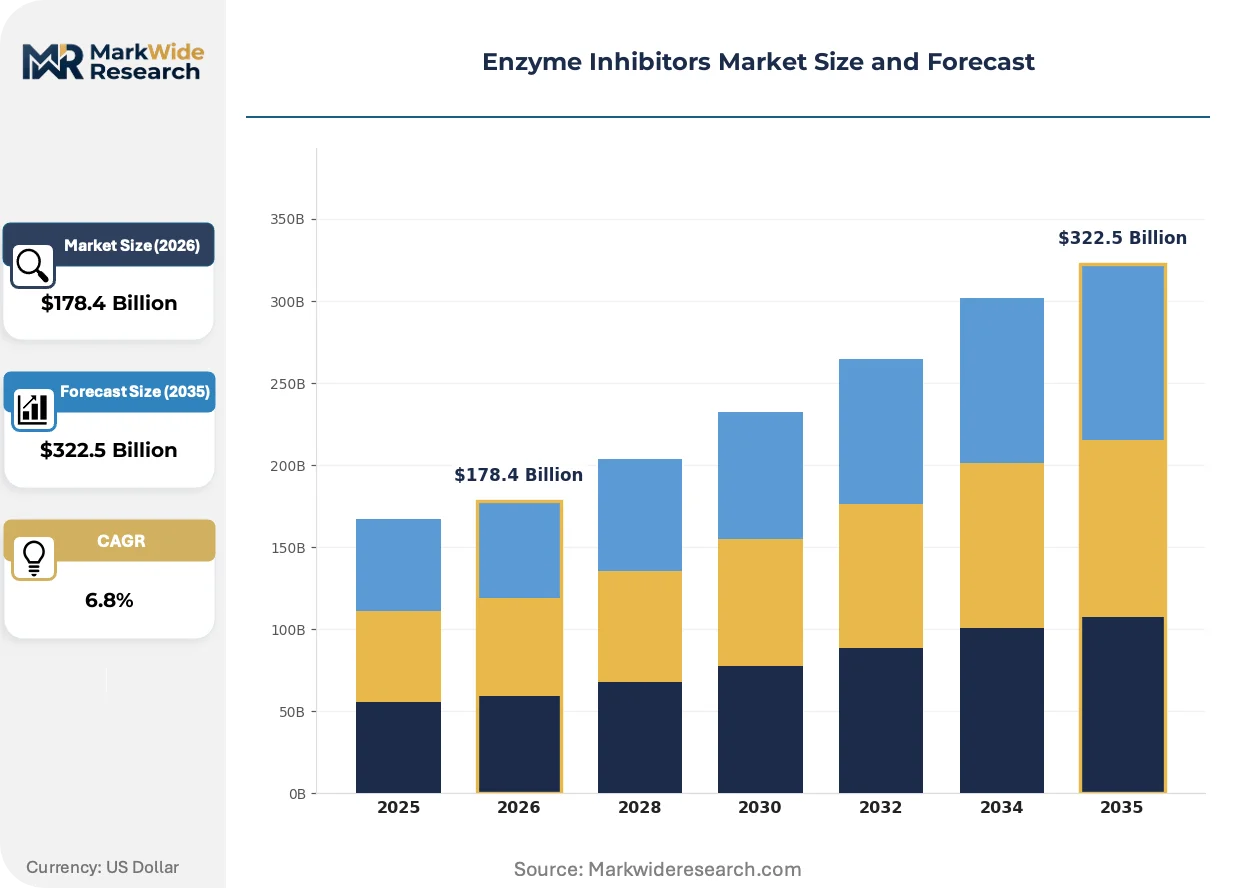
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protease Inhibitors, Kinase Inhibitors, Phosphatase Inhibitors, Polymerase Inhibitors, Ligase Inhibitors Application: Oncology, Neurodegenerative Disorders, Infectious Diseases, Metabolic Disorders, Cardiovascular Conditions End User: Pharmaceutical Companies, Biotech Firms, Research Institutes, Contract Research Organizations, Academic Labs Technology: Small Molecule Inhibitors, Monoclonal Antibodies, Peptide-Based Inhibitors, RNAi-Based Therapeutics, Aptamer Technology |
| Companies Covered | Pfizer, Bayer, AstraZeneca, Boehringer Ingelheim, Abbott Laboratories, Merck, F. Hoffmann-La Roche, GSK, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzyme Inhibitors Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards greater precision and efficiency, with computational tools and novel partnership models fundamentally altering how new enzyme inhibitors are discovered, developed, and brought to market for specific patient populations.
Artificial intelligence-driven platforms are a cornerstone of modern drug discovery, using algorithms to analyze vast datasets and predict molecular interactions. Biotech startups and established pharmaceutical R&D units are rapidly adopting this approach to screen virtual compound libraries. This technology is digitizing the traditionally slow and resource-intensive process of lead compound identification, compressing early-stage development timelines significantly.
Regulatory frameworks are adapting to the pace of innovation, particularly in oncology. The FDA's accelerated approval pathway allows for earlier market access for drugs targeting serious conditions based on surrogate endpoints, a mechanism heavily utilized for enzyme inhibitors. Developers of kinase inhibitors, in particular, leverage this US-based program to shorten the time from pivotal trials to commercialization, providing earlier patient access.
A notable behavioral shift is occurring in R&D funding, moving away from purely internal discovery toward externalized co-development models. Large pharmaceutical firms now frequently finance the costly clinical trials of specialized biotech startups in exchange for future commercialization rights. This symbiotic relationship is most visible within the highly competitive oncology and rare disease research clusters in the United States and Germany.
Enzyme Inhibitors Market Segmentation
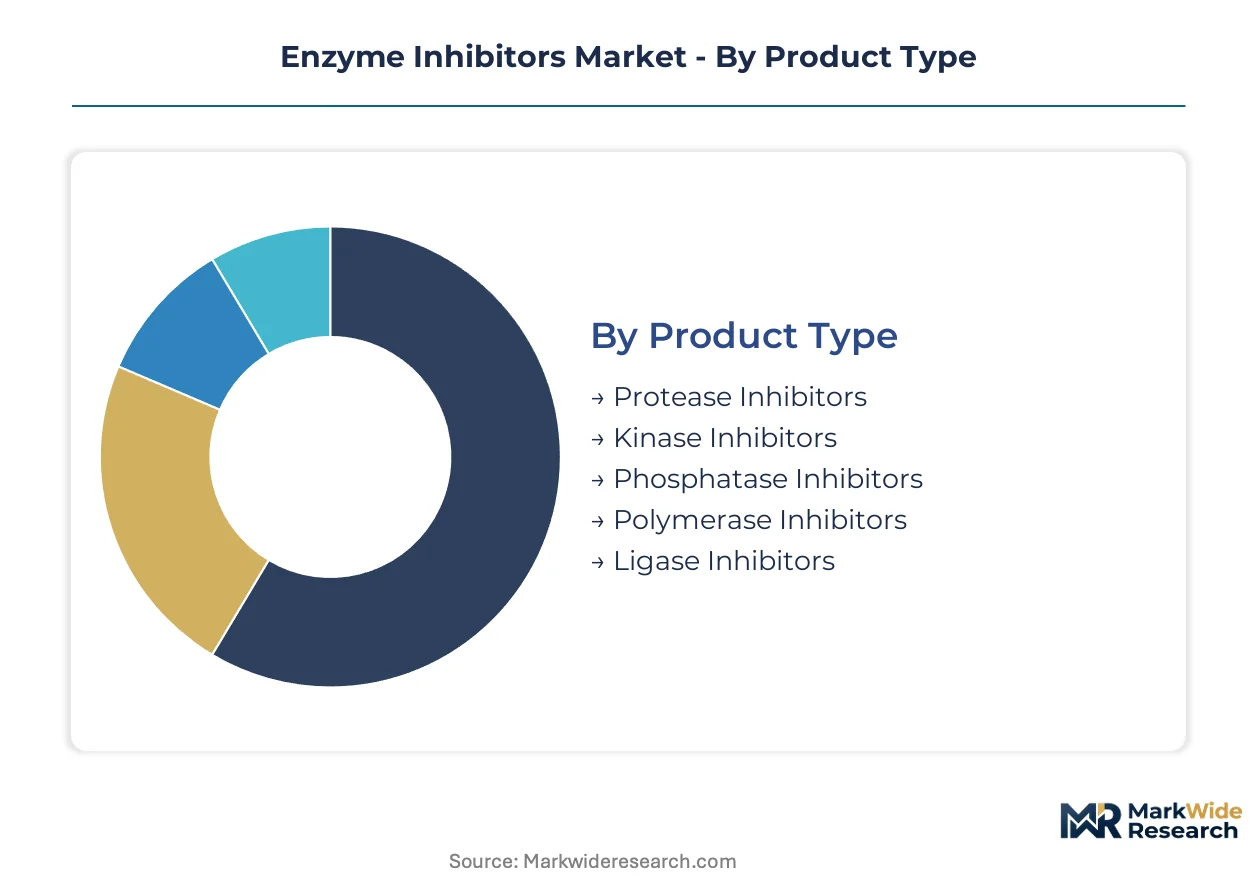
The enzyme inhibitors market is highly diversified, reflecting the broad therapeutic potential and varied mechanisms of action for these critical compounds. Understanding market segmentation is essential for identifying areas of concentrated demand, emerging therapeutic applications, and the operational specificities of different end-user groups. This granular view informs strategic investment in research and development pipelines.
Product Type:
The development cycle for enzyme inhibitors varies significantly by product type, with some classes requiring extensive validation due to complex binding mechanisms, while others benefit from established screening protocols.
- Kinase Inhibitors:These molecules target protein kinases, crucial enzymes in cell signaling pathways, often involved in cancer proliferation. Demand concentrates heavily in oncology therapeutics across the United States and Germany, driven by their effectiveness in targeted cancer treatments.
- Protease Inhibitors:These compounds block the activity of proteases, enzymes that break down proteins, finding applications in infectious diseases and certain cancers. Significant investment in their development continues due to their role in antiviral therapies.
- Phosphatase Inhibitors:These agents modulate phosphatases, enzymes critical for dephosphorylation processes in cellular regulation.
- Polymerase Inhibitors:These molecules interfere with polymerase enzymes, essential for DNA or RNA synthesis, making them relevant in antiviral and antibacterial drug development.
- Ligase Inhibitors:These compounds target ligase enzymes, which catalyze the joining of molecules, holding potential in various therapeutic areas including DNA repair.
Protease Inhibitors anchor the volume base while Kinase Inhibitors gain share at the steepest rate.
Application:
The therapeutic application of enzyme inhibitors dictates specific regulatory pathways and clinical trial designs, with some areas like oncology experiencing faster approval timelines due to unmet medical needs.
- Oncology:Enzyme inhibitors in oncology target specific cancer cell pathways, offering more precise treatments than traditional chemotherapy. The US Food and Drug Administration (FDA) and European Medicines Agency (EMA) have established expedited review programs for these therapies, accelerating market access.
- Neurodegenerative Disorders:These applications focus on modulating enzymes involved in the progression of diseases like Alzheimer's and Parkinson's. Research institutes in the United States are leading early-stage pathway validation efforts, signaling future growth.
- Infectious Diseases:Enzyme inhibitors are vital in combating viral and bacterial infections by disrupting pathogen replication or survival mechanisms.
- Metabolic Disorders:This segment involves inhibitors targeting enzymes implicated in metabolic imbalances, such as diabetes and obesity.
- Cardiovascular Conditions:Enzyme inhibitors play a role in managing heart-related conditions by modulating pathways involved in blood pressure regulation or clot formation.
Oncology applications command significant market attention, while neurodegenerative disorders represent an expanding frontier for novel enzyme inhibitor development.
End User:
The procurement patterns for enzyme inhibitors vary considerably among end-user segments, influenced by internal R&D capabilities, funding models, and the scale of clinical operations.
- Pharmaceutical Companies:These large entities engage in extensive in-house research and development, often leveraging co-development financing models with biotech startups. Their demand for inhibitors spans all therapeutic areas, focusing on late-stage clinical trials and commercialization.
- Research Institutes:These academic and non-profit organizations conduct fundamental research and early-stage drug discovery, particularly in emerging areas like neurodegenerative disorders. They represent an accelerating user segment for studying novel enzymatic pathways.
- Biotech Firms:Specialized biotech firms focus on innovative drug candidates, often partnering with larger pharmaceutical companies for clinical development and market access.
- Contract Research Organizations:CROs provide specialized research services to pharmaceutical and biotech companies, including preclinical testing and clinical trial management for enzyme inhibitors.
- Academic Labs:Academic laboratories contribute to basic scientific understanding of enzyme function and inhibition mechanisms, often using inhibitors as research tools.
Pharmaceutical Companies maintain the largest purchasing volume, while Research Institutes drive early-stage innovation and pathway validation.
Technology:
The maturity curve for enzyme inhibitor technologies ranges from well-established small molecules to nascent gene-editing approaches, each presenting distinct development hurdles and market entry strategies.
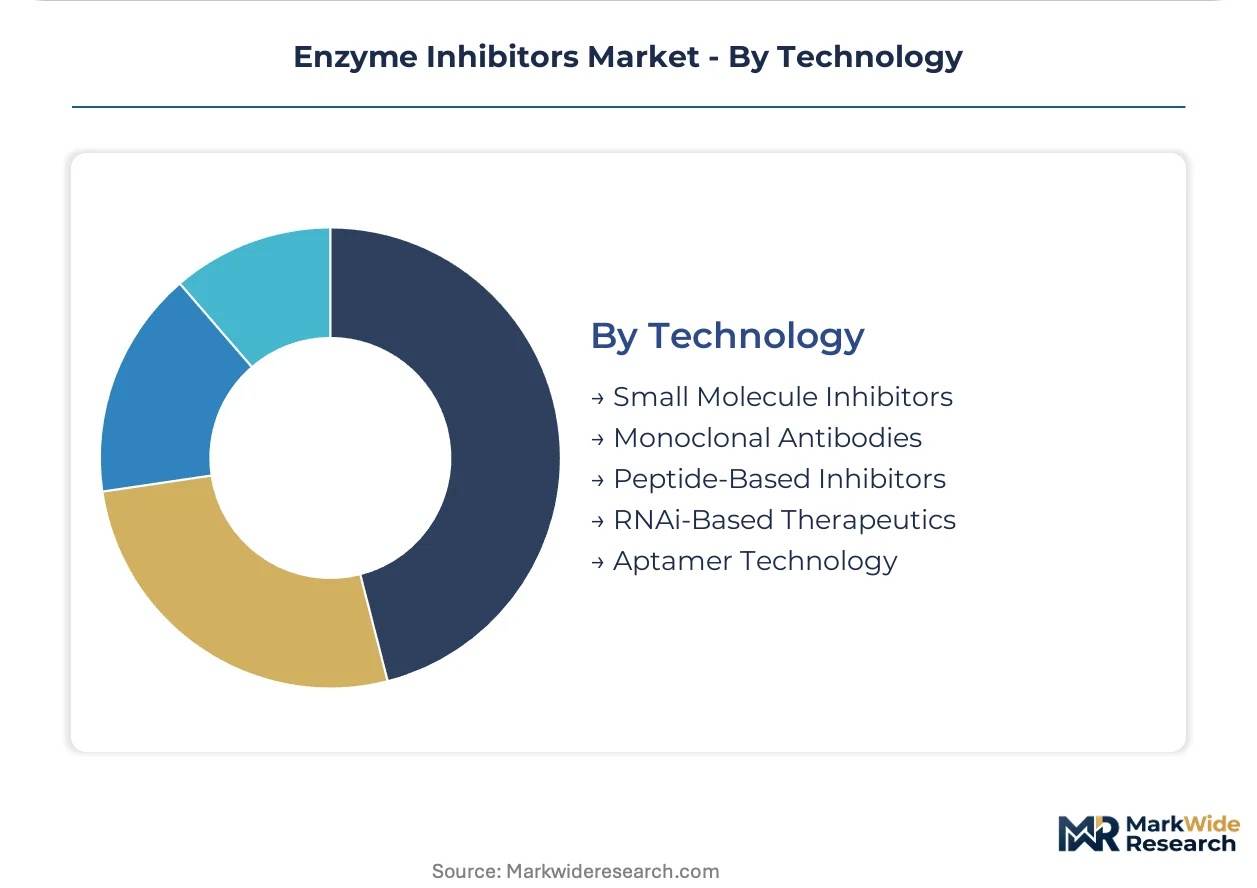
- Small Molecule Inhibitors:These are chemically synthesized compounds designed to bind to enzyme active sites, representing the most common and mature technology. They offer advantages in oral bioavailability and manufacturing scalability.
- Monoclonal Antibodies:These biologics specifically target and neutralize enzymes or their receptors, offering high specificity and reduced off-target effects. Their development is capital-intensive but yields highly effective targeted therapies.
- Peptide-Based Inhibitors:These inhibitors are short chains of amino acids that can mimic natural substrates or block enzyme activity. They offer high specificity but often face challenges with stability and delivery.
- RNAi-Based Therapeutics:This technology uses RNA interference to silence the genes responsible for producing target enzymes, representing a cutting-edge approach to enzyme modulation.
- Aptamer Technology:Aptamers are nucleic acid molecules that bind to specific target molecules, including enzymes, with high affinity and specificity, offering an alternative to antibody-based inhibitors.
Small Molecule Inhibitors dominate current market offerings, while Monoclonal Antibodies are experiencing substantial expansion due to their precision and efficacy in targeted treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical companies and research institutes, as primary buyers of enzyme inhibitors, concentrate their activities in key global hubs. These regions drive both the demand for novel therapeutic agents and the foundational research into enzymatic pathways. Stringent regulatory frameworks and advanced scientific infrastructure support market expansion.
United States
The United States drives significant demand for enzyme inhibitors, particularly in oncology and neurodegenerative disorder research. The FDA's accelerated approval pathway incentivizes rapid development for unmet medical needs. Biotech clusters in Boston and the San Francisco Bay Area lead early-stage discovery and clinical trials.
Germany
Germany represents a core European market for enzyme inhibitors, fueled by strong oncology therapeutics development. The European Medicines Agency's PRIME scheme supports expedited market access for innovative therapies. Biotech clusters around Munich and Berlin specialize in advanced R&D initiatives.
Japan
Japan exhibits unique demand patterns for enzyme inhibitors, driven by a focus on targeted therapies for its specific population. The PMDA dictates rigorous development pathways for market approval within the country. Major pharmaceutical R&D facilities in Tokyo and Osaka contribute to local innovation.
China
China's expanding healthcare market generates substantial demand for enzyme inhibitors, particularly in infectious diseases and metabolic disorders. The NMPA actively works to streamline drug approvals, impacting development timelines. Shanghai and Beijing are rapidly becoming significant biotech innovation centers.
India
India's pharmaceutical sector shows rising demand, supported by its robust generic drug manufacturing base and increasing R&D investments. The CDSCO ensures regulatory compliance for both domestic production and clinical trials. Hyderabad and Bengaluru are evolving as key pharmaceutical research and development hubs.
Enzyme Inhibitors Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping the enzyme inhibitors market into a tiered competitive structure. Large pharmaceutical firms, with their extensive distribution networks and R&D budgets, often dominate late-stage development and commercialization. Specialized biotech firms, on the other hand, focus on innovative drug candidates and early-stage discovery. Strategic partnerships and co-development financing models represent key competitive moves to access novel drug candidates.
Within the large pharmaceutical archetype, Pfizer Inc. and AstraZeneca PLC exemplify firms actively expanding their oncology pipelines through strategic co-development models. These global entities leverage substantial capital reserves to fund clinical trials of specialized biotech startups, securing future commercialization rights. Meanwhile, Novartis AG, a Swiss-based pharmaceutical giant, occupies a distinct position by specializing in kinase inhibitors for targeted therapies. These companies collectively anchor the market's commercialization phase, driving significant investment into advanced therapeutic areas.
| Leading Market Players |
|---|
| Pfizer |
| Bayer |
| AstraZeneca |
| Boehringer Ingelheim |
| Abbott Laboratories |
| Merck |
| F. Hoffmann-La Roche |
| GSK |
| Novartis |
| Others |
Cost & Logistics Intelligence
Biotech clusters in the United States and Germany drive specialized enzyme inhibitor capacity, influencing premium pricing structures for novel compounds. The high capital expenditure required for advanced research and manufacturing in these hubs directly impacts the cost of lead candidates.
Pricing Analysis
Certification level (FDA/EMA approval) creates the primary spread in enzyme inhibitor pricing. The dominant pricing model leans towards value-based contracts and long-term licensing agreements, reflecting the significant R&D investment. Price differentiation stems from clinical efficacy, target specificity, and the therapeutic area's unmet medical need. Pricing pressure arises from healthcare payers demanding cost-effectiveness for commercialized products. Research institutes exhibit lower price sensitivity for early-stage research tools, while pharmaceutical companies are highly sensitive for late-stage clinical candidates.
Supply Chain Analysis
Export control regimes for highly specialized chemical precursors or biological materials can limit cross-border flows. Supply concentration for enzyme inhibitors centers in the United States, Germany, and Japan, which host advanced R&D and manufacturing facilities. Raw material dependencies include specialized reagents for high-throughput screening and active pharmaceutical ingredients (APIs). Single-source vulnerability for novel APIs represents a structural risk. Distribution primarily involves direct channels to pharmaceutical companies and research institutes, often requiring specialized cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enzyme inhibitors market presents a defensive moat due to regulatory entrenchment and high switching costs associated with complex drug development pathways.
For Market Incumbents:
Pre-empt emerging competition by investing heavily in next-generation high-throughput screening technologies. Consolidate market share through strategic co-development financing models, particularly with biotech startups possessing novel oncology pipelines. This approach mitigates the threat from smaller, agile firms leveraging AI-driven drug design. Reinforce channel control by leveraging established commercialization networks for new therapeutic agents.
For New Entrants and Emerging Players:
Pursue niche applications in areas like neurodegenerative disorders where unmet medical needs are substantial and research institutes lead early-stage pathway validation. Target specific kinase inhibitor subtypes with high selectivity to address off-target toxicity challenges. A viable go-to-market angle involves partnering with larger pharmaceutical firms for clinical development and global market access, leveraging their capital and regulatory expertise.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized biotech firms with strong intellectual property in novel enzyme targets or advanced computational biology platforms. Long-term viability is robust, driven by expanding applications beyond oncology and sustained R&D investment. Identify acquisition targets with promising Phase II clinical trial assets or proprietary AI-driven drug discovery capabilities. A key signal to watch is successful clinical validation for inhibitors in non-oncology therapeutic areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Acceleration | Shortens time-to-market for novel enzyme inhibitors through expedited regulatory pathways. |
| AI-Driven Drug Discovery | Identifies potent molecules with higher specificity, reducing development timelines. |
| Co-Development Partnerships | Expands oncology pipelines for large pharmaceutical firms, sharing R&D risk. |
| Pipeline Diversification | Reduces reliance on single therapeutic areas like oncology, broadening market reach. |
| Regulatory Pathway Optimization | Secures expedited approval for unmet medical needs in key global markets. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from drug development executives, regulatory affairs leads, research institute directors, and biotech founders. This qualitative data was triangulated with quantitative information from secondary sources, including FDA filings, EMA submissions, ClinicalTrials.gov, and relevant academic publications.
Forecast inputs being considered included therapeutic application, product type, end-user segment, and technology maturity. The analytical framework modeled segmentation dimensions such as oncology, neurodegenerative disorders, kinase inhibitors, small molecule inhibitors, pharmaceutical companies, and research institutes. CAGRs were derived from historical growth trends and projected R&D investment across the analysis window. Industry-specific inputs included new drug approvals and clinical trial pipeline progression.
Sensitivities concentrate around unforeseen regulatory changes or breakthroughs in competing therapeutic modalities. Forecasts reflect assumptions concerning R&D investment and market adoption rates over the projection horizon. Material shifts in global health crises or major patent expirations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market