
 Potassium Alum Market | 2026-2036
Potassium Alum Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Alum Market Outlook
REACH is realigning the cost-of-entry calculus for European potassium alum suppliers by mandating stricter purity documentation and supply chain transparency. Merck KGaA leverages its pharmaceutical-grade certification infrastructure to command premium positioning across regulated jurisdictions. Thermo Fisher Scientific anchors its competitiveness through laboratory chemical distribution networks that bypass commodity pricing cycles. Holland Company specializes in water treatment applications, sustaining long-term municipal contracts through technical service bundling.
Potassium aluminium sulfate is a double salt with the chemical formula KAl(SO₄)₂·12H₂O, typically manufactured through the reaction of aluminium sulfate with potassium sulfate followed by controlled crystallization, yielding colorless octahedral crystals soluble in water. The compound functions primarily as a coagulating agent in water purification, a mordant in textile dyeing, and a food additive under designated regulatory thresholds. Powder formulations dominate volume shipments due to handling efficiency in bulk water treatment operations, while pharmaceutical-grade material commands the widest margin pool owing to compendial testing burdens. Food-grade alum encounters tightening substitution pressure from alternative preservatives in processed goods, yet coagulant applications in municipal utilities sustain the largest absolute demand base.
EPA drinking water standards in the United States, ECHA REACH registrations in Europe, and FSSAI food additive limits in India collectively shape product specifications and market access conditions for potassium alum manufacturers. Compliance with these overlapping frameworks requires multi-jurisdictional testing protocols that favor suppliers with established analytical laboratories. Stakeholders must monitor regulatory divergence between pharmaceutical and food-grade standards, as tightening in one category rarely predicts movement in the other.
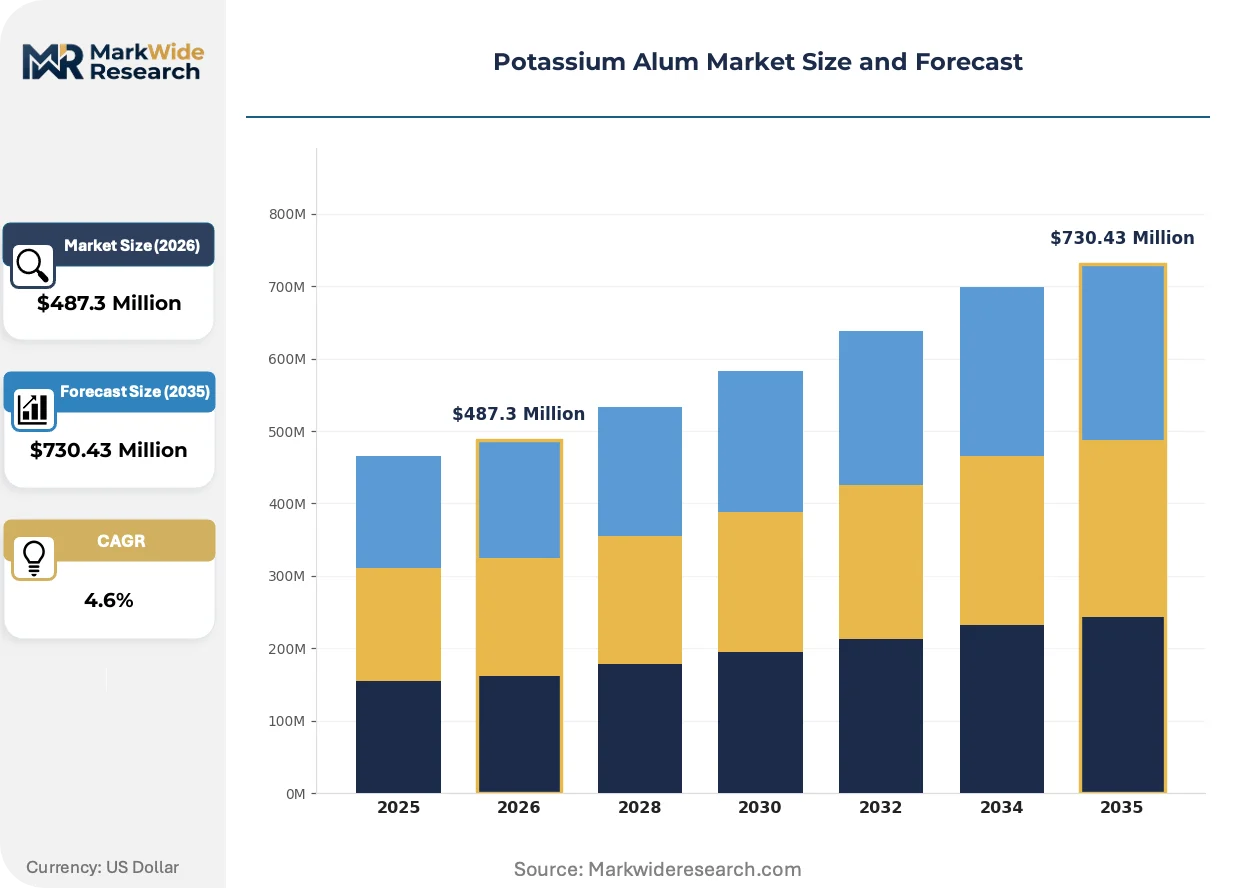
Market Dynamics
REACH compliance in Europe is compressing supplier margins through compendial testing burdens while China's Shandong and Jiangsu industrial corridors concentrate production capacity, creating divergent competitive pressures across regulatory jurisdictions.
Growth Catalysts
- Water treatment infrastructure:Municipal utilities in developing economies are expanding alum procurement for purification systems, with procurement volumes scaling alongside urbanization rates.
- REACH registration thresholds:ECHA mandates are tightening purity documentation requirements, favoring suppliers with established analytical laboratory infrastructure.
- Food additive applications:FSSAI thresholds in India are formalizing quality benchmarks that standardize market access conditions for compliant manufacturers.
Market Restraints
- Aluminum sulfate input volatility:Feedstock price swings compress margin predictability for crystallization-based production methods.
- Shandong-Jiangsu concentration:Over two-thirds of industrial-grade capacity clusters in these Chinese provinces, exposing buyers to geographic supply risk.
- Polyaluminum chloride substitution:Municipal water treatment operators in North America are trialing alternative coagulants with lower sludge generation profiles.
Strategic Opportunities
- Pharmaceutical-grade compounding:Astringent applications in dermatological preparations offer margin expansion beyond commodity water treatment pricing.
- Textile mordant recovery:Dye-house effluent recycling systems in Bangladesh and Vietnam are creating closed-loop alum demand.
- Laboratory reagent channels:Distribution partnerships with scientific supply networks bypass cyclical municipal tendering patterns.
Industry Challenges
- Analytical chemist scarcity:Multi-jurisdictional testing protocols require specialized talent pools that compete with pharmaceutical and biotechnology sectors.
- Crystallizer retrofit timelines:REACH-mandated purity upgrades demand eighteen-to-twenty-four-month equipment modification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Alum Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Aluminium Sulfate, Powder, Granule, Liquid End Use Industry: Water Treatment, Food Processing, Cosmetics, Paper Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Coagulant, Flocculant, pH Regulator, Preservative |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Holland Company, Sigma-Aldrich, ICL Group, Baslini SpA, Zibo Dazhong Edible Chemical Co. Ltd., Nanjing Jiayi Sunway Chemical, Powder Pack Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Alum Market Strategic Shifts
Automation of quality assurance and crystallization control is compressing batch-to-batch variation while regulatory documentation digitization is reshaping supplier-buyer information exchange protocols across pharmaceutical and food-grade segments.
Continuous crystallization monitoring via inline particle size analyzers is automating quality control in pharmaceutical-grade production. European manufacturers with GMP certifications are deploying these systems fastest, reducing manual sampling labor and compendial testing rejection rates. The technology is automating consistency verification that previously required offline laboratory analysis.
ECHA's SCIP database requirements under REACH are mandating supply chain transparency declarations for alum-containing articles. Suppliers must now document full substance origin pathways, increasing administrative overhead but creating differentiation for vertically integrated producers. Pharmaceutical-grade shipments to EU member states face the most intensive documentation scrutiny.
Specification-driven tendering is consolidating municipal water treatment procurement into multi-year framework agreements with technical service bundling. Large utilities in the United States are displacing spot purchasing through master service contracts that lock in volume commitments. California and Texas municipalities are pioneering this consolidation pattern.
Potassium Alum Market Segmentation
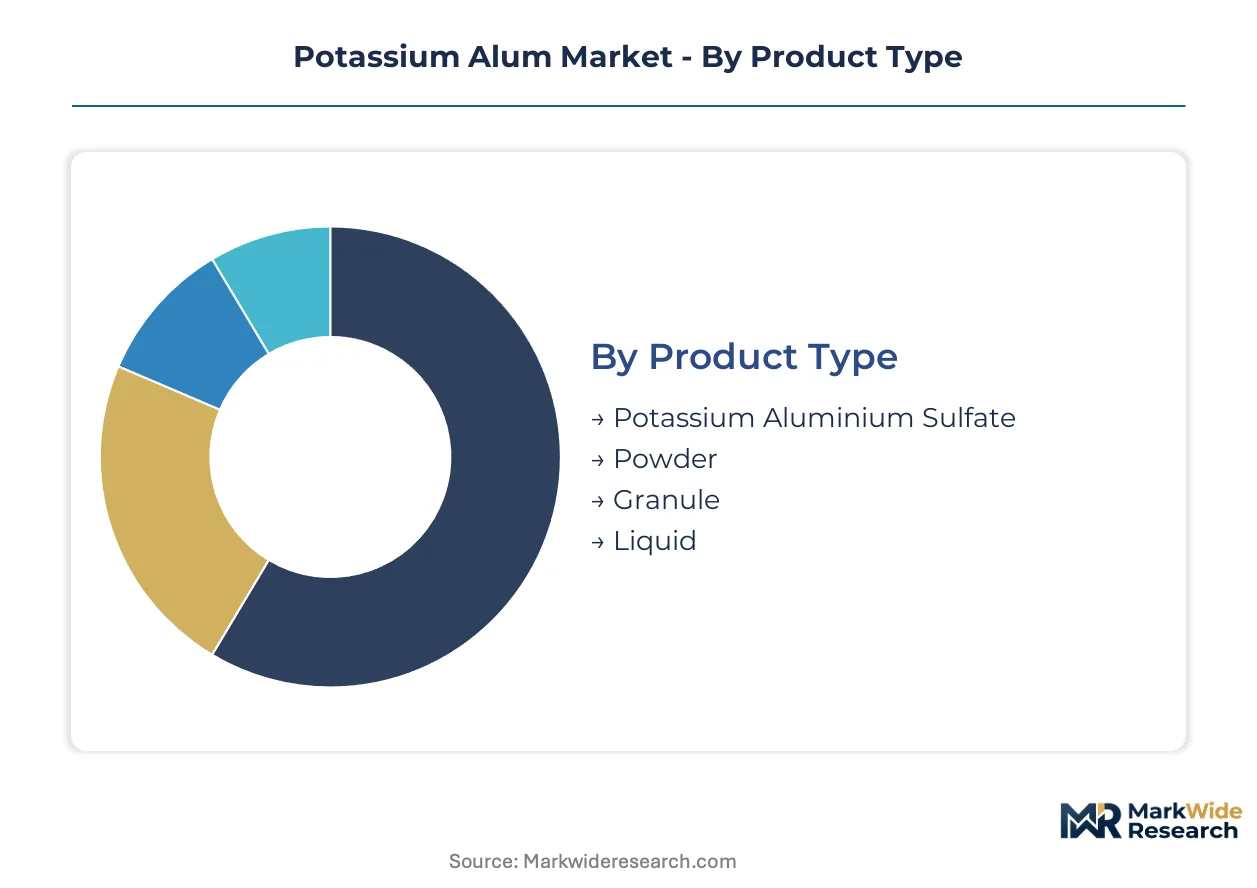
Potassium alum demand fragments across purity thresholds and physical states that dictate procurement channels. Grade certification and formulation type determine margin capture, with pharmaceutical and food segments commanding testing premiums over commodity industrial supply.
Product Type:
Powder and granule formulations integrate directly into bulk handling systems, while liquid variants embed into continuous dosing infrastructure.
- Powder:Fine crystalline material with bulk density optimized for pneumatic conveying in municipal water treatment plants. Procurement concentrates in developing economy utilities scaling purification capacity alongside urbanization.
- Liquid:Pre-dissolved solution eliminating on-site dissolution equipment, embedding into automated chemical feed systems at large North American and European treatment facilities where labor minimization drives specification.
- Potassium Aluminium Sulfate:Anhydrous or lower-hydrate variants for specialized industrial synthesis.
- Granule:Free-flowing agglomerated crystals reducing dust generation during manual handling.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
End Use Industry:
Cost tiers separate capital-intensive municipal infrastructure from formulation-sensitive consumer goods manufacturing.
- Water Treatment:Municipal and industrial purification systems consuming bulk alum as primary coagulant. Demand clusters in China's Shandong-Jiangsu corridor and expanding Indian utilities under tightening BIS drinking water standards.
- Food Processing:Pickling and baking applications requiring FSSAI-compliant food-grade certification. Substitution pressure from alternative preservatives constrains volume growth in processed goods segments.
- Cosmetics:Astringent and antiperspirant formulations in dermatological preparations.
- Paper:Sizing agent in specialty paper manufacturing, particularly in Bangladesh and Vietnamese mills.
Water Treatment dominates absolute volume; Cosmetics exhibits the steepest margin expansion trajectory.
Grade:
Margin stratification follows testing burden intensity, with pharmaceutical certification creating the widest spread over technical-grade commodity supply.
- Industrial Grade:Uncompounded crystalline material for water treatment and paper sizing. Shandong and Jiangsu producers concentrate capacity here, exposing buyers to geographic concentration risk.
- Pharmaceutical Grade:USP/EP-compliant material with full compendial documentation for astringent and hemostatic applications. REACH-mandated SCIP database requirements intensify supply chain transparency burdens for EU-bound shipments.
- Food Grade:FSSAI and FDA-compliant material for direct food contact applications.
- Technical Grade:Lower-purity material for non-critical industrial synthesis and textile mordants.
Industrial Grade anchors volume; Pharmaceutical Grade captures the fastest value expansion.
Application:
Customer type separates municipal procurement officers from formulation chemists in consumer goods laboratories.
- Coagulant:Primary charge-neutralization mechanism in turbidity removal, embedding into conventional water treatment trains. EPA drinking water standards in the United States and parallel frameworks in India and China sustain specification stability.
- Flocculant:Bridging agent enhancing particle aggregation downstream of initial coagulation. Polyaluminum chloride substitution trials in North American utilities threaten displacement in sludge-sensitive operations.
- pH Regulator:Buffering capacity in specialized industrial processes.
- Preservative:Antimicrobial function in traditional food preparation methods.
Coagulant claims the largest volume placement; Flocculant faces the most substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's chemical industry incentive zones concentrate over two-thirds of industrial-grade potassium alum capacity, creating a geographic supply anchor that shapes procurement patterns across Asia-Pacific and export markets.
China
Municipal water treatment utilities in Jiangsu and Shandong provinces drive bulk alum procurement alongside expanding pharmaceutical manufacturing in the Yangtze River Delta. GB standards administered by SAMR tighten food-grade purity thresholds for domestic consumption. Qingdao's port infrastructure enables crystalline alum exports to Southeast Asian textile dyeing operations.
United States
EPA drinking water standards sustain coagulant demand across municipal utilities in California and Texas, where drought-driven water reuse intensifies chemical dosing requirements. Master service contracts are displacing spot purchasing in large metropolitan systems. Houston's petrochemical corridor hosts blending operations serving Gulf Coast treatment facilities.
Germany
REACH registration mandates through ECHA compel pharmaceutical-grade suppliers to maintain SCIP database transparency for EU-bound shipments. Merck KGaA leverages existing GMP certification infrastructure to command premium positioning. Darmstadt's analytical laboratory cluster supports compendial testing burdens for regulated jurisdictions.
India
FSSAI food additive limits formalize quality benchmarks for pickling and baking applications while BIS drinking water standards expand municipal procurement in Delhi-NCR and Maharashtra. Gujarat's chemical manufacturing belt concentrates technical-grade production for domestic textile mordant demand. Surat's dye-house sector sustains closed-loop alum recovery system adoption.
Brazil
ANVISA pharmaceutical regulations shape import specifications for astringent dermatological preparations while municipal utilities in São Paulo state expand purification capacity. São Paulo's industrial corridor hosts distribution nodes serving Andean mining operations. Minas Gerais water treatment cooperatives trial alternative coagulants amid sludge disposal cost pressures.
Potassium Alum Market Competitive Environment
Chinese producers anchor the commodity industrial-grade tier; European and North American specialists hold premium-grade positioning through certification infrastructure. Market structure fragments across purity thresholds rather than consolidating around scale, with three archetypes dominating: vertically integrated chemical conglomerates with crystallization capacity, laboratory reagent distributors with scientific supply networks, and regional water treatment service bundlers with municipal contract expertise. Capacity expansion and regulatory certification upgrades represent the dominant competitive moves.
Among Germany-based pharmaceutical-grade suppliers, Merck KGaA exemplifies the certification-driven archetype through its compendial documentation infrastructure. Thermo Fisher Scientific occupies a position within the laboratory reagent distribution tier, leveraging scientific supply networks that bypass commodity pricing cycles. Holland Company represents the service-bundling specialist archetype, anchoring competitiveness through long-term municipal contracts with technical support integration.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Holland Company |
| Sigma-Aldrich |
| ICL Group |
| Baslini SpA |
| Zibo Dazhong Edible Chemical Co. Ltd. |
| Nanjing Jiayi Sunway Chemical |
| Powder Pack Chem |
| Others |
Value Chain & Pricing Dynamics
REACH-mandated SCIP database transparency gates qualified supply for European pharmaceutical-grade shipments while simultaneously erecting premium-tier pricing access barriers that favor vertically integrated producers with captive analytical infrastructure. This regulatory filter compresses margin predictability for crystallization-based manufacturers lacking GMP certification pathways.
Pricing Analysis
Short lead-time premiums of fifteen-to-twenty percent over contract baselines reward suppliers with crystallizer retrofit completion and REACH documentation readiness, while spot inventory discounts clear working capital for Shandong producers facing aluminum sulfate feedstock volatility. Three-tier pricing structure across pharmaceutical, food, and industrial grade levels anchors differentiation to compendial testing burden and certification infrastructure investment. Cost compression in industrial-grade powder runs through polyaluminum chloride substitution trials in North American municipal utilities. Municipal procurement officers in developing economies exhibit highest price sensitivity; pharmaceutical formulation chemists demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from European pharmaceutical manufacturers mandate multi-supplier qualification across at least two of Germany, China, and India to mitigate geographic concentration risk. Raw material dependencies center on aluminum sulfate from bauxite refining, potassium sulfate from potash mining, and crystallization energy inputs. Single-source vulnerability concentrates in Shandong-Jiangsu corridor capacity exceeding two-thirds of industrial-grade global output. Distribution runs through laboratory reagent networks for pharmaceutical-grade, bulk chemical distributors for water treatment, and direct mill relationships for textile mordant applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemist scarcity across compendial testing functions props pricing for certified suppliers while crystallizer retrofit timelines extend eighteen-to-twenty-four months, constraining rapid capacity response.
For Market Incumbents: To counter polyaluminum chloride substitution in North American municipal water treatment, Merck KGaA and European GMP-certified suppliers should deepen backward integration into pharmaceutical-grade crystallization capacity and anchor long-term municipal contracts through technical service bundling that embeds alum into multi-year framework agreements. For New Entrants and Emerging Players: FSSAI formalization of food additive limits in India opens a window for Gujarat-based technical-grade producers to upgrade certification infrastructure and capture pickling and baking applications from informal suppliers. Target Bangladesh and Vietnamese dye-house effluent recycling systems for closed-loop mordant recovery partnerships, leveraging direct mill relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: REACH-mandated SCIP database requirement enforcement is the leading indicator that pharmaceutical-grade certification infrastructure will command sustained premium multiples. Five-to-ten year viability favors acquisition of European laboratory reagent distributors with established scientific supply networks and existing ECHA registration pathways. Monitor aluminum sulfate price volatility indices as the inflection signal for margin compression timing in commodity-grade exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Crystallizer Retrofit Completion | Eighteen-to-twenty-four-month equipment cycles unlock REACH-compliant pharmaceutical-grade shipment eligibility to EU member states. |
| Backward Integration into Aluminum Sulfate | Captive feedstock supply from bauxite refining insulates margin predictability against commodity price swings. |
| GMP Certification Investment | Compendial documentation infrastructure commands premium positioning across regulated jurisdictions including Germany and the United States. |
| Long-term Municipal Supply Agreement | Master service contracts in California and Texas displace spot purchasing and lock volume commitments. |
| Closed-loop Mordant Recovery Partnership | Dye-house effluent recycling systems in Bangladesh and Vietnam create differentiated alum demand outside commodity cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with plant managers at Shandong and Jiangsu crystallization facilities, procurement leads at municipal water treatment utilities, distribution channel partners in laboratory reagent networks, and technical R&D directors at pharmaceutical-grade manufacturers provided operational validation. ECHA REACH registration databases, FSSAI food additive notifications, EPA drinking water compliance reports, and SAMR GB standards publications supplied regulatory boundary conditions. Bottom-up volume modeling triangulated against top-down demand aggregation across grade tiers and end-use industries.
Granularity-level modeling disaggregated shipments by pharmaceutical, food, industrial, and technical grade tiers; powder, liquid, and granule formulation types; water treatment, food processing, cosmetics, and paper end-use industries; and coagulant, flocculant, pH regulator, and preservative applications. CAGRs derived from regression analysis of historical procurement patterns projected across the analysis window. Industry-specific forecast inputs incorporated urbanization rates for developing economy municipal demand and polyaluminum chloride substitution trial progress in North American utilities.
The model assumes a particular technology adoption path; alternative pathways for continuous crystallization monitoring via inline particle size analyzers would alter the outlook for pharmaceutical-grade batch rejection rates and labor cost structures. Deviation in ECHA enforcement intensity for SCIP database compliance would shift the outlook materially for European market access conditions and premium-tier pricing sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global E Series Glycol Ether Market
Chemicals
Acid Anhydrides Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Cupric Chloride Market
Chemicals
Global Cresols Market
Chemicals
Ferric Chloride Market
Chemicals
Benzhydrol Market
Chemicals
Potassium Permanganate Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Isopropanolamine Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Asia-Pacific Non-Phthalate Plasticizers Market
Chemicals
Anhydrides Market
Chemicals
Muriatic Acid Market
Chemicals
p-Coumaric Acid Market