
 Fine Hydrate Market | 2026-2036
Fine Hydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Hydrate Market Analysis
Direct procurement partnerships between hydrate producers and pharmaceutical compounders is reshaping how fine hydrate reaches end users. Nabaltec AG leverages its flame-retardant technology heritage to sustain technical credibility across European industrial markets. Huber Engineered Materials anchors North American supply through specialized precipitation facilities. Hindalco Industries Limited competes on alumina feedstock integration, while Sumitomo Chemical Co., Ltd. differentiates via ultra-high-purity grades for electronic applications.
Fine hydrate denotes precipitated aluminum hydroxide with controlled particle size distribution, typically below 10 microns, manufactured through seeded precipitation or Bayer process refinement for use as flame retardant filler, pharmaceutical excipient, or chemical intermediate. Industrial-grade hydrates dominate volume flows into plastics and rubber compounding, where cost efficiency outweighs purity premiums. Pharmaceutical-grade hydrates command superior margins from tablet disintegrant and antacid applications, while cosmetic-grade variants gain share in mineral sunscreen formulations as titanium dioxide alternatives face regulatory pressure.
EPA oversight of aluminum processing effluents and REACH registration requirements for nano-scale hydrate particles constrain capacity expansion in Western markets. FDA excipient monograph standards and ICH Q3D elemental impurity guidelines elevate qualification barriers for pharmaceutical-grade supply. ISO 10993 biocompatibility testing protocols further segment the medical-grade subset. Stakeholders must weigh feedstock security against certification investments as regional purity standards diverge.
Market Dynamics
REACH compliance in Europe is compressing the supplier base for personal care-grade fine hydrate, forcing producers to consolidate precipitation capacity or exit cosmetic applications entirely. This regulatory pressure cascades through pharmaceutical and industrial segments, redistributing margin pools toward certified producers.
Growth Catalysts
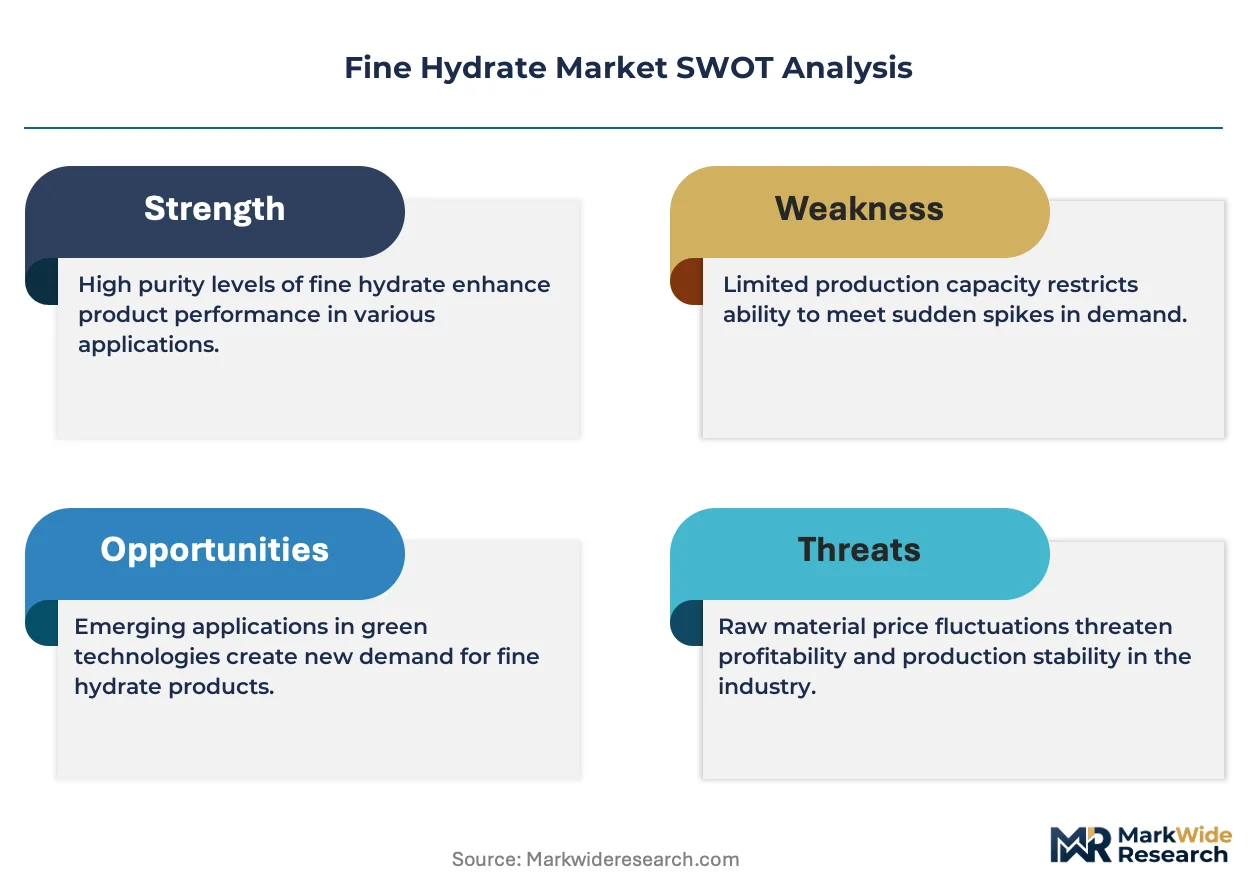
- Flame-retardant mandate expansion:Construction codes in Germany and France now require halogen-free fillers in public infrastructure, pulling industrial-grade hydrate into cable sheathing and insulation compounds.
- EMA excipient qualification pathway:Streamlined monograph updates for aluminum hydroxide antacids accelerate pharmaceutical-grade adoption across EU generic drug manufacturing.
- Bayer process refinement:Seeded precipitation technology originating in Leverkusen specialty chemicals clusters now yields sub-5-micron particle distributions for high-performance rubber compounding.
Market Restraints
- Alumina feedstock concentration:Bayer liquor supply concentrates among integrated aluminum smelters, exposing hydrate producers to bauxite cost volatility and captive pricing.
- Nano-scale particle registration:ECHA's evolving nanoform requirements create compliance uncertainty for sub-100nm hydrate variants entering European cosmetics.
- Magnesium hydroxide substitution:Lower-decomposition-temperature alternatives capture share in polyolefin cable applications where processing temperatures permit.
Strategic Opportunities
- India pharmaceutical excipient localization:CDSCO's phased import substitution incentives create opening for domestic hydrate producers to displace European supply in tablet manufacturing.
- Mineral sunscreen titanium dioxide replacement:Cosmetic-grade hydrate gains formulation share as ECHA restricts TiO2 nanoforms, with brands reformulating SPF products.
- Direct compounding partnerships:Pharmaceutical compounders in Ludwigshafen and Leverkusen now bypass distributors for API-excipient bundles, compressing channel margins.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Medical-grade hydrate qualification timelines extend 18-24 months as notified body capacity constrains implantable device material approvals.
- Precipitation facility reconfiguration:Legacy seeded precipitation lines require $15-25 million retrofit investments to meet pharmaceutical-grade particle distribution tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Hydrate Market |
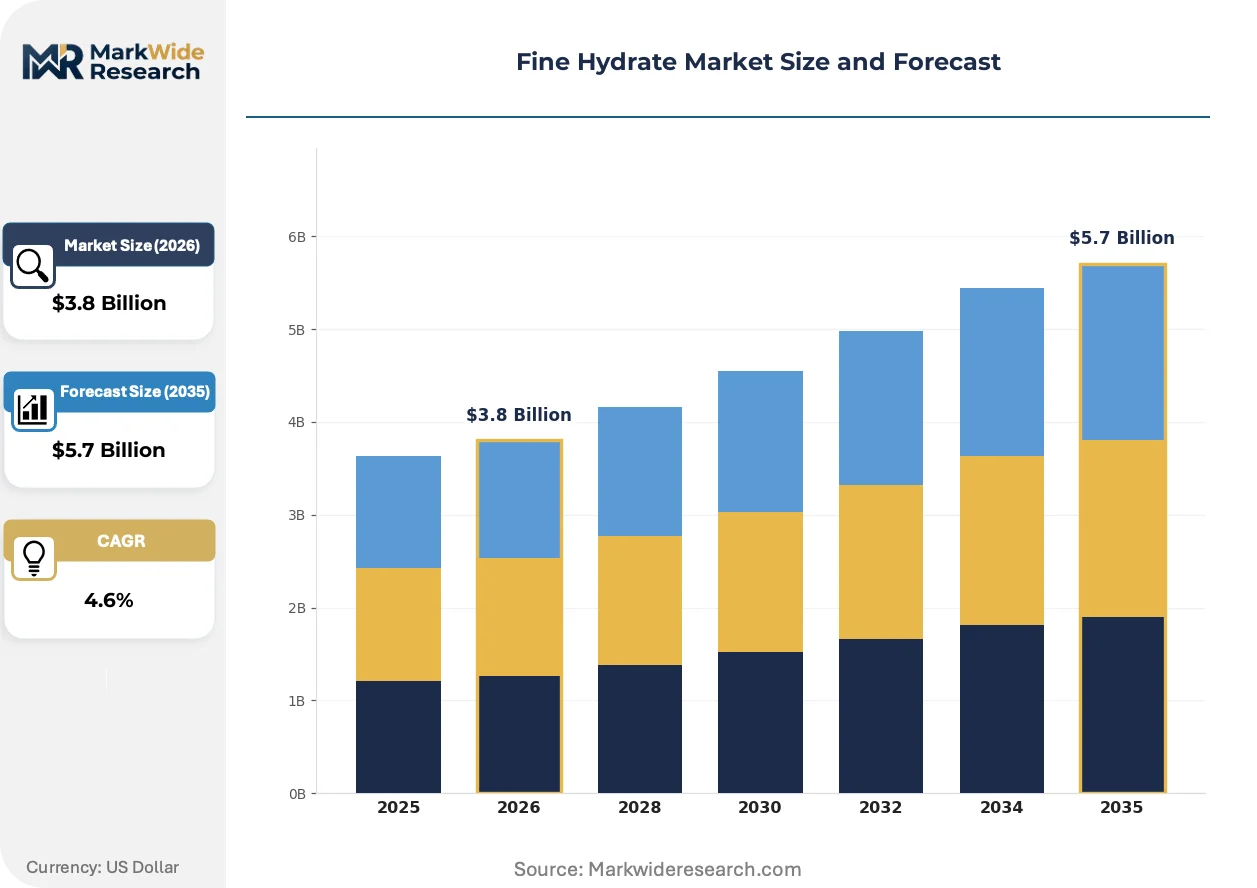
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food & Beverages, Pharmaceuticals, Personal Care, Paints & Coatings End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Paint Manufacturers Distribution Channel: Online Sales, Wholesale Suppliers, Direct Sales, Retail Outlets |
| Companies Covered | Nabaltec AG, Huber Engineered Materials, Hindalco Industries Limited, Sumitomo Chemical Co., Ltd., Aluminum Corporation of China Limited (CHALCO), Showa Denko K.K., Aluchem Inc., The R.J. Marshall Company, TOR Minerals International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Hydrate Market Emerging Trajectories
Seeded precipitation control systems are merging with real-time particle monitoring, collapsing the development cycle for application-specific hydrate grades. This convergence redistributes technical capability from commodity producers toward specialty chemical houses with process analytical technology expertise.
Continuous flow precipitation is hybridizing with in-line laser diffraction sensors to enable real-time particle size distribution control. Pharmaceutical compounders in Germany's specialty chemicals corridor adopt these systems to reduce batch-to-batch variability in tablet disintegrant applications. The technology is compressing qualification timelines for excipient supply agreements from 36 months toward 18 months.
REACH Article 33 disclosure requirements for nano-scale substances now extend to aluminum hydroxide particles below 100nm in consumer products. Cosmetic manufacturers reformulate mineral sunscreens to avoid nano-hydrate classification, shifting demand toward controlled-agglomeration grades. German and French brands lead this specification change, with personal care contract manufacturers in Ludwigshafen adapting precipitation protocols.
Compounders increasingly specify hydrate grades by performance outcome rather than particle size distribution alone. Pharmaceutical tablet manufacturers in Leverkusen now contract for disintegration time guarantees, transferring particle engineering risk to hydrate suppliers. This specification shift concentrates supply relationships among producers with in-house formulation testing capability.
Fine Hydrate Market Segmentation
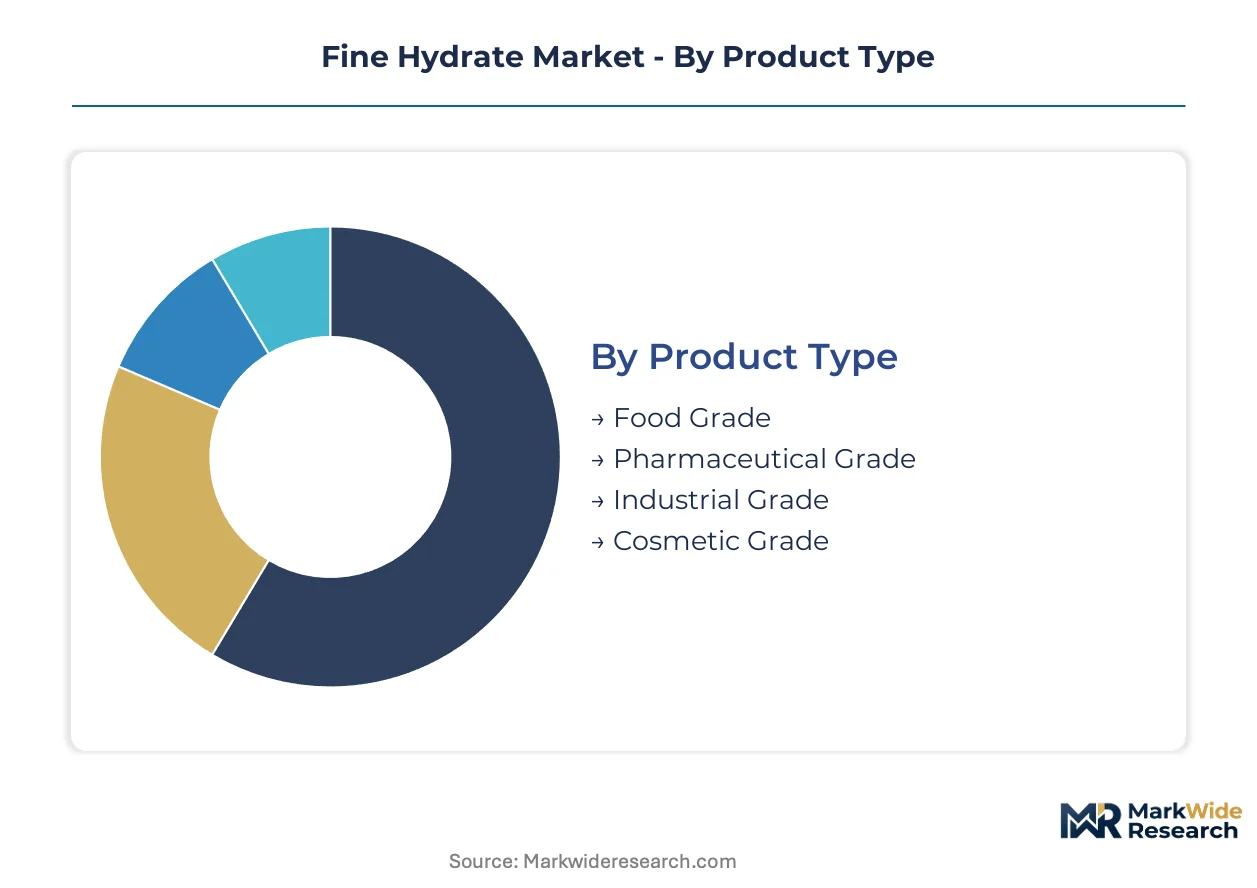
Segmentation in the fine hydrate market separates specification tiers that command radically different margin structures. Certification requirements and end-use performance demands create distinct commercial battlegrounds across each dimension.
Product Type:
Cost tier stratification dominates product classification, with purity thresholds and certification investments determining market positioning.
- Pharmaceutical Grade:Precipitated aluminum hydroxide meeting USP-NF monographs and ICH Q3D elemental impurity limits for tablet disintegrants and antacid APIs. CDSCO's import substitution push in India is concentrating demand localization efforts among domestic producers seeking excipient qualification.
- Industrial Grade:Flame-retardant filler for cable sheathing and rubber compounding with broader particle distribution tolerances. German construction code mandates for halogen-free public infrastructure are pulling volume toward Leverkusen and Ludwigshafen specialty chemicals clusters.
- Cosmetic Grade:Controlled-agglomeration hydrate for mineral sunscreen formulations avoiding ECHA nanoform classification. REACH Article 33 disclosure requirements are forcing reformulation away from sub-100nm variants.
- Food Grade:FCC-compliant aluminum hydroxide for food additive applications with specific residue limits. BIS certification requirements govern supply into Indian processed food manufacturing.
Industrial grade holds installed capacity. Pharmaceutical grade is rotating up the share rankings.
Application:
End-use performance specifications reshape how hydrate grades translate into commercial value across distinct formulation environments.
- Pharmaceuticals:Tablet disintegrant and antacid applications requiring excipient monograph compliance and biocompatibility documentation. EMA qualification pathways are accelerating generic drug manufacturer adoption across EU manufacturing sites.
- Personal Care:Mineral sunscreen and cosmetic filler applications where particle size distribution directly impacts SPF efficacy and skin feel. ECHA restrictions on titanium dioxide nanoforms are creating substitution demand for controlled-agglomeration hydrate grades.
- Food & Beverages:Food additive and processing aid applications governed by FCC and JECFA specifications. FSSAI registration requirements structure supply relationships into Indian food manufacturing.
- Paints & Coatings:Functional filler for corrosion resistance and flame-retardant properties in industrial coatings. Formulation shifts toward waterborne systems are modifying particle surface treatment requirements.
Pharmaceutical applications command premium positioning. Personal care is climbing the fastest as titanium dioxide substitution accelerates.
End User:
Customer type determines procurement complexity, with certification depth and volume scale creating divergent commercial relationships.
- Pharmaceutical Companies:Compounders and generic drug manufacturers requiring excipient qualification bundles with API sourcing. Direct procurement partnerships in Germany's specialty chemicals corridor are compressing traditional distributor margins.
- Cosmetic Brands:Mineral sunscreen and personal care formulators prioritizing REACH compliance and nanoform avoidance. Reformulation timelines tied to ECHA regulatory deadlines are concentrating specification authority with technical marketing teams.
- Food Manufacturers:Processed food and beverage producers sourcing FCC-compliant additives through qualified supplier programs. BIS and FSSAI dual certification requirements structure Indian supply relationships.
- Paint Manufacturers:Industrial and architectural coatings producers integrating hydrate as functional filler and flame retardant. Construction sector demand cycles in Germany and France influence volume contracting patterns.
Pharmaceutical companies anchor qualification-intensive supply. Cosmetic brands are gaining procurement sophistication fastest.
Distribution Channel:
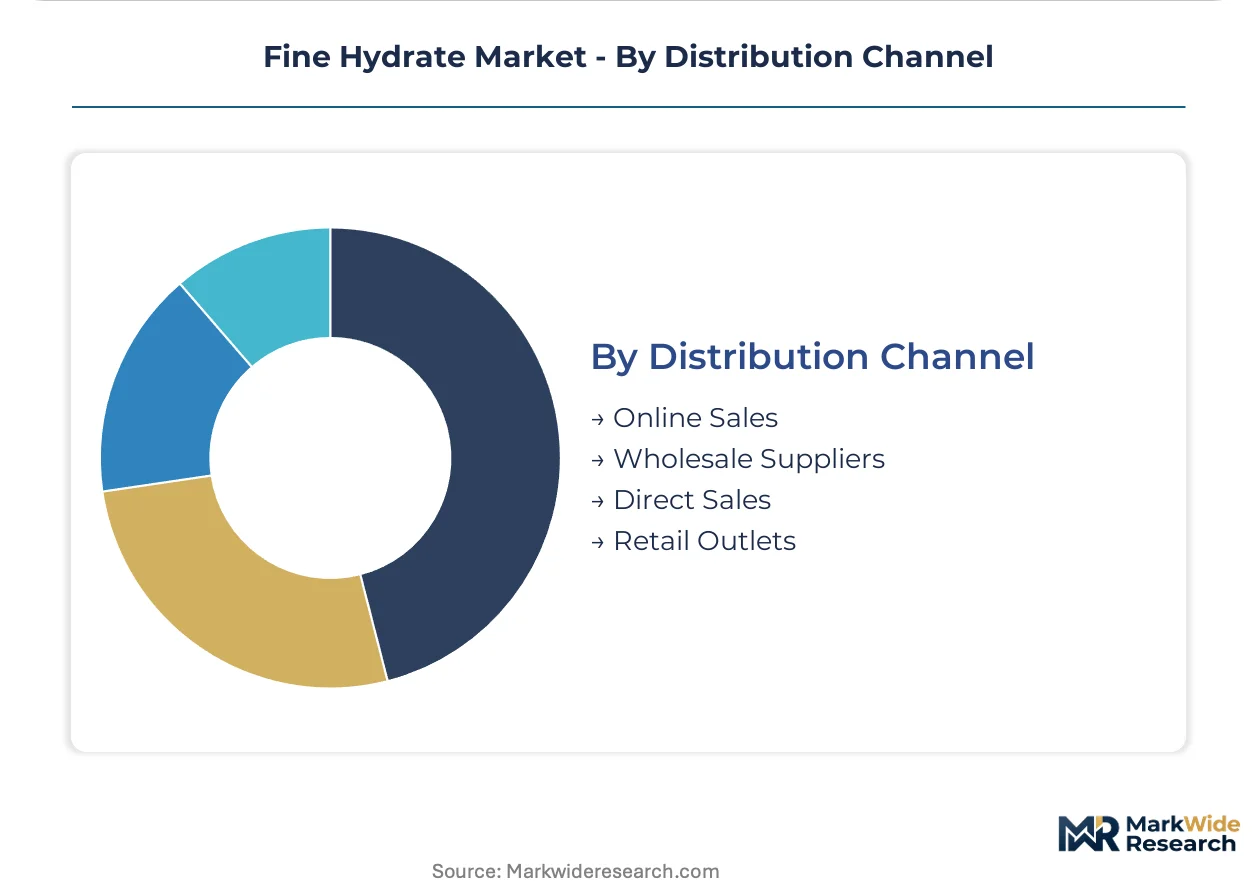
Channel structure reflects customer scale and specification complexity, with direct relationships displacing intermediaries in certified segments.
- Direct Sales:Long-term supply agreements between hydrate producers and pharmaceutical compounders or cosmetic manufacturers. Technical service integration and joint formulation development characterize these relationships.
- Wholesale Suppliers:Distributor networks serving industrial-grade demand in plastics, rubber, and coatings compounding. Volume aggregation and logistics efficiency sustain channel relevance in specification-tolerant segments.
- Online Sales:Digital procurement platforms for standardized industrial grades and smaller-volume specialty orders. E-procurement adoption varies significantly by geography and customer digital maturity.
- Retail Outlets:Limited presence for small-scale laboratory and research quantities, primarily in reagent-grade hydrate variants.
Direct sales capture margin in qualified segments. Wholesale suppliers defend position in industrial volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance anchors European demand for certified fine hydrate grades, while pharmaceutical excipient localization reshapes procurement patterns across Asia. Construction code mandates and mineral sunscreen reformulation are redistributing volume toward specialized precipitation clusters.
Germany
Halogen-free construction mandates in public infrastructure pull industrial-grade hydrate into cable sheathing applications. ECHA nanoform disclosure requirements under REACH Article 33 constrain cosmetic-grade supply. The Leverkusen-Ludwigshafen specialty chemicals corridor concentrates precipitation capacity for pharmaceutical and personal care segments.
United States
Flame-retardant filler demand from wire and cable compounding sustains industrial-grade volume flows. EPA effluent oversight of aluminum processing constrains greenfield precipitation capacity. Huber Engineered Materials anchors North American supply through specialized facilities serving plastics and rubber markets.
India
CDSCO import substitution incentives accelerate pharmaceutical-grade hydrate localization for tablet manufacturing. BIS certification requirements structure food-grade supply into processed food manufacturing. Hindalco Industries leverages integrated alumina feedstock to compete in domestic excipient qualification.
Japan
Ultra-high-purity hydrate demand from electronic applications drives seeded precipitation refinement. METI industrial standards govern particle size distribution specifications for specialty chemical supply. Sumitomo Chemical occupies a position serving semiconductor and advanced materials markets.
China
Alumina refining capacity concentration supports industrial-grade hydrate exports for flame-retardant applications. GB standards and dual carbon goals modify Bayer process facility permitting. Aluminum Corporation of China Limited represents state-backed vertical integration from bauxite through hydrate derivatives.
Fine Hydrate Market Vendor Landscape
Integrated aluminum majors and specialty chemical houses split the market between feedstock security and formulation expertise. Tiered competitive positioning separates commodity-scale precipitators from certified-grade specialists. Two archetypes dominate: smelter-integrated hydrate producers leveraging captive Bayer liquor supply, and independent specialty chemical houses with process analytical technology capabilities. Capacity reconfiguration and direct compounding partnerships represent the dominant competitive moves reshaping channel relationships.
Among German-anchored specialists, Nabaltec AG exemplifies the flame-retardant heritage archetype sustaining technical credibility across European industrial markets. At the Asia-Pacific integrated end, Hindalco Industries Limited and Sumitomo Chemical Co., Ltd. represent contrasting models—Indian feedstock integration versus Japanese ultra-high-purity specialization—each occupying distinct positions in the certification-tiered supply structure. These three names anchor the competitive map without exhausting its diversity.
| Leading Market Players |
|---|
| Nabaltec AG |
| Huber Engineered Materials |
| Hindalco Industries Limited |
| Sumitomo Chemical Co., Ltd. |
| Aluminum Corporation of China Limited (CHALCO) |
| Showa Denko K.K. |
| Aluchem Inc. |
| The R.J. Marshall Company |
| TOR Minerals International |
| Others |
Supply Flow & Price Mechanics
The Leverkusen-Ludwigshafen specialty chemicals corridor concentrates pharmaceutical-grade precipitation capacity, translating upstream certification investments into downstream pricing power for excipient suppliers serving EMA-qualified compounders. REACH compliance costs and Bayer liquor feedstock volatility propagate through contract structures, compressing margins for uncertified producers while consolidating premium capture among qualified specialists.
Pricing Analysis
Price spreads between German pharmaceutical-grade hydrate and Chinese industrial-grade exports exceed threefold, reflecting certification tier premiums and EMA qualification barriers. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates USP-NF compliant supply from FCC-grade and uncertified flame-retardant fillers. Cost compression in industrial-grade cable sheathing compounds intensifies as magnesium hydroxide substitutes capture polyolefin applications. Pharmaceutical compounders in Leverkusen exhibit lowest price sensitivity due to excipient qualification switching costs, while plastics compounders in Asia-Pacific volume markets drive hardest bargain negotiations.
Supply Chain Analysis
Bayer liquor supply concentrates among integrated aluminum smelters in Germany, China, and India, tethering hydrate producers to captive alumina refining economics and bauxite cost volatility. Precipitation capacity draws from bauxite mining, caustic soda refining, and seeded precipitation technology licensing. Single-source vulnerability runs through Leverkusen-Ludwigshafen pharmaceutical-grade clusters where EMA-qualified precipitation lines lack geographic redundancy. Distribution runs through direct sales agreements for certified grades and wholesale distributor networks for industrial volume flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where EMA qualification and REACH nanoform compliance create switching-cost moats that protect incumbent margin structures from commodity erosion.
For Market Incumbents: Build certification moats by deepening EMA excipient qualification bundles and securing direct compounding partnerships in Ludwigshafen and Leverkusen. Expand backward integration into Bayer liquor supply through alumina refining joint ventures in Germany or India to offset feedstock volatility. Magnesium hydroxide substitution in polyolefin cable applications threatens industrial-grade volume; counter by advancing halogen-free formulation technical service capabilities. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical excipient localization wave by securing CDSCO qualification ahead of European supply displacement. Target cosmetic-grade controlled-agglomeration hydrate for mineral sunscreen reformulation as ECHA TiO2 restrictions accelerate. Go-to-market through personal care contract manufacturers in Ludwigshafen adapting precipitation protocols for nanoform avoidance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical houses with process analytical technology capabilities over smelter-integrated commodity producers. Long-term viability rests on qualification-intensive segments where regulatory barriers compound. Acquisition target archetype: independent precipitation specialists with in-house laser diffraction control systems and existing pharmaceutical customer relationships. Watch ECHA nanoform guidance evolution as inflection signal for cosmetic-grade specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Excipient Qualification Bundle | Compresses pharmaceutical compounder procurement cycles from 36 toward 18 months in Leverkusen. |
| Backward Integration into Bayer Liquor | Secures alumina feedstock margin control against Hindalco and CHALCO captive pricing power. |
| Process Analytical Technology Deployment | Enables real-time particle distribution control for tablet disintegrant performance guarantees. |
| Direct Compounding Partnership | Bypasses distributor margins in Germany's specialty chemicals corridor for API-excipient bundles. |
| Controlled-Agglomeration Grade Development | Captures mineral sunscreen reformulation demand as ECHA restricts titanium dioxide nanoforms. |
Methodological Framework
Desk research of customs/trade data, SEC filings, ECHA registration databases, and CDSCO excipient guidelines preceded structured interviews with pharmaceutical compounders, cosmetic formulators, precipitation plant managers, and distribution channel partners. Primary fieldwork with Bayer process engineers and EMA regulatory consultants combined with secondary validation through Cefic chemical industry reports and BIS certification records. Bottom-up volume modeling triangulated against top-down market sizing across grade tier and application segments.
Assumptions held REACH nanoform thresholds, EMA monograph standards, and construction code mandates fixed while varying alumina feedstock cost trajectories and pharmaceutical localization incentives across the projection horizon. Segmentation modeling spanned product grade, end-use application, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of historical precipitation capacity expansion correlated with downstream demand elasticity in flame-retardant and excipient applications.
Macroeconomic conditions sit as an overlay; deviation in construction sector investment cycles, bauxite pricing volatility, or pharmaceutical R&D expenditure would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and qualification timeline stability. Cross-checking against ECHA registration database trends and CDSCO import substitution policy announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Precipitated Fine Hydrate Market