
 Japan Caustic Potash Market | 2026-2036
Japan Caustic Potash Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Caustic Potash Market Intelligence
Aftermarket technical service revenue is rewriting profitability expectations for caustic potash suppliers serving Japan's precision industries. UNID Corp. leverages its captive membrane-cell capacity to secure long-term pharmaceutical contracts. AGC Inc. anchors its position through backward integration into chlor-alkali feedstock production. Olin Corporation competes by sustaining dedicated export logistics for Asian specialty chemical buyers.
Caustic potash, chemically potassium hydroxide with formula KOH, contains approximately 90 percent purity in industrial grades and functions as a strong base in pH regulation, saponification, and potassium salt synthesis. The product type dimension shows flake and pellet forms commanding premium positioning where free-flowing handling properties reduce downstream processing losses. Within end use industry segmentation, pharmaceutical and food processing applications attract tightening purity audits while fertilizer demand follows broader agricultural potassium cycles.
METI enforces industrial chemical facility standards under the High Pressure Gas Safety Act, while JIS K 8575 governs reagent-grade potassium hydroxide specifications for laboratory and pharmaceutical use. Compliance with these frameworks shapes capital allocation toward membrane-cell upgrades and quality certification investments. Stakeholders must weigh the trade-off between scaling liquid bulk delivery infrastructure versus maintaining higher-margin packaged specialty grades.
Market Dynamics
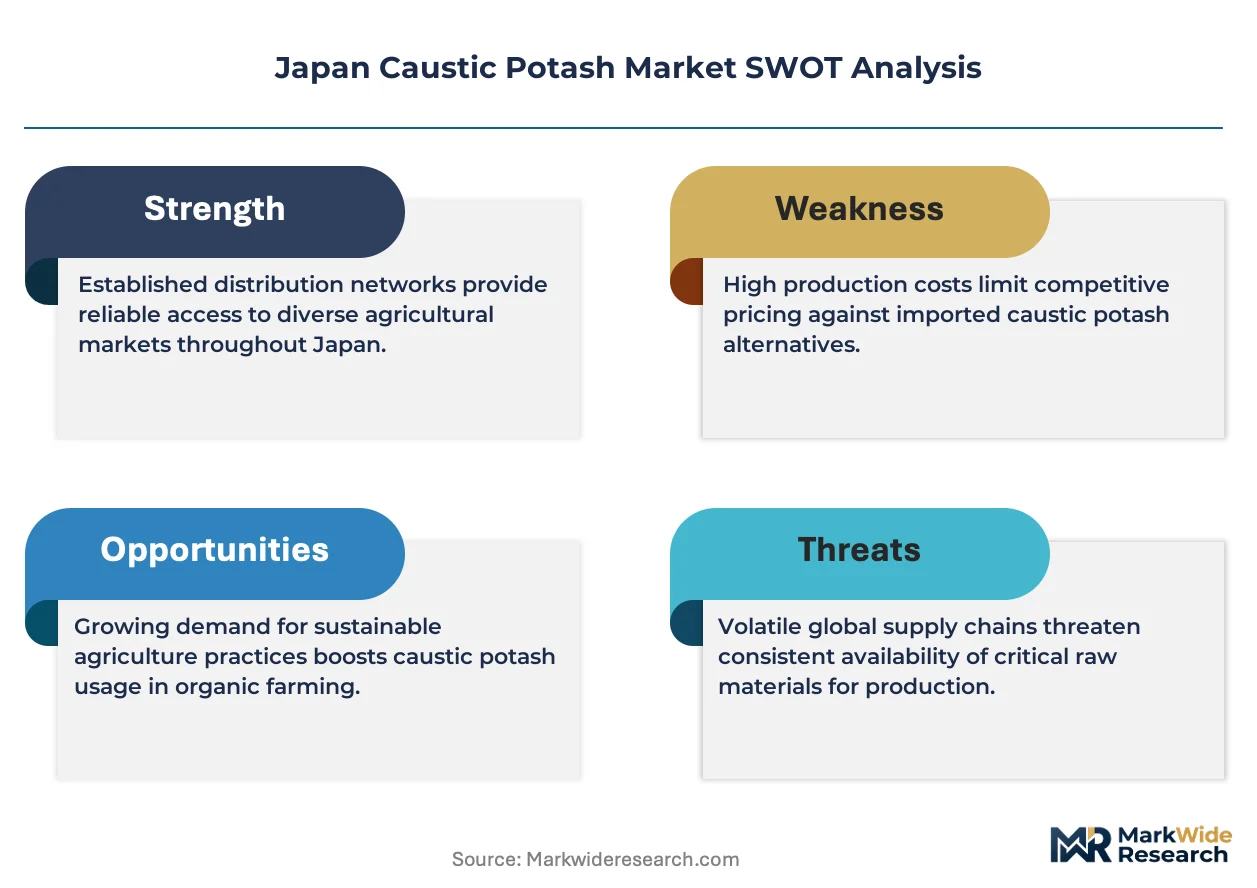
Pharmaceutical-grade purity mandates from METI are compressing supplier margins while consolidating procurement toward membrane-cell producers with captive certification capabilities.
Growth Catalysts
- Pharmaceutical-grade demand:METI guidance on reagent specifications is tightening purity thresholds for potassium hydroxide used in active pharmaceutical ingredient synthesis.
- Membrane-cell technology:Chlor-alkali producers deploying membrane electrolysis achieve lower mercury contamination risk and higher KOH consistency for food processing applications.
- Kanto corridor concentration:Integrated chemical complexes in Chiba and Kanagawa prefectures generate sustained bulk demand for flake and liquid caustic potash.
Market Restraints
- Energy cost volatility:Electrolytic production of caustic potash exposes margins to Japanese industrial electricity tariffs and LNG import pricing.
- Import dependency for potassium chloride:Domestic chlor-alkali producers rely on Canadian and Jordanian KCl feedstock, creating currency and geopolitical exposure.
- Mercury-cell phase-out legacy:Remaining diaphragm-cell capacity faces accelerated depreciation and environmental liability under High Pressure Gas Safety Act amendments.
Strategic Opportunities
- Osaka-Kobe pharmaceutical cluster:Underpenetrated specialty chemical demand in western Japan offers packaged-grade expansion beyond Kanto bulk supply.
- Battery electrolyte applications:Potassium hydroxide purity specifications for next-generation energy storage converge with existing pharmaceutical certification investments.
- JIS K 8575 laboratory reagent tier:Premium positioning for analytical-grade KOH creates margin expansion independent of commodity alkali cycles.
Industry Challenges
- Membrane-cell engineering talent scarcity:Specialized electrolyzer maintenance and ion-exchange membrane replacement skills concentrate at legacy chlor-alkali operators.
- Multi-grade certification timelines:Simultaneous compliance with JIS reagent standards, food additive specifications, and pharmaceutical GMP extends qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Caustic Potash Market |
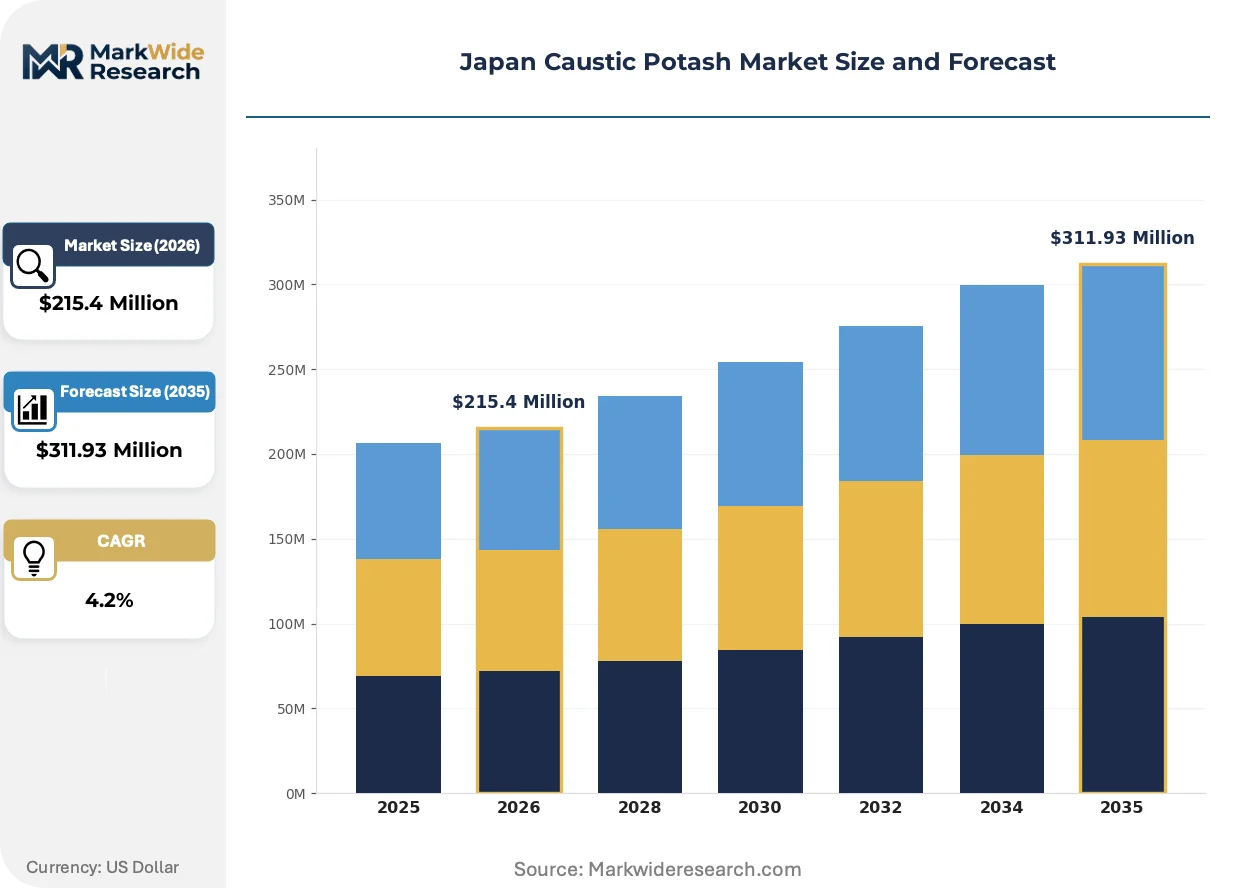
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $311.93 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Pellets, Liquid, Powder End Use Industry: Fertilizers, Pharmaceuticals, Food Processing, Cosmetics Manufacturing Stage: Raw Material, Intermediate, Finished Goods, Specialty Chemicals Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | UNID Corp., AGC Inc., Olin Corporation, Occidental Petroleum Corporation, Tessenderlo Group, ASHTA Chemicals, Evonik Industries, ICL Fertilizers, Westlake Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Caustic Potash Market Strategic Shifts & Innovations
Digital quality assurance and membrane-cell automation are compressing batch-to-batch variation while METI regulatory updates accelerate grade stratification across end-use verticals.
Membrane electrolyzer control systems is virtualizing manual process intervention in caustic potash production. Pharmaceutical and food-grade buyers now mandate automated pH and conductivity monitoring with real-time batch certification. This technology is virtualizing traditional laboratory quality control staffing models and compressing supplier qualification cycles.
METI's 2023 amendments to the High Pressure Gas Safety Act imposed stricter mercury emissions thresholds on remaining diaphragm-cell installations. Chlor-alkali producers face accelerated capital allocation toward membrane conversion or facility closure. Pharmaceutical-grade KOH supply is consolidating toward operators with completed membrane transitions and JIS K 8575 certification.
Technical service unbundling from commodity supply contracts is altering buyer-supplier relationships in specialty chemical procurement. Precision manufacturers now contract separately for on-site pH system calibration and emergency alkali logistics. This pattern is most pronounced among Osaka-based pharmaceutical formulators with just-in-time potassium salt synthesis requirements.
Japan Caustic Potash Market Segmentation
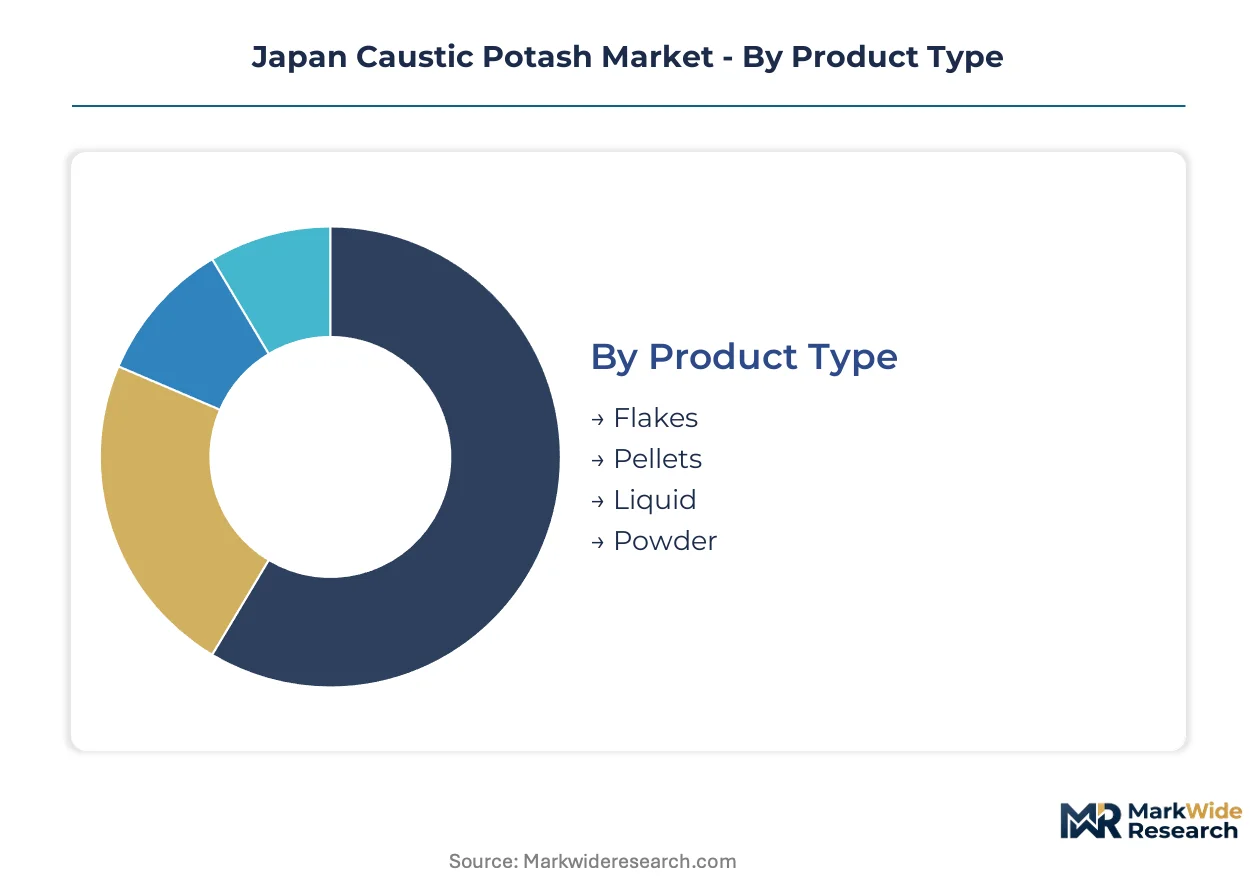
Caustic potash segmentation in Japan reflects divergent purity requirements across end-use verticals, with pharmaceutical and food-grade specifications commanding certification premiums while bulk industrial grades compete on logistics efficiency. Membrane-cell producers leverage grade stratification to capture margin pools unavailable to commodity alkali suppliers.
Product Type:
Mature industrial formats dominate volume flows through the Kanto corridor, while emerging specialty configurations target precision handling requirements in western Japan's pharmaceutical cluster.
- Flakes:Thin, brittle sheets with approximately 90 percent KOH purity and low dust generation profile. Chiba and Kanagawa prefectures absorb the majority of flake volumes for integrated chemical complex feedstock, driven by consistent bulk handling infrastructure and established membrane-cell supply contracts.
- Pellets:Compressed cylindrical forms engineered for free-flowing properties and reduced caking during storage. Osaka-Kobe pharmaceutical formulators specify pellet grades for automated potassium salt synthesis systems, where metering precision directly impacts active pharmaceutical ingredient yield consistency.
- Liquid:Aqueous solutions at varying concentrations for direct pH adjustment applications.
- Powder:Fine particulate form with high surface area for rapid dissolution requirements.
Flakes handle the majority of throughput; pellets are expanding most quickly on share as pharmaceutical automation spreads beyond legacy Kanto facilities.
End Use Industry:
Application-driven cost tiers separate commodity fertilizer absorption from premium-grade pharmaceutical and food processing certification tracks.
- Pharmaceuticals:Reagent-grade KOH meeting JIS K 8575 specifications for active pharmaceutical ingredient synthesis and pH control in sterile manufacturing environments. METI guidance on mercury contamination thresholds has consolidated procurement toward membrane-cell producers with completed JIS certification, compressing qualified supplier lists.
- Food Processing:Food additive-grade potassium hydroxide for pH regulation in cocoa processing, olive curing, and soft drink formulation. PMDA and METI joint oversight of food chemical specifications creates multi-agency compliance burden that favors established chlor-alkali operators with dedicated quality systems.
- Fertilizers:Agricultural potassium salt production and soil amendment applications.
- Cosmetics:Personal care formulation for pH balancing in skincare and haircare products.
Pharmaceuticals command the steepest margin tier; food processing is climbing the fastest on certification investment returns.
Manufacturing Stage:
Customer type segmentation distinguishes between integrated chemical producers seeking raw material feedstock and specialty formulators requiring validated intermediate specifications.
- Raw Material:Bulk KOH for captive consumption in downstream chemical synthesis.
- Intermediate:Partially processed grades for potassium carbonate and potassium phosphate production.
- Finished Goods:Packaged reagents and laboratory chemicals for direct end-user consumption.
- Specialty Chemicals:Ultra-high purity grades with custom certification for pharmaceutical and electronics applications.
Raw material and intermediate stages absorb the bulk of electrolytic output; specialty chemicals is gaining share fastest on purity premium capture.
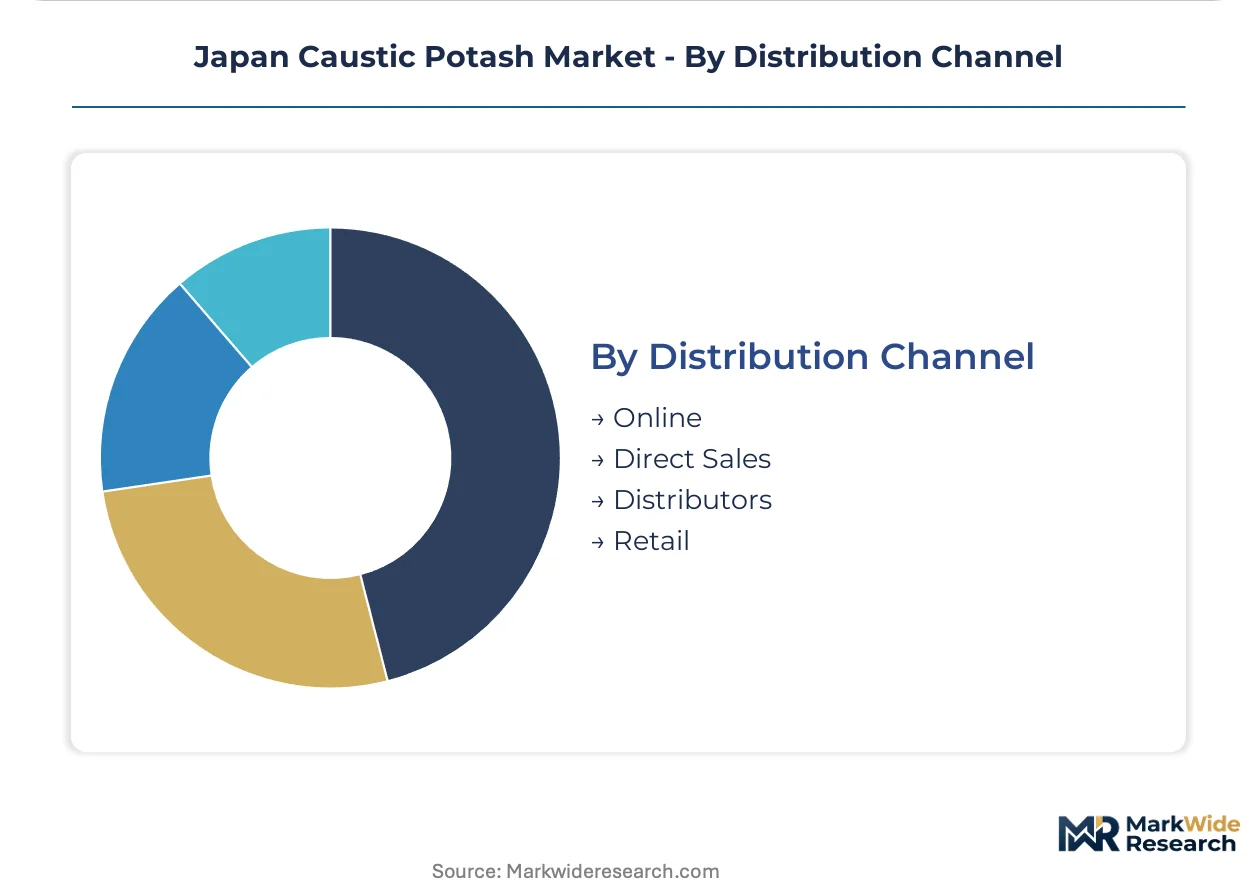
Distribution Channel:
Supply concentration in membrane-cell production clusters shapes logistics configuration, with direct sales dominating high-volume flows and distributor networks covering fragmented specialty demand.
- Direct Sales:Long-term supply agreements between chlor-alkali producers and integrated chemical complexes. Chiba and Kanagawa buyers lock in liquid bulk delivery through dedicated pipeline and tanker infrastructure, minimizing handling losses and ensuring just-in-time alkali availability for continuous process operations.
- Distributors:Intermediary networks managing packaged-grade logistics for small and mid-sized formulators. Osaka-based pharmaceutical clusters rely on distributor-stocked pellet and flake inventories to buffer against membrane-cell supply concentration risk and enable rapid grade switching during formulation trials.
- Online:Digital procurement platforms for standardized laboratory reagent orders.
- Retail:Consumer-facing channels for small-scale industrial and educational laboratory supply.
Direct sales channel handles the majority of tonnage; distributor networks are expanding fastest on specialty grade fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto prefectures absorb bulk industrial volumes through pipeline-fed chemical complexes, while Kansai pharmaceutical clusters drive premium-grade pellet demand for automated synthesis systems.
Kanto/Tokyo
Chiba and Kanagawa prefectures host integrated chlor-alkali complexes supplying membrane-cell KOH to downstream chemical manufacturers. METI's High Pressure Gas Safety Act enforcement accelerates mercury-cell phase-outs in coastal industrial zones. The Keiyo Rinkai industrial corridor maintains dedicated liquid bulk delivery infrastructure for continuous process operations.
Kansai/Osaka
Osaka-Kobe pharmaceutical formulators specify pellet-grade potassium hydroxide for active pharmaceutical ingredient synthesis with just-in-time logistics requirements. PMDA oversight of sterile manufacturing environments tightens mercury contamination thresholds. The Hanshin industrial belt drives distributor network expansion for packaged specialty grades.
Chubu/Nagoya
Nagoya-based automotive and electronics chemical suppliers consume intermediate-grade KOH for potassium salt production in battery and plating applications. METI industrial chemical facility standards govern membrane-cell certification timelines. The Ise Bay manufacturing zone concentrates procurement through long-term direct supply agreements.
Kyushu
Fukuoka and Kitakyushu chemical processors absorb flake caustic potash for fertilizer and agricultural potassium salt production. The national government's regional industrial revitalization programs support chlor-alkali capacity modernization. Northern Kyushu industrial ports handle imported potassium chloride feedstock from Jordanian and Canadian sources.
Hokkaido
Sapporo-area food processors utilize food additive-grade potassium hydroxide for regional dairy and beverage pH regulation. JIS K 8575 laboratory reagent specifications govern quality certification for smaller-scale formulators. The Ishikari Bay industrial zone maintains limited but specialized packaged-grade distribution infrastructure.
Japan Caustic Potash Market Key Industry Players
Capability concentration sits with membrane-cell operators possessing JIS certification infrastructure; scale advantage sits with diversified chlor-alkali producers leveraging captive feedstock integration. Japanese pharmaceutical and food-grade procurement consolidates toward qualified suppliers with completed mercury-cell transitions. Three archetypes dominate: integrated chemical conglomerates with backward chlor-alkali control, specialty alkali pure-plays, and multinational suppliers with regional export logistics. Competitive moves center on membrane conversion capital deployment and technical service unbundling from commodity contracts.
Within the integrated chemical tier, UNID Corp. and AGC Inc. occupy positions shaped by captive membrane-cell capacity and domestic production infrastructure. Olin Corporation exemplifies the multinational logistics archetype, leveraging dedicated export capabilities for Asian specialty chemical buyers. These three operators anchor procurement consolidation as METI purity mandates compress qualified supplier lists toward certified membrane-cell producers.
| Leading Market Players |
|---|
| UNID Corp. |
| AGC Inc. |
| Olin Corporation |
| Occidental Petroleum Corporation |
| Tessenderlo Group |
| ASHTA Chemicals |
| Evonik Industries |
| ICL Fertilizers |
| Westlake Chemical Corporation |
| Others |
Cost & Logistics Intelligence
The Keiyo Rinkai industrial corridor's liquid bulk pipeline infrastructure compresses logistics costs for membrane-cell producers while amplifying price differentiation between pharmaceutical-grade pellet premiums and commodity flake benchmarks. Supply concentration in Chiba and Kanagawa prefectures grants certified producers pricing power over downstream formulators lacking alternative qualified sources.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between chlor-alkali producers and integrated chemical complexes, with spot transactions limited to distributor-stocked packaged grades. Price differentiation rests on JIS K 8575 certification tier and mercury contamination thresholds rather than volume scale alone. Cost compression in pharmaceutical-grade supply is intensifying because membrane-cell conversion capital requirements accelerate depreciation schedules. Fertilizer and agricultural potassium salt buyers exhibit highest price sensitivity, while sterile pharmaceutical formulators absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Currency exposure between Canadian and Jordanian potassium chloride suppliers and yen-denominated chlor-alkali producers dominates supply chain risk assessment. Geographic supply concentration centers on domestic membrane-cell capacity in Chiba and Kanagawa, with residual diaphragm-cell output in northern Kyushu facing accelerated phase-out. Raw material dependencies draw from Saskatchewan potash mines and Dead Sea extraction operations. Single-source vulnerability concentrates in ion-exchange membrane supply from Japanese and Belgian specialty chemical producers. Distribution runs through dedicated pipeline infrastructure for liquid bulk and distributor networks for packaged specialty grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across purity tiers and regional demand clusters creates multiple niche entry points as METI guidance splinters procurement requirements beyond one-size-fits-all supply relationships.
For Market Incumbents: Harden membrane-cell certification moats through simultaneous JIS K 8575 reagent-grade and food additive qualification investments before remaining diaphragm-cell competitors complete conversions. Prioritize captive potassium chloride feedstock agreements with Canadian suppliers to hedge currency volatility threatening margin stability. Channel control over Osaka-Kobe distributor networks defends against packaged-grade entrants targeting pharmaceutical automation demand. For New Entrants and Emerging Players: Build out technical service capabilities unbundled from commodity supply contracts, targeting Osaka-based pharmaceutical formulators with just-in-time pH system calibration and emergency alkali logistics. The underpenetrated laboratory reagent tier offers lowest certification barriers relative to pharmaceutical GMP requirements. A go-to-market angle emphasizing automated batch monitoring compliance accelerates supplier qualification cycles against legacy chlor-alkali operators. For Investors and Strategic Acquirers: Specialty alkali pure-plays with completed membrane transitions and established PMDA food additive registrations represent the most defensible acquisition profile. Long-term viability across the analysis window hinges on consolidation economics as mercury-cell phase-outs eliminate sub-scale competitors. The signal to watch is METI enforcement intensity on High Pressure Gas Safety Act amendments accelerating forced exits.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Conversion | Completed conversions secure METI compliance and pharmaceutical procurement eligibility. |
| Backward Integration into KCl Feedstock | Captive supply agreements with Canadian producers hedge yen-dollar volatility exposure. |
| JIS K 8575 Certification Investment | Reagent-grade qualification opens laboratory and analytical chemistry revenue streams. |
| Technical Service Unbundling | Separate pH system calibration contracts capture margin beyond commodity alkali sales. |
| Osaka-Kobe Distribution Expansion | Distributor network penetration addresses pharmaceutical automation demand in western Japan. |
Research Approach
Desk research of METI regulatory filings, JIS standard documentation, and chlor-alkali industry association reports preceded structured interviews with membrane-cell plant managers, pharmaceutical procurement leads, and distributor channel partners. Secondary validation drew from customs trade data, SEC filings of multinational chemical producers, and High Pressure Gas Safety Act amendment records. Bottom-up capacity modeling and top-down demand segmentation were triangulated against operating metrics disclosed in technical industry presentations.
Assumptions around membrane-cell conversion timelines, potassium chloride import pricing bands, and METI enforcement intensity were held fixed across baseline scenarios while pharmaceutical demand elasticity and currency volatility were stress-tested in sensitivity runs. Segmentation dimensions modeled include product form, end-use industry purity tier, manufacturing stage, and regional demand cluster. CAGRs were derived from electrolytic capacity expansion schedules and downstream consumption intensity ratios.
Stress conditions across yen-Canadian dollar exchange rates, LNG import pricing for electrolytic energy costs, and mercury-cell phase-out acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory compliance timelines and feedstock sourcing stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Zinc Gluconate Granules Market