
 Sodium Carbonate Market | 2026-2036
Sodium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Carbonate Market Analysis
Modular supply arrangements for dense soda ash in bulk railcar increments is recalibrating procurement patterns among glass manufacturers seeking inventory flexibility. Tata Chemicals leverages its integrated soda ash-bicarbonate complex in Wyoming to sustain cost-advantaged supply to North American flat glass producers. Ciner Group anchors the global export trade through its massive Wyoming trona reserves, while WE Soda competes on European proximity and lower-carbon logistics to Mediterranean detergent makers.
Sodium carbonate, also known as soda ash, is an anhydrous sodium salt of carbonic acid with the chemical formula Na₂CO₃ and a melting point of 851°C, produced commercially through the Solvay process or mined as trona ore before refining. The material functions primarily as an alkaline flux in glass melting, a pH buffer in chemical synthesis, and a water softener in detergent formulations. Dense soda ash dominates volume flows into glass manufacturing, where its particle size and bulk density reduce dusting and improve furnace charging efficiency, while light soda ash commands premium positioning in detergent and specialty chemical applications requiring rapid dissolution. Sodium bicarbonate derived from soda ash processing represents the fastest-growing product line, propelled by expanding food processing and pharmaceutical buffering demand.
EPA emissions standards for hazardous air pollutants from mineral processing facilities constrain US trona-based production methods, while REACH registration requirements in Europe mandate detailed chemical safety dossiers for soda ash imports and downstream formulations. China's MEE enforces increasingly stringent carbon intensity benchmarks on Solvay process plants, pressuring older coal-sourced operations toward fuel switching or closure. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional energy price divergences that will reshape competitive positioning between natural trona and synthetic production routes.
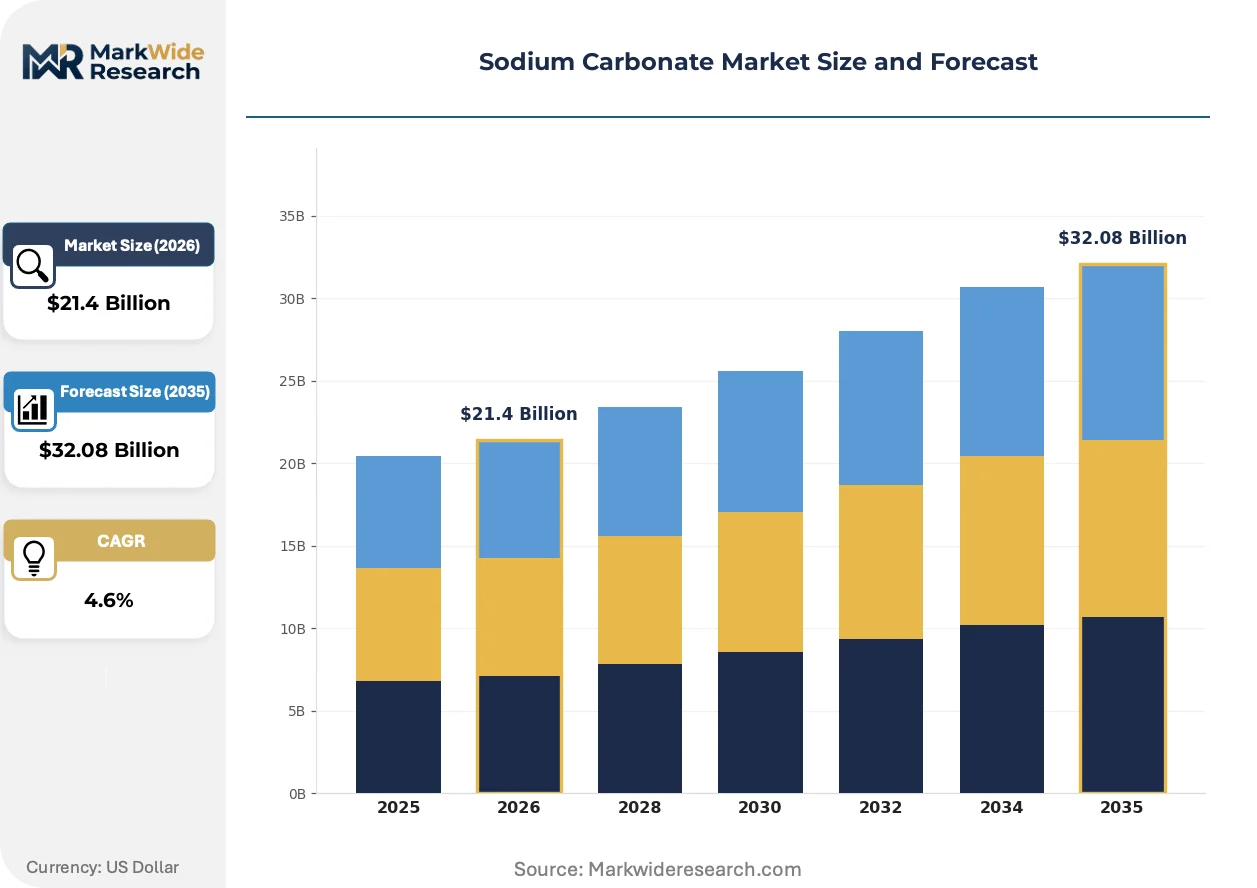
Market Dynamics
China's MEE carbon intensity benchmarks are forcing Solvay process plants toward fuel switching or closure, compressing synthetic supply capacity while natural trona operations in Wyoming consolidate export positioning.
Growth Catalysts
- Solar glass expansion:Photovoltaic panel manufacturers in India and China are scaling tempered glass output under PLI scheme support and dual carbon goals, pulling dense soda ash volumes.
- REACH registration tailwinds:ECHA chemical safety dossier requirements for soda ash imports are favoring established European suppliers with compliant downstream formulations.
- Trona mining efficiency:Wyoming's massive natural ore reserves enable lower-carbon dense soda ash production compared to coal-sourced Solvay synthesis.
Market Restraints
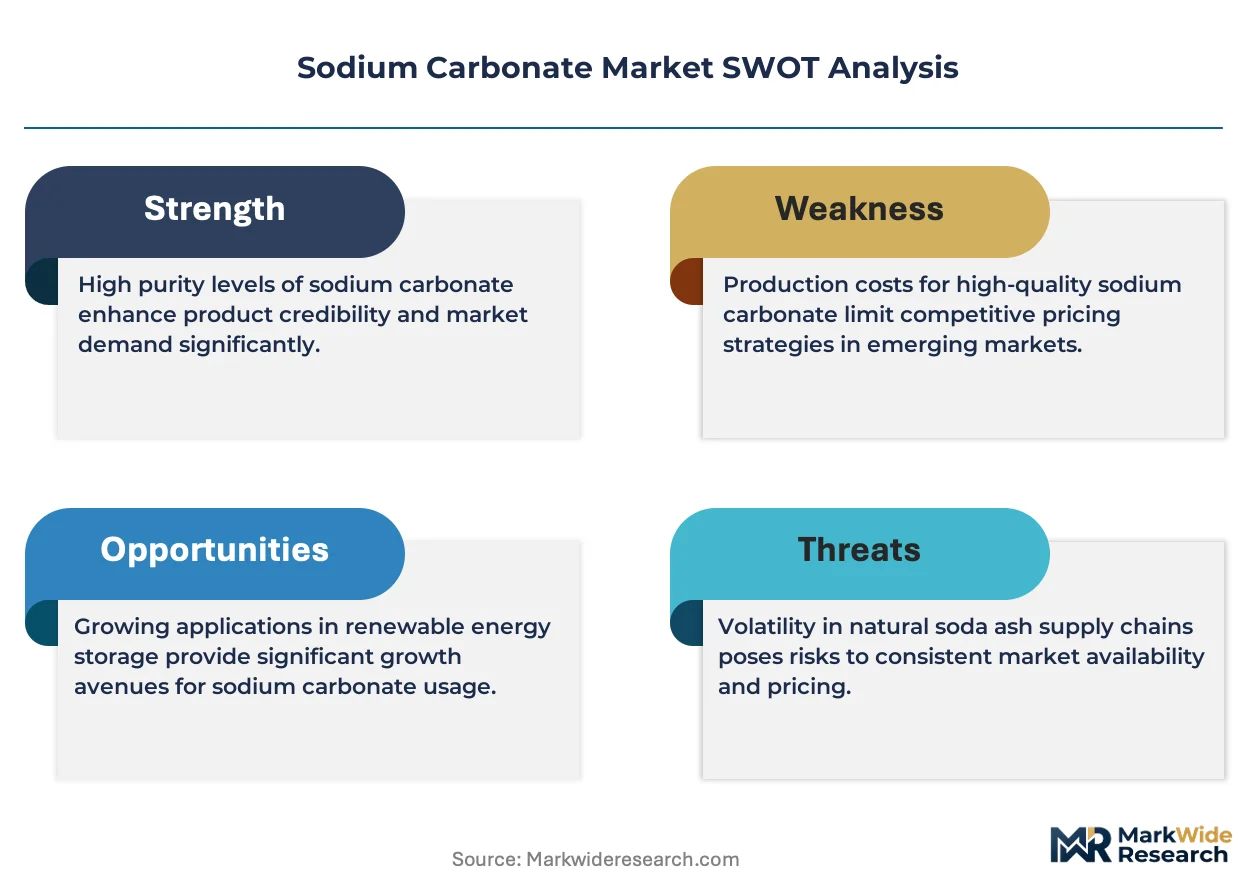
- Energy cost volatility:Natural gas and coal price swings directly compress margins for synthetic production routes dependent on thermal process inputs.
- Supply concentration risk:Wyoming trona reserves dominate global natural soda ash exports, creating geographic single-point vulnerability for dense grade availability.
- Caustic soda substitution:Some detergent formulators are shifting toward sodium hydroxide where rapid alkalinity and lower freight costs outweigh handling complexity.
Strategic Opportunities
- India manufacturing localization:PLI scheme incentives for domestic glass and chemical production are accelerating import substitution opportunities for dense soda ash supply.
- Sodium bicarbonate food processing:Pharmaceutical buffering and bakery leavening applications are outpacing traditional soda ash growth trajectories.
- Railcar modular contracting:Glass manufacturers are adopting flexible bulk procurement structures to manage furnace inventory without fixed-volume commitments.
Industry Challenges
- Process engineering talent scarcity:Solvay plant optimization and trona refining operations require specialized chemical engineering expertise that is aging out of the workforce.
- EPA hazardous air pollutant compliance:US mineral processing facilities face capital-intensive emissions control upgrades under tightening EPA standards for HAP releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Carbonate Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $32.08 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Soda Ash, Dense Soda Ash, Sodium Bicarbonate, Soda Ash Solvay Process End Use Industry: Glass Manufacturing, Detergents, Chemical Processing, Food Processing Application: Buffering Agent, pH Regulator, Catalyst, Glass Production Sales Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Tata Chemicals, DCW Ltd., WE Soda, Xinjiang Zhongtai Chemical, NIRMA, Solvay, Ciner Group, SINOPEC, Şişecam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Carbonate Market Emerging Trajectories
Electrification of thermal processes and carbon capture retrofits are reshaping production economics, while procurement digitization and sustainability-linked contracting are restructuring buyer-supplier relationships across the value chain.
Electrolytic sodium carbonate synthesis is electrifying carbon-intensive production pathways by replacing coal-fired thermal calcination with grid-powered electrochemical cells. European chemical producers are piloting this technology to meet EU Green Deal carbon neutrality timelines. The approach is compressing synthetic route competitiveness against natural trona mining where renewable electricity is available.
China's MEE enforcement of carbon intensity benchmarks is accelerating fuel-switching investments at coastal Solvay plants. Older coal-sourced operations face closure pressure while natural gas retrofits and carbon capture installations absorb capital allocation. Dense soda ash output from upgraded facilities is capturing premium positioning in domestic solar glass supply chains.
Glass manufacturers are consolidating purchase volumes through digital procurement platforms that aggregate railcar scheduling and quality certification documentation. Platform-based sourcing is displacing traditional broker-mediated spot transactions for dense grade material. This shift is most visible in North American flat glass production where furnace operators prioritize supply security over price optimization.
Sodium Carbonate Market Segmentation
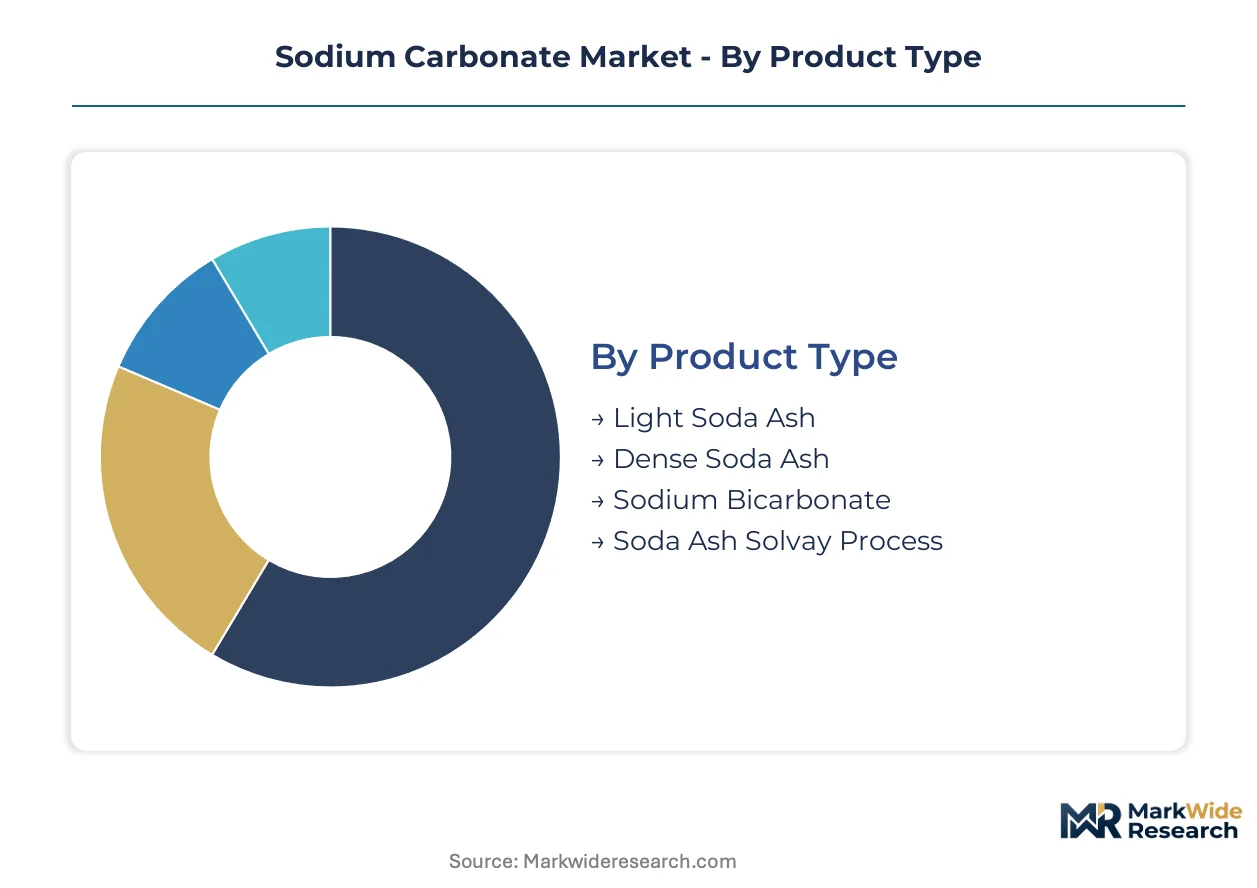
Sodium carbonate markets fragment across technical specifications that determine furnace charging efficiency, dissolution rates, and regulatory compliance burdens. Each segment carries distinct certification requirements from EPA hazardous air pollutant standards to REACH registration dossiers and food-grade purity mandates.
Product Type:
Dense soda ash commands FDA food-contact approvals for glass container manufacturing, while light grades require FSSAI registration for detergent applications in India. Sodium bicarbonate carries the heaviest pharmaceutical-grade certification load across USP and EP monographs.
- Dense Soda Ash:Higher bulk density particles reduce dusting during pneumatic conveying and improve furnace charging uniformity in flat glass operations. Demand concentrates in China's solar panel glass sector where MEE carbon intensity benchmarks favor low-carbon dense grades from upgraded Solvay plants.
- Sodium Bicarbonate:Refined derivative with pharmaceutical buffering and food-grade leavening specifications requiring USP-NF and FCC compliance. Pharmaceutical formulators in India and bakery processors across Europe are pulling volumes faster than traditional soda ash applications.
- Light Soda Ash:Lower density crystals engineered for rapid dissolution in detergent slurry formulations and chemical synthesis.
- Soda Ash Solvay Process:Synthetic production route yielding consistent purity grades for specialty chemical synthesis and laboratory reagents.
Leading the category by volume: Dense Soda Ash. Growing fastest: Sodium Bicarbonate.
End Use Industry:
Glass manufacturers dominate procurement volumes through long-term railcar contracts, while food processors impose the strictest audit requirements for supply chain traceability.
- Glass Manufacturing:Flat, container, and specialty glass producers consume dense soda ash as alkaline flux to lower silica melting temperatures. Solar panel tempered glass expansion in India under PLI scheme incentives is reshaping regional demand patterns.
- Detergents:Powder and liquid laundry formulations utilize light soda ash for water softening and pH buffering. European formulators face REACH downstream user obligations that favor compliant regional suppliers.
- Chemical Processing:Intermediate reagent for sodium silicate, sodium phosphates, and chlorine production.
- Food Processing:Sodium bicarbonate applications spanning bakery leavening, pH adjustment, and food preservation with stringent FSSAI and FDA purity requirements.
Glass Manufacturing commands the largest volume share. Food Processing exhibits the steepest expansion trajectory as pharmaceutical buffering demand accelerates.
Application:
Buffering applications in pharmaceutical manufacturing carry GMP compliance costs that segment pricing tiers, while glass production applications prioritize bulk density consistency over certification complexity.
- Glass Production:Fluxing agent reducing energy consumption in soda-lime-silica melting. Chinese solar glass foundries are pulling dense grade volumes under dual carbon goals and domestic manufacturing incentives.
- pH Regulator:Alkaline adjustment in wastewater treatment, swimming pools, and chemical synthesis requiring regional environmental permits.
- Buffering Agent:Pharmaceutical and biological applications demanding USP-grade sodium bicarbonate with validated supply chain documentation.
- Catalyst:Support material and acid scavenger in petrochemical and polymerization processes.
Glass Production leads by tonnage. Buffering Agent applications gain share fastest on pharmaceutical sector expansion.
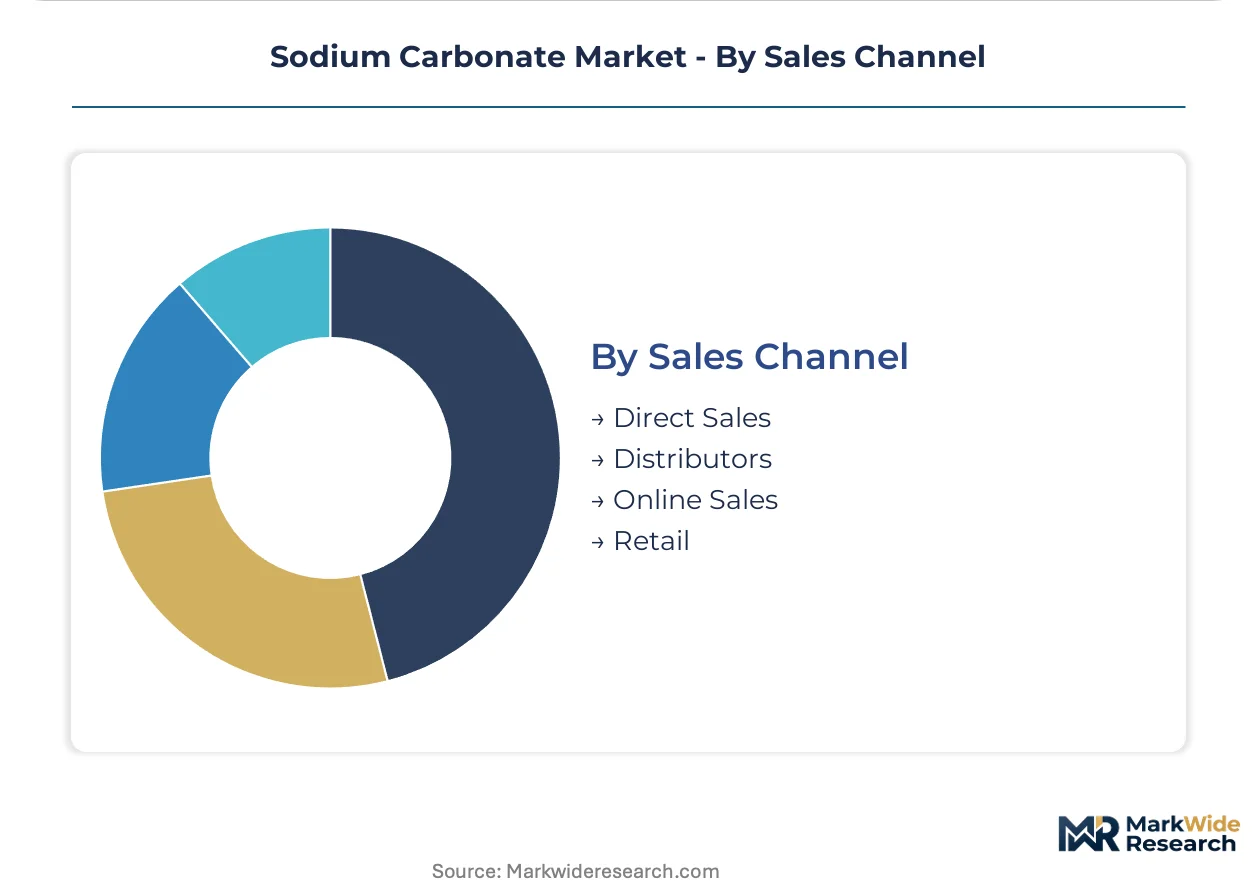
Sales Channel:
Direct sales relationships dominate dense soda ash procurement for furnace operators requiring guaranteed railcar scheduling, while distributor networks handle fragmented detergent and food-grade volumes.
- Direct Sales:Long-term contracts linking Wyoming trona producers to North American flat glass manufacturers with dedicated railcar fleets and quality certification integration.
- Distributors:Regional chemical distributors managing inventory for mid-sized detergent compounders and specialty chemical processors.
- Online Sales:E-procurement platforms aggregating spot purchases for laboratory reagents and small-batch industrial users.
- Retail:Consumer-packaged sodium bicarbonate for household cleaning and personal care applications.
Direct Sales channels capture the highest volume throughput. Online Sales channels expand most quickly as procurement digitization penetrates mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trona mining in Wyoming supplies export markets while Asian manufacturing clusters consume dense grades for glass production. China's Solvay process plants face carbon intensity pressures from MEE enforcement. India's PLI scheme accelerates domestic soda ash demand for solar panel manufacturing.
United States
Wyoming's trona reserves feed dense soda ash production for North American flat glass and export markets. EPA hazardous air pollutant standards constrain mineral processing facility emissions, requiring capital-intensive control upgrades. The Green River Basin hosts concentrated mining and refining operations serving container and automotive glass manufacturers.
China
Solar panel glass foundries in Jiangsu and Anhui provinces pull dense soda ash volumes under dual carbon goals. MEE carbon intensity benchmarks force coastal Solvay plants toward natural gas retrofits or closure. Shandong Peninsula chemical clusters integrate upgraded synthetic production with domestic solar manufacturing supply chains.
India
PLI scheme incentives for domestic glass and chemical manufacturing accelerate dense soda ash consumption. FSSAI registration requirements govern food-grade and detergent applications. Gujarat's chemical manufacturing corridor expands soda ash derivative production for pharmaceutical and detergent formulators.
Germany
REACH registration dossiers favor established European suppliers with compliant downstream formulations. ECHA chemical safety requirements structure import competition for detergent and specialty chemical applications. The Rhine-Ruhr industrial region maintains processing capacity for glass and chemical synthesis customers.
Turkey
Şişecam's integrated operations anchor soda ash supply to Mediterranean glass and detergent markets. Proximity to European and Middle Eastern buyers reduces logistics costs for dense grade exports. The Aegean and Marmara regions concentrate production capacity serving regional manufacturing clusters.
Sodium Carbonate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across trona mining, synthetic production, and derivative processing segments. Market structure consolidates around Wyoming-based natural producers and Asian synthetic operators, with mid-tier regional processors filling specialty niches. Strategic archetypes include integrated mining-refining operators, coastal Solvay process specialists, and bicarbonate derivative processors. Capacity expansion and fuel-switching retrofits dominate competitive moves as carbon regulations tighten.
Among Wyoming-based mining operators, Ciner Group and Tata Chemicals occupy positions anchored to massive trona reserves. WE Soda represents European proximity-based competition serving Mediterranean markets with lower-carbon logistics. Xinjiang Zhongtai Chemical exemplifies Chinese synthetic production scale facing MEE carbon intensity compliance pressures.
| Leading Market Players |
|---|
| Tata Chemicals |
| DCW Ltd. |
| WE Soda |
| Xinjiang Zhongtai Chemical |
| NIRMA |
| Solvay |
| Ciner Group |
| SINOPEC |
| Şişecam |
| Others |
Supply Flow & Price Mechanics
Electrification of Solvay process thermal operations is compressing synthetic production economics while concentrating supply power among Wyoming trona operators with captive low-carbon dense soda ash output. This dual shift simultaneously narrows price competition windows for coal-sourced plants and amplifies railcar contracting leverage for natural producers serving flat glass manufacturers.
Pricing Analysis
Margin tightening in synthetic grades reflects MEE carbon intensity enforcement pressuring older Chinese coal-fired operations toward fuel-switching capital burdens. Contract-based long-term offtake dominates procurement, with price differentiation separating pharmaceutical-grade sodium bicarbonate under USP-NF compliance from industrial dense grades. Glass manufacturers exhibit highest price sensitivity due to furnace throughput volumes, while pharmaceutical formulators absorb premiums for validated supply chain documentation.
Supply Chain Analysis
Regional distribution centers in Wyoming's Green River Basin anchor hub-and-spoke patterns feeding North American flat glass foundries and export terminals. Supply concentrates in the United States, China, and Turkey, with raw material dependencies on trona ore reserves, synthetic limestone and salt inputs, and natural gas feedstock. Single-source vulnerability from Wyoming's export dominance creates structural exposure to rail logistics disruptions. Distribution runs through dedicated railcar fleets linking mining complexes to furnace operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as producers pursue backward control over trona reserves and captive dense soda ash-bicarbonate complexes to secure cost-advantaged positioning against carbon-regulated synthetic competitors.
For Market Incumbents: Deploy fuel-switching retrofits at coastal Solvay plants to defend margin position against MEE closure mandates threatening older coal-sourced capacity. Consolidate railcar fleet control through dedicated long-term contracts with flat glass manufacturers facing furnace inventory security priorities. Carbon border adjustment mechanisms and energy price divergences between natural trona and synthetic routes represent the critical threat trajectory requiring defensive capital allocation. For New Entrants and Emerging Players: Launch via modular railcar contracting platforms targeting mid-sized Indian glass manufacturers under PLI scheme expansion. White-space concentrates in pharmaceutical-grade sodium bicarbonate processing where USP-NF compliance barriers deter commodity entrants. Gujarat's chemical corridor offers the most penetrable geography for import-substituting dense soda ash supply to domestic solar panel glass foundries. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated mining-refining operators with Wyoming trona reserve positions and established rail infrastructure. Long-term viability favors natural production routes with lower carbon intensity profiles aligned to tightening EPA and MEE benchmarks. Watch for MEE enforcement acceleration as the inflection signal compressing synthetic capacity valuations and amplifying natural producer acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Green River Basin operators add dense soda ash output to capture solar glass demand from Jiangsu and Anhui provinces. |
| Backward Integration | Glass manufacturers secure captive trona mining positions to insulate furnace operations from Wyoming supply concentration risk. |
| Green Manufacturing Transition | Electrolytic synthesis pilots in European chemical clusters compress synthetic route carbon intensity against natural trona benchmarks. |
| Long-term Supply Agreement | Railcar fleet dedications linking Ciner Group and Tata Chemicals to North American flat glass producers displace spot procurement. |
| Joint Venture | Indian chemical processors partner with Wyoming miners to localize dense soda ash production under PLI scheme incentives. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning plant managers at Solvay and trona operations, procurement leads at flat glass OEMs, distribution channel partners, and technical R&D directors overseeing process electrification pilots. Bottom-up and top-down triangulation validated volume estimates against ACC industry reports, SEC 10-K disclosures, and EPA hazardous air pollutant compliance documentation.
Granularity-level modeling captured grade tier distinctions between dense and light soda ash, end-use industry segmentation across glass manufacturing and detergent formulators, packaging format variations for bulk railcar versus bagged delivery, and regional production hub economics spanning Wyoming, Shandong Peninsula, and Gujarat corridors. CAGRs were derived from production capacity trajectories and demand elasticity parameters across the projection horizon, incorporating MEE carbon intensity benchmark enforcement timelines and PLI scheme incentive disbursement patterns as industry-specific forecast inputs.
Regulatory enforcement acceleration, energy price volatility, and carbon border adjustment implementation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding MEE compliance timelines and rail infrastructure capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Propionaldehyde Market