
 Hydrogen Bromide Market | 2026-2036
Hydrogen Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Bromide Market Outlook
The EU Green Deal's chemical sustainability targets is broadening scrutiny of halogenated intermediate supply chains. Albemarle Corporation leverages its bromine asset base in Arkansas to sustain captive hydrogen bromide output. Linde plc anchors industrial gas distribution networks that compete on delivery reliability for anhydrous grades. Tosoh Corporation specializes in electronic-grade purification, dominating semiconductor etchant applications.
Hydrogen bromide (HBr) is a diatomic hydrogen halide existing as a corrosive aqueous solution or compressed anhydrous gas, typically manufactured via direct synthesis from hydrogen and bromine or as a byproduct of organic bromination. The compound functions primarily as a bromination agent, acid catalyst, and intermediate in pharmaceutical and agrochemical synthesis. Pharma grade product types command premium positioning due to stringent impurity thresholds, while aqueous formulations occupy volume leadership in flame retardant feedstock. The pesticides application segment sustains structural demand from organobromine biocide production, though pharmaceutical bromination is accelerating fastest on generic API expansion.
EPA regulations under the Clean Air Act and OSHA permissible exposure limits shape domestic handling protocols, while REACH registration requirements in Europe constrain import eligibility for non-compliant suppliers. The EU F-Gas Regulation indirectly pressures brominated alternatives in certain thermal management applications, redirecting formulation demand. Stakeholders must monitor evolving halogen restriction proposals in consumer goods jurisdictions to anticipate substitution risks in flame retardant end uses.
Market Dynamics
Pharmaceutical manufacturers are intensifying hydrogen bromide consumption for active pharmaceutical ingredient bromination, while EPA Clean Air Act enforcement pressures producers toward closed-loop recovery infrastructure. This dual pressure on supply security and environmental compliance is restructuring competitive positioning across the value chain.
Growth Catalysts
- API Synthesis Expansion:Generic pharmaceutical manufacturers are scaling bromination capacity for antihistamine and analgesic intermediates, pulling anhydrous HBr volumes upward.
- REACH Registration Compliance:European chemical registration requirements are filtering out non-compliant suppliers, consolidating demand toward certified producers with established dossiers.
- Flame Retardant Feedstock:Construction and electronics sectors sustain structural consumption of aqueous HBr as a bromine carrier for tetrabromobisphenol-A production.
Market Restraints
- Bromine Price Volatility:Elemental bromine supply concentration in Arkansas and Dead Sea brine operations exposes HBr producers to input cost swings.
- Halogen Substitution Pressure:Phosphorus-nitrogen flame retardant formulations are displacing brominated alternatives in consumer electronics enclosures.
- F-Gas Regulation Indirect Effects:EU restrictions on fluorinated gases are redirecting thermal management formulation demand away from certain brominated candidates.
Strategic Opportunities
- Electronic-Grade Purification:Semiconductor etchant applications require sub-ppb metal impurity thresholds, creating premium positioning for purification technology specialists.
- India Pharmaceutical Manufacturing:CDSCO-aligned API producers are expanding bromination capacity under production-linked incentive schemes, opening import substitution potential.
- Closed-Loop Recovery Mandates:EPA emissions frameworks are incentivizing on-site HBr regeneration systems that convert waste acid back to feedstock.
Industry Challenges
- Corrosion-Resistant Infrastructure:Handling anhydrous HBr requires Hastelloy or titanium alloy equipment, elevating capital intensity for capacity expansion.
- Pharma Grade Certification Timelines:FDA and EMA validation protocols for excipient-grade material extend qualification cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Bromide Market |
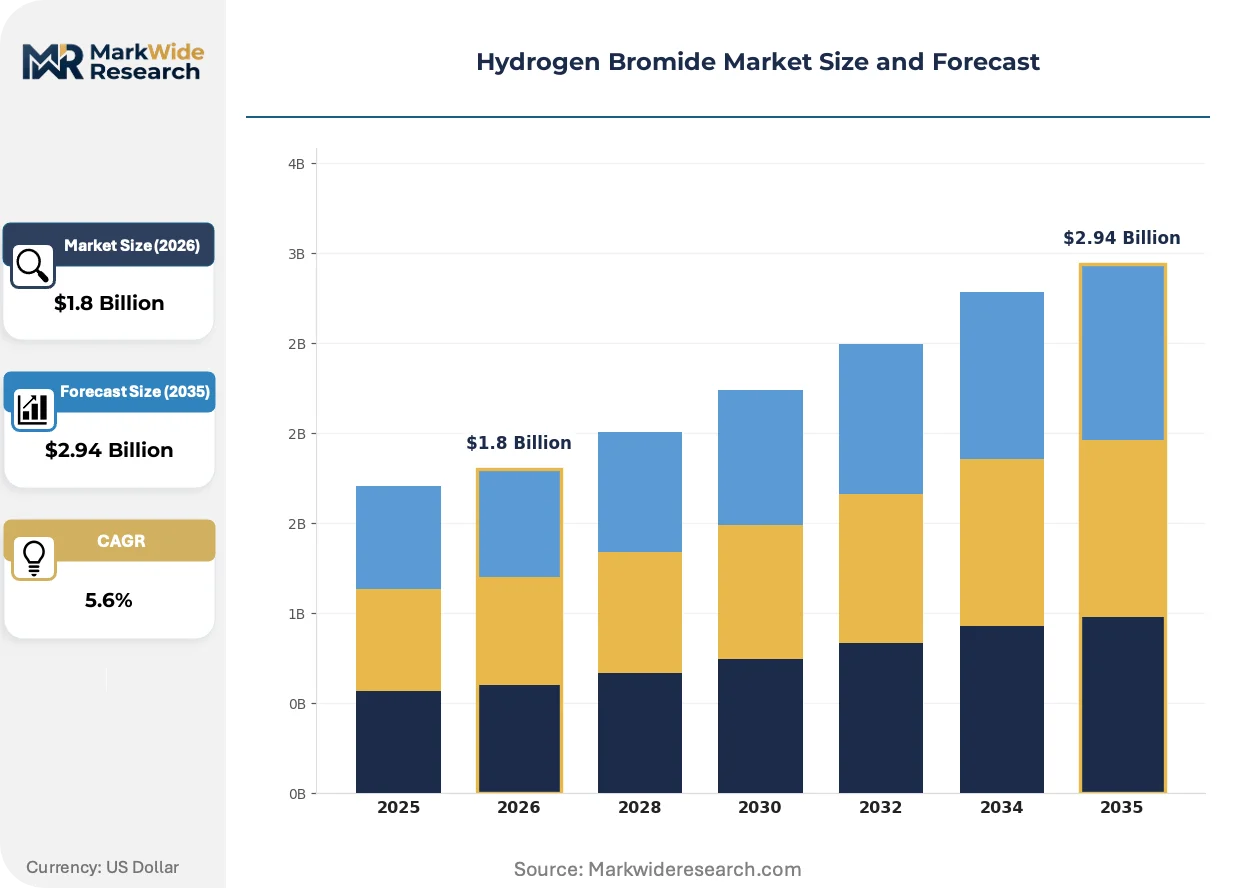
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Pesticides, Pharmaceuticals, Dyes, Flame Retardants Product Type: Aqueous, Anhydrous, Industrial Grade, Pharma Grade End User: Agriculture, Chemicals, Manufacturing, Textile Distribution Channel: Direct Sales, Distributors, Online, Retailers |
| Companies Covered | Air Liquide, Albemarle Corporation, Linde plc, LANXESS, Tosoh Corporation, Chevron Phillips Chemical Company LLC, Gulf Resources, Showa Denko K.K., ICL Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Bromide Market Strategic Shifts
Process intensification and regulatory stringency are simultaneously reshaping hydrogen bromide production economics and end-use specifications. Three developments are altering competitive dynamics across pharmaceutical, electronics, and agrochemical applications.
Membrane electrolysis for anhydrous HBr generation is converging with on-site bromine recovery systems. Specialty chemical producers in the United States are adopting integrated synthesis loops to reduce transportation risk and EPA reporting burdens. This technology convergence is compressing the viable radius between bromine extraction and HBr consumption, favoring Gulf Coast integrated operations.
REACH authorization requirements for Substances of Very High Concern are tightening brominated intermediate documentation obligations. European formulators now demand full supply chain transparency from bromine source to final derivative. Pharmaceutical and agrochemical end-users are responding by consolidating supplier relationships toward vertically integrated bromine-HBr producers with established registration dossiers.
Just-in-time inventory practices are displacing bulk storage models among semiconductor manufacturers. Wafer fabrication facilities in Japan and South Korea are shifting toward small-lot, high-frequency deliveries of electronic-grade HBr to reduce on-site hazardous material quantities. This consumption-pattern shift is elevating logistics reliability and packaging integrity as competitive differentiators over unit pricing alone.
Hydrogen Bromide Market Segmentation
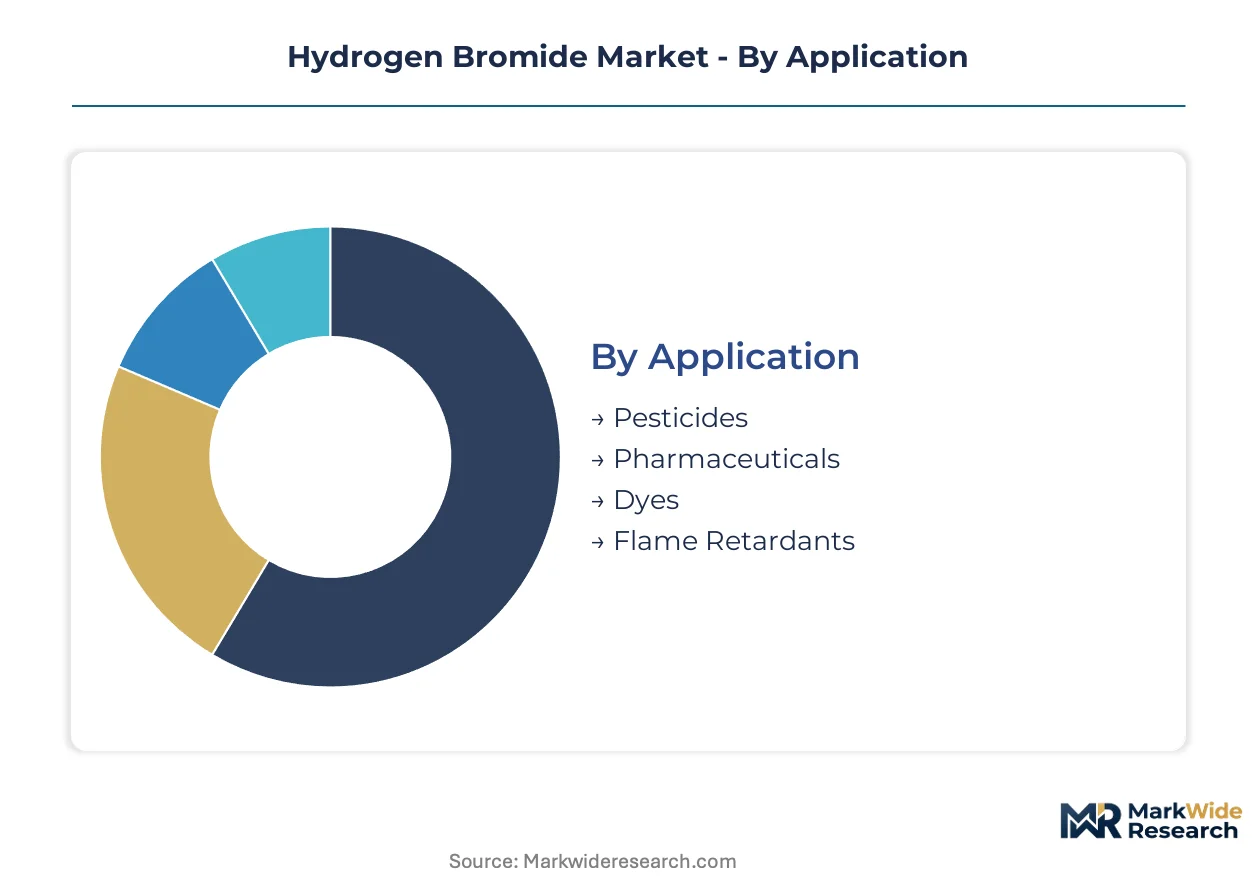
Segmentation in hydrogen bromide procurement reflects divergent purity requirements, handling protocols, and regulatory thresholds across end-use industries. Buyers in pharmaceutical and electronics applications impose specification standards that aqueous industrial users do not require, fragmenting supplier qualification pathways and pricing structures.
Application:
Purity thresholds and regulatory exposure dictate application-level procurement strategies, with semiconductor and pharmaceutical buyers commanding premium positioning through qualification barriers.
- Pharmaceuticals:Active pharmaceutical ingredient bromination requires anhydrous grades with sub-ppm impurity ceilings. Generic manufacturers in India under CDSCO-aligned production-linked incentive schemes are accelerating consumption for antihistamine and analgesic intermediates.
- Flame Retardants:Aqueous HBr functions as a bromine carrier for tetrabromobisphenol-A synthesis in construction and electronics enclosures. Demand faces substitution pressure from phosphorus-nitrogen formulations in consumer electronics applications.
- Pesticides:Organobromine biocide production sustains structural consumption volumes. EPA registration requirements for agricultural chemical intermediates constrain supplier eligibility to established dossier holders.
- Dyes:Textile colorant synthesis utilizes aqueous formulations for brominated dye intermediates. Procurement concentrates among specialty chemical manufacturers with integrated bromination capacity.
Flame Retardants leads on scale; Pharmaceuticals leads on momentum.
Product Type:
Capital intensity and purification technology separate product tiers, with electronic-grade anhydrous production requiring membrane electrolysis and metal-separation infrastructure that aqueous operations do not demand.
- Anhydrous:Compressed gas specifications serve semiconductor etchant and pharmaceutical bromination applications. Sub-ppb metal impurity thresholds in wafer fabrication facilities elevate purification specialists above commodity producers.
- Pharma Grade:FDA and EMA validation protocols for excipient-grade material extend qualification cycles to 18-24 months, creating captive relationships between certified suppliers and generic API manufacturers.
- Aqueous:Hydrohalic acid solutions dominate volume consumption in flame retardant feedstock and agrochemical intermediate production. Gulf Coast chemical clusters sustain concentrated supply through integrated bromine extraction operations.
- Industrial Grade:Standard purity specifications serve general chemical synthesis and mineral processing applications. Price sensitivity drives procurement toward bulk contractual arrangements with regional distributors.
Aqueous dominates volume throughput; Pharma Grade commands the steepest expansion trajectory.
End User:
Industry-specific regulatory frameworks and handling infrastructure requirements shape end-user procurement patterns, with chemical sector buyers leveraging captive bromine assets unavailable to textile or agricultural purchasers.
- Chemicals:Specialty and commodity chemical manufacturers represent the core consumption base, utilizing HBr for bromination catalysis and intermediate synthesis. Integrated producers with captive bromine supply in Arkansas and Dead Sea operations command cost advantages.
- Agriculture:Pesticide formulators and biocide manufacturers require EPA-registered intermediate supply chains. REACH authorization documentation obligations in Europe are consolidating supplier relationships toward vertically integrated bromine-HBr producers.
- Manufacturing:Electronics and construction material producers consume flame retardant derivatives. Just-in-time inventory practices among semiconductor fabricators in Japan and South Korea are elevating logistics reliability as a competitive differentiator.
- Textile:Dye intermediate producers utilize aqueous grades for brominated colorant synthesis. Environmental discharge regulations constrain on-site storage volumes, favoring regional distributor relationships over direct mill procurement.
Chemicals anchors procurement volume; Manufacturing exhibits the fastest share gain.
Distribution Channel:
Hazardous material handling certifications and delivery reliability requirements stratify channel selection, with anhydrous and electronic-grade buyers prioritizing direct relationships over distributor intermediation.
- Direct Sales:Anhydrous and pharma-grade buyers contract directly with producers for qualified supply security. Linde plc anchors industrial gas distribution networks competing on delivery reliability for semiconductor fabrication facilities.
- Distributors:Regional chemical distributors serve aqueous and industrial-grade consumers with storage and blending infrastructure. EPA emissions reporting burdens are incentivizing closed-loop recovery system partnerships.
- Online:Digital procurement platforms facilitate spot market transactions for standard-grade aqueous formulations. Documentation and certification verification capabilities remain limited versus direct channels.
- Retailers:Small-volume laboratory and research supply houses serve analytical and pilot-scale consumption. Geographic concentration limits viable retail presence to major chemical manufacturing clusters.
Direct Sales commands premium-tier volume; Distributors maintains broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hydrogen bromide industry traces its modern scaling to post-war American chemical manufacturing, when Gulf Coast bromine extraction operations first supplied integrated HBr production for pharmaceutical and agrochemical synthesis.
United States
Arkansas bromine brine operations and Gulf Coast chemical clusters sustain the largest integrated production base. EPA Clean Air Act enforcement pressures producers toward closed-loop recovery infrastructure. Albemarle Corporation leverages its Arkansas asset base to maintain captive hydrogen bromide output for downstream derivatives.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr and Bavaria regions consume anhydrous grades for pharmaceutical bromination and agrochemical intermediates. REACH registration requirements filter supplier eligibility toward established dossier holders. LANXESS anchors industrial-grade supply through its Leverkusen-centered operations.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region drive electronic-grade HBr demand for wafer etching applications. METI industrial chemical standards govern handling protocols for compressed anhydrous gas. Tosoh Corporation specializes in sub-ppb metal impurity purification for semiconductor clients.
India
CDSCO-aligned API producers under production-linked incentive schemes are expanding bromination capacity for generic pharmaceutical manufacturing. Central Drug Standard Control Organization regulations shape excipient-grade qualification timelines. Gujarat and Maharashtra chemical corridors concentrate new hydrogen bromide consumption for antihistamine and analgesic intermediates.
China
Shandong Peninsula and Yangtze River Delta chemical parks host flame retardant and agrochemical intermediate production. Ministry of Ecology and Environment emissions frameworks pressure toward on-site acid regeneration systems. Domestic bromine extraction from brine resources in Shandong sustains captive supply for integrated HBr operations.
Hydrogen Bromide Market Competitive Environment
Capital-heavy producers with captive bromine assets compete with asset-light distributors focused on logistics reliability and delivery frequency. The market structure concentrates around integrated chemical conglomerates with upstream bromine control, regional gas specialists with distribution networks, and purification technology providers serving semiconductor applications. Three archetypes dominate: upstream-integrated bromine operators, industrial gas logistics platforms, and electronic-grade purification specialists. Competitive moves center on backward integration into bromine extraction and geographic expansion toward Asian pharmaceutical manufacturing clusters.
Among upstream-integrated operators, Albemarle Corporation exemplifies the captive-resource archetype through its Arkansas bromine base. Linde plc and Air Liquide occupy positions as industrial gas distribution platforms competing on delivery reliability for anhydrous grades. Tosoh Corporation represents the purification-specialist tier, with electronic-grade positioning in semiconductor etchant applications. ICL Group Ltd. and Showa Denko K.K. sit within diversified chemical conglomerates with bromine derivative portfolios.
| Leading Market Players |
|---|
| Air Liquide |
| Albemarle Corporation |
| Linde plc |
| LANXESS |
| Tosoh Corporation |
| Chevron Phillips Chemical Company LLC |
| Gulf Resources |
| Showa Denko K.K. |
| ICL Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Membrane electrolysis adoption for anhydrous HBr generation is compressing the viable radius between bromine extraction and consumption, simultaneously elevating capital intensity for producers and concentrating pricing power among Gulf Coast integrated operators with captive brine assets. This technology shift tightens the feedback loop between elemental bromine cost swings and downstream hydrogen bromide quotations.
Pricing Analysis
Three-tier pricing structure across pharma grade, electronic grade, and industrial aqueous levels dominates hydrogen bromide procurement. Price differentiation hinges on metal impurity thresholds and FDA or EMA validation status, with semiconductor fabricators paying substantial premiums for sub-ppb specifications. Cost compression in industrial aqueous tiers is intensifying because phosphorus-nitrogen flame retardant substitution erodes volume leverage. Generic API manufacturers in India exhibit the highest price sensitivity, while wafer fabrication facilities in Japan and South Korea prioritize delivery reliability over unit cost.
Supply Chain Analysis
REACH registration and FDA validation protocols function as steep qualification gates that filter supplier eligibility toward established dossier holders with 18-24 month certification timelines. Geographic supply concentration centers on the United States, China, and Israel, with Arkansas and Shandong brine operations feeding captive HBr synthesis. Raw material dependencies draw from elemental bromine, hydrogen feedstock, and corrosion-resistant Hastelloy or titanium alloy equipment. Single-source vulnerability runs through Dead Sea bromine concentration, where ICL Group and Albemarle command dominant extraction positions. Distribution runs through direct sales for anhydrous and pharma grades, with regional distributors handling aqueous industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen bromide procurement has shifted toward late-cycle quality specifications as semiconductor etchant and generic API applications impose sub-ppm impurity ceilings that commodity producers cannot satisfy. Premium-grade suppliers with established regulatory dossiers now command structural margin advantages over volume-focused competitors.
For Market Incumbents: Hedge bromine price volatility through backward integration into brine extraction or long-term offtake agreements with Arkansas and Dead Sea operators. Defensive consolidation toward closed-loop recovery infrastructure addresses EPA Clean Air Act enforcement pressures while raising rival capital barriers. Certification investment in CDSCO-aligned Indian API supply chains captures production-linked incentive scheme momentum before qualification timelines extend further. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for thermal management formulation alternatives that bypass restricted brominated candidates, creating white-space in specialty chemical derivatives. CDSCO production-linked incentive schemes in India offer the most penetrable geography for import substitution in antihistamine and analgesic intermediate supply. A go-to-market angle anchored in small-lot, high-frequency electronic-grade delivery protocols addresses just-in-time inventory shifts among Japanese and South Korean wafer fabricators. For Investors and Strategic Acquirers: Valuations sit cheapest among regional aqueous distributors lacking pharma or electronic-grade qualification pathways, yet these assets face structural demand erosion from phosphorus-nitrogen substitution. Long-term viability over the coming decade favors purification technology specialists with membrane electrolysis capabilities and established semiconductor customer relationships. The signal to watch is EPA enforcement intensity around closed-loop recovery mandates, which would accelerate consolidation toward integrated bromine-HBr operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Extraction | Captive brine assets in Arkansas insulate margin structures from elemental bromine spot volatility. |
| Electronic-Grade Purification Capacity | Sub-ppb metal separation technology addresses METI standards for Kyushu wafer fabrication facilities. |
| Closed-Loop Recovery Infrastructure | On-site HBr regeneration converts waste acid to feedstock under EPA Clean Air Act frameworks. |
| CDSCO-Aligned Certification Investment | Excipient-grade qualification opens production-linked incentive scheme procurement in Gujarat and Maharashtra. |
| Small-Lot Logistics Capability | High-frequency delivery protocols match just-in-time inventory practices among South Korean semiconductor manufacturers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with specialty chemical plant managers, pharmaceutical procurement leads, semiconductor materials engineers, and industrial gas distribution channel partners with secondary validation against SEC 10-K filings, customs and trade databases, ACC and Cefic industry reports, and EPA enforcement records. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers anchored the analysis.
Comparable historical periods across the projection horizon established baseline growth trajectories for hydrogen bromide demand. The analytical framework modeled segmentation across grade tier, end-use application, regional production hub, and packaging format. CAGRs derived from volume-weighted averaging of segment-specific growth rates incorporated bromine price elasticity, REACH registration compliance timelines, and semiconductor capital expenditure cycles as industry-specific forecast inputs.
Revisions become necessary when EPA enforcement intensity shifts, EU halogen restriction proposals advance, or phosphorus-nitrogen flame retardant substitution accelerates beyond modeled trajectories. Forecasts reflect assumptions around bromine supply concentration, qualification timeline stability, and just-in-time inventory persistence among Asian electronics manufacturers. A model refresh is warranted upon material change in CDSCO production-linked incentive scheme allocation or Dead Sea brine extraction economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Saudi Arabia Sodium Thiosulphate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Global Potassium Metabisulfite Market