
 Europe Lithium Chloride Market | 2026-2036
Europe Lithium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lithium Chloride Market Insights
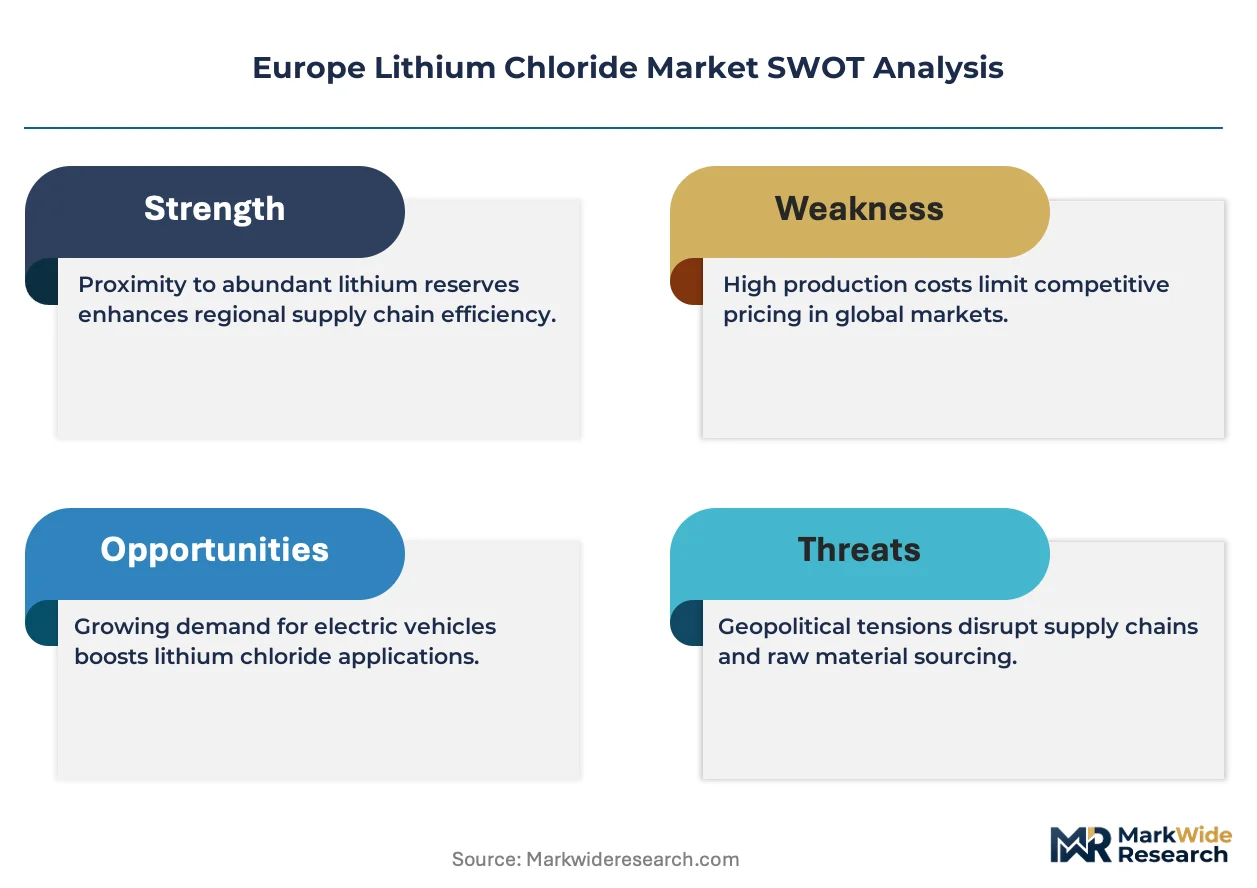
European hard-rock and geothermal brine developers is consolidating around a finite set of permitted projects with offtake visibility. Albemarle Corporation leverages its Antofagasta-linked technical expertise to sustain qualification programs for European cathode plants. Keliber Oy anchors Finland's emerging lithium corridor through its Kokkola refining footprint. Vulcan Energy Resources Ltd. differentiates by positioning zero-carbon geothermal extraction in Germany's Upper Rhine Valley.
Lithium chloride is an ionic salt with formula LiCl, typically produced at purity thresholds from 99.0% technical grade through 99.5%-plus battery grade, serving primarily as a precursor for lithium metal and electrolyte formulations in electrochemical systems. Battery grade captures the dominant margin pool as European cell producers enforce tighter impurity ceilings on sodium, calcium, and magnesium content. Technical grade retains stable volume in air conditioning desiccants and industrial gas drying, though pricing power lags the electrochemical segment. Pharmaceutical grade occupies a narrow, high-barrier niche governed by European Pharmacopoeia monographs.
ECHA administers REACH registration obligations that govern chemical safety dossiers for lithium chloride importers and manufacturers across the European Economic Area. The EU Battery Regulation mandates recycled-content quotas and supply-chain due diligence that reshape procurement criteria for battery-grade material. EFSA and national competent authorities monitor residual limits where lithium chloride touches food-contact or agricultural applications. Stakeholders must track permitting timelines for domestic refining assets against the gap between European demand and currently operational supply.
Market Dynamics
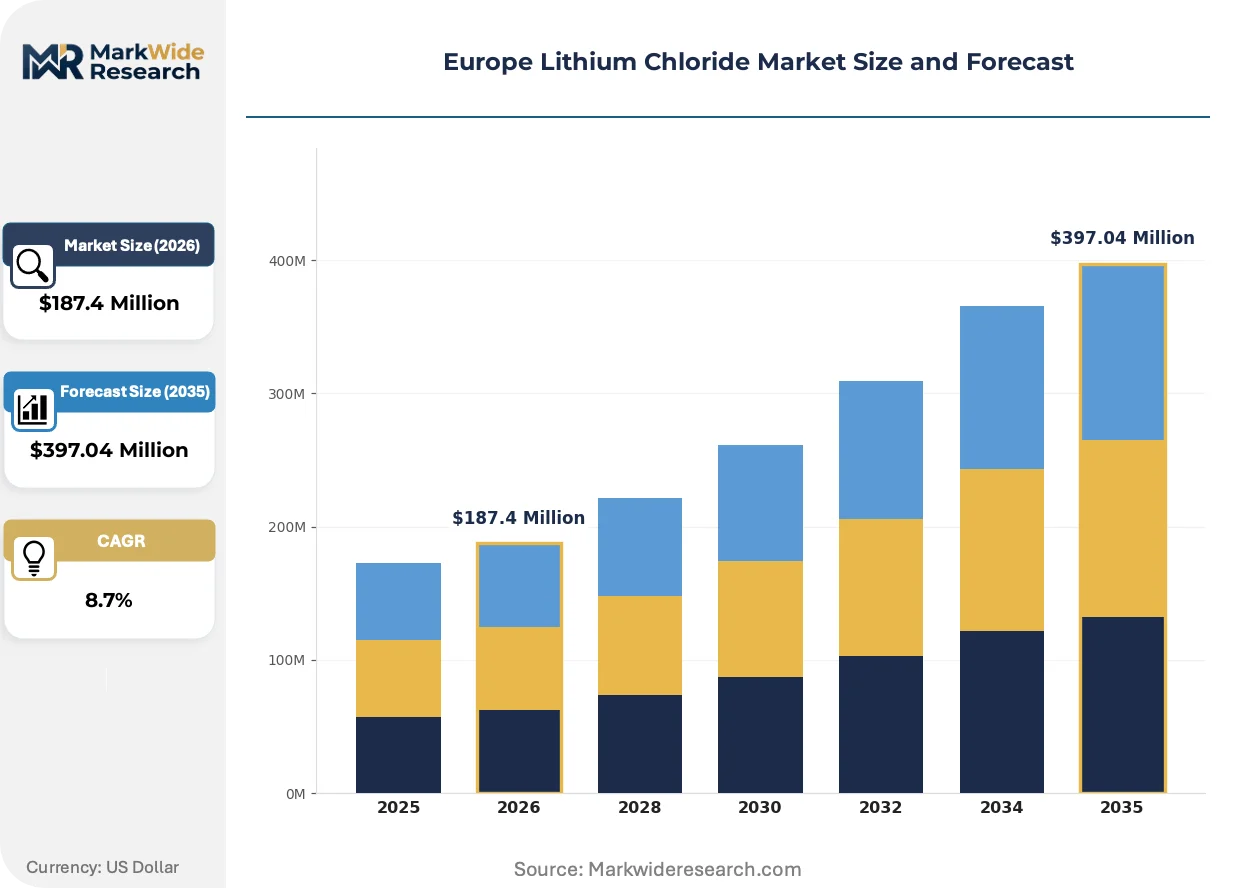
European cathode manufacturers are accelerating domestic lithium chloride sourcing to satisfy EU Battery Regulation recycled-content mandates and reduce dependency on Asian refined supply. This structural pull is compressing project development timelines for hard-rock and geothermal brine developers across Finland, Germany, and Portugal.
Growth Catalysts
- EU Battery Regulation mandates:Recycled-content quotas and supply-chain due diligence requirements are compelling European cell producers to qualify local lithium chloride sources ahead of 2030 compliance deadlines.
- Geothermal brine extraction:Zero-carbon lithium recovery from deep geothermal reservoirs in Germany's Upper Rhine Valley is attracting offtake commitments from automotive OEMs with net-zero targets.
- Hard-rock spodumene processing:Finland's emerging lithium corridor is leveraging existing mining infrastructure and Kokkola refining capacity to shorten delivery routes to Nordic cathode plants.
Market Restraints
- Energy cost volatility:Electrowinning and thermal conversion processes for battery-grade lithium chloride remain exposed to natural gas and electricity price swings across continental Europe.
- Permitting concentration risk:Domestic extraction projects face multi-year environmental approval timelines concentrated in national competent authorities with limited technical staffing.
- Spodumene supply dependency:European refiners currently rely on imported concentrate from Australia and Canada, creating feedstock vulnerability during shipping disruptions.
Strategic Opportunities
- Portuguese lithium belt:Underdeveloped hard-rock deposits in the Iberian Pyrite Belt offer untapped resource bases with existing mining codes and European Union membership advantages.
- Solid-state battery electrolytes:Lithium chloride derivatives for sulfide and halide solid electrolytes represent an emerging demand vertical as European OEMs advance next-generation cell architectures.
- REACH registration synergies:ECHA's consolidated chemical safety dossier requirements create first-mover advantages for producers establishing compliant product specifications early.
Industry Challenges
- Metallurgical expertise scarcity:Qualified process engineers for lithium chloride purification and conversion are concentrated in legacy industrial regions, constraining project staffing across emerging extraction sites.
- Battery-grade certification timelines:Cathode producer qualification protocols require 18-36 months of continuous sample validation, delaying revenue recognition for new refining capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lithium Chloride Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Battery Grade, Pharmaceutical Grade, Anhydrous End Use Industry: Electronics, Chemical Processing, Pharmaceuticals, Agricultural Form: Powder, Crystals, Solution, Tablet Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Albemarle Corporation, Nemaska Lithium Inc., Keliber Oy, Vulcan Energy Resources Ltd., European Lithium Ltd., Rock Tech Lithium Inc., Livent Corporation, Nippon Chemical Industrial CO., LTD., LEVERTON HELM LTD, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lithium Chloride Market Trends and Innovations
Direct lithium extraction from geothermal brines is reshaping European supply assumptions by eliminating conventional evaporation ponds and their associated land and water footprints. This technological pivot is attracting capital allocation away from traditional hard-rock processing routes.
Chloride-based direct lithium extraction using selective sorbents is electrifying project economics in Germany's Upper Rhine Valley by enabling continuous production with minimal reagent consumption. Vulcan Energy Resources and regional utilities are deploying modular units adjacent to existing geothermal power infrastructure. This approach is compressing development timelines and positioning zero-carbon lithium chloride for premium offtake contracts with automotive cell producers.
REACH registration obligations administered by ECHA are tightening purity disclosure requirements for lithium chloride importers and manufacturers across the European Economic Area. Battery-grade specifications now demand documented impurity ceilings for sodium, calcium, and magnesium alongside carbon-footprint attestations. Cathode plants in Germany and Poland are restructuring procurement contracts to incorporate these compliance checkpoints.
Long-term offtake agreements are displacing spot market purchases as European cell producers secure qualified supply chains ahead of EU Battery Regulation enforcement. Tier-one cathode manufacturers in Finland and Hungary are negotiating five-to-ten-year contracts with fixed volume escalators and price adjustment mechanisms tied to energy indices. This behavioral shift is most visible in negotiations with domestic refining projects seeking construction financing.
Europe Lithium Chloride Market Segmentation
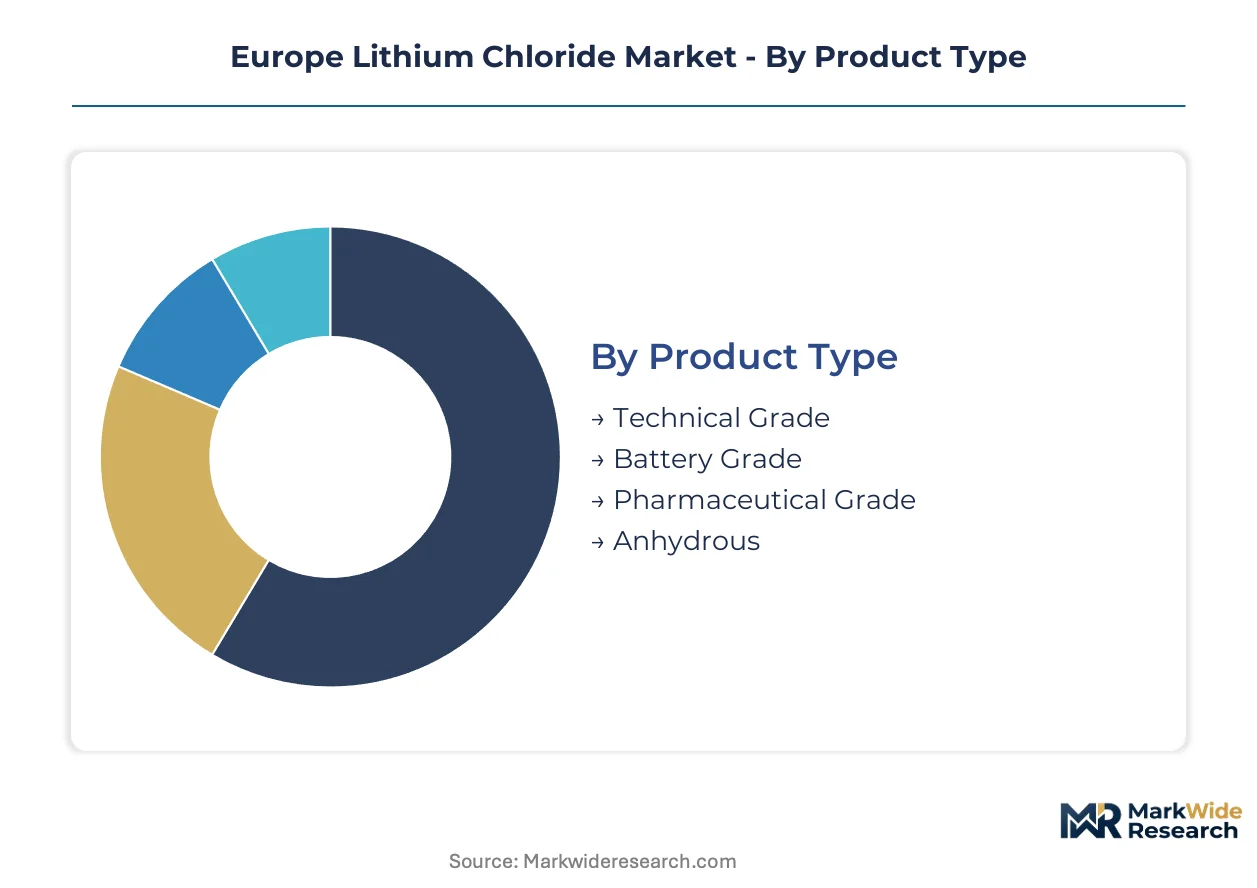
Segmentation in the Europe lithium chloride market reveals how purity thresholds and regulatory compliance reshape procurement economics. European cathode manufacturers enforce strict impurity ceilings that fragment the market into distinct pricing tiers and qualification protocols.
Product Type:
Battery grade commands premium positioning through tighter sodium, calcium, and magnesium specifications, while technical grade sustains volume throughput in industrial applications with lower purity barriers.
- Battery Grade:Purity thresholds exceed 99.5% with documented impurity ceilings for sodium, calcium, and magnesium. European cathode plants in Germany and Poland enforce these specifications through 18-36 month qualification protocols, compressing supplier margins until certification completion.
- Technical Grade:Specifications center on 99.0% purity with broader impurity tolerances. Air conditioning desiccant manufacturers and industrial gas drying operations in Spain and Italy absorb steady volumes at pricing indexed to energy costs rather than electrochemical premiums.
- Pharmaceutical Grade:European Pharmacopoeia monographs govern production for medical applications with batch-level traceability requirements.
- Anhydrous:Water content below 0.1% suits moisture-sensitive electrolyte formulations and specialized chemical synthesis.
Mature deployment sits with technical grade in legacy industrial drying. Newer deployment is concentrated in battery grade as European cell producers accelerate domestic qualification timelines.
End Use Industry:
Electronics applications concentrate margin capture through electrochemical system integration, while chemical processing retains volume stability in mature industrial corridors.
- Electronics:Lithium metal production and electrolyte formulations for solid-state and conventional cell architectures. Finnish and Hungarian cathode plants are restructuring procurement contracts to incorporate REACH compliance checkpoints and carbon-footprint attestations.
- Chemical Processing:Catalyst precursors and organolithium reagents for polymerization and pharmaceutical intermediates. German chemical clusters along the Rhine maintain captive consumption patterns with minimal spot market exposure.
- Pharmaceuticals:Mood stabilizer formulations and diagnostic reagents with European Medicines Agency oversight on active pharmaceutical ingredient sourcing.
- Agricultural:Limited applications in livestock feed supplements with EFSA monitoring on residual lithium limits in food-chain products.
Electronics applications are climbing the fastest as EU Battery Regulation mandates force supply-chain restructuring. Chemical processing maintains the deepest volume base through established industrial relationships.
Form:
Powder and crystal forms dominate physical handling economics, while solution and tablet formats address specialized delivery requirements in downstream processing.
- Powder:Free-flowing particulate with controlled particle size distribution for dry blending into cathode precursor slurries. Nordic refineries are optimizing particle morphology to reduce dust exposure and improve handling economics at cathode plants.
- Crystals:Large-format solid with minimal surface area for moisture-stable storage and controlled dissolution kinetics. German logistics providers favor crystalline form for reduced packaging requirements during rail transport.
- Solution:Aqueous or organic solvent preparations for direct injection into continuous electrowinning processes.
- Tablet:Compressed solid for precise dosing in pharmaceutical and laboratory applications.
Crystalline form anchors established supply contracts with predictable logistics costs. Powder configurations are gaining share fastest through compatibility with automated cathode manufacturing lines.
Distribution Channel:
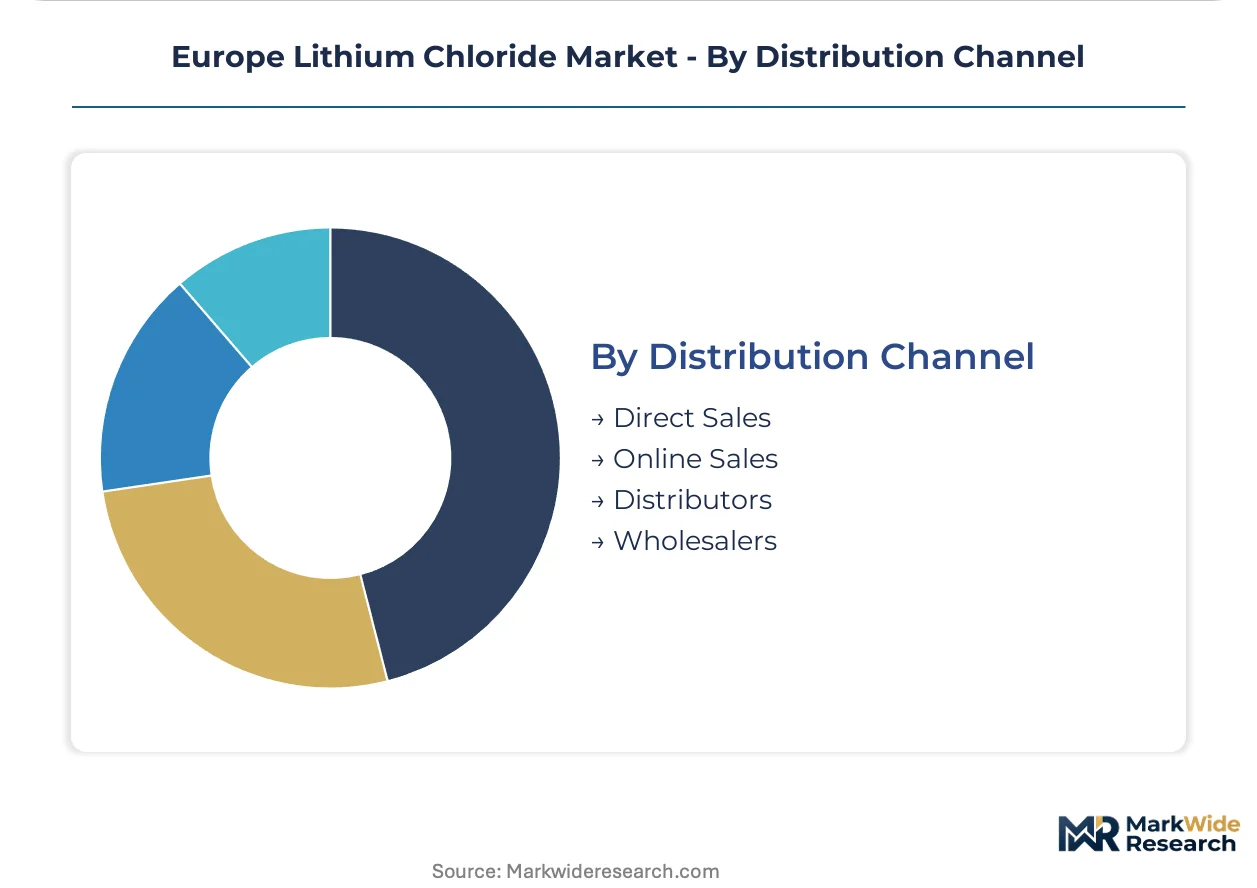
Direct sales capture premium relationships with qualified cathode producers, while distributor networks extend geographic reach into fragmented industrial demand pockets.
- Direct Sales:Long-term offtake agreements with five-to-ten year horizons and price adjustment mechanisms tied to energy indices. Finnish refining projects leverage direct relationships with Nordic cathode plants to secure construction financing.
- Distributors:Regional inventory positioning for technical grade spot purchases by mid-sized chemical processors. Portuguese and Spanish distributors are consolidating warehousing capacity to serve Iberian industrial corridors.
- Online Sales:Limited to laboratory-scale quantities and reagent-grade products with credit-card transaction thresholds.
- Wholesalers:Bulk aggregation for agricultural and technical applications with minimal specification differentiation.
Wholesaler relationships dominate agricultural and legacy technical grade flows. Direct sales channels are expanding most quickly as battery-grade qualification requirements compress viable supplier pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish spodumene deposits and German geothermal brines anchor Europe's emerging lithium chloride supply base. Domestic refining projects concentrate around existing industrial corridors with permitted infrastructure and cathode producer proximity. Regulatory deadlines under the EU Battery Regulation compress development timelines across the continent.
Germany
Geothermal brine extraction in the Upper Rhine Valley supplies zero-carbon lithium chloride to automotive cell producers. The Federal Mining Act governs permitting for deep drilling operations while KBA oversees vehicle battery compliance. Ludwigshafen and Düsseldorf host refining partnerships between energy utilities and chemical processors.
Finland
Hard-rock spodumene mining in Central Ostrobothnia feeds the Kokkola refining corridor serving Nordic cathode plants. Finnish mining legislation streamlines environmental approvals compared to continental counterparts. Vaasa and Kokkola concentrate lithium processing infrastructure adjacent to existing nickel and cobalt refineries.
Portugal
Untapped lithium pegmatites in the Iberian Pyrite Belt attract exploration investment from battery supply chain financiers. Portuguese mining codes offer EU membership advantages with existing environmental frameworks. Guarda and Viseu districts host preliminary drilling campaigns targeting battery-grade feedstock.
United Kingdom
Geothermal lithium exploration in Cornwall targets domestic supply for British cell manufacturing investments. The UK Battery Strategy mandates supply chain resilience assessments for critical mineral sourcing. Redruth and St Austell host pilot extraction facilities leveraging historical mining infrastructure.
France
Geothermal brine prospects in Alsace and the Massif Central compete for EU Innovation Fund support against hard-rock alternatives. French mining regulations require extensive public consultation extending project timelines. Mulhouse and Strasbourg evaluate direct lithium extraction adjacent to existing heat and power facilities.
Europe Lithium Chloride Market Competitive Landscape
Global majors compete with regional champions across extraction methodology and carbon intensity credentials. Market structure tilts toward project developers with permitted assets and offtake visibility rather than established commodity traders. Three archetypes dominate: integrated mining-refining operators, geothermal specialists with utility partnerships, and trading houses with qualification expertise. Capacity expansion and long-term supply agreements constitute the primary competitive moves as cathode producers lock in qualified volumes.
Among North American-listed developers, Nemaska Lithium Inc. and Rock Tech Lithium Inc. occupy positions within the hard-rock processing archetype. Australian-registered Vulcan Energy Resources Ltd. exemplifies the geothermal-zero-carbon positioning. Finnish Keliber Oy anchors the integrated Nordic corridor. These entities represent distinct technical routes to battery-grade certification.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Nemaska Lithium Inc. |
| Keliber Oy |
| Vulcan Energy Resources Ltd. |
| European Lithium Ltd. |
| Rock Tech Lithium Inc. |
| Livent Corporation |
| Nippon Chemical Industrial CO., LTD. |
| LEVERTON HELM LTD |
| Others |
Pricing and Supply Chain Analysis
Captive integration into domestic refining assets anchors both supply security and pricing power for European cathode producers navigating EU Battery Regulation compliance. German and Finnish projects leverage utility partnerships and existing industrial corridors to compress qualification timelines while commanding premium positioning against Asian imports.
Pricing Analysis
Long-term offtake bundling with carbon-footprint attestation separates qualified battery-grade supply from spot technical-grade transactions. Pricing stratifies across battery, technical, and pharmaceutical tiers based on REACH documentation depth and impurity certification rigor. Cost compression in technical grade intensifies as energy-indexed contracts expose producers to continental electricity volatility. Mid-sized chemical processors in Southern Europe exhibit highest price sensitivity, while Nordic cathode plants prioritize qualification speed over unit economics.
Supply Chain Analysis
Reverse-logistics frameworks for battery recycling are reshaping feedstock flows as EU Battery Regulation mandates drive closed-loop lithium recovery. Primary extraction concentrates in Finland, Germany, and Portugal, with hard-rock spodumene and geothermal brine routes competing for project finance. European refiners draw from Australian and Canadian concentrate imports, creating feedstock vulnerability during maritime disruptions. Tariff exposure on imported spodumene concentrate constitutes the dominant structural risk. Distribution runs through direct sales channels for battery-grade volumes, while distributor networks handle technical-grade spot demand across Iberian and Italian industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU Battery Regulation qualification timelines is forcing sub-scale developers toward joint ventures or exit, rewarding permitted assets with offtake visibility.
For Market Incumbents: Anchor qualification pipelines through accelerated sample validation programs at Finnish and German cathode plants. Deepen backward integration into Portuguese hard-rock deposits to diversify feedstock exposure beyond Australian concentrate. Defend margin position by locking five-to-ten-year offtake contracts with energy-indexed price adjustment mechanisms before competitor capacity reaches commissioning.
For New Entrants and Emerging Players: The premium-to-economy price gap in battery-grade certification offers entry leverage for geothermal specialists with zero-carbon positioning. Target Portuguese exploration licenses in the Iberian Pyrite Belt where mining codes and EU membership reduce regulatory friction. Pursue utility partnership structures in Germany's Upper Rhine Valley to access existing geothermal infrastructure and compress development timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated mining majors seeking European battery supply chain exposure. Long-term viability hinges on permitted status and cathode producer qualification progress rather than resource scale alone. Monitor ECHA REACH registration completion timelines as the critical inflection signal for revenue recognition readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hard-Rock Mining | Portuguese pegmatite access reduces Australian concentrate dependency for Nordic refiners. |
| Geothermal Zero-Carbon Certification | Upper Rhine Valley projects qualify for automotive OEM net-zero procurement mandates. |
| Long-Term Offtake Agreement Structuring | Finnish cathode plants secure construction financing for Kokkola corridor expansion. |
| REACH Registration Acceleration | ECHA dossier completion unlocks battery-grade qualification revenue recognition timelines. |
| Utility Partnership Formation | German energy operators provide permitted drilling rights and existing heat infrastructure access. |
Research Methodology
Trade databases, ECHA registration filings, and EU customs records formed the secondary backbone for supply flow quantification. Primary interviews with cathode plant procurement directors, geothermal project developers, and hard-rock mining engineers validated capacity assumptions and qualification timelines. Bottom-up and top-down triangulation reconciled project-level production estimates against end-use demand aggregation across electronics, chemical processing, and pharmaceutical applications.
Bottom-up modeling of permitted project capacities anchored volume projections across the analysis window. Segmentation dimensions included purity grade tier, end-use industry, physical form, and distribution channel structure. CAGRs derived from logistic curve fitting of adoption rates for domestic versus imported supply. Forecast inputs incorporated EU Battery Regulation enforcement schedules and ECHA REACH registration completion trajectories.
Inputs from ECHA dossier databases and national mining authority permit registries were available through the study window; gaps in pre-revenue project commissioning timelines introduce uncertainty bands around near-term supply estimates. Forecasts reflect stated assumptions regarding cathode producer qualification protocol durations and geothermal extraction technology deployment rates. Practitioners should monitor ECHA registration publication dates and Finnish mining authority environmental approval announcements for early signals of supply inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Copper Sulfate Market