
 Europe Ammonium Nitrate Market | 2026-2036
Europe Ammonium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ammonium Nitrate Market Insights
Modular fertilizer bundling with micronutrient co-formulations is hardening buyer preferences across European distribution channels. YARA leverages its integrated ammonia-to-nitrate supply chain to sustain premium positioning in Nordic markets. EuroChem Group anchors volume competitiveness through captive phosphate-nitrate blending operations in Belgium and the Netherlands.
Ammonium nitrate is a crystalline salt compound produced through the neutralization of nitric acid with ammonia, typically formulated at nitrogen concentrations between 33.5% and 34.5% for agricultural and industrial applications. The material serves as both a high-analysis nitrogen fertilizer and the principal oxidizer in ammonium nitrate fuel oil explosives used in surface mining and quarrying. Granular and prill formulations dominate agricultural offtake, with prills commanding tighter specifications for pneumatic spreading equipment across large-scale farming operations in Eastern Europe. The explosives application segment maintains higher per-ton margins despite smaller volumes, driven by open-pit mining activity in Scandinavia and the Iberian Peninsula.
The EU Green Deal, REACH chemicals framework, and F-Gas Regulation collectively constrain production emissions and mandate cleaner manufacturing pathways for nitrogen fertilizer producers. ECHA classification requirements for oxidizing substances restrict cross-border transport modalities and storage configurations, reshaping logistics networks. EFSA and national regulators in Germany and France impose strict ammonium nitrate concentration limits in blended products, compressing formulation flexibility for compound fertilizers. Stakeholders must monitor evolving carbon border adjustment mechanisms and national fertilizer subsidy recalibrations to anticipate demand shifts between imported and domestically produced material.
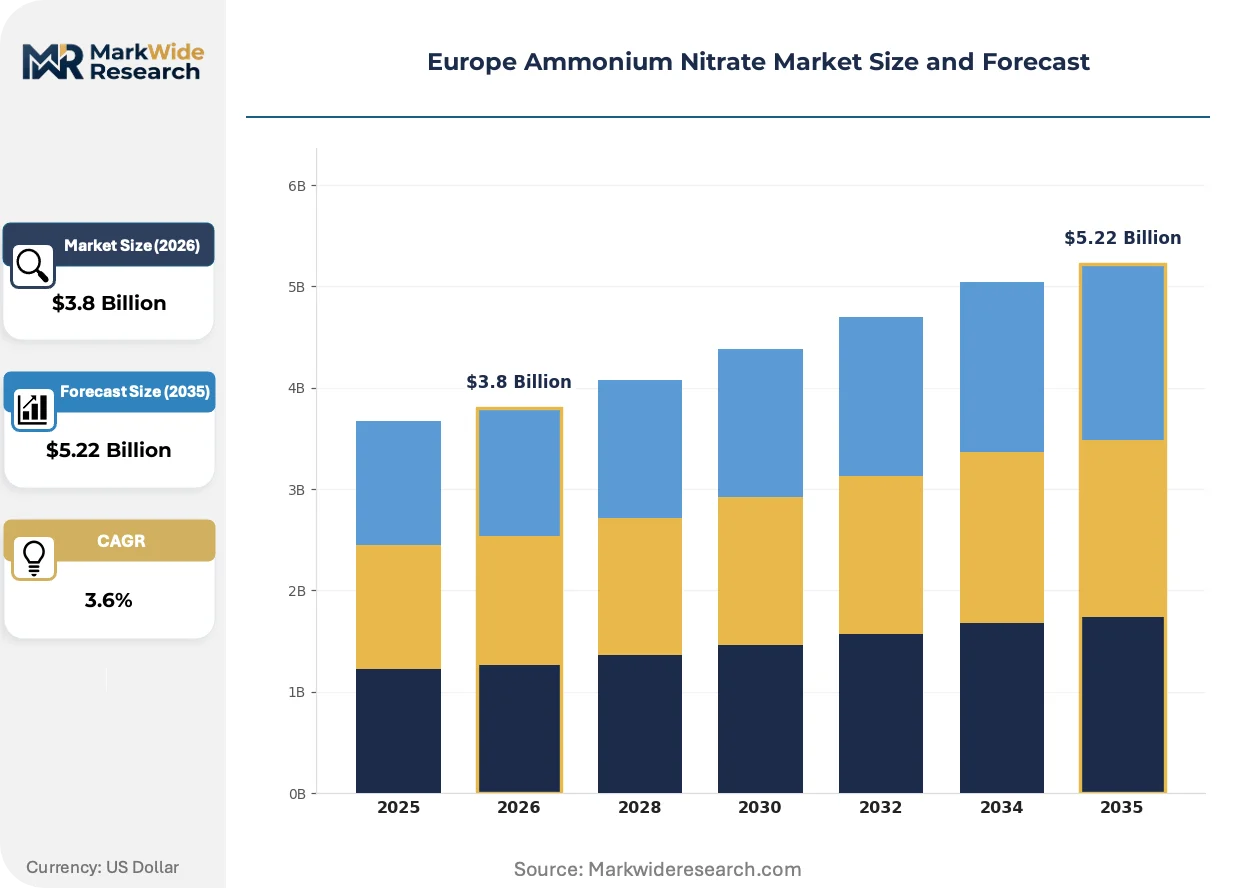
Market Dynamics
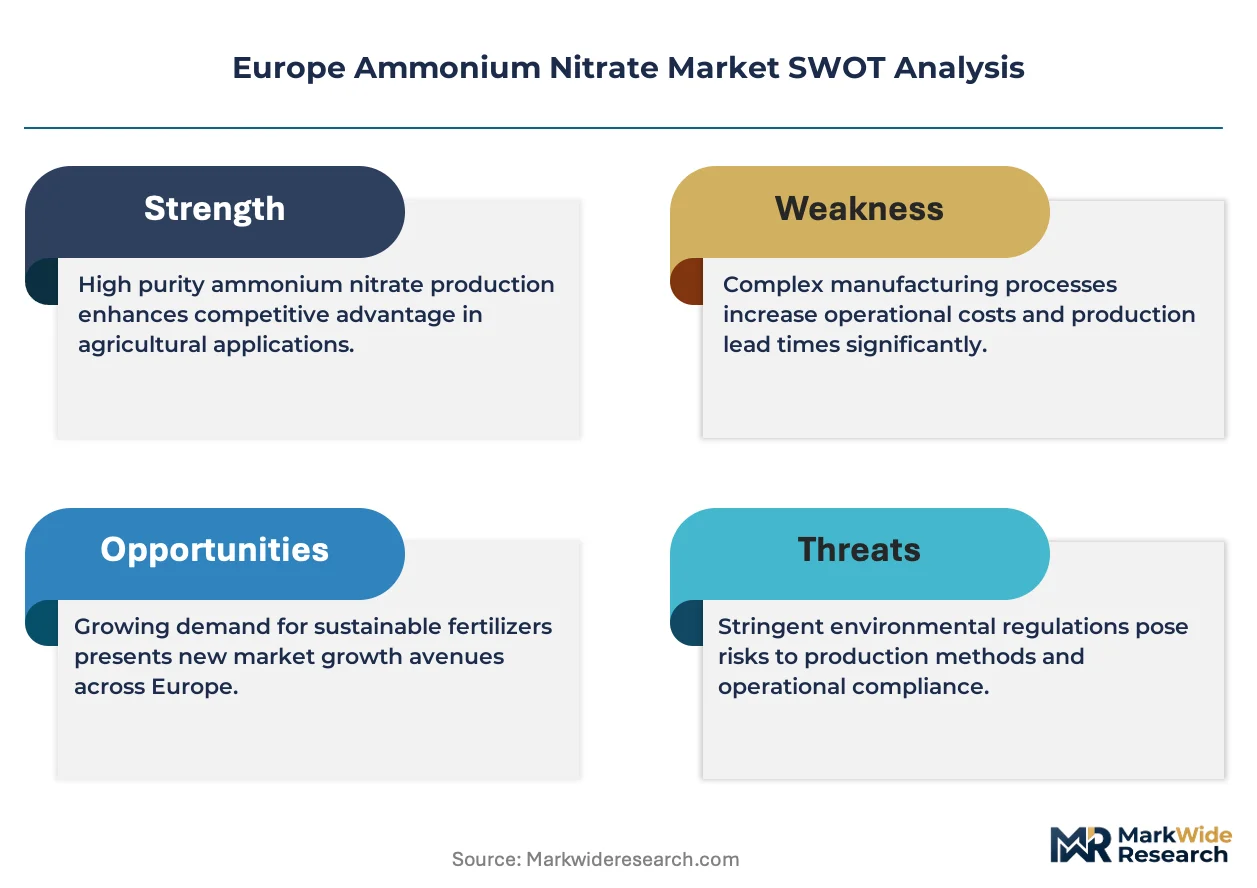
The EU Green Deal and F-Gas Regulation are compressing production margins while redirecting capital toward low-carbon ammonia cracker retrofits and carbon capture integration at nitric acid plants.
Growth Catalysts
- Precision agriculture adoption:Variable-rate application systems across Germany and France are pulling demand for high-analysis nitrogen fertilizers with uniform prill specifications.
- EU carbon border adjustment mechanisms:Import parity shifts are favoring domestic European production over North African and Russian supply, tightening regional supply-demand balances.
- Controlled-release coating technologies:Polymer-encapsulated ammonium nitrate variants are extending nutrient availability windows for specialty row-crop applications.
Market Restraints
- Natural gas feedstock volatility:Ammonia production costs swing with TTF hub pricing, compressing nitrate producer margins during winter demand spikes.
- ECHA oxidizer classification constraints:Cross-border transport of high-concentration ammonium nitrate faces modal restrictions and storage separation mandates, inflating logistics costs.
- Organic farming substitution:EU Farm-to-Fork targets are accelerating manure-based and biostimulant alternatives in certified organic acreage across Austria and Denmark.
Strategic Opportunities
- Polish agricultural consolidation:Large-scale farming cooperatives in Greater Poland Voivodeship are centralizing procurement, creating volume anchor contracts for integrated suppliers.
- Green ammonia offtake agreements:Electrolyzer-based ammonia projects in Norway and the Netherlands offer zero-carbon nitrate pathways for sustainability-linked procurement.
- Blended explosive-grade formulations:Open-pit mining expansion in Sweden and Finland is widening demand for high-density prills with optimized oil absorption characteristics.
Industry Challenges
- Process safety engineer scarcity:Nitric acid plant operators face recruitment gaps for Seveso III compliance and hazard analysis expertise.
- REACH registration timelines:Co-formulant additives in enhanced fertilizers face extended ECHA evaluation periods, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ammonium Nitrate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.22 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Ammonium Nitrate Prills, Ammonium Nitrate Solution Application: Agriculture, Explosives, Fertilizers, Chemical Manufacturing End User: Farming, Mining, Construction, Industrial Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Sales |
| Companies Covered | YARA, EuroChem Group, Orica Limited, URALCHEM JSC, ENAEX, Neochim PLC, Fertiberia SA, OSTCHEM, Borealis AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ammonium Nitrate Market Trends and Innovations
Carbon intensity metrics are penetrating procurement specifications, while coating technologies and logistics digitization are reconfiguring how value is captured across the nitrogen fertilizer chain.
Stabilized ammonium nitrate formulations incorporating calcium magnesium nitrate shells are absorbing premium positioning in pneumatic spreading applications across Eastern European large-scale farms. Polish and Czech agricultural contractors are specifying these variants for reduced caking and improved flowability. The technology is absorbing margin compression from standard-grade commoditization by commanding 8-12% price premiums in spot tender markets.
REACH chemicals framework amendments are tightening impurity thresholds for heavy metals and pesticide co-residues in fertilizer-grade nitrate. ECHA dossier updates are forcing reformulation of legacy anti-caking agents containing ferrocyanide complexes. German and French compound fertilizer blenders are most affected, accelerating substitution toward organic polymer dispersants.
Cooperative procurement platforms are consolidating smallholder demand into aggregated tender volumes across Romanian and Bulgarian distribution territories. Regional agronomy consortia are displacing traditional merchant trader intermediaries with direct mill gate contracts. The shift is most visible in the Black Sea corridor, where port logistics integration is enabling synchronized loading windows for bulk vessel charters.
Europe Ammonium Nitrate Market Segmentation
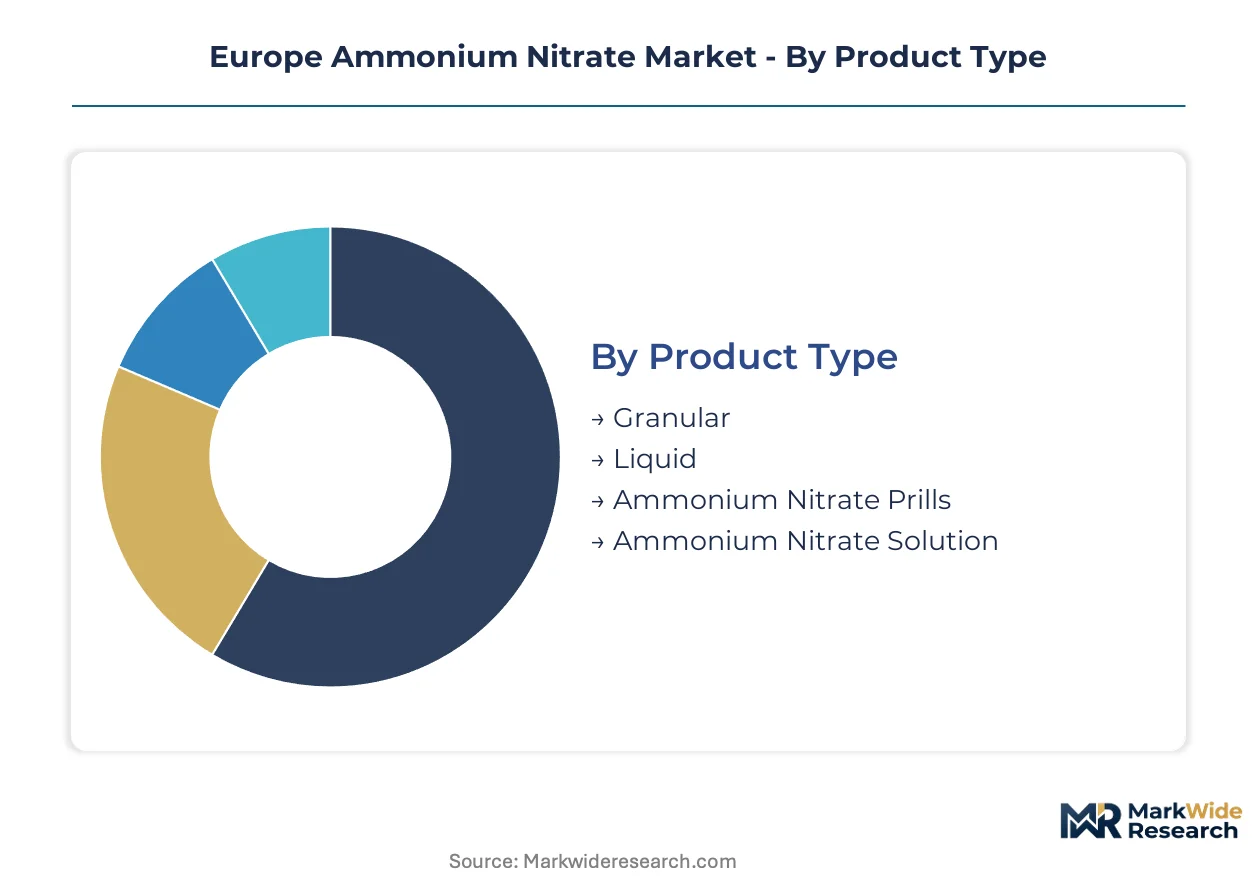
European ammonium nitrate procurement patterns diverge sharply between bulk agricultural buyers seeking uniform physical specifications and industrial consumers prioritizing chemical purity. Understanding these segment boundaries clarifies why producers maintain parallel product lines despite overlapping nitrogen content.
Product Type:
Buyers differentiate primarily by handling infrastructure and application equipment compatibility.
- Granular:Dense crystalline particles with superior crushing strength suit mechanical spreading across German and Polish arable operations. Demand concentrates in compound fertilizer blending facilities where particle size uniformity determines segregation resistance during pneumatic transport.
- Liquid:Pre-dissolved formulations eliminate dissolution infrastructure for smaller French and Belgian farming cooperatives. Adoption accelerates where irrigation injection systems enable fertigation coupling with precision agriculture platforms.
- Ammonium Nitrate Prills:Spherical particles optimized for pneumatic spreading equipment dominate Eastern European large-scale farming. Czech and Romanian contractors specify prill hardness and oil absorption characteristics for explosives-grade applications.
- Ammonium Nitrate Solution:Concentrated aqueous formulations serve industrial nitration processes and explosives manufacturing in Scandinavian mining corridors. Swedish and Finnish open-pit operators favor solution delivery for on-site fuel oil blending.
Prills lead volumes today; liquid formulations are gaining share fastest.
Application:
Margin profiles and regulatory exposure separate commercial segments more than volume scale.
- Agriculture:High-analysis nitrogen delivery for row-crop and cereal production across the Central European farming belt. EFSA concentration limits in Germany and France compress formulation flexibility for compound fertilizers.
- Explosives:ANFO and emulsion blasting agents for surface mining in Sweden, Finland, and the Iberian Peninsula command premium per-ton margins despite smaller offtake volumes. ECHA oxidizer classification restricts cross-border transport modalities.
- Fertilizers:Straight nitrogen application and NPK blending feedstock for distribution networks across Poland and the Czech Republic. REACH framework amendments tighten heavy metal impurity thresholds for legacy anti-caking agents.
- Chemical Manufacturing:Industrial nitration feedstock for specialty chemicals and pharmaceutical intermediates. Batch purity specifications exceed agricultural grades, commanding certification premiums in Benelux chemical corridors.
Fertilizer applications anchor volume; explosives manufacturing delivers steepest margin expansion.
End User:
Procurement scale and technical sophistication determine channel access and pricing leverage.
- Farming:Arable cooperatives and contractor spraying services across Greater Poland Voivodeship and Romanian Black Sea plains centralize procurement through cooperative platforms. Aggregated tender volumes displace traditional merchant intermediaries.
- Mining:Open-pit operators in Swedish iron ore districts and Finnish limestone quarries specify high-density prills with optimized oil absorption. Long-term offtake agreements with integrated suppliers secure supply continuity.
- Construction:Quarrying and infrastructure blasting contractors in Germany and Austria face seasonal demand fluctuations. Just-in-time delivery requirements favor regional solution terminals over bulk granular shipments.
- Industrial:Chemical processors and explosives manufacturers in Belgium and the Netherlands require certificate-of-analysis documentation for each batch. REACH registration timelines for co-formulant additives delay product qualification by 18-24 months.
Farming absorbs the largest tonnage; mining contracts are climbing the fastest.
Distribution Channel:
Logistics integration depth and working capital availability shape channel selection.
- Direct Sales:Mill gate contracts between producers and large-scale farming cooperatives eliminate intermediary margins. Polish agricultural consolidation enables synchronized loading windows for bulk vessel charters.
- Wholesalers:Regional distributors aggregate fragmented demand across Bulgarian and Romanian territories. Port logistics integration in the Black Sea corridor enables competitive import parity positioning.
- Retailers:Farm supply stores and agronomy service centers serve smallholder segments in Austria and Denmark. Organic farming substitution pressures compress ammonium nitrate shelf space in certified organic acreage regions.
- Online Sales:Digital procurement platforms emerge for standardized fertilizer grades with transparent pricing. Limited penetration reflects transport regulatory complexity under ECHA oxidizer classification.
Direct sales dominate tonnage; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale ammonium nitrate production first achieved commercial scale in Germany during the early twentieth century, establishing Central Europe as the foundational region for nitrogen fertilizer chemistry and explosives manufacturing expertise.
Germany
Variable-rate application systems across Bavaria and Lower Saxony pull demand for high-analysis nitrogen fertilizers with uniform prill specifications. The F-Gas Regulation and national fertilizer subsidy recalibrations compress formulation flexibility for compound fertilizers. The Rhine-Ruhr chemical corridor hosts integrated ammonia-to-nitrate operations serving both agricultural and explosives-grade markets.
Poland
Large-scale farming cooperatives in Greater Poland Voivodeship centralize procurement through cooperative platforms, creating volume anchor contracts. EU carbon border adjustment mechanisms favor domestic production over imported supply. The Vistula River basin concentrates blending facilities and port logistics integration for Black Sea corridor exports.
France
Precision agriculture adoption across the Île-de-France and Hauts-de-France cereal belts drives specification requirements for pneumatic spreading equipment. EFSA concentration limits in blended products mandate reformulation of legacy compound fertilizers. The Paris Basin agronomy clusters displace traditional merchant intermediaries with direct mill gate contracts.
Sweden
Open-pit mining expansion in the Kiruna iron ore district widens demand for high-density prills with optimized oil absorption characteristics. ECHA oxidizer classification restricts cross-border transport modalities for explosives-grade material. The Scandinavian mining corridor sustains long-term offtake agreements with integrated suppliers for supply continuity.
Netherlands
Electrolyzer-based ammonia projects in the Rotterdam port cluster offer zero-carbon nitrate pathways for sustainability-linked procurement. REACH registration timelines for co-formulant additives delay product qualification. The Benelux chemical corridor maintains certificate-of-analysis documentation requirements for industrial nitration feedstock.
Europe Ammonium Nitrate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across carbon intensity and supply chain integration depth. The vendor base fragments between integrated ammonia-nitrate producers and merchant blenders dependent on traded feedstock. Three archetypes dominate: Nordic integrated majors with captive ammonia supply, Central European phosphate-nitrate blenders with captive phosphate integration, and regional explosives specialists with mining sector relationships. Capacity expansion and green ammonia offtake agreements constitute the dominant competitive moves.
Among Nordic integrated majors, YARA anchors premium positioning through its ammonia-to-nitrate supply chain control. EuroChem Group occupies a position exemplifying volume competitiveness through captive phosphate-nitrate blending operations in Belgium and the Netherlands. Orica Limited represents the explosives-specialist archetype with mining sector relationships across Scandinavian open-pit operations.
| Leading Market Players |
|---|
| YARA |
| EuroChem Group |
| Orica Limited |
| URALCHEM JSC |
| ENAEX |
| Neochim PLC |
| Fertiberia SA |
| OSTCHEM |
| Borealis AG |
| Others |
Pricing and Supply Chain Analysis
TTF natural gas feedstock costs cascade through ammonia synthesis into three distinct pricing tiers for downstream ammonium nitrate offtake. Premium stabilized formulations with calcium magnesium nitrate shells command 8-12% markups over standard grades in Polish spot tenders, while explosives-grade prills with optimized oil absorption characteristics sustain higher per-ton margins despite smaller volumes.
Pricing Analysis
Contract-based long-term offtake agreements dominate agricultural procurement, with volume scale and carbon intensity certification as primary price differentiation drivers. Cost compression in standard-grade commoditization is intensifying because EU carbon border adjustment mechanisms favor domestic production over North African and Russian supply. Farming cooperatives across Greater Poland Voivodeship exhibit highest price sensitivity through aggregated tender platforms, while Scandinavian mining operators show lowest sensitivity due to supply continuity requirements.
Supply Chain Analysis
EU carbon border adjustment mechanisms and domestic-content preferences are reshaping sourcing patterns toward integrated European ammonia-nitrate producers. Supply concentrates in Germany, Poland, and the Netherlands, with raw material dependencies on natural gas from Norwegian fields and ammonia from Rotterdam electrolyzer projects. Single-source vulnerability around TTF hub pricing volatility constitutes the principal structural risk. Distribution runs through direct mill gate contracts for large-scale cooperatives and regional wholesalers for fragmented Bulgarian and Romanian territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Ammonium Nitrate Market operates as a stable compounder, with precision agriculture adoption and EU decarbonization mandates driving steady nitrogen fertilizer demand across the Central European farming belt.
For Market Incumbents: Lock in green ammonia offtake agreements with Norwegian and Dutch electrolyzer projects to secure zero-carbon nitrate pathways ahead of sustainability-linked procurement mandates. Deepen backward integration into captive ammonia supply to defend margins against TTF hub volatility, while accelerating polymer-encapsulated formulation R&D to offset standard-grade commoditization pressure from organic farming substitution. For New Entrants and Emerging Players: Begin with cooperative procurement platform partnerships in Romanian and Bulgarian distribution territories, where traditional merchant intermediaries face displacement from regional agronomy consortia. The explosives-grade segment offers most penetrable white-space opportunity, particularly high-density prill supply for Swedish and Finnish open-pit mining expansion, with direct mill gate contracting as the preferred go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where carbon intensity metrics penetrate procurement specifications and REACH registration timelines delay product qualification for co-formulant additives. Mid-term viability over the coming decade favors integrated ammonia-nitrate producers with captive supply chains over merchant blenders dependent on traded feedstock. Watch green ammonia project commissioning announcements as the critical inflection indicator for zero-carbon nitrate pathway competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Green Ammonia Offtake Agreement | Secures zero-carbon nitrate supply for EU Green Deal compliance in German and Dutch markets. |
| Polymer Encapsulation Technology Investment | Extends nutrient availability windows for precision agriculture adoption across French cereal belts. |
| Captive Ammonia Capacity Expansion | Reduces TTF hub exposure and secures margin control for Polish agricultural cooperative contracts. |
| Explosives-Grade Prill Specialization | Captures premium positioning in Scandinavian open-pit mining corridor long-term supply agreements. |
| Cooperative Platform Integration | Displaces merchant intermediaries through direct mill gate contracts in Black Sea corridor territories. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Scandinavia, with primary inputs from each region combined with secondary validation. Plant managers at integrated ammonia-nitrate facilities, procurement leads at Polish agricultural cooperatives, distribution channel partners across Romanian and Bulgarian territories, and technical R&D directors at coating technology specialists contributed primary perspectives. Secondary sources include customs and trade data from Eurostat, Cefic nitrogen fertilizer reports, SEC filings for listed chemical producers, and ECHA REACH registration databases. Bottom-up volume modeling triangulates against top-down macroeconomic indicators.
Granularity extends to product type, application, end user, and distribution channel dimensions across the projection horizon. Agricultural grade tiers separate stabilized formulations from standard commoditized product, while explosives specifications model oil absorption and prill hardness requirements. End-use segmentation captures farming cooperative scale, mining contract duration, and industrial purity certification needs. CAGRs derive from regression analysis against nitrogen fertilizer consumption intensity, TTF price trajectories, and EU carbon border adjustment implementation schedules.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on fertilizer subsidy programs, unforeseen Seveso III safety incidents triggering capacity closures, and breakthrough biostimulant technologies displacing mineral nitrogen demand. Forecasts reflect documented assumptions around natural gas price normalization and EU ETS carbon price trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market