
 Water Leak Sensing Cable Market | 2026-2036
Water Leak Sensing Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Water Leak Sensing Cable Market Insights
Modular sensor-to-gateway bundling is recalibrating procurement patterns across industrial buyers. TTK Leak Detection leverages integrated cable-and-controller packages to dominate European data center deployments. RLE Technologies sustains competitive positioning through specialized analog-to-digital interface modules that reduce installation complexity. Pentair anchors North American market presence with backward integration into proprietary conductive polymer formulations.
Water leak sensing cable consists of a conductive or resistive core sheathed in hygroscopic polymers, engineered to detect fluid contact through impedance change across lengths spanning 5 to 150 meters, primarily serving infrastructure protection in mission-critical facilities. Resistive cables occupy the largest installed base due to proven reliability in subfloor plenum environments, while fiber optic variants represent the fastest-growing technology segment as they eliminate electromagnetic interference in high-voltage equipment rooms. Digital sensing architectures command premium positioning by enabling addressable fault location, whereas analog systems retain cost-sensitive applications in municipal water distribution networks.
NFPA 75 and NFPA 76 standards in the United States compel fire and water suppression monitoring in telecommunications facilities, directly shaping product certification requirements for cable flame resistance and leak response latency. The EU Green Deal and national building efficiency directives in France, Germany, and Italy accelerate retrofit installations by mandating predictive maintenance systems in public infrastructure. Stakeholders must monitor evolving CE marking protocols under the EU Construction Products Regulation as these will determine market access for next-generation capacitance-based cable designs.
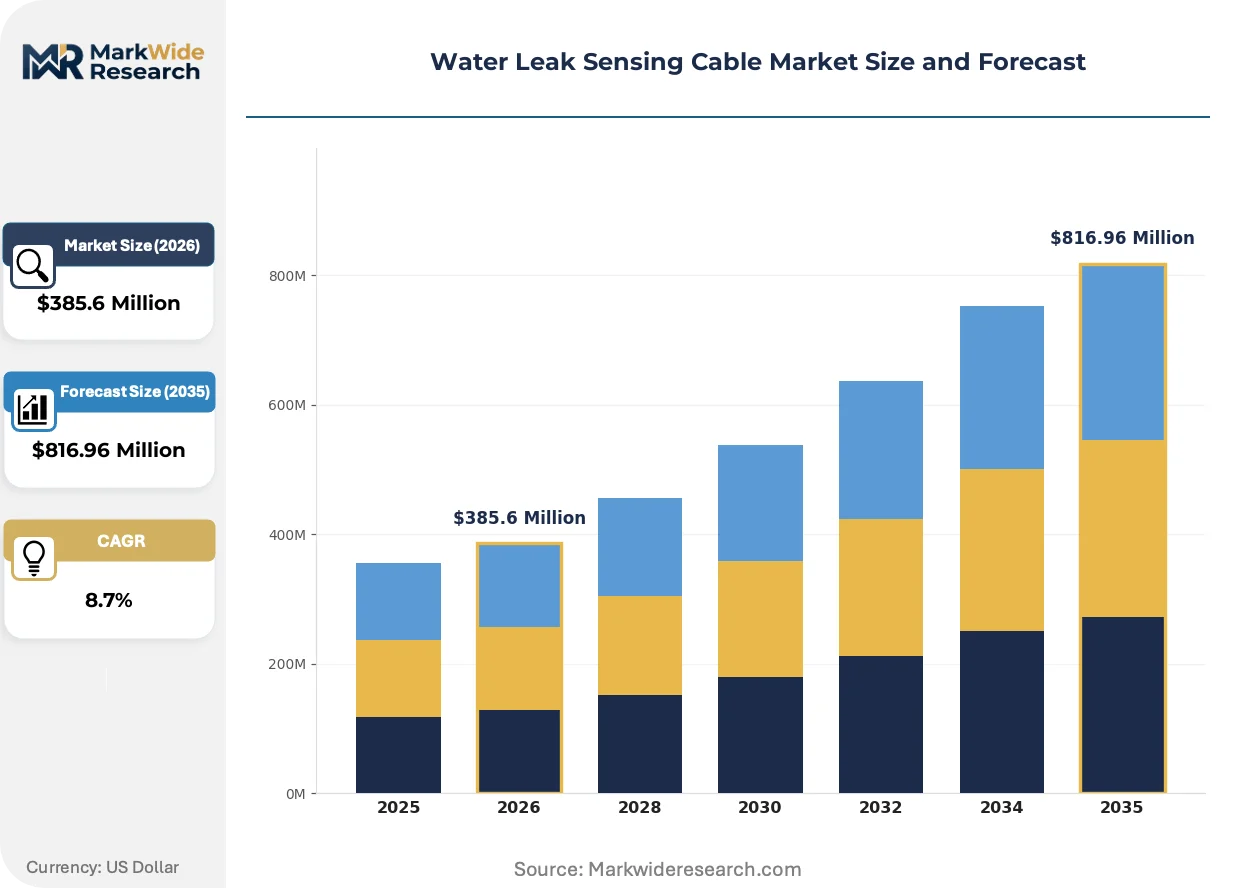
Market Dynamics
Data center operators across Germany, the United States, and Japan are consolidating procurement around bundled sensor-to-gateway systems, compressing standalone cable margins while elevating addressable digital architectures that enable precise fault location across mission-critical infrastructure.
Growth Catalysts
- EU Green Deal mandates:France, Germany, and Italy now require predictive maintenance systems in public infrastructure, accelerating retrofit installations of continuous leak monitoring in facilities housing electrical equipment.
- NFPA 75/76 compliance:United States telecommunications facilities must maintain fire and water suppression monitoring, directly shaping product certification requirements for cable flame resistance and leak response latency.
- Fiber optic sensing:Elimination of electromagnetic interference in high-voltage equipment rooms is displacing resistive cables in premium data center segments.
Market Restraints
- Conductive polymer supply concentration:Proprietary formulations for cable sheathing remain captive to specialized chemical suppliers in Western Europe, creating input bottlenecks.
- CE marking protocol uncertainty:Evolving EU Construction Products Regulation standards for capacitance-based cable designs are delaying market access for next-generation products.
- Wireless sensor substitution:Battery-powered point detectors are capturing cost-sensitive municipal water distribution applications where analog sensing cables previously dominated.
Strategic Opportunities
- Japan's aging pipeline networks:Persistent surveillance requirements for high-value industrial assets in chemical and semiconductor manufacturing facilities create demand for 150-meter span digital systems.
- Modular bundling innovation:Integrated cable-and-controller packages are opening new channel relationships with electrical contractors previously excluded from leak detection specification.
- EU building efficiency directives:National mandates in member states are creating regulatory tailwinds for early water intrusion detection in electrical equipment housing.
Industry Challenges
- Analog-to-digital integration complexity:Facilities managers face skill gaps in configuring addressable fault location systems alongside legacy resistive cable installations.
- NFPA certification timelines:Flame resistance testing for subfloor plenum environments extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Leak Sensing Cable Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Cables, Resistive Cables, Fiber Optic Cables, Capacitance Cables Technology: Analog Sensing, Digital Sensing, Wireless Transmission, Satellite Integration Application: Data Centers, Oil & Gas Facilities, Water Treatment Plants, Chemical Processing Units End User: Telecom Operators, Municipal Water Authorities, Manufacturing Plants, Research Laboratories |
| Companies Covered | TTK Leak Detection, RLE Technologies, Pentair, Aquilar Ltd., Honeywell International Inc., Siemens AG, Dorlen Products Inc., nVent Thermal Management, PermAlert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Leak Sensing Cable Market Trends and Innovations
Digital sensing architectures are compressing the competitive landscape by enabling precise fault location, while fiber optic variants eliminate electromagnetic interference constraints that previously limited cable deployment in high-voltage environments.
Fiber optic leak sensing cables are rewriting the technical boundaries of data center protection by transmitting light-pulse anomalies through hygroscopic cladding rather than electrical impedance. Hyperscale operators in Germany and the United States are specifying these systems for new construction at accelerating rates. The technology is compressing the addressable premium segment by eliminating grounding requirements and enabling 150-meter continuous spans without signal degradation.
REACH and RoHS substance restrictions in the European Union are forcing reformulation of conductive polymer sheathing materials used in resistive cable cores. Industrial consequences include accelerated R&D cycles and supplier qualification delays for cable manufacturers serving EU member states. German chemical formulators are responding with halogen-free hygroscopic compounds that maintain impedance sensitivity while satisfying substance restriction protocols.
Electrical contractors are displacing traditional security integrators as the primary specification channel for leak detection systems in North American data centers. Bundled sensor-to-gateway packages with simplified installation protocols are enabling this channel shift by reducing technical qualification barriers. The phenomenon is most visible in United States hyperscale construction, where procurement teams now prioritize turnkey installation support over component-level sourcing.
Water Leak Sensing Cable Market Segmentation
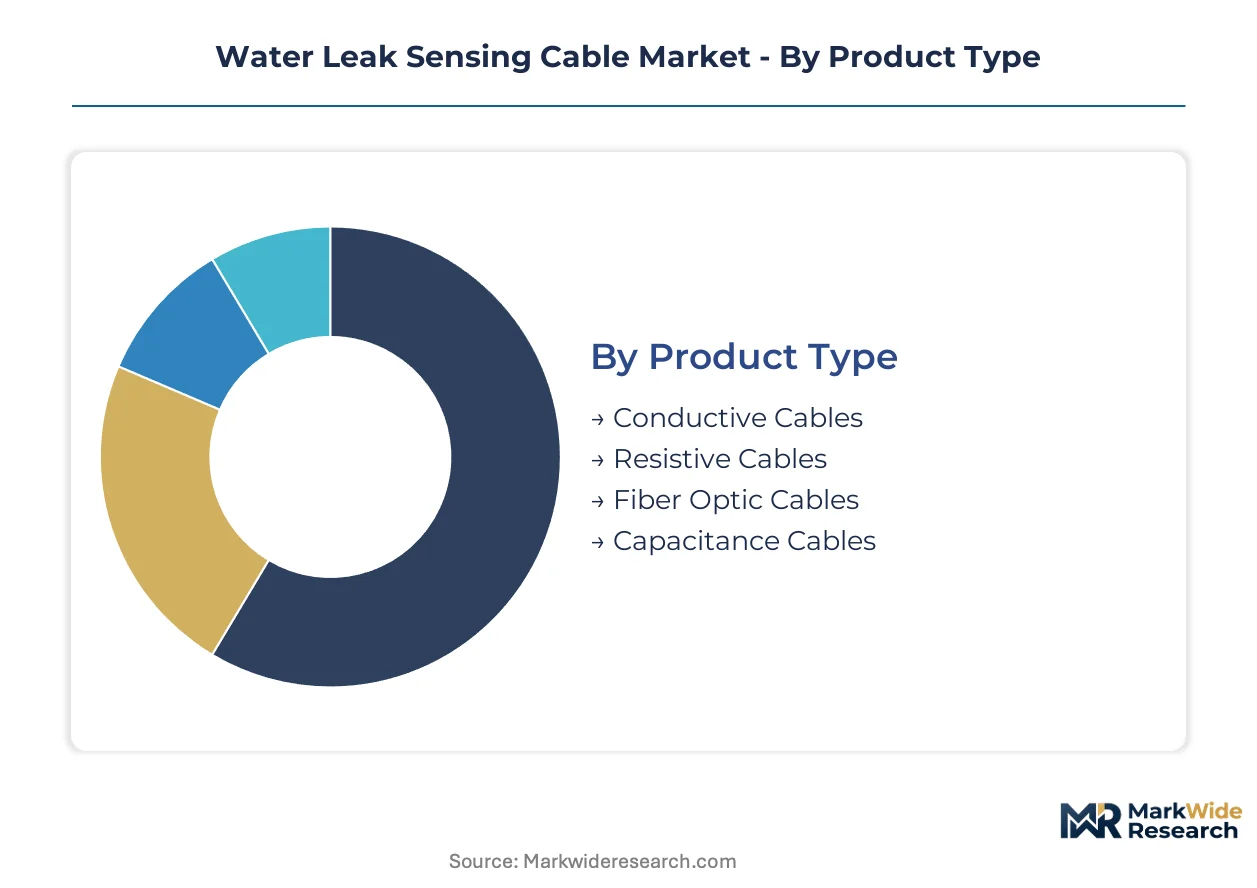
Water leak sensing cable procurement splits sharply by infrastructure criticality and electromagnetic environment constraints. Capital allocation patterns diverge between legacy analog installations and premium digital architectures with addressable fault location.
Product Type:
Capital intensity escalates from conductive polymer formulations to fiber optic and capacitance architectures requiring specialized manufacturing equipment and cleanroom sheathing processes.
- Conductive Cables:Metal-core designs wrapped in hygroscopic polymers detect fluid contact through resistance change across cable length. Demand concentrates in United States municipal water distribution networks where NFPA 75 compliance mandates flame-resistant subfloor monitoring at lowest installed cost.
- Resistive Cables:Impedance-based detection using proprietary conductive polymer cores dominates European data center retrofits under EU Green Deal predictive maintenance mandates. German facilities operators specify these for 5-to-50-meter spans in electrical equipment rooms.
- Fiber Optic Cables:Light-pulse anomaly detection through hygroscopic cladding eliminates grounding requirements in high-voltage environments.
- Capacitance Cables:Dielectric sensing enables non-contact moisture detection with highest precision positioning.
Most installed capacity flows through Resistive Cables. Expansion is steepest in Fiber Optic Cables.
Technology:
Customer sophistication determines technology selection, with facilities managers in mission-critical infrastructure accepting premium pricing for precise fault isolation.
- Analog Sensing:Continuous electrical monitoring without addressable location capability serves cost-constrained applications. United States telecommunications facilities deploy these for NFPA 76-compliant area coverage where pinpoint accuracy is secondary to flame resistance certification.
- Digital Sensing:Addressable architectures enable meter-precise fault location through microprocessor-embedded cable segments. Japan's semiconductor manufacturing plants specify 150-meter span systems for cleanroom infrastructure protection.
- Wireless Transmission:Battery-powered point detectors reduce cabling infrastructure in remote monitoring scenarios.
- Satellite Integration:Telemetry backhaul for distributed pipeline networks across geographically dispersed assets.
Volume leadership sits with Analog Sensing. Digital Sensing commands the steepest expansion trajectory.
Application:
Asset value density and downtime cost dictate cable specification tier, with hyperscale data centers absorbing premium digital systems while municipal utilities optimize for scale.
- Data Centers:Subfloor plenum and raised-floor monitoring in Germany and United States hyperscale facilities drives fiber optic and digital sensing demand. EU building efficiency directives accelerate retrofit installations with continuous monitoring requirements.
- Oil & Gas Facilities:Hazardous area classifications and explosion-proof requirements shape cable sheathing specifications.
- Water Treatment Plants:Large-area coverage needs favor resistive cable loops with simplified installation protocols.
- Chemical Processing Units:Corrosive environment resistance determines material selection for cable jacketing.
Data Centers absorb the highest unit pricing. Chemical Processing Units show the fastest adoption climb.
End User:
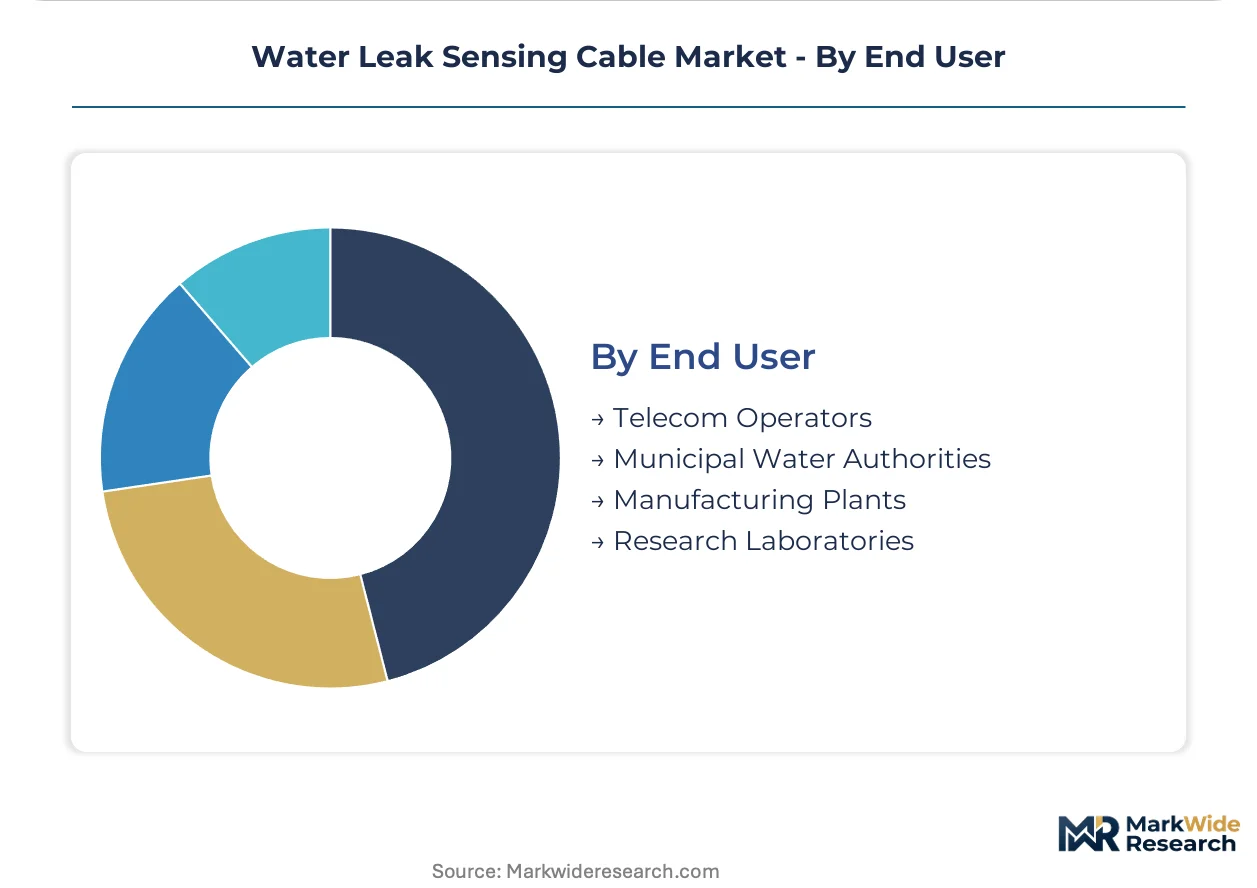
Procurement centralization varies sharply, with telecom operators consolidating specifications across national footprints while municipal authorities fragment purchasing across regional districts.
- Telecom Operators:United States carriers mandate NFPA 75/76-compliant bundled systems across switching facilities and central offices. Standardized specifications enable volume procurement of integrated cable-and-controller packages.
- Municipal Water Authorities:France, Germany, and Italy public infrastructure operators deploy predictive maintenance systems under EU Green Deal retrofit mandates.
- Manufacturing Plants:Japan's chemical and electronics producers specify 150-meter digital spans for high-value asset protection.
- Research Laboratories:Cleanroom and controlled environment monitoring with minimal electromagnetic interference.
Telecom Operators represent the largest contract value. Manufacturing Plants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water leak sensing cable technology first achieved commercial scale in European data center infrastructure during the early 2000s, with German industrial automation demand subsequently driving resistive cable refinement and standardization across the continent.
United States
Hyperscale data center construction in Northern Virginia, Dallas-Fort Worth, and Phoenix is absorbing premium fiber optic and digital sensing systems. NFPA 75 and NFPA 76 standards mandate flame-resistant subfloor monitoring in telecommunications facilities, compressing certification timelines for cable manufacturers. Electrical contractors in Ashburn, Virginia now specify bundled sensor-to-gateway packages for new construction.
Germany
EU Green Deal retrofit mandates are accelerating predictive maintenance system installations in Frankfurt and Munich data center clusters. REACH and RoHS substance restrictions are forcing reformulation of conductive polymer sheathing materials by chemical suppliers in the Rhine-Ruhr industrial region. German facilities operators specify resistive cables for 5-to-50-meter spans in electrical equipment rooms.
Japan
Aging pipeline networks and high-value semiconductor manufacturing assets in Kyushu and Kansai regions are driving demand for 150-meter span digital systems. METI industrial safety guidelines emphasize continuous leak monitoring in chemical processing facilities. Cleanroom infrastructure protection in Osaka semiconductor plants specifies addressable fault location capabilities.
France
National building efficiency directives under the EU Construction Products Regulation are mandating early water intrusion detection in facilities housing electrical equipment. Paris and Lyon data center operators are retrofitting continuous monitoring systems to comply with evolving CE marking protocols. French public infrastructure operators deploy predictive maintenance systems under Green Deal retrofit mandates.
United Kingdom
London and Slough data center clusters are consolidating procurement around integrated cable-and-controller packages. Post-Brexit regulatory alignment with EU substance restrictions is delaying supplier qualification for cable manufacturers. UK telecommunications facilities maintain NFPA-equivalent fire and water suppression monitoring standards.
Water Leak Sensing Cable Market Competitive Landscape
The competitive structure tilts toward integrated solution providers with captive polymer formulation capabilities. Market concentration is moderate, with specialist cable manufacturers competing against diversified industrial conglomerates with sensing divisions. Two strategic archetypes dominate: European specialists bundling cable-and-controller packages for data center retrofits, and North American diversified industrials leveraging backward integration into proprietary conductive polymers. Competitive moves center on modular bundling innovation and channel expansion through electrical contractor relationships.
Among European specialists, TTK Leak Detection and RLE Technologies exemplify the integrated bundling archetype, with the former representing French engineering-focused positioning and the latter occupying a position among analog-to-digital interface specialists. Pentair anchors the North American diversified industrial tier, with its corporate structure reflecting multi-industry portfolio breadth. These three companies collectively illustrate the geographic bifurcation between European retrofit-focused bundling and North American scale-driven polymer integration strategies.
| Leading Market Players |
|---|
| TTK Leak Detection |
| RLE Technologies |
| Pentair |
| Aquilar Ltd. |
| Honeywell International Inc. |
| Siemens AG |
| Dorlen Products Inc. |
| nVent Thermal Management |
| PermAlert |
| Others |
Pricing and Supply Chain Analysis
Conductive polymer formulations for cable sheathing cascade from specialized chemical suppliers in Western Europe through three distinct pricing tiers downstream, with proprietary formulation costs concentrating margin capture upstream while bundled sensor-to-gateway packages compress component-level pricing power at the buyer interface.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and after-sales service intensity. Fiber optic and digital sensing architectures with CE marking and NFPA flame resistance certifications command premium positioning, while analog resistive cables face intensifying cost compression from wireless point detector substitution in municipal applications. Hyperscale data center operators in Germany and the United States show lowest price sensitivity due to downtime cost exposure, whereas French and Italian municipal water authorities prioritize lowest installed cost under Green Deal retrofit mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated cable-and-controller packages, while electrical contractor distribution feeds North American data center construction. Manufacturing concentrates in Germany, the United States, and Japan, with conductive polymer cores and hygroscopic cladding materials drawing from specialized chemical formulators in the Rhine-Ruhr region. REACH and RoHS regulatory restrictions create single-source vulnerability for EU-compliant sheathing formulations. Distribution runs through bundled system providers for mission-critical infrastructure and component distributors for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as data center operators consolidate procurement around addressable digital architectures with precise fault location capabilities, displacing legacy analog installations.
For Market Incumbents: Anchor market position through backward integration into proprietary conductive polymer formulations and captive supply of halogen-free hygroscopic compounds compliant with EU substance restrictions. Defend against wireless sensor substitution by embedding predictive maintenance analytics into bundled sensor-to-gateway packages for electrical contractor channels. For New Entrants and Emerging Players: Launch via specialized fiber optic manufacturing partnerships targeting Japan's 150-meter span semiconductor cleanroom applications. Penetrate the chemical processing segment through corrosion-resistant cable jacketing innovations, leveraging METI safety guideline compliance as a specification wedge against established resistive cable suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where analog-to-digital interface capabilities fragment across mid-tier European specialists. Long-term viability favors integrated solution providers with captive polymer formulation and controller bundling expertise. Watch fiber optic adoption rates in United States hyperscale construction as the inflection indicator for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive supply of REACH-compliant sheathing materials locks in EU market access against regulatory delays. |
| Sensor-to-Gateway Bundling | Integrated packages reduce electrical contractor qualification barriers and compress standalone cable margins. |
| Fiber Optic Manufacturing Scale-Up | 150-meter continuous spans without signal degradation address Japan's semiconductor cleanroom specifications. |
| NFPA Certification Investment | Flame resistance testing for subfloor plenum environments secures United States telecommunications facility mandates. |
| Electrical Contractor Channel Partnership | Turnkey installation support displaces security integrators in North American hyperscale procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facilities managers, electrical contractor procurement leads, cable manufacturer R&D directors, and chemical formulator technical specialists with secondary validation through SEC filings, EU Construction Products Regulation documentation, and customs trade data for conductive polymer inputs. Bottom-up installation tracking across Germany, the United States, and Japan triangulated against top-down market sizing from bundled system revenue disclosures.
Historical reference periods anchored the forecast window to observed technology transition patterns from resistive to fiber optic architectures, with modeled segmentation across product type, technology tier, application criticality, and end-user procurement centralization. CAGRs derived from installation run-rate analysis and replacement cycle assumptions for aging pipeline infrastructure, with specific inputs including NFPA certification timeline data and EU Green Deal retrofit mandate implementation schedules across member states.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CE marking protocol delays for capacitance-based designs and accelerated wireless sensor substitution in municipal water distribution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Global Cable Tie Market
Cables
Mexico Wires and Cables Market
Cables
Solar Cable Market
Cables
Low-Temperature Cable Market
Cables
Electric Submersible Cable Sales Market
Cables
XLPE Cables Market
Cables
Aluminum Cable Market
Cables
High-Speed Interconnects Market
Cables
UK Cables Market
Cables
North America Wire and Cable Market
Cables
Submarine Cabling Systems Market
Cables
HVDC Cables Market
Cables
North America HVAC Cables Market
Cables
Submarine Data Cables Market
Cables
Cable Testers Market
Cables
SATA Power Cable Market